
 ASEAN Countries Electric Vehicle Battery Manufacturing Market | 2026-2036
ASEAN Countries Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Countries Electric Vehicle Battery Manufacturing Market Insights
A shift from imported cell packs to localized cathode-active-material production is pivoting procurement strategy across Southeast Asia. CATL leverages its Indonesia battery plant partnership to anchor nickel-to-cell integration. BYD Company Ltd. sustains vertical control through in-house LFP cell and EV platform manufacturing. Samsung SDI Co. Ltd. differentiates via high-nickel prismatic cell technology aimed at premium OEM supply.
ASEAN Countries Electric Vehicle Battery Manufacturing encompasses the industrial production of electrochemical energy storage systems, specifically lithium-ion cells with nickel-cobalt-manganese or lithium-iron-phosphate cathode formulations, assembled into modules and packs for traction power in electric vehicles. These systems store and discharge electrical energy through reversible lithium-ion intercalation, serving as the primary propulsion source for battery electric and plug-in hybrid vehicles across passenger, commercial, and public transport categories. Lithium-ion chemistry dominates current installed capacity due to mature supply chains and energy density thresholds, while solid-state architectures represent the fastest-growing technology segment as manufacturers pursue ceramic electrolyte designs for improved thermal stability. Automotive OEMs constitute the deepest margin pool among end users, though fleet operators are expanding order volumes as logistics electrification accelerates across Jakarta, Bangkok, and Singapore.
Thailand's Board of Investment coordinates EV manufacturing incentives with national industrial standards administered by the Thai Industrial Standards Institute. Indonesia's Ministry of Industry enforces domestic content requirements under nickel downstreaming mandates, while Singapore's Land Transport Authority shapes urban fleet electrification timelines. These regulatory frameworks collectively determine market access thresholds, local content ratios, and product certification pathways for cell and pack producers. Stakeholders must monitor evolving mineral export restrictions and carbon-border adjustment preparations as these instruments reshape cost structures for integrated versus import-dependent manufacturing models.
Market Dynamics
Indonesia's nickel downstreaming mandates and Thailand's Board of Investment incentive packages are redirecting supply chain investment from imported cell packs toward localized cathode-active-material production, compressing procurement timelines and reconfiguring supplier relationships across Southeast Asia.
Growth Catalysts
- Thailand's BOI Incentive Packages:Tax holidays and import duty exemptions for EV battery manufacturing equipment are attracting cathode precursor investments to the Eastern Economic Corridor.
- Nickel Downstreaming Mandates:Indonesia's Ministry of Industry domestic content requirements force integrated nickel-to-cell production, anchoring smelter investments in Morowali Industrial Park.
- Fleet Electrification Timelines:Singapore's Land Transport Authority urban bus and logistics electrification schedules are generating module-level demand from municipal fleet operators.
Market Restraints
- Lithium Carbonate Price Volatility:Input cost swings for lithium hydroxide and carbonate destabilize cell cost models, forcing producers to absorb margin compression or renegotiate OEM contracts.
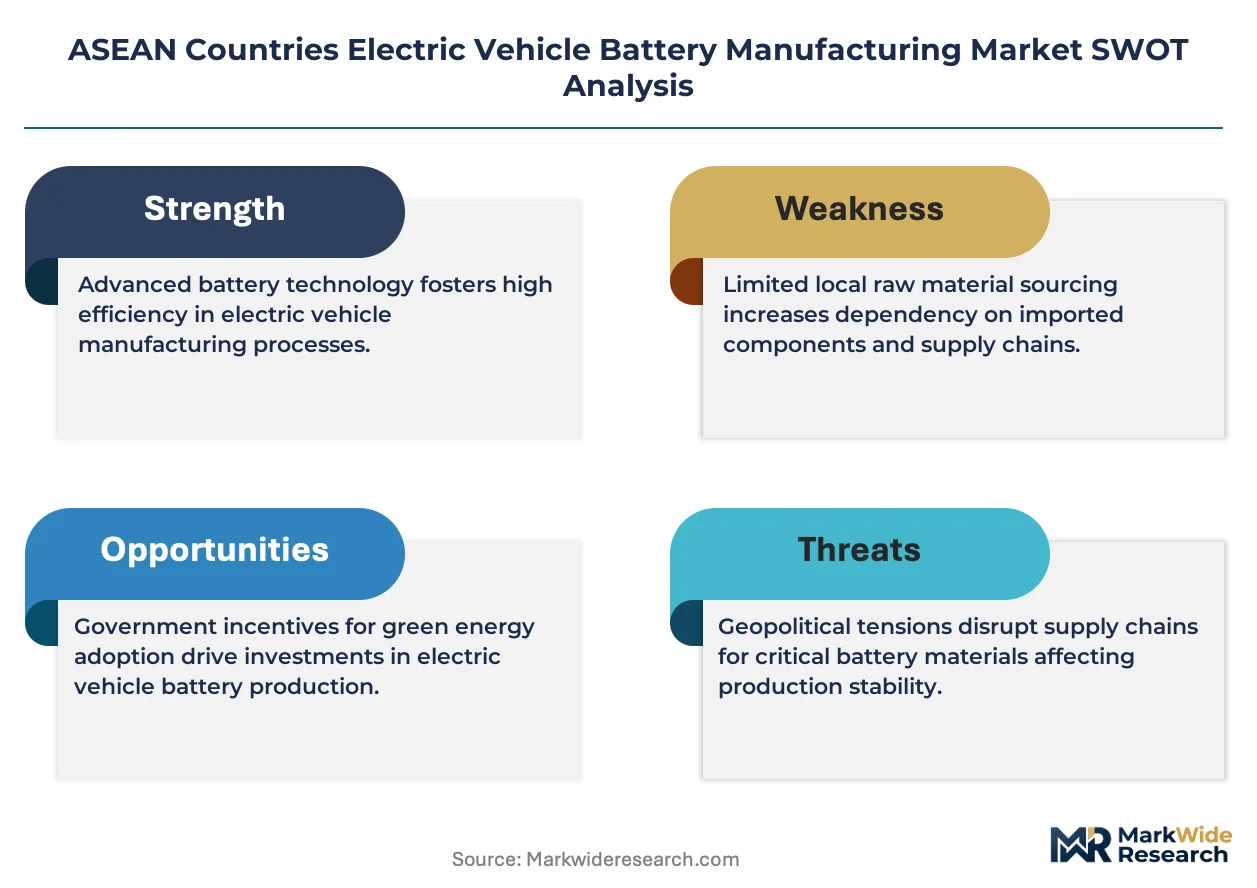
- Single-Source Cathode Supply:NCM precursor dependence on Chinese chemical processing creates concentration risk that ASEAN governments seek to dilute through local content mandates.
- Energy Density Ceiling:Current LFP formulations face theoretical limits below 200 Wh/kg at cell level, constraining range performance for commercial vehicle applications.
Strategic Opportunities
- Vietnam's Underpenetrated Assembly Base:Absence of integrated cell production creates white space for module-pack assembly investments serving emerging domestic EV brands.
- Solid-State Electrolyte Convergence:Ceramic sulfide and oxide electrolyte research programs in Singapore and Thailand offer pathway to thermal runaway elimination and fast-charge capability.
- Second-Life Stationary Storage:Retired automotive packs from Bangkok and Jakarta fleet deployments enable grid-scale energy storage repurposing through battery management system reconfiguration.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell design and dry electrode coating expertise concentrates in Northeast Asia, forcing ASEAN facilities to recruit expatriate technical leadership or fund prolonged training programs.
- UN 38.3 Certification Timelines:Lithium-ion cell transport safety testing and IEC 62660 compliance documentation create 8-14 month product launch delays for new regional entrants.
- Legacy Internal Combustion Supplier Integration:Tier-1 automotive suppliers with engine component heritage face capability gaps in thermal management and battery management system software development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Countries Electric Vehicle Battery Manufacturing Market |
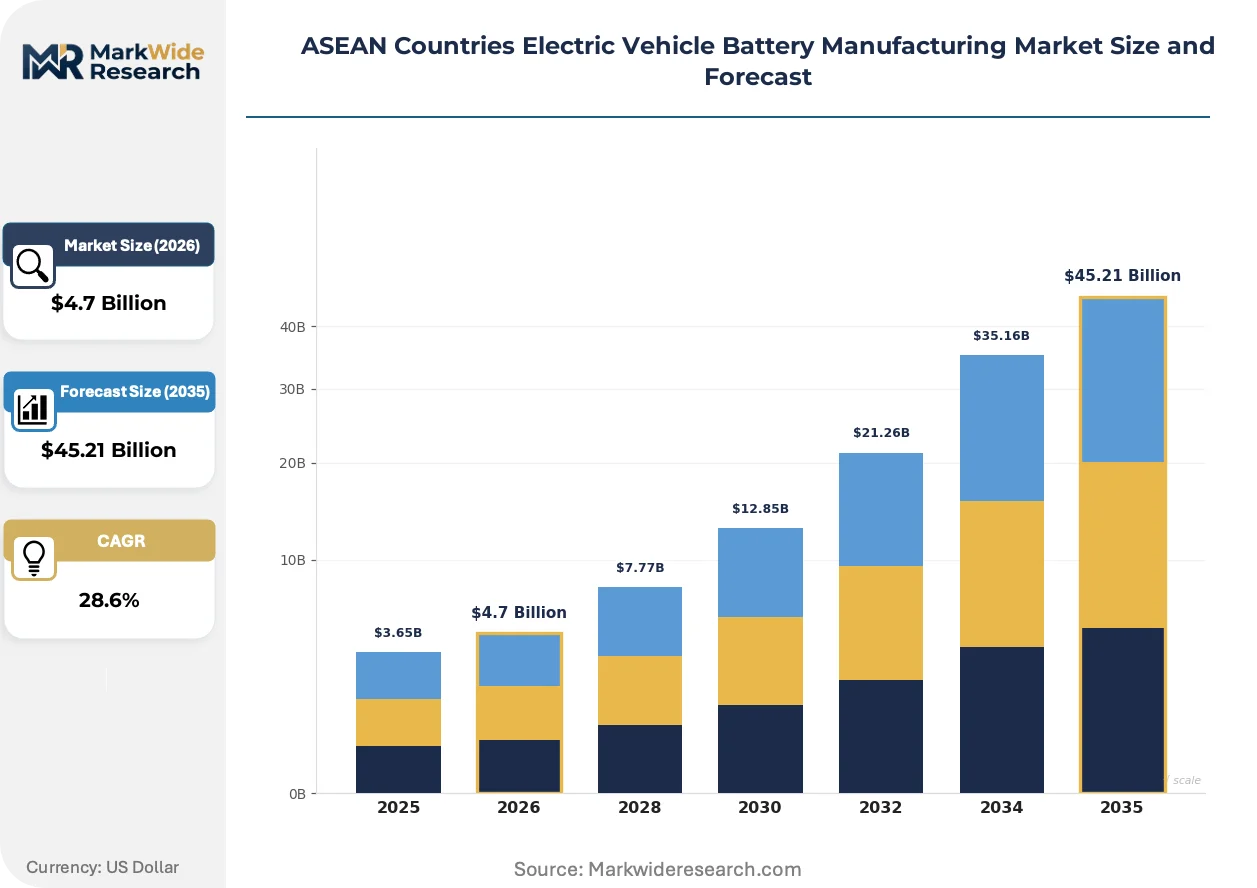
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state End User: Automotive OEMs, Public Transportation, Fleet Operators, Aftermarket Services Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores Technology: Battery Management Systems, Fast Charging, Regenerative Braking, Thermal Management |
| Companies Covered | BYD Company Ltd., Contemporary Amperex Technology Co. Ltd. (CATL), LG Energy Solution Ltd., Samsung SDI Co. Ltd., Panasonic Holdings Corporation, SK Innovation Co. Ltd., SVOLT Energy Technology Co. Ltd., Ningde E-CON Power System Co. Ltd., Deutsche ACCUmotive GmbH & Co. KG, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Countries Electric Vehicle Battery Manufacturing Market Trends and Innovations
Cell chemistry standardization and dry electrode manufacturing processes are compressing capital intensity and enabling faster capacity scaling across Thailand and Indonesia production zones.
High-nickel NCM cathode formulations are consolidating as the dominant chemistry for premium passenger EV applications targeting 600+ kilometer range thresholds. Korean and Chinese producers are expanding precursor investments in Morowali to secure nickel sulfate supply. This chemistry is consolidating market share in ASEAN premium OEM supply contracts as energy density requirements tighten.
Indonesia's Ministry of Industry domestic content mandates are forcing cathode precursor and nickel sulfate production localization as a condition of EV manufacturing license eligibility. Industrial park operators in Morowali and Weda Bay are rezoning smelter-adjacent land for integrated battery material zones. Cell producers without captive nickel supply face exclusion from national incentive programs.
Fleet procurement teams in Jakarta, Bangkok, and Singapore are unbundling battery pack purchases from vehicle chassis contracts, creating direct cell-producer-to-fleet-operator relationships. Logistics operators with centralized charging depots now specify cycle life and degradation warranties independently of OEM platform warranties. This pattern is most visible in refrigerated last-mile delivery electrification programs across metropolitan Southeast Asia.
ASEAN Countries Electric Vehicle Battery Manufacturing Market Segmentation
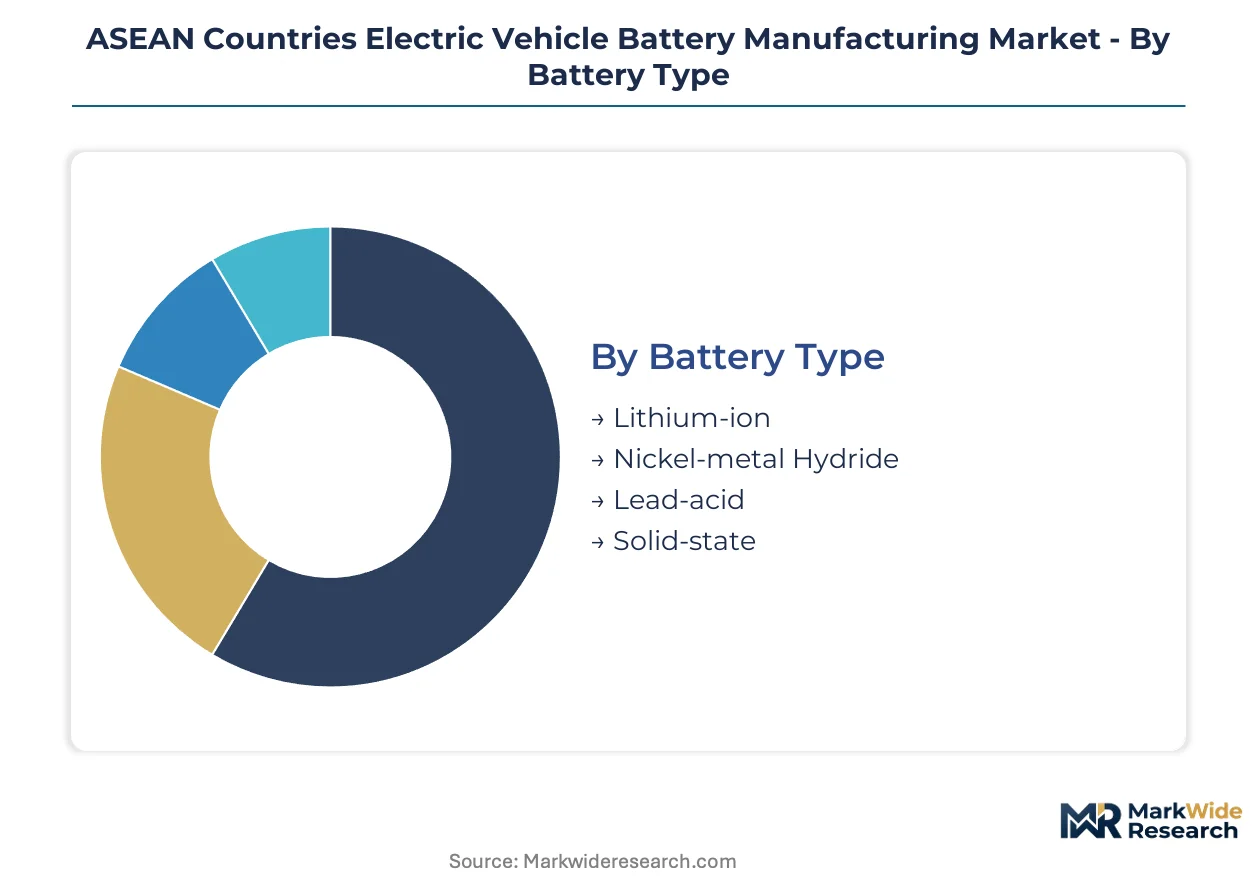
ASEAN battery manufacturing exhibits distinct procurement patterns across chemistry types, end-use applications, and distribution models. Each segment carries unique technical specifications, margin structures, and regulatory compliance requirements that determine competitive positioning.
Battery Type:
Customization intensity varies sharply across this category, from standardized commodity formats to application-specific cell architectures requiring dedicated production lines.
- Lithium-ion:NCM and LFP cathode formulations dominate current installed capacity across Thailand's Eastern Economic Corridor and Indonesia's Morowali Industrial Park. Automotive OEMs in Bangkok and Jakarta specify cell-to-pack integration to optimize thermal performance in tropical climates.
- Solid-state:Ceramic electrolyte designs eliminate thermal runaway risks while enabling fast-charge capability. Singapore's research institutions and Thailand's national labs are accelerating pilot production timelines as Korean and Japanese producers evaluate ASEAN assembly locations.
- Nickel-metal Hydride:Hybrid vehicle auxiliary power applications persist in legacy Toyota and Honda production bases across Thailand.
- Lead-acid:Starter-lighting-ignition replacement demand concentrates in Indonesia's aftermarket service networks.
Most installed capacity flows through Lithium-ion. Expansion is steepest in Solid-state.
End User:
Volume concentration and margin capture diverge significantly across customer types, with captive OEM supply commanding premium pricing against fragmented aftermarket demand.
- Automotive OEMs:Cell producers negotiate multi-year offtake agreements with Thailand's BOI-registered EV assemblers and Indonesia's national car programs. These contracts specify nickel sulfate provenance and carbon intensity thresholds.
- Fleet Operators:Logistics electrification across Jakarta, Bangkok, and Singapore generates module-level procurement independent of vehicle chassis contracts. Centralized depot charging enables standardized pack specifications and direct manufacturer relationships.
- Public Transportation:Municipal bus electrification mandates in Singapore and Bangkok create tender-based demand with extended warranty requirements.
- Aftermarket Services:Replacement pack demand concentrates in Indonesia's independent repair networks with limited technical certification.
Revenue concentrates in Automotive OEMs. Fleet Operators are gaining share fastest.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to production clusters.
- Direct Sales:High-volume OEM and fleet contracts bypass intermediaries for cell-to-pack integration services. CATL and BYD maintain direct technical teams in Bangkok and Jakarta.
- Distributors:Regional warehousing networks serve fragmented aftermarket demand across secondary Indonesian cities and Vietnamese emerging markets.
- Online Retail:Limited to consumer-grade power tool and mobility scooter batteries with standardized form factors.
- Specialty Stores:Technical consultation for commercial vehicle retrofit applications in Thailand's Eastern Economic Corridor.
Transaction value concentrates in Direct Sales. Distributors are expanding coverage most aggressively.
Technology:
Technology adoption correlates with end-use performance requirements and local engineering capabilities.
- Battery Management Systems:Software-defined thermal and state-of-charge algorithms differentiate premium cell offerings. Korean producers embed proprietary BMS with high-nickel NCM cells for ASEAN luxury EV platforms.
- Thermal Management:Liquid cooling circuits and phase-change materials address tropical ambient temperature challenges. Thai Industrial Standards Institute certification mandates specific thermal runaway propagation tests.
- Fast Charging:800V architectures and silicon-anode compatibility enable 10-80% charge cycles under 20 minutes. Singapore's charging infrastructure investments are accelerating deployment timelines.
- Regenerative Braking:Integrated power electronics capture kinetic energy in urban stop-start driving patterns across Jakarta and Bangkok metropolitan areas.
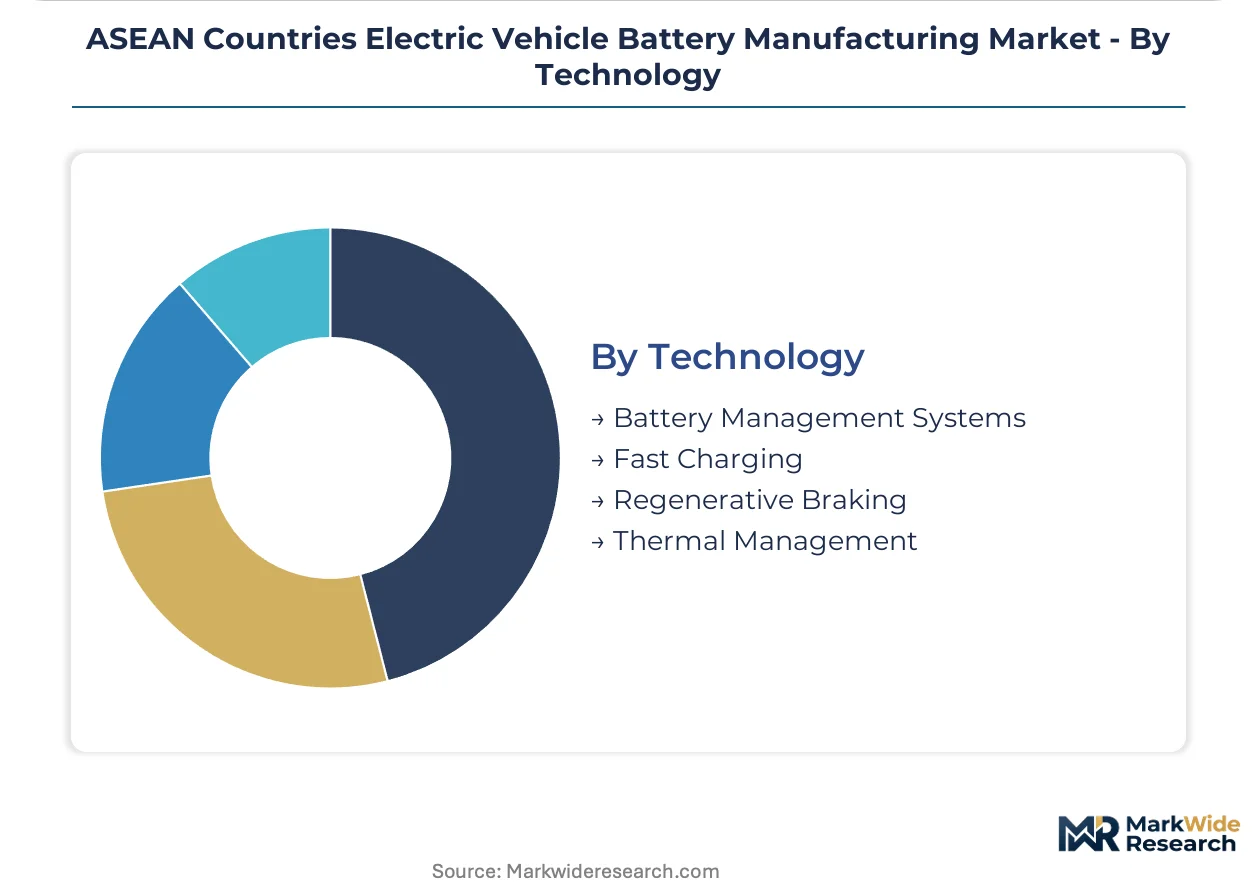
Development investment concentrates in Battery Management Systems. Fast Charging is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where nickel downstreaming mandates and investment incentive packages compress compliance costs relative to import-dependent models. Thailand and Indonesia exploit this regulatory-arbitrage gap to anchor cell manufacturing against Vietnamese and Malaysian assembly-only alternatives.
Thailand
Thailand's Board of Investment incentive packages attract cathode precursor investments to the Eastern Economic Corridor. The Thai Industrial Standards Institute administers certification mandates for thermal runaway propagation testing. Rayong and Chonburi provinces concentrate cell-to-pack integration facilities serving Bangkok-registered automotive OEMs.
Indonesia
Indonesia's Ministry of Industry enforces domestic content requirements under nickel downstreaming policies that force integrated nickel-to-cell production. Morowali Industrial Park anchors smelter-adjacent battery material zones with captive nickel sulfate supply. Weda Bay rezoning accommodates Korean and Chinese precursor investments seeking license eligibility.
Singapore
Singapore's Land Transport Authority shapes urban fleet electrification timelines that generate module-level demand from municipal bus and logistics operators. The country's research institutions accelerate solid-state electrolyte pilot programs. Jurong Island clusters materials science facilities evaluating ceramic sulfide architectures.
Vietnam
Vietnam's absence of integrated cell production creates white space for module-pack assembly investments serving emerging domestic EV brands. The country's national industrial regulator shapes foreign investment thresholds for battery manufacturing equipment imports. Ho Chi Minh City and Hanoi metropolitan areas concentrate logistics fleet electrification procurement.
Malaysia
Malaysia's industrial development authority coordinates electronics manufacturing incentives that extend to battery management system component production. The country's national standards body adapts IEC 62660 compliance pathways for regional entrants. Penang and Selangor states host power electronics suppliers targeting ASEAN thermal management subsystem demand.
ASEAN Countries Electric Vehicle Battery Manufacturing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state specialization and second-life stationary storage adjacencies. The vendor base stratifies across integrated nickel-to-cell operators, module-pack assemblers, and materials science specialists. Three archetypes dominate: Korean conglomerates with high-nickel prismatic expertise, Chinese producers with LFP scale advantages, and European automotive-tier suppliers with captive OEM relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure nickel sulfate offtake and localize precursor production.
Within the integrated production tier, BYD Company Ltd. and Contemporary Amperex Technology Co. Ltd. exemplify divergent scale strategies. BYD represents vertical control through in-house LFP cell and EV platform manufacturing. CATL anchors nickel-to-cell integration via its Indonesia battery plant partnership. Samsung SDI Co. Ltd. occupies a position within the premium-tier vector, differentiating through high-nickel prismatic cell technology aimed at automotive OEM supply contracts. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning across ASEAN manufacturing zones.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| LG Energy Solution Ltd. |
| Samsung SDI Co. Ltd. |
| Panasonic Holdings Corporation |
| SK Innovation Co. Ltd. |
| SVOLT Energy Technology Co. Ltd. |
| Ningde E-CON Power System Co. Ltd. |
| Deutsche ACCUmotive GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement teams in Bangkok and Jakarta command dominant negotiating leverage through multi-year offtake agreements, compressing cell producers into contract-based long-term pricing with nickel sulfate provenance premiums. Thailand's BOI-registered assemblers and Indonesia's national car programs extract volume discounts that relegate spot-market transactions to fragmented aftermarket channels.
Pricing Analysis
Distributor margins absorb 12-18% in secondary Indonesian cities where technical certification gaps limit direct manufacturer presence. Three-tier pricing structure across premium high-nickel NCM, standard LFP, and economy refurbished packs differentiates by energy density thresholds and cycle life warranties. Cost compression in standard-tier LFP cells is intensifying because Chinese precursor imports undercut localized cathode production. Fleet operators with centralized charging depots exhibit highest price sensitivity; premium OEM supply contracts show lowest elasticity due to thermal performance specifications mandated by Thai Industrial Standards Institute certification.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Thailand's Eastern Economic Corridor and Indonesia's Morowali Industrial Park, bypassing intermediary markups for cell-to-pack integration services. Raw material flows draw from Indonesian nickel smelters, Chinese lithium hydroxide refiners, and Korean cobalt traders. Single-source vulnerability concentrates in NCM precursor dependence on Chinese chemical processing. Distribution runs through captive nickel-to-cell integrated facilities in Morowali and Weda Bay, with module-pack assembly radiating to Vietnamese emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where 600+ kilometer range thresholds and fast-charge capability specifications are displacing commoditized LFP procurement. Premium thermal management and battery management system differentiation now determines contract win rates.
For Market Incumbents: Lock in nickel sulfate offtake through smelter-adjacent precursor investments in Morowali and Weda Bay before Indonesia's Ministry of Industry tightens domestic content thresholds. Secure Thai Industrial Standards Institute thermal runaway certification ahead of competing Korean and Chinese producers. Solid-state electrolyte research programs in Singapore represent the priority R&D lever against ceramic sulfide disruption. For New Entrants and Emerging Players: Fleet operator procurement teams in Ho Chi Minh City and Hanoi offer the most penetrable entry vector given Vietnam's absence of integrated cell production and unbundled battery pack purchasing trends. Target module-pack assembly serving emerging domestic EV brands with standardized LFP specifications. A go-to-market angle anchored in second-life stationary storage repurposing from Bangkok and Jakarta retired fleet deployments bypasses direct cell manufacturing capital intensity. For Investors and Strategic Acquirers: Korean conglomerates with high-nickel prismatic expertise are the most active acquirers in this space, seeking ASEAN manufacturing footholds to offset domestic capacity constraints. Long-term viability favors integrated nickel-to-cell operators with captive Morowali smelter supply over import-dependent module assemblers. Battery management system software capabilities and solid-state electrolyte patent portfolios signal acquisition target quality. Watch for Indonesia's nickel export restriction announcements as inflection indicators for integrated versus non-integrated cost structure divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Sulfate | Captive Morowali smelter supply secures Indonesia EV manufacturing license eligibility under Ministry of Industry mandates. |
| Solid-State Electrolyte Pilot Production | Singapore research institutions and Thailand national labs accelerate ceramic sulfide architectures toward thermal runaway elimination. |
| Direct Fleet Operator Relationships | Unbundled battery pack procurement from Jakarta and Bangkok logistics operators bypasses OEM platform intermediation. |
| Second-Life Stationary Storage Repurposing | Retired automotive packs from ASEAN fleet deployments enable grid-scale energy storage through battery management system reconfiguration. |
| Thai Industrial Standards Institute Certification | Thermal runaway propagation testing compliance opens BOI-registered OEM supply contracts in Eastern Economic Corridor. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell design engineers, cathode precursor procurement leads, fleet electrification managers, and national regulator policy officers with secondary validation. Trade data from Indonesian Ministry of Industry smelter output disclosures, Thai Board of Investment EV manufacturing registration databases, and Singapore Land Transport Authority tender documentation anchored supply-side calibration. Bottom-up cell capacity buildout estimates and top-down OEM platform deployment trajectories were cross-referenced for triangulation.
Segment-weighting applied chemistry type, end-use application, and distribution channel dimensions across the projection horizon. Automotive OEM, fleet operator, public transportation, and aftermarket service end-use splits were modeled with regional production cluster overlays. CAGRs derived from installed capacity ramp rates against vehicle electrification policy timelines. Nickel downstreaming mandate compliance thresholds and lithium carbonate price volatility bands served as scenario sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Indonesia's mineral export restriction timing and solid-state electrolyte pilot production scale-up. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
EV Battery Heating System Market
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Germany Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
Solar DC Coupled Battery Market