
 Watch Battery Market | 2026-2036
Watch Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Watch Battery Market Insights
Subscription-based battery replacement programs is restructuring how watch battery makers monetize aftermarket demand. Renata SA leverages its Swiss manufacturing heritage to sustain premium positioning in analog watch servicing. Maxell, Ltd. anchors Asian supply chains through specialized silver oxide production. Panasonic Energy Europe n.v. competes on high-drain lithium coin cell reliability for hybrid timepieces.
Watch batteries are compact electrochemical cells, typically silver oxide or lithium-based, engineered to deliver stable voltage output over multi-year lifespans in low-drain environments. Their primary purpose is to power timekeeping movements, digital modules, and wireless connectivity chipsets without frequent replacement. Silver oxide cells dominate traditional analog applications where stable voltage curves preserve mechanical movement accuracy, while lithium variants capture expanding share in smartwatches and hybrid timepieces due to higher energy density requirements. The coin cell size category concentrates the highest volume, though margin pools sit with small cell formats tailored for ultra-thin luxury watch designs.
REACH restrictions in Europe, RoHS directives limiting hazardous substances, and China's GB standards on heavy metal content collectively constrain permissible chemistries and manufacturing processes. These frameworks elevate compliance costs for alkaline formulations while accelerating lithium and nickel metal hydride transitions. Stakeholders must monitor how evolving EU Battery Regulation passport requirements reshape material traceability obligations across their supplier networks.
Market Dynamics
The watch battery market is undergoing a chemistry transition as EU Battery Regulation cadmium and mercury limits force manufacturers away from legacy alkaline formulations toward lithium and silver oxide alternatives. This regulatory compression is reshaping supply chain configurations across contract manufacturers clustered in Shenzhen and Dongguan.
Growth Catalysts
- Wearable Health Monitoring Expansion:Smartwatch manufacturers are scaling orders for rechargeable lithium cells as continuous glucose monitoring and ECG functionality become standard features in consumer wearables.
- REACH and RoHS Compliance Deadlines:European hazardous substance directives are accelerating the phase-out of mercury-containing button cells, creating replacement demand for compliant chemistries in analog watch servicing networks.
- China's Dual Carbon Goals:Domestic battery producers in Guangdong province are retooling production lines to meet national carbon neutrality targets, expanding capacity for low-carbon lithium coin cell manufacturing.
Market Restraints
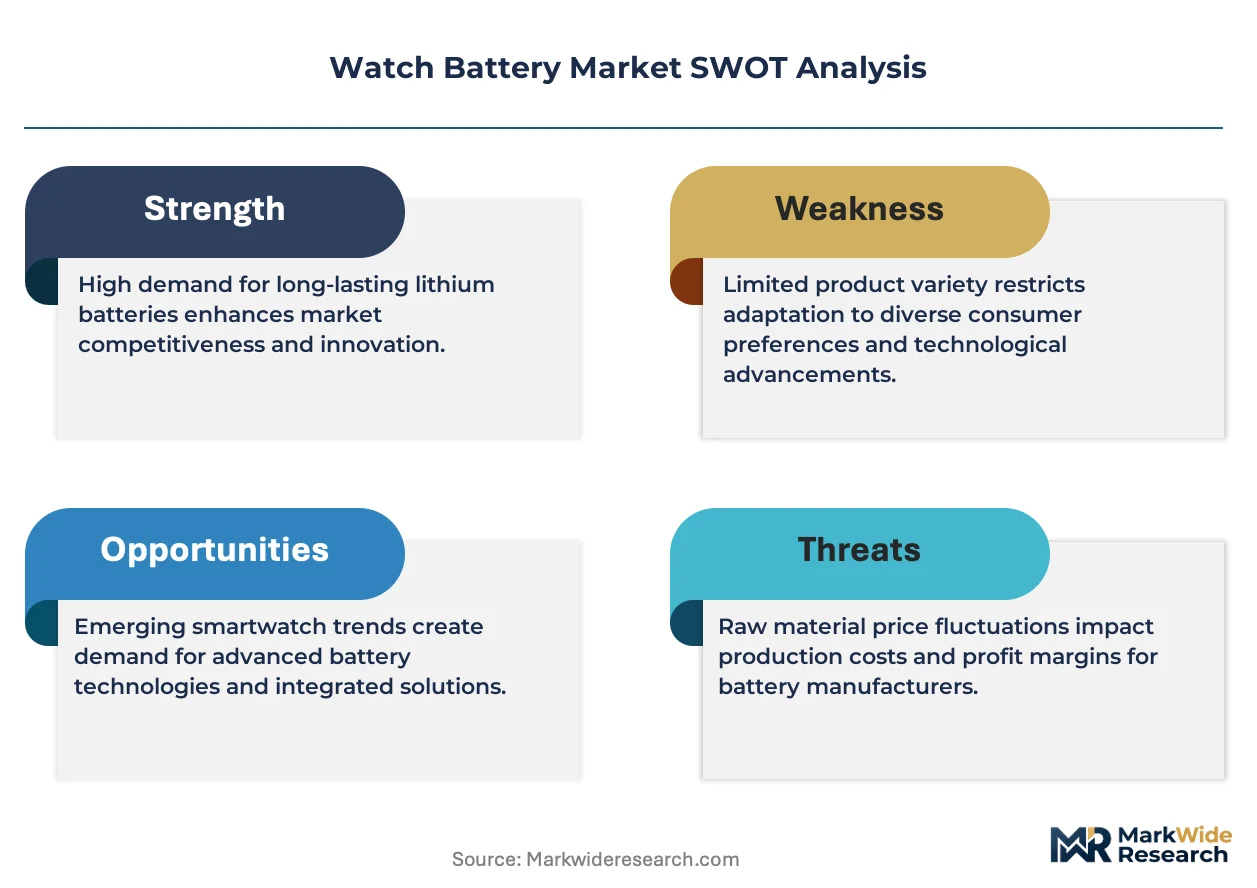
- Raw Material Concentration Risk:Cobalt and lithium refining capacity concentrates in Chinese state-owned enterprises, exposing non-Chinese cell assemblers to supply interruption and price volatility.
- Technical Energy Density Ceiling:Silver oxide chemistry faces fundamental limitations below 200 Wh/kg, constraining its viability for next-generation smartwatches with GPS and cellular connectivity modules.
- EU Battery Passport Requirements:Material traceability obligations under the EU Battery Regulation are elevating compliance costs for small-format cell producers serving European watch brands.
Strategic Opportunities
- India's Manufacturing Incentive Schemes:PLI scheme subsidies for advanced chemistry cell production are attracting watch battery assemblers to Gujarat and Tamil Nadu industrial corridors.
- Solid-State Electrolyte Convergence:Thin-film solid-state technology is converging with micro-battery form factors, enabling sub-millimeter cells for ultra-luxury mechanical watch hybridization.
- Subscription Replacement Channels:Direct-to-consumer battery replacement programs are bypassing traditional jewelry retail networks, capturing aftermarket margin pools previously held by regional distributors.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Specialized expertise in thin-film deposition and solid-state interface engineering is concentrated in Japanese and South Korean research institutions, constraining European and North American producer R&D velocity.
- Certification Timeline Compression:UN 38.3 lithium transport certification and IEC 60086 safety testing are creating 6-12 month product launch delays for new cell formats targeting smartwatch OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Watch Battery Market |
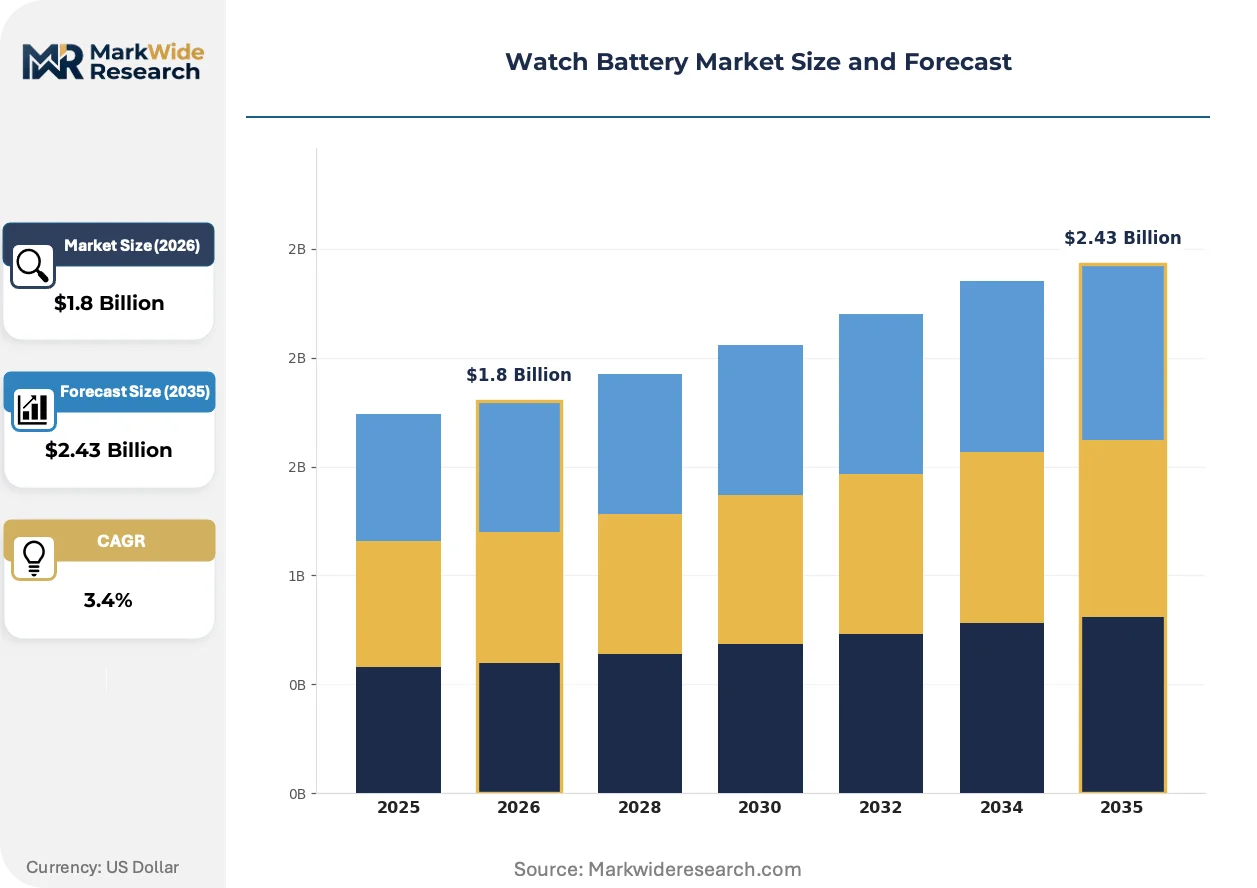
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Alkaline, Lithium, Silver Oxide, Nickel Metal Hydride Application: Analog Watches, Digital Watches, Smartwatches, Hybrid Timepieces Size: Small Cell, Medium Cell, Large Cell, Coin Cell End User: Manufacturers, Retailers, Repair Shops, Consumers |
| Companies Covered | Renata SA, Maxell, Ltd., Panasonic Energy Europe n.v., Sony Corporation, Duracell Inc., Camelion Battery Co., Ltd., EVE Energy, GPB International Limited, NANFU BATTERY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Watch Battery Market Trends and Innovations
Solid-state micro-battery architectures and printed electronics are compressing the traditional trade-off between energy density and form factor flexibility. These advances are enabling new device categories that previously required wired power or frequent replacement cycles.
Zinc-air chemistry is converging with printed circuit integration to create ultra-thin cells for hybrid smartwatches. Swiss luxury manufacturers are piloting these cells in limited editions where mechanical movement preservation meets connected functionality. The technology is converging with MEMS fabrication processes, collapsing the thickness constraint that previously separated analog and digital timepiece design paradigms.
REACH authorization requirements for nickel compounds are tightening across European Economic Area member states. This regulatory pressure is forcing silver oxide producers to reformulate cathode materials and document alternative substance assessments. Traditional analog watch battery suppliers serving German and French servicing networks are accelerating nickel-free chemistry transitions ahead of 2027 sunset dates.
After-sales unbundling is disrupting the jewelry retail channel that historically controlled battery replacement revenue. Direct manufacturer subscription programs are capturing customer relationships and recurring revenue streams previously held by independent watchmakers. This channel compression is most visible in North American and Western European urban markets where smartwatch penetration has trained consumers to expect seamless digital service experiences.
Watch Battery Market Segmentation
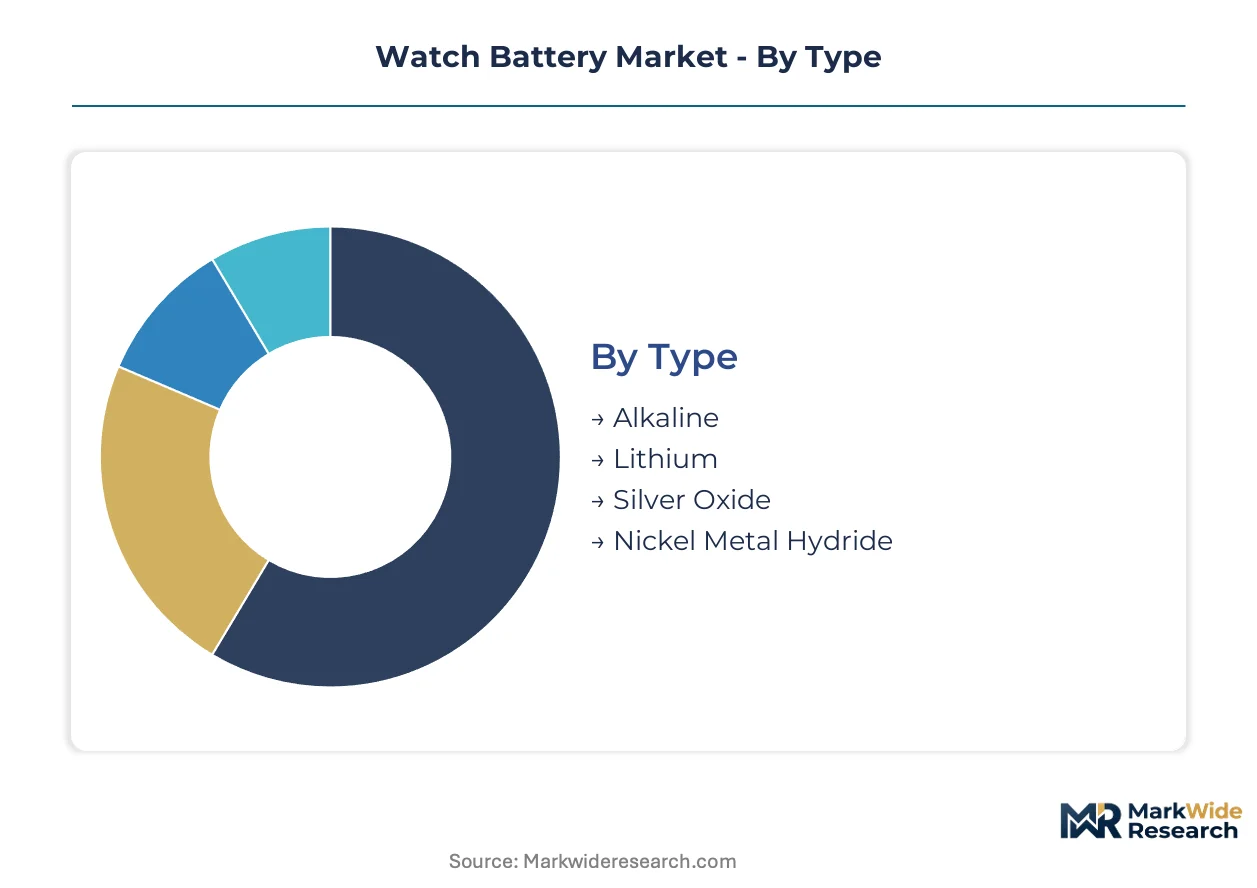
Watch battery segmentation reflects divergent technical requirements across mechanical precision timekeeping, connected wearables, and aftermarket servicing channels. Chemistry selection, form factor constraints, and end-user procurement patterns create distinct margin pools that manufacturers navigate through specialized production lines.
Type:
Standardization dominates commodity alkaline production while lithium and silver oxide chemistries demand customized electrode formulations and purity protocols.
- Lithium:Rechargeable lithium-ion and primary lithium coin cells deliver energy density exceeding 260 Wh/kg, essential for GPS-enabled smartwatches and cellular-connected wearables. Shenzhen-based contract manufacturers are scaling cylindrical and prismatic formats for Apple and Samsung supplier ecosystems.
- Silver Oxide:These cells maintain voltage stability within 1% deviation across discharge curves, preserving mechanical movement accuracy in Swiss and Japanese analog timepieces. REACH nickel compound restrictions are forcing cathode material reformulations ahead of regulatory deadlines.
- Alkaline:Lowest-cost chemistry constrained by mercury and cadmium bans across EU and Chinese regulatory frameworks.
- Nickel Metal Hydride:Limited adoption in hybrid timepieces requiring moderate energy density with reduced environmental hazard classification.
Most installed capacity flows through Silver Oxide. Expansion is steepest in Lithium.
Application:
Volume concentrates in legacy analog segments while value migrates toward connected device categories with integrated sensor arrays.
- Smartwatches:Continuous glucose monitoring, ECG, and SpO2 functionality demand 200-500 mAh rechargeable cells with 500+ cycle durability. FDA-cleared health features in Apple Watch and Samsung Galaxy Watch are accelerating mAh-per-millimeter optimization races among cell designers.
- Analog Watches:Traditional mechanical movements require 1.55V stable output with sub-microamp drain profiles, sustaining decades-long servicing relationships between Swiss manufacturers and replacement networks.
- Digital Watches:LCD and basic LED timekeeping modules utilize cost-optimized alkaline or silver oxide configurations with 2-5 year replacement cycles.
- Hybrid Timepieces:Mechanical movements paired with Bluetooth connectivity create dual-power architectures requiring primary and secondary cell integration.
Hybrid Timepieces command the highest per-unit cell value. Smartwatches are climbing the fastest in absolute volume terms.
Size:
Manufacturing scale inversely correlates with form factor miniaturization, with ultra-thin formats requiring dedicated cleanroom deposition equipment.
- Coin Cell:CR2032 and SR626SW formats dominate standardized volume, enabling automated assembly across Shenzhen and Dongguan production clusters. IEC 60086 dimensional tolerances permit interchangeability that supports global aftermarket distribution.
- Small Cell:Sub-10mm diameter formats for ultra-thin luxury watches require precision stamping and laser welding capabilities concentrated in Japanese and Swiss supplier bases.
- Medium Cell:Mid-range digital watches and fitness trackers utilize these formats where space constraints moderate.
- Large Cell:Limited to early-generation smartwatches and specialized industrial timekeeping devices with relaxed dimensional constraints.
Coin Cell absorbs the majority of production throughput. Small Cell is gaining share fastest in premium mechanical hybrid designs.
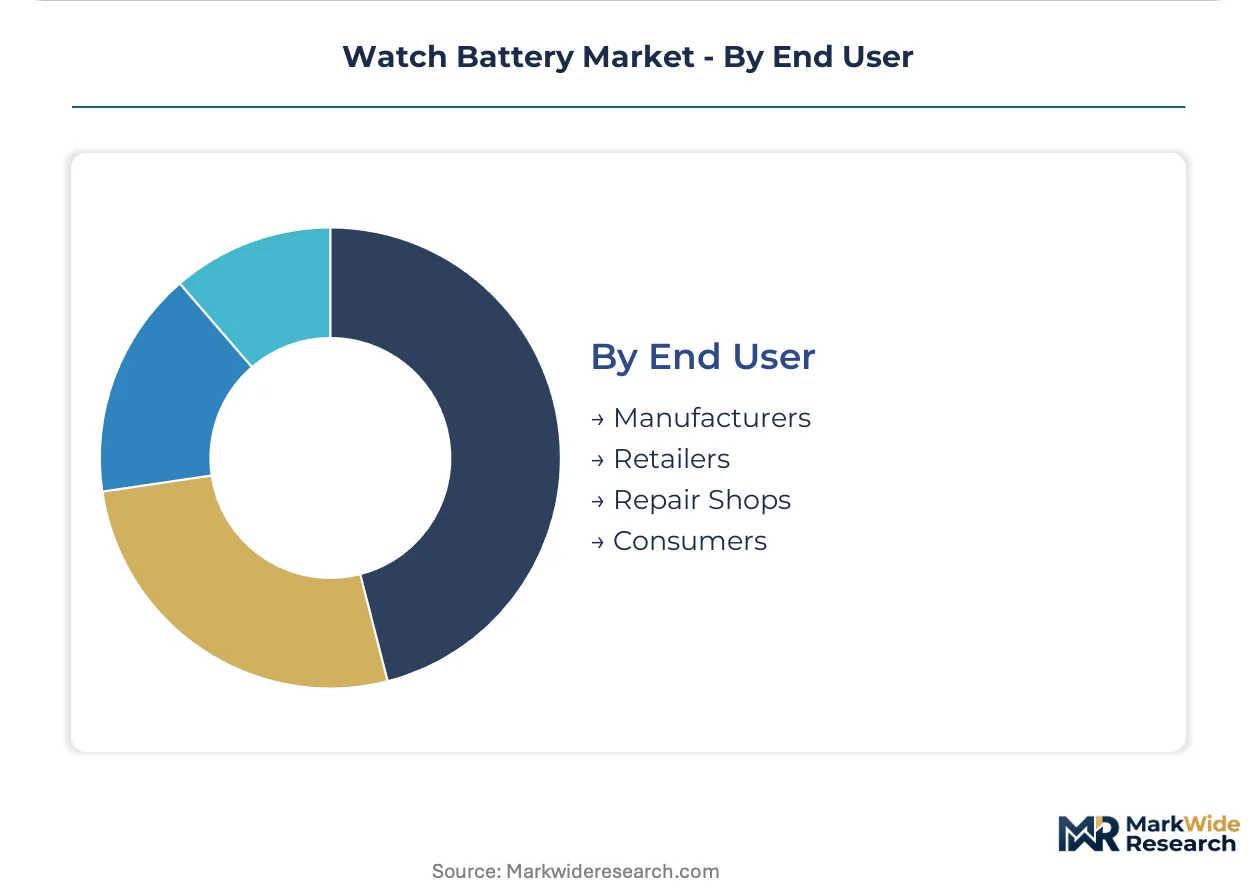
End User:
Procurement patterns bifurcate between OEM specification control and fragmented aftermarket price sensitivity.
- Manufacturers:Apple, Samsung, Garmin, and Fossil Group negotiate multi-year supply agreements with cell producers, embedding UN 38.3 certification and material traceability requirements directly into procurement specifications.
- Repair Shops:Independent watchmakers in Germany, France, and Switzerland source replacement cells through authorized distributor networks, with Renata SA and Maxell capturing premium positioning in European servicing corridors.
- Retailers:Jewelry chains and electronics stores stock standardized coin cell formats for consumer self-replacement, competing on shelf placement and private label positioning.
- Consumers:Direct-to-consumer subscription programs are bypassing traditional retail channels, with manufacturers capturing recurring revenue through automated replacement scheduling.
Manufacturers lock in the largest contract volumes. Repair Shops are shifting procurement fastest toward certified compliant chemistries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate to jurisdictions with lower compliance costs. The EU Battery Regulation's material passport requirements and cadmium restrictions have elevated European production costs. Asian manufacturing clusters absorb this migration through established electronics ecosystems and streamlined environmental permitting.
China
Smartwatch OEM procurement concentrates in Shenzhen and Dongguan contract manufacturing corridors. GB standards on heavy metal content and MIIT dual carbon targets are accelerating lithium coin cell retooling. Guangdong province producers are expanding cleanroom capacity for rechargeable formats serving Apple and Samsung supplier ecosystems.
Switzerland
Luxury mechanical watch servicing sustains premium silver oxide demand through authorized replacement networks. Swissmedic medical device frameworks and REACH nickel compound restrictions are forcing cathode material reformulations. Jura region battery assemblers are consolidating nickel-free chemistry transitions ahead of regulatory deadlines.
Japan
Thin-film solid-state research and MEMS fabrication expertise concentrates in METI-funded national laboratories. JIS standards on button cell dimensional tolerances preserve interchangeability for global aftermarket distribution. Osaka and Nagoya industrial zones host precision stamping capabilities for sub-10mm ultra-thin formats.
United States
Direct-to-consumer subscription battery replacement programs are bypassing traditional jewelry retail channels. FDA-cleared health features in consumer wearables are accelerating rechargeable cell specification requirements. Texas and California logistics hubs are capturing distribution margin pools through automated replacement scheduling infrastructure.
Germany
Independent watchmaker servicing networks in Baden-Württemberg and Bavaria source compliant chemistries through authorized distributor channels. KBA transport certification alignment with UN 38.3 lithium shipping rules is compressing product launch timelines. Frankfurt and Hamburg trading corridors are consolidating European aftermarket procurement for Renata SA and Maxell premium positioning.
Watch Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with chemistry expertise determining premium positioning versus volume scale. The vendor base concentrates around Swiss-Japanese precision specialists and Chinese contract assemblers serving consumer electronics OEMs. Three archetypes dominate: heritage-branded servicing specialists, Asian scale producers, and diversified electronics conglomerates with captive battery divisions. Competitive moves center on chemistry transition acceleration and direct-to-consumer channel capture.
Within the heritage-branded tier, Renata SA and Maxell, Ltd. exemplify positioning built on authorized distributor relationships and Swiss-Japanese manufacturing credibility. Panasonic Energy Europe n.v. occupies the diversified conglomerate archetype, leveraging electronics group resources for hybrid timepiece cell development. These three anchors illustrate how regulatory compliance capabilities and servicing network access separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Renata SA |
| Maxell, Ltd. |
| Panasonic Energy Europe n.v. |
| Sony Corporation |
| Duracell Inc. |
| Camelion Battery Co., Ltd. |
| EVE Energy |
| GPB International Limited |
| NANFU BATTERY |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between UN 38.3 lithium transport certified cells and uncertified commodity alternatives manifests in pricing spreads exceeding three-to-one multiples, while simultaneously concentrating premium-tier procurement through Shenzhen contract manufacturers with in-house testing laboratories and compressing commodity alkaline margins through Dongguan price competition.
Pricing Analysis
Distributor markups in European servicing networks absorb margin pools previously held by jewelry retailers, while direct-to-OEM volume discounts compress unit economics for lithium coin cell producers serving Apple and Samsung ecosystems. Price differentiation rests on IEC 60086 safety certification tiers and material traceability documentation depth. Cost compression in alkaline formulations intensifies because REACH mercury bans eliminated chemistry-compliant suppliers. Repair shops in Germany and Switzerland exhibit highest price sensitivity; luxury watch OEMs in Jura region show lowest.
Supply Chain Analysis
Electrochemical engineering talent scarcity in Guangdong province and Jura region constrains cleanroom operator availability for thin-film deposition lines. Geographic supply concentration centers on China, Japan, and Switzerland. Raw material dependencies draw from cobalt refining in Chinese state-owned enterprises, silver oxide precursor chemicals in Japanese specialty chemical producers, and lithium carbonate from South American brine operations. Single-source vulnerability in cobalt sulfate creates supply interruption exposure. Distribution runs through authorized distributor networks in European servicing corridors and direct OEM procurement in Asian electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in solid-state electrolyte transitions and subscription replacement channel capture, with chemistry compliance costs acting as the primary cost-down driver through regulatory arbitrage relocation.
For Market Incumbents: Hedge against silver oxide demand erosion by diversifying into rechargeable lithium formats for hybrid timepiece OEMs. Accelerate nickel-free cathode material transitions ahead of REACH sunset deadlines. Defensive consolidation through captive control over Swiss and Japanese precision stamping capabilities preserves ultra-thin format positioning against Chinese contract manufacturer encroachment. For New Entrants and Emerging Players: Authorized distributor partnerships in German and French watchmaker servicing networks offer lowest competitive density for compliant chemistry market entry. Target India's PLI-subsidized manufacturing corridors for lithium cell assembly capacity. White-space penetration runs through direct-to-consumer subscription programs bypassing traditional jewelry retail markups. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance capabilities concentrate in heritage-branded servicing specialists with documented alternative substance assessments. Five-to-ten year viability favors producers with dual chemistry lithium and silver oxide production flexibility. Acquisition target archetype: Swiss-Japanese precision specialists with MEMS fabrication integration. Signal to watch: EU Battery Regulation passport implementation timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte R&D Partnership | Thin-film solid-state convergence with MEMS fabrication enables sub-millimeter cell formats for luxury hybrid timepieces. |
| Subscription Replacement Platform Launch | Direct-to-consumer battery replacement programs capture recurring revenue streams from independent watchmaker networks. |
| India PLI Manufacturing Relocation | Gujarat and Tamil Nadu industrial corridors offer subsidized capacity for advanced chemistry cell production. |
| Nickel-Free Cathode Reformulation | REACH authorization requirements force silver oxide producers to document alternative substance assessments ahead of deadlines. |
| Material Traceability System Deployment | EU Battery Regulation passport requirements elevate compliance costs for small-format cell producers serving European brands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell design engineers at Swiss and Japanese precision manufacturers, procurement leads at Shenzhen contract assemblers, regulatory affairs specialists at EU battery trade associations, and independent watchmaker servicing network operators in Germany and France with secondary validation against IEC standards documentation, UN transport regulation filings, ECHA REACH authorization databases, and MIIT dual carbon policy disclosures. Bottom-up cell shipment estimates triangulated against top-down OEM procurement disclosures.
Segment-weighting approaches applied chemistry type, application category, form factor size, and end-user procurement pattern dimensions across the modeling period. CAGRs derived from regression analysis of historical shipment volumes against smartwatch OEM production forecasts and analog watch servicing replacement cycle data. Industry-specific inputs included continuous glucose monitoring feature penetration rates in consumer wearables and REACH nickel compound restriction implementation timelines.
Revisions become necessary when EU Battery Regulation passport enforcement timelines accelerate, solid-state electrolyte commercialization breakthroughs collapse energy density constraints, or cobalt supply disruption triggers chemistry substitution waves. Forecasts reflect documented assumptions about regulatory implementation pacing and technology convergence trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Middle East and Africa SLI Battery Market
Batteries
Power Tool Batteries Market
Batteries
Japan Mobile Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
48 Volt Battery System Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Global Zinc Air Batteries Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Smart Battery Market
Batteries
Forklift Battery Charger Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Power Battery Cells Market