
 Nickel Cadmium Battery Market | 2026-2036
Nickel Cadmium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Cadmium Battery Market Intelligence
China's expanding manufacturing base for industrial battery systems is tilting toward heavy-duty applications. Saft Groupe SAS dominates European aerospace and defense contracts with specialized ventilated cell designs. EnerSys leverages its global service network to sustain aftermarket revenue from telecom backup installations. HBL Power Systems Limited anchors the Indian railway electrification segment with pocket plate Ni-Cd batteries engineered for tropical climates.
A nickel cadmium battery is a rechargeable electrochemical cell employing nickel oxide hydroxide and metallic cadmium electrodes with an alkaline electrolyte of potassium hydroxide, typically operating across temperature extremes from minus forty to plus fifty degrees Celsius. Its primary commercial purpose centers on delivering reliable backup power in harsh environments where lithium-ion thermal stability proves inadequate. Sealed Ni-Cd cells occupy the largest volume share in medical equipment and emergency lighting where maintenance-free operation commands premium positioning. Pocket plate Ni-Cd variants lead margin pools in railway and telecommunications applications due to their extended cycle life and tolerance to deep discharge regimes.
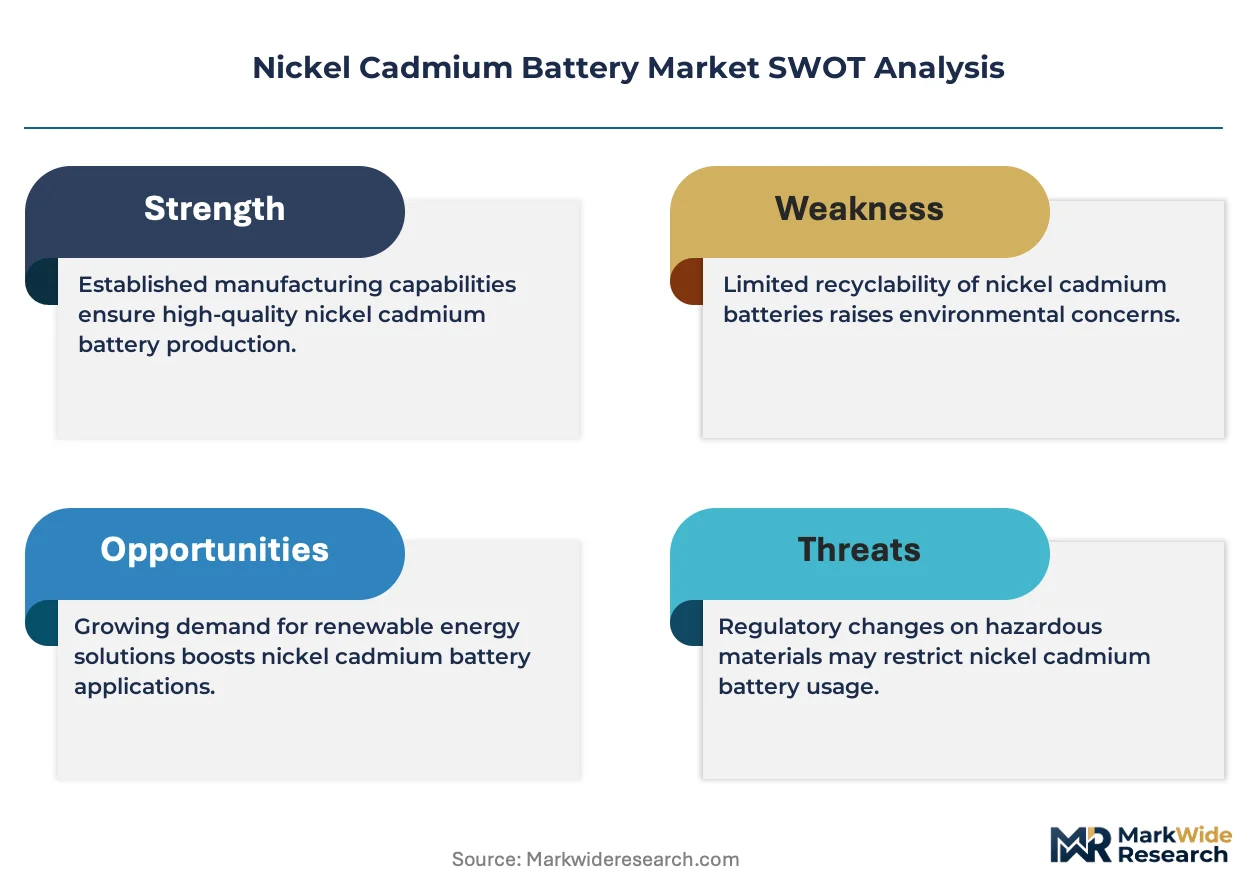
The EU REACH regulation and RoHS directive constrain cadmium deployment in consumer electronics across Europe, while India's BIS certification mandates specific performance benchmarks for railway battery procurement. China's GB standards and MIIT directives govern domestic Ni-Cd manufacturing emissions and recycling chain accountability. Stakeholders must monitor evolving hazardous substance restrictions and assess captive recycling capabilities before committing to long-term capacity investments.
Market Dynamics
EU REACH cadmium restrictions are forcing a wholesale pivot from consumer electronics toward industrial-grade sealed cells, compressing addressable volume while concentrating margin pools in railway and defense procurement channels.
Growth Catalysts
- Railway Electrification Mandates:India's Dedicated Freight Corridor and metro expansion programs specify pocket plate Ni-Cd batteries for tropical climate resilience, anchoring procurement volume through 2035.
- REACH Regulatory Arbitrage:European industrial battery exemptions for aerospace and defense applications redirect manufacturing capacity toward premium ventilated cell designs with 20-year service life guarantees.
- Deep Discharge Tolerance:Telecommunications backup installations in remote geographies favor Ni-Cd chemistry over lithium-ion for operational reliability across uncontrolled temperature swings.
Market Restraints
- Cadmium Price Volatility:Primary cadmium supply concentrates in zinc smelting byproduct streams, exposing cell manufacturers to base metal processing economics beyond battery demand cycles.
- Substitution by Lithium Iron Phosphate:Stationary energy storage and commercial UPS segments are migrating to LFP chemistry as thermal management systems improve and unit costs compress.
- EU RoHS Scope Creep:Ongoing regulatory review threatens to narrow industrial exemptions, constraining future addressable market definition for European production facilities.
Strategic Opportunities
- Defense Electrification:NATO military vehicle modernization programs specify Ni-Cd for battlefield reliability where thermal runaway risks disqualify lithium alternatives.
- Recycling Infrastructure Control:Closed-loop cadmium recovery capabilities create regulatory compliance advantages and input cost hedges against primary metal volatility.
- Sub-Saharan Railway Projects:Chinese-financed African rail corridors specify tropical-grade pocket plate batteries, opening export channels for Indian and Chinese manufacturers with climate-hardened product lines.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Ni-Cd specialized R&D expertise has atrophied as academic programs pivot to lithium-ion, constraining incremental innovation pipelines.
- BIS Certification Timelines:Indian railway procurement requires 18-24 month qualification cycles for new cell designs, freezing product iteration speed relative to substitute chemistries.
- Legacy System Integration:Existing railway and telecom backup architectures use proprietary charging profiles, complicating drop-in replacement with modified cell formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Cadmium Battery Market |
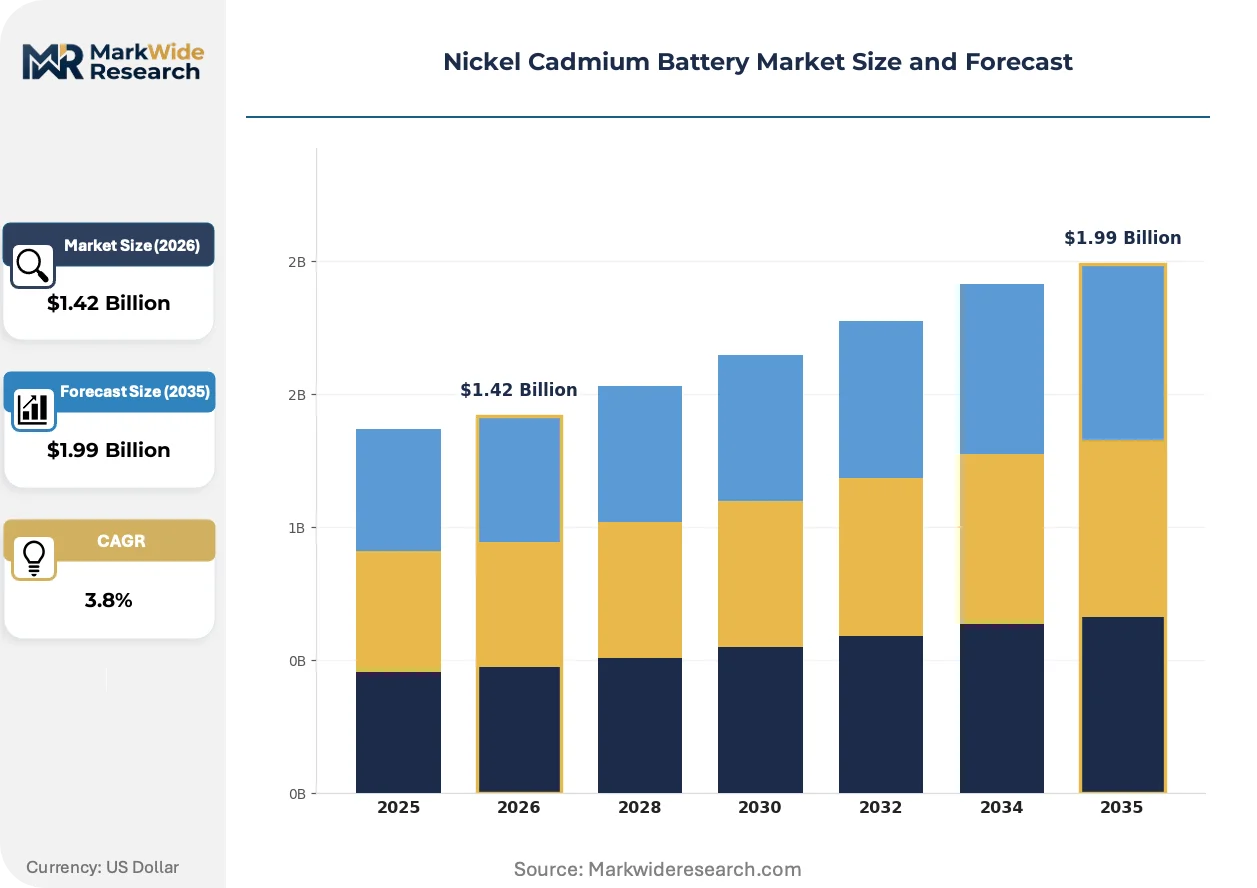
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $1.99 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Ni-Cd, Ventilated Ni-Cd, Cylindrical Ni-Cd, Prismatic Ni-Cd, Pocket Plate Ni-Cd Application: Power Tools, Uninterruptible Power Supply, Medical Equipment, Aerospace Systems, Emergency Lighting End User Industry: Consumer Electronics, Military & Defense, Telecommunications, Renewable Energy, Railways Charging Technology: Fast Charging, Trickle Charging, Pulse Charging, Smart Charging, Thermal Management |
| Companies Covered | ALCAD, HBL Power Systems Limited, Saft Groupe SAS, Exide Industries Ltd., Panasonic Energy, EnerSys, HOPPECKE Batterien GmbH & Co. KG, Cell-Con Inc., GS Yuasa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Cadmium Battery Market Strategic Shifts & Innovations
Battery architecture is converging around service-life extension and closed-loop material recovery, displacing pure cost-minimization as the dominant design priority across industrial procurement specifications.
Sintered plate electrode technology is hybridizing with fiber-structured nickel matrices to improve active material utilization rates. Railway operators in India and China are qualifying these hybrid designs for 25-year service intervals in tropical climates. The structural consequence is compressing aftermarket replacement revenue while front-loading contract values toward initial system procurement.
Europe's F-Gas Regulation and REACH Annex XVII amendments are tightening hazardous substance tracking across battery supply chains. Industrial cell manufacturers must now document cadmium provenance from smelter through final assembly. Aerospace and defense contractors are responding by consolidating supplier bases to vertically integrated producers with captive recycling capabilities.
Chinese state-owned rail operators are unbundling battery procurement from rolling stock contracts, creating direct vendor relationships previously intermediated by system integrators. This channel shift compresses margin capture by European battery specialists while expanding addressable market access for domestic manufacturers. The pattern is most visible in CRRC's metro electrification programs across Tier 2 and Tier 3 provincial cities.
Nickel Cadmium Battery Market Segmentation
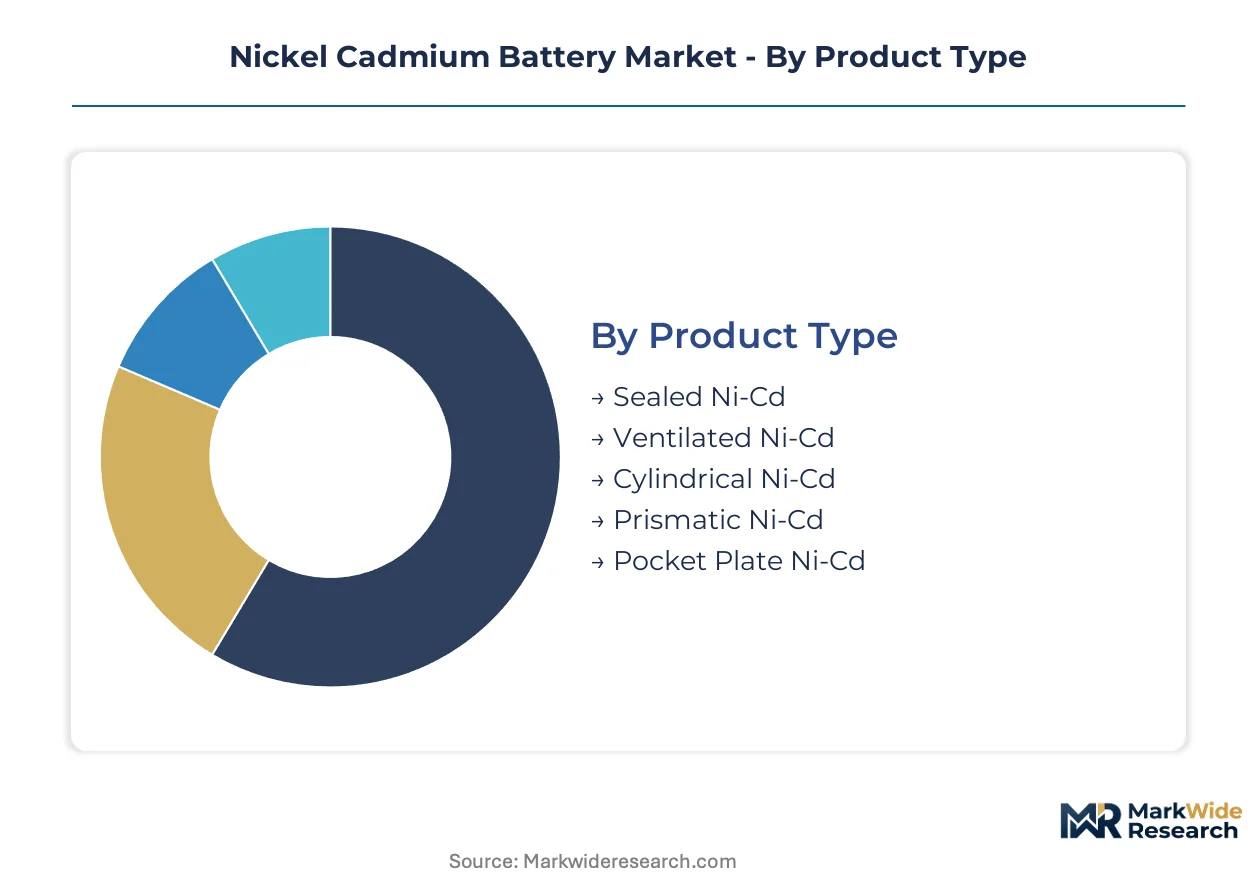
Ni-Cd battery procurement specifications diverge sharply across end-use environments, with railway electrification programs demanding tropical-grade pocket plate designs while aerospace contractors prioritize ventilated cells with multi-decade service guarantees. Understanding these segment boundaries clarifies where margin pools concentrate versus where substitution pressure from lithium-ion chemistry intensifies.
Product Type:
Engineering teams specify cell architecture based on thermal management requirements, maintenance access, and duty cycle severity across the use-case spectrum.
- Pocket Plate Ni-Cd:Electrodes consist of perforated nickel-plated steel pockets filled with active material, delivering exceptional deep discharge recovery and mechanical robustness for vibration-intensive environments. Indian railway procurement under BIS certification mandates these designs for tropical climate resilience on the Dedicated Freight Corridor, locking in long-term supply agreements with domestic manufacturers.
- Sealed Ni-Cd:Starved electrolyte designs with recombination chemistry eliminate maintenance requirements and enable installation in confined spaces without ventilation infrastructure. Medical equipment and emergency lighting installations across European healthcare facilities specify these cells for regulatory compliance with EU F-Gas Regulation hazardous substance tracking requirements.
- Ventilated Ni-Cd:Flooded electrolyte systems with gas venting accommodate high-rate discharge and extended cycling in uncontrolled temperature environments.
- Cylindrical Ni-Cd:Standardized form factors suit legacy power tool platforms and portable equipment where dimensional interchangeability preserves aftermarket value.
- Prismatic Ni-Cd:Rectangular cell geometries optimize volumetric efficiency in space-constrained railway and telecom cabinet installations.
The dominant share belongs to Pocket Plate Ni-Cd, while Sealed Ni-Cd is closing the gap fastest as REACH restrictions compress ventilated cell addressable markets.
Application:
Performance specifications harden around reliability metrics as application criticality escalates from convenience tools to life-safety systems.
- Aerospace Systems:Ventilated Ni-Cd configurations with sintered plate technology deliver the thermal stability and fault tolerance required for flight-critical backup power. European defense contractors under NATO procurement guidelines specify these cells for military aircraft where lithium-ion thermal runaway risks are disqualifying.
- Uninterruptible Power Supply:Stationary backup installations in remote telecommunications infrastructure favor Ni-Cd chemistry for tolerance to uncontrolled temperature swings and deep discharge cycling without battery management system complexity.
- Emergency Lighting:Regulatory mandates across multiple jurisdictions require maintained illumination systems with demonstrated reliability across temperature extremes.
- Power Tools:Professional-grade cordless equipment continues specified Ni-Cd compatibility for vibration resistance and cost predictability in fleet replacement cycles.
- Medical Equipment:Patient-connected devices specify sealed cells for maintenance-free operation and compliance with electromagnetic compatibility standards.
Aerospace Systems commands the premium pricing tier, though UPS applications are expanding most quickly as telecom infrastructure hardens against climate volatility.
End User Industry:
Procurement sophistication varies from commodity purchasing in consumer channels to engineered specifications with decade-long qualification cycles in regulated industries.
- Railways:Chinese state-owned operators and Indian railway electrification programs specify tropical-grade pocket plate batteries with 25-year service intervals, unbundling procurement from rolling stock contracts to create direct vendor relationships. CRRC's metro expansion across Tier 2 and Tier 3 provincial cities anchors volume concentration.
- Military & Defense:NATO vehicle modernization and battlefield power systems prioritize Ni-Cd for reliability under thermal stress where alternative chemistries fail safety protocols.
- Telecommunications:Remote base station backup requirements favor deep discharge tolerance over energy density optimization.
- Consumer Electronics:EU REACH cadmium restrictions have eliminated this channel for European manufacturers, redirecting residual volume toward industrial exemptions.
- Renewable Energy:Grid-scale storage procurement increasingly favors lithium iron phosphate as thermal management economics improve.
Railways holds the largest committed procurement pipeline, while Military & Defense shows the steepest expansion trajectory as electrification programs accelerate.
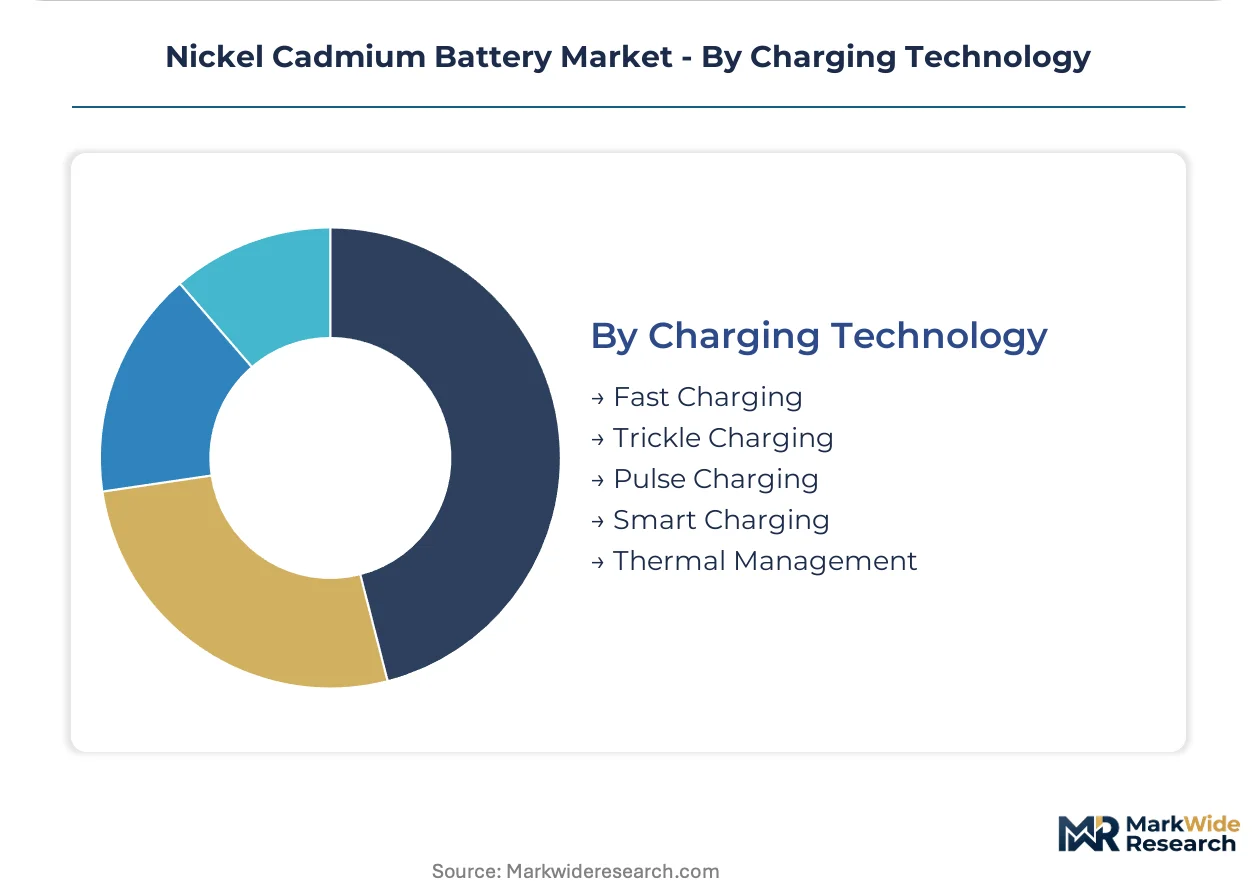
Charging Technology:
Charging infrastructure compatibility constrains cell selection as legacy railway and telecom architectures embed proprietary control profiles.
- Trickle Charging:Continuous low-rate maintenance charging preserves standby readiness in emergency lighting and alarm systems without electrolyte depletion. European building codes mandate this charging mode for life-safety battery backup systems.
- Smart Charging:Microprocessor-controlled charge termination with temperature compensation extends cycle life in premium industrial applications. Indian railway specifications increasingly require smart charging integration for remote monitoring of battery health across the Dedicated Freight Corridor.
- Fast Charging:High-rate current acceptance enables rapid turnaround for industrial equipment with intensive duty cycles.
- Pulse Charging:Intermittent current delivery reduces crystalline formation and extends service life in deep-cycle applications.
- Thermal Management:Active heating and cooling systems expand operable temperature range for extreme environment deployments.
Trickle Charging retains the widest installed base, though Smart Charging is gaining share fastest as digital monitoring requirements penetrate industrial procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT directives in China anchor the dominant geography for Ni-Cd battery deployment, with cadmium supply chain governance and railway electrification programs converging on industrial-grade sealed cell production. Regulatory frameworks in India, Europe, and select industrial economies shape procurement specifications and manufacturing compliance requirements across distinct climate and application environments.
China
CRRC's metro expansion across Tier 2 and Tier 3 provincial cities drives pocket plate battery procurement for tropical-grade installations. GB standards and MIIT directives govern domestic manufacturing emissions and recycling chain accountability for cadmium handling. The Yangtze River Delta cluster concentrates cell fabrication capacity serving state-owned rail operators now unbundling battery procurement from rolling stock contracts.
India
The Dedicated Freight Corridor and urban metro programs specify pocket plate Ni-Cd batteries engineered for tropical climate resilience and deep discharge recovery. BIS certification mandates 18-24 month qualification cycles for new cell designs entering railway procurement channels. HBL Power Systems Limited anchors domestic manufacturing from Hyderabad, supplying tropical-hardened product lines for electrification infrastructure.
Germany
Industrial battery procurement from HOPPECKE Batterien GmbH & Co. KG concentrates in railway backup and telecom infrastructure applications requiring REACH Annex XVII compliance. The EU F-Gas Regulation tightens hazardous substance tracking across supply chains, favoring vertically integrated producers with captive recycling capabilities. Bavaria-based engineering clusters specialize in ventilated cell designs for aerospace and defense contractors under NATO procurement guidelines.
France
Saft Groupe SAS dominates European aerospace and defense contracts with specialized ventilated cell configurations delivering multi-decade service guarantees. ECHA oversight of REACH cadmium restrictions redirects manufacturing capacity toward industrial exemptions for military aircraft where lithium-ion thermal runaway risks are disqualifying. The Paris-Saclay industrial corridor hosts qualification facilities for flight-critical backup power systems.
Japan
GS Yuasa Corporation occupies a position within the industrial battery tier serving railway and telecommunications segments across East Asian markets. METI oversight of battery recycling infrastructure supports closed-loop cadmium recovery capabilities creating regulatory compliance advantages. The Kanto region maintains electrode manufacturing expertise for sintered plate technology hybridizing with fiber-structured nickel matrices.
Nickel Cadmium Battery Market Key Industry Players
Vertically integrated specialists and regional engineering houses split the market across distinct procurement channels defined by qualification complexity and regulatory jurisdiction. European producers concentrate on aerospace and defense exemptions under REACH, while Asian manufacturers capture railway electrification volume through climate-hardened pocket plate designs. Two dominant competitive moves are reshaping positioning: consolidation of supplier bases toward producers with captive recycling capabilities, and geographic expansion through Chinese-financed rail corridors in Sub-Saharan Africa.
Within the premium industrial tier, Saft Groupe SAS and HOPPECKE Batterien GmbH & Co. KG exemplify European specialists anchored to defense and railway procurement channels requiring REACH-compliant hazardous substance documentation. HBL Power Systems Limited represents the regional engineering house archetype, occupying a position within Indian railway electrification through BIS-certified tropical-grade manufacturing. These three companies illustrate how regulatory arbitrage and climate-specific engineering create defensible positioning against lithium-ion substitution pressure.
| Leading Market Players |
|---|
| ALCAD |
| HBL Power Systems Limited |
| Saft Groupe SAS |
| Exide Industries Ltd. |
| Panasonic Energy |
| EnerSys |
| HOPPECKE Batterien GmbH & Co. KG |
| Cell-Con Inc. |
| GS Yuasa Corporation |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta cluster concentrates pocket plate cell fabrication capacity serving Chinese state-owned rail operators, and this geographic density translates into asymmetric pricing power for domestic manufacturers against European specialists. Contract values for tropical-grade railway batteries front-load toward initial procurement as 25-year service intervals compress replacement revenue, forcing margin capture toward certification premiums and captive recycling capabilities.
Pricing Analysis
European ventilated cell quotations command substantial premiums over Chinese pocket plate offerings, with aerospace and defense procurement under NATO guidelines absorbing the widest spreads. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant hazardous substance documentation tiers, with after-sales service bundling adding further differentiation. Cost compression in standard-grade telecom backup segments is intensifying because lithium iron phosphate substitution pressure constrains Ni-Cd addressable volume. Railway procurement offices in India exhibit the highest price sensitivity due to BIS-mandated qualification cycles, while European defense contractors demonstrate the least.
Supply Chain Analysis
HBL Power Systems Limited and Saft Groupe SAS anchor contract manufacturing concentration for tropical-grade and aerospace-grade cells respectively. Primary cadmium supply draws from zinc smelting byproduct streams concentrated in China, South Korea, and Kazakhstan, with electrode manufacturing resting on nickel powder and potassium hydroxide feedstocks. Single-source vulnerability in cadmium recovery infrastructure poses structural risk as REACH Annex XVII tightens provenance documentation requirements. Distribution runs through direct vendor relationships with state-owned rail operators, bypassing system integrators previously intermediating battery procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to railway electrification capital expenditure cycles, with Chinese metro expansion programs and Indian Dedicated Freight Corridor commitments providing the dominant cyclical driver.
For Market Incumbents: Harden defensive positioning by securing captive cadmium recycling capabilities ahead of REACH Annex XVII provenance mandates, and deepen backward integration into nickel powder processing to hedge input cost volatility. Lithium iron phosphate substitution in telecom backup segments demands channel control reinforcement through smart charging integration and remote monitoring service bundling.
For New Entrants and Emerging Players: Sub-Saharan African rail corridors financed through Chinese development institutions represent the most penetrable geographic white space, with tropical-grade pocket plate specifications mirroring Indian railway requirements. Target defense electrification programs in NATO-aligned Eastern European markets where thermal runaway disqualification of lithium alternatives sustains Ni-Cd demand. A go-to-market angle emphasizing closed-loop material recovery and regulatory compliance documentation differentiation offers the clearest positioning against established European specialists.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated producers with captive recycling infrastructure and multi-decade service contract backlogs. Long-term viability hinges on railway electrification durability and defense procurement continuity rather than volume expansion. Acquisition targets should demonstrate BIS or REACH qualification completion and tropical climate engineering capabilities. The signal to watch is lithium iron phosphate thermal management cost compression in stationary backup applications, which would accelerate substitution pressure and compress residual addressable market definition.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure Buildout | REACH Annex XVII compliance and input cost hedging against cadmium price volatility. |
| Smart Charging Integration Development | Remote battery health monitoring for Indian Dedicated Freight Corridor specifications. |
| Tropical Climate Engineering Qualification | BIS certification enabling procurement on CRRC metro expansion programs. |
| Defense Contract Consolidation | NATO procurement guidelines favoring multi-decade service guarantee capabilities. |
| Sub-Saharan Distribution Partnership | Chinese-financed African rail corridor access for climate-hardened product lines. |
Research Approach
Initial hypotheses were tested against primary input from railway procurement officers, battery plant engineering directors, defense contractor supply chain managers, and telecom infrastructure planners, and refined through secondary validation against MIIT directive filings, BIS certification databases, ECHA REACH guidance documents, and customs trade flow records. Bottom-up cell shipment estimates were triangulated with top-down railway electrification capital expenditure projections.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by electrode architecture, application criticality tiers, end-user industry procurement sophistication, and charging technology compatibility requirements. CAGRs were derived from regression analysis of historical railway electrification program commitments and defense procurement cycle patterns, with cadmium price volatility assumptions and lithium substitution elasticity parameters as key sensitivity inputs.
Practitioners should monitor cadmium spot price movements, REACH exemption review timelines, and lithium iron phosphate thermal management cost trajectories for early signals of forecast revision necessity. Quarterly review of Indian railway tender issuance patterns and CRRC unbundling announcement cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Solid-State Car Battery Market
Batteries
Battery Wash System Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Medical Batteries Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
Electric Battery Market
Batteries
India Alkaline Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
East Europe Battery Market
Batteries
Global Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
South Korea Rechargeable Battery Market
Batteries
Europe SLI Battery Market
Batteries
Printable Battery Market