
 South America Rechargeable Battery Market | 2026-2036
South America Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Rechargeable Battery Market Insights
UN 38.3 lithium battery transport certification is unwinding competitive access across South America, forcing importers and assemblers into multi-month qualification cycles before customs clearance. BYD Company Ltd leverages its in-house cell production to bypass third-party certification bottlenecks in Chile and Colombia. Samsung SDI anchors its regional position through distributor partnerships with Brazilian industrial OEMs. Exide Industries Ltd competes on lead-acid replacement cycles in Argentina's mining and telecom backup sectors.
A rechargeable battery is an electrochemical energy storage device designed for repeated charge-discharge cycles, typically employing lithium-ion chemistry with nominal voltages of 3.2–3.7 V per cell and energy densities exceeding 250 Wh/kg for NMC formulations, serving to power mobile equipment, grid-tied storage installations, and electric drivetrains. Lithium-ion cells dominate value capture due to their superior cycle life and energy density, while lead-acid retains substantial volume in price-sensitive industrial backup roles across the Andean region. Sodium-ion chemistry represents an emerging structural bet for mining and utility buyers seeking to reduce cobalt and nickel supply exposure.
ANVISA in Brazil and the country's national energy regulator enforce safety and grid-interconnection standards that determine which battery systems qualify for renewable energy storage tenders and electric vehicle subsidies. Argentina's mining secretariat and Chile's environmental evaluation service add layers of site-specific permitting for large-scale industrial deployments. Stakeholders must track how evolving MERCOSUR technical regulations harmonize—or fragment—cross-border product approval pathways.
Market Dynamics
UN 38.3 lithium battery transport certification is compressing competitive entry timelines across South America, forcing importers and assemblers into multi-month qualification cycles before customs clearance while rewarding producers with captive cell manufacturing capabilities.
Growth Catalysts
- Inova Energia program:Brazil's industrial policy shapes local assembly incentives for lithium-ion pack production, drawing component suppliers to Minas Gerais and São Paulo states.
- Electric bus fleet procurement:Santiago's municipal transit authority anchors demand at the fleet level, establishing reference procurement specifications adopted by Colombian and Peruvian operators.
- MERCOSUR technical regulation harmonization:Cross-border product approval pathways are converging, reducing duplicate testing costs for Brazil-Argentina battery trade corridors.
Market Restraints
- Lithium carbonate price volatility:Chilean and Argentine brine extraction concentration exposes cell assemblers to input cost swings that compress margin visibility on long-dated supply contracts.
- UN 38.3 certification bottlenecks:Third-party testing capacity scarcity in the region extends qualification timelines, advantaging producers with in-house UN-certified laboratories.
- Lead-acid replacement cycle inertia:Mining and telecom backup buyers in the Andean region retain price-sensitive procurement habits that slow lithium-ion penetration in industrial stationary applications.
Strategic Opportunities
- Sodium-ion chemistry deployment:Mining and utility buyers in Chile and Peru are evaluating cobalt-free and nickel-free formulations to reduce supply chain concentration risk.
- Grid-interconnection standards evolution:ANVISA and Brazil's national energy regulator are expanding qualifying battery systems for renewable energy storage tenders, opening new revenue pools for certified integrators.
- Argentina's mining secretariat permitting:Site-specific approvals for large-scale industrial deployments are streamlining, enabling earlier-stage project development in lithium triangle extraction zones.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management specialists command premium compensation in São Paulo's manufacturing corridor, constraining expansion timelines for new entrants.
- Capex intensity for formation and aging equipment:Lithium-ion cell finishing lines require substantial upfront investment, disadvantaging regional assemblers against integrated producers with captive equipment supply.
- Legacy system integration complexity:Industrial buyers in Argentina's mining sector face technical friction retrofitting lithium-ion replacements into existing lead-acid charging infrastructure and battery management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Rechargeable Battery Market |
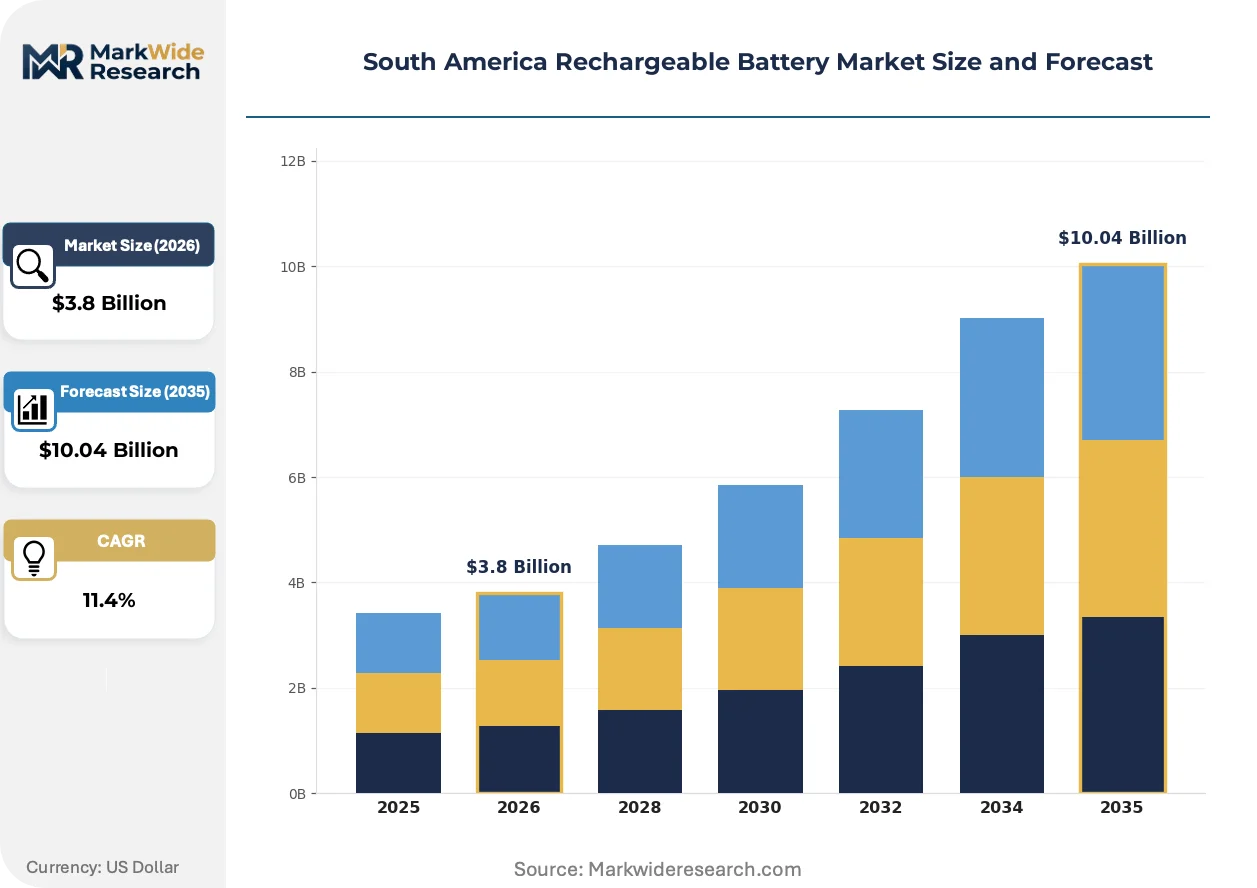
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Metal Hydride, Lead-acid, Sodium-ion Application: Consumer Electronics, Automotive, Industrial, Renewable Energy Storage End User: Manufacturers, Retailers, End Consumers, Utilities Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | BYD Company Ltd, Duracell Inc., Panasonic Holdings Corporation, EnerSys, Exide Industries Ltd, Samsung SDI, FIAMM Energy Technology SpA, Saft Groupe SA, Clarios, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Rechargeable Battery Market Trends and Innovations
Technology substitution and regulatory convergence are compressing traditional competitive advantages in South American battery markets, with chemistry evolution and certification requirements reshaping who can participate in high-value segments.
Lithium iron phosphate (LFP) cathode formulations are gaining traction in electric bus and energy storage applications due to superior thermal stability and extended cycle life compared to nickel-manganese-cobalt alternatives. Brazilian fleet operators and Chilean utility buyers are specifying LFP-dominant procurement tenders to reduce fire risk and simplify thermal management system design. This chemistry migration is supplanting NMC cell demand in price-sensitive, high-utilization segments where energy density trade-offs are acceptable.
ANVISA safety standards and Brazil's national energy regulator grid-interconnection mandates are determining which battery systems qualify for renewable energy storage tenders and electric vehicle subsidies. Industrial OEMs are restructuring product development roadmaps to front-load certification compliance, treating regulatory approval as a competitive moat rather than a post-development formality. Energy storage integrators in São Paulo and Minas Gerais states face the most concentrated compliance burden, with tender eligibility contingent on full certification documentation.
Direct procurement relationships between cell producers and end-use fleet operators are displacing traditional distributor-mediated supply chains in high-volume segments. Chilean mining companies and Colombian transit authorities are negotiating multi-year offtake agreements that specify cell chemistry, cycle life guarantees, and recycling obligations, compressing distributor margin capture. This channel restructuring is most visible in Santiago's electric bus procurement and Peru's utility-scale storage deployments, where volume concentration rewards direct engagement models.
South America Rechargeable Battery Market Segmentation
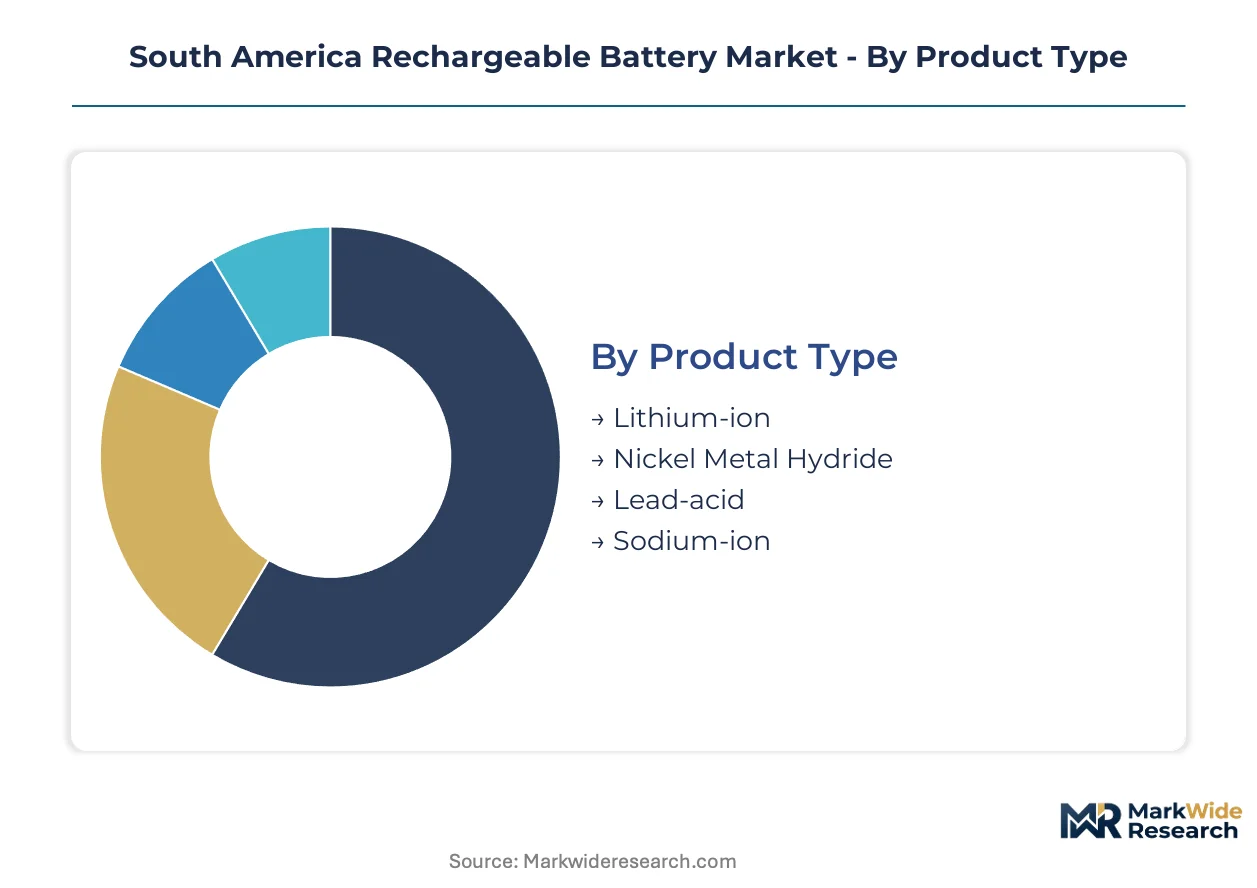
Segmentation in South America's rechargeable battery market reveals how chemistry choices, application requirements, and channel structures concentrate value capture differently across Brazil's manufacturing corridor versus Andean mining zones. Understanding these splits exposes where certification burdens, supply chain access, and procurement scale reshape competitive positioning.
Product Type:
Lithium-ion dominates Brazilian domestic assembly while sodium-ion draws cross-border technology interest from Chilean and Peruvian mining operators seeking supply chain risk reduction.
- Lithium-ion:Cells employing layered oxide or phosphate cathode chemistries with nominal voltages of 3.2–3.7 V serve electric bus fleets in Santiago and grid-tied storage tenders governed by ANVISA certification requirements. Brazilian pack assemblers in Minas Gerais concentrate procurement of NMC and LFP formulations for automotive and stationary applications.
- Sodium-ion:Emerging chemistry utilizing abundant sodium intercalation materials eliminates cobalt and nickel feedstock exposure. Chilean mining companies and Peruvian utility buyers are evaluating pilot deployments to reduce dependency on Argentine and Chilean brine supply concentration.
- Lead-acid:Mature electrochemical technology with lower energy density retains substantial volume in Argentine mining backup and telecom infrastructure across the Andean region where price sensitivity dominates procurement.
- Nickel Metal Hydride:Older rechargeable chemistry with moderate energy density persists in limited consumer electronics and hybrid vehicle applications where established supply relationships reduce switching incentives.
Lithium-ion holds the largest share; momentum sits with sodium-ion.
Application:
Cost tier stratification separates premium-certified automotive systems from price-pressured industrial backup segments across regional deployment patterns.
- Automotive:Electric drivetrain and auxiliary power applications specify UN 38.3 certified packs with thermal management systems. Santiago's municipal bus procurement establishes reference specifications adopted by Colombian and Brazilian fleet operators.
- Renewable Energy Storage:Grid-interconnected battery systems qualifying for Brazilian regulator tenders require ANVISA safety documentation and formation traceability. São Paulo and Minas Gerais integrators face concentrated compliance burdens for utility-scale deployments.
- Industrial:Forklift, mining equipment, and stationary backup applications span lead-acid replacement cycles in Argentina's extraction zones and lithium-ion adoption in Brazilian manufacturing facilities.
- Consumer Electronics:Portable power applications for smartphones, laptops, and personal devices flow through distributor-mediated channels with less stringent certification requirements than automotive or grid segments.
Automotive commands premium pricing; renewable energy storage is climbing the fastest.
End User:
Customer type determines whether procurement flows through specification-heavy tender processes or price-optimized spot purchasing across the region.
- Utilities:Grid operators and renewable energy developers in Brazil and Chile issue multi-year tenders with chemistry specifications, cycle life guarantees, and recycling obligations that compress distributor margins.
- Manufacturers:Brazilian industrial OEMs and automotive assemblers source certified packs through direct relationships with cell producers, bypassing traditional distribution layers for volume commitments.
- Retailers:Electronics and automotive parts distributors serve fragmented consumer and small commercial demand with standardized product lines and limited technical customization.
- End Consumers:Individual purchasers of replacement batteries and portable power products drive lowest-margin volume through online retail and wholesale channels.
Utilities concentrate value; manufacturers are gaining procurement sophistication fastest.
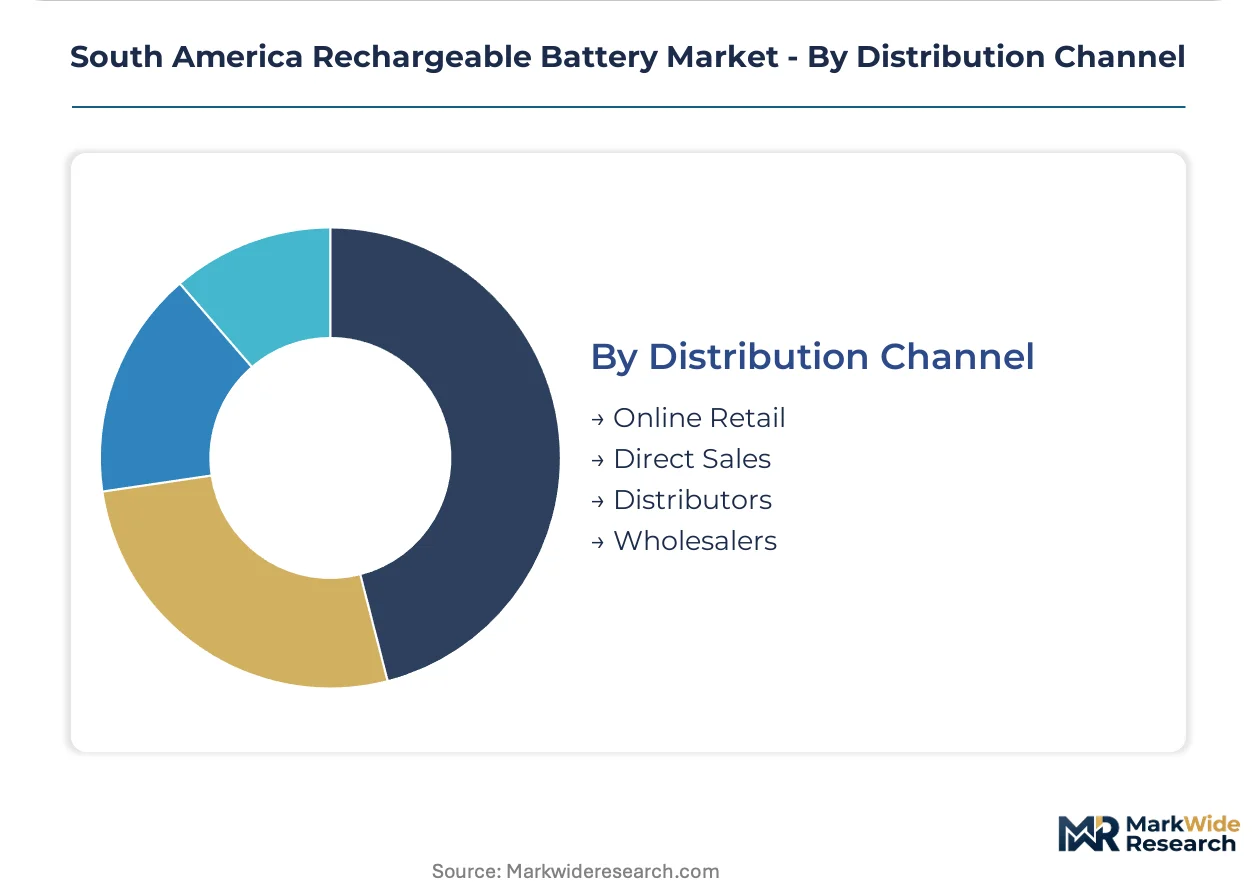
Distribution Channel:
Volume concentration in high-tender segments is displacing traditional intermediaries with direct producer-to-operator relationships.
- Direct Sales:Cell producers and integrated pack manufacturers negotiate multi-year offtake agreements with Chilean mining companies, Colombian transit authorities, and Brazilian fleet operators. This channel captures highest-margin, specification-intensive demand.
- Distributors:Regional industrial OEM partnerships, exemplified by Samsung SDI's Brazilian relationships, serve mid-volume manufacturing customers with certified product lines and local technical support.
- Online Retail:E-commerce platforms aggregate fragmented consumer electronics and replacement battery demand with limited service attachment and price-transparent competition.
- Wholesalers:Bulk procurement intermediaries serve price-sensitive industrial backup and telecom sectors across Argentina and peripheral Brazilian markets with lead-acid and entry lithium-ion products.
Direct sales holds the largest share; momentum sits with distributor partnerships consolidating technical service capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Inova Energia program anchors industrial policy incentives across the region, drawing component suppliers toward Minas Gerais and São Paulo. Chilean mining operators and Colombian transit authorities are establishing direct procurement relationships that bypass traditional distribution channels. Argentina's lithium triangle extraction zones attract early-stage project development despite permitting complexity.
Brazil
Minas Gerais and São Paulo states concentrate lithium-ion pack assembly for automotive and stationary applications. ANVISA safety standards and the national energy regulator's grid-interconnection mandates determine tender eligibility for renewable energy storage systems. São Paulo's manufacturing corridor faces concentrated compliance burdens as integrators front-load certification documentation.
Chile
Santiago's municipal transit authority anchors electric bus fleet procurement with reference specifications adopted regionally. The environmental evaluation service layers site-specific permitting requirements on large-scale industrial deployments. Mining companies in the lithium triangle are evaluating sodium-ion pilot deployments to reduce feedstock concentration risk.
Argentina
Mining and telecom backup sectors retain price-sensitive procurement habits that slow lithium-ion penetration in industrial stationary applications. The mining secretariat is streamlining site-specific approvals for extraction zone deployments. Argentine brine extraction concentration exposes assemblers to lithium carbonate input cost volatility on long-dated supply contracts.
Colombia
Transit authorities are adopting Santiago's electric bus procurement specifications for fleet-level demand. UN 38.3 certification bottlenecks extend qualification timelines for importers lacking in-house testing laboratories. Direct producer-to-operator negotiations are compressing traditional distributor margins in high-volume segments.
Peru
Utility-scale storage deployments reward direct engagement models with volume concentration. Mining operators are evaluating cobalt-free and nickel-free battery formulations to diversify supply chain exposure. Third-party testing capacity scarcity across the Andean region advantages producers with captive UN-certified laboratory capabilities.
South America Rechargeable Battery Market Competitive Landscape
Player mix skews toward integrated cell manufacturers and regional pack assemblers with captive certification capabilities. Market structure concentrates around producers with in-house UN 38.3 testing laboratories that bypass third-party bottlenecks. Three archetypes dominate: integrated Asian cell producers with direct fleet relationships, European industrial battery specialists with distributor partnerships, and regional lead-acid incumbents defending replacement cycles. Competitive moves center on backward integration into cell production and direct offtake agreements with mining and transit operators.
Within the integrated producer tier, BYD Company Ltd and Samsung SDI occupy distinct positions. BYD leverages in-house cell manufacturing to circumvent certification delays in Chile and Colombia. Samsung SDI anchors regional presence through distributor partnerships with Brazilian industrial OEMs. Exide Industries Ltd exemplifies the lead-acid incumbent archetype, competing on replacement cycles in Argentina's mining and telecom backup sectors where price sensitivity persists.
| Leading Market Players |
|---|
| BYD Company Ltd |
| Duracell Inc. |
| Panasonic Holdings Corporation |
| EnerSys |
| Exide Industries Ltd |
| Samsung SDI |
| FIAMM Energy Technology SpA |
| Saft Groupe SA |
| Clarios |
| Others |
Pricing and Supply Chain Analysis
Lithium iron phosphate cathode substitution for nickel-manganese-cobalt formulations is redrawing procurement economics across South America, compressing cell cost structures while relocating thermal management system value capture toward Brazilian pack integrators serving Santiago's electric bus tenders.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation anchor long-term supply agreements between Chilean brine extractors and Brazilian cell assemblers. Price differentiation separates UN 38.3 certified automotive packs from uncertified industrial backup units, with ANVISA documentation adding substantial compliance premiums. Cost compression in standard-grade lithium-ion runs through Argentine mining procurement, where lead-acid replacement cycles retain price-sensitive buying patterns. Fleet operators in Santiago and São Paulo exhibit lowest price sensitivity due to total-cost-of-ownership optimization, while telecom backup buyers in the Andean region drive hardest bargain on unit economics.
Supply Chain Analysis
Strait of Magellan maritime transit underwrites Chilean lithium carbonate export routes to Asian cell manufacturing hubs before finished cells return to Brazilian assembly corridors. Supply concentrates in China's cathode active material production, South Korea's electrolyte formulation, and Japan's separator membrane technology. Raw material dependencies span Chilean and Argentine brine lithium, Indonesian nickel, and DRC cobalt feedstocks. Single-source vulnerability in third-party UN 38.3 testing capacity across the Andean region extends qualification timelines. Distribution runs through direct producer-to-operator channels in high-volume mining and transit segments, with distributor partnerships serving mid-tier Brazilian industrial OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's rechargeable battery market sits in early-cycle expansion, with sodium-ion chemistry pilots and grid-interconnection standard evolution opening penetration pathways that did not exist three years ago.
For Market Incumbents: Shield margin position in certified automotive segments by accelerating backward integration into cell formation equipment. Capture ANVISA pre-approval documentation as a competitive moat against emerging pack assemblers. Defend against sodium-ion substitution threat by locking multi-year offtake guarantees with Chilean mining operators before pilot deployments scale.
For New Entrants and Emerging Players: Anchor in Argentina's mining backup sector where lead-acid replacement inertia creates white-space for lithium-ion value proposition. Target Peruvian utility-scale storage tenders where direct engagement models reward new chemistry evaluation. Pursue distributor partnerships with São Paulo industrial OEMs as the fastest path to volume credibility without captive certification infrastructure.
For Investors and Strategic Acquirers: MERCOSUR technical regulation harmonization reshapes the acquisition landscape by reducing duplicate testing costs across Brazil-Argentina corridors. Five-to-ten year viability favors integrated producers with in-house UN-certified laboratories and direct fleet relationships. Watch sodium-ion pilot deployment announcements from Chilean mining companies as the signal for chemistry substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Formation | Captive aging equipment supply eliminates third-party testing bottlenecks for Brazilian assemblers. |
| ANVISA Pre-Certification Investment | Early documentation submission locks tender eligibility before competitor compliance roadmaps mature. |
| Sodium-Ion Pilot Partnerships | Chilean mining offtake agreements reduce cobalt-nickel supply concentration risk for forward-thinking operators. |
| Direct Fleet Operator Engagement | Santiago bus procurement specifications adopted across Colombia compress distributor margin capture. |
| MERCOSUR Harmonization Compliance | Cross-border approval pathway convergence reduces duplicate certification spend for Brazil-Argentina trade. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with Brazilian pack assembly engineers, Chilean mining procurement directors, Argentine telecom infrastructure managers, and Colombian transit authority planners contributing operational perspective. Secondary validation drew from ANVISA regulatory filings, Brazilian national energy regulator tender documentation, Chilean environmental evaluation service permits, and customs trade records. Bottom-up cell shipment data triangulated against top-down fleet deployment tracking.
Across the analysis window, the analytical framework modeled chemistry type, application tier, end-user procurement sophistication, and distribution channel structure as core segmentation dimensions. CAGRs were derived from installed base replacement cycles, fleet electrification roadmaps, and utility storage pipeline tracking. Forecast inputs incorporated lithium carbonate price volatility assumptions and UN 38.3 certification capacity expansion timelines.
Material uncertainties — lithium brine extraction disruption, sodium-ion chemistry performance validation, MERCOSUR regulatory divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions on fleet adoption curves and grid-interconnection standard evolution. Practitioners should keep alternative scenarios live as ANVISA certification backlogs and Chilean mining permitting timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Middle-East Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
Micro Battery Market
Batteries
Industrial Backup Battery Market
Batteries
Watch Battery Market
Batteries
Myanmar Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Battery Anode Materials Market
Batteries
Custom Battery Pack Market
Batteries
Global Electric Scooter Batteries Market
Batteries
North America Industrial Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Battery Maintainer Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Military Battery Market