
 US Motive Lead Acid Battery Market | 2026-2036
US Motive Lead Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
US Motive Lead Acid Battery Market Insights
The gap between premium absorbed glass mat (AGM) systems and commodity flooded designs is expanding across US material handling fleets. Clarios leverages its vertically integrated recycling infrastructure to control lead feedstock costs in premium segments. EnerSys sustains technology leadership through advanced AGM formulations targeting high-cycle warehouse applications. East Penn Manufacturing anchors its position in flooded batteries serving cost-sensitive forklift operators in the Great Lakes region.
A motive lead acid battery is an electrochemical energy storage device using lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte to deliver deep-cycle power for mobile industrial equipment, typically rated between 6 and 48 volts with capacities from 100 to 2000 ampere-hours. Its primary purpose is to supply sustained traction power to electric forklifts, pallet jacks, and automated guided vehicles operating in enclosed warehouse environments where emissions restrictions prohibit internal combustion. Flooded batteries still dominate unit shipments in US warehouse operations due to lower upfront capital requirements, though AGM products capture margin pools in cold-storage and opportunity-charging applications where maintenance access proves difficult. Gel and spiral-wound variants occupy narrower niches in railway signaling and specialty electric vehicle builds where vibration resistance or orientation flexibility matters.
OSHA enforces worker exposure limits during battery watering and charging operations in US distribution facilities, while the EPA regulates spent lead-acid battery recycling through the Universal Waste Rule to prevent improper disposal. The Department of Transportation classifies these batteries as hazardous materials in interstate commerce, shaping packaging and shipping compliance costs for multi-state fleet operators. Stakeholders must monitor how lithium-ion competition and state-level clean energy procurement standards reshape replacement cycle economics in motive power fleets.
Market Dynamics
The US motive lead acid battery market faces structural compression from lithium-ion substitution in high-cycle warehouse fleets, forcing incumbent suppliers to defend position through recycling economics and regional service density rather than technology leadership alone.
Growth Catalysts
- OSHA Workplace Safety Mandates:Stricter enforcement of worker exposure limits during battery watering and charging operations compels fleet operators toward sealed AGM systems that reduce maintenance labor and compliance liability in multi-shift distribution centers.
- Midwest Distribution Center Automation:Warehouse operators across Illinois, Indiana, and Michigan are absorbing motive power units at accelerated rates as e-commerce fulfillment networks expand, driving replacement battery demand for electric forklift fleets.
- EPA Lead Recycling Standards:Tightened Universal Waste Rule compliance creates competitive advantage for suppliers with captive smelting infrastructure, as proper spent battery handling becomes a procurement criterion for sustainability-conscious logistics operators.
Market Restraints
- Lead Price Volatility:Primary lead feedstock costs fluctuate with LME pricing and secondary supply availability, squeezing margin pools for flooded battery producers lacking backward integration into recycling operations.
- Lithium-Ion Substitution Threat:Declining lithium-ion pack costs and opportunity-charging compatibility are capturing share in cold-storage and high-throughput applications where lead acid's cycle life limitations prove prohibitive.
- Great Lakes Supplier Concentration:Battery manufacturing clusters in Pennsylvania and Ohio create geographic supply risk for western US fleet operators, elevating freight costs and delivery lead times for replacement units.
Strategic Opportunities
- Southeast Logistics Corridor Expansion:Greenfield distribution center development across Georgia, Tennessee, and South Carolina offers first-mover advantage for battery suppliers establishing regional service depots and fast-turn replacement programs.
- California Clean Energy Procurement Standards:State-level mandates for zero-emission material handling equipment in ports and inland warehouses create regulatory tailwind for advanced lead acid and hybrid power systems qualifying under interim compliance pathways.
- Telematics-Battery Convergence:Integration of IoT-enabled state-of-charge monitoring with fleet management platforms enables predictive replacement scheduling and performance-based service contracts, shifting revenue from unit sales to recurring service models.
Industry Challenges
- Certified Technician Shortage:Proper handling of sulfuric acid electrolyte and lead components requires OSHA-compliant training that fewer vocational programs now provide, constraining fleet operator ability to maintain flooded battery systems in-house.
- Legacy Charger Infrastructure Stranding:Existing 24-volt and 36-volt charging stations in older warehouses lack compatibility with newer high-capacity battery formats, forcing capital-intensive facility upgrades that delay replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Motive Lead Acid Battery Market |
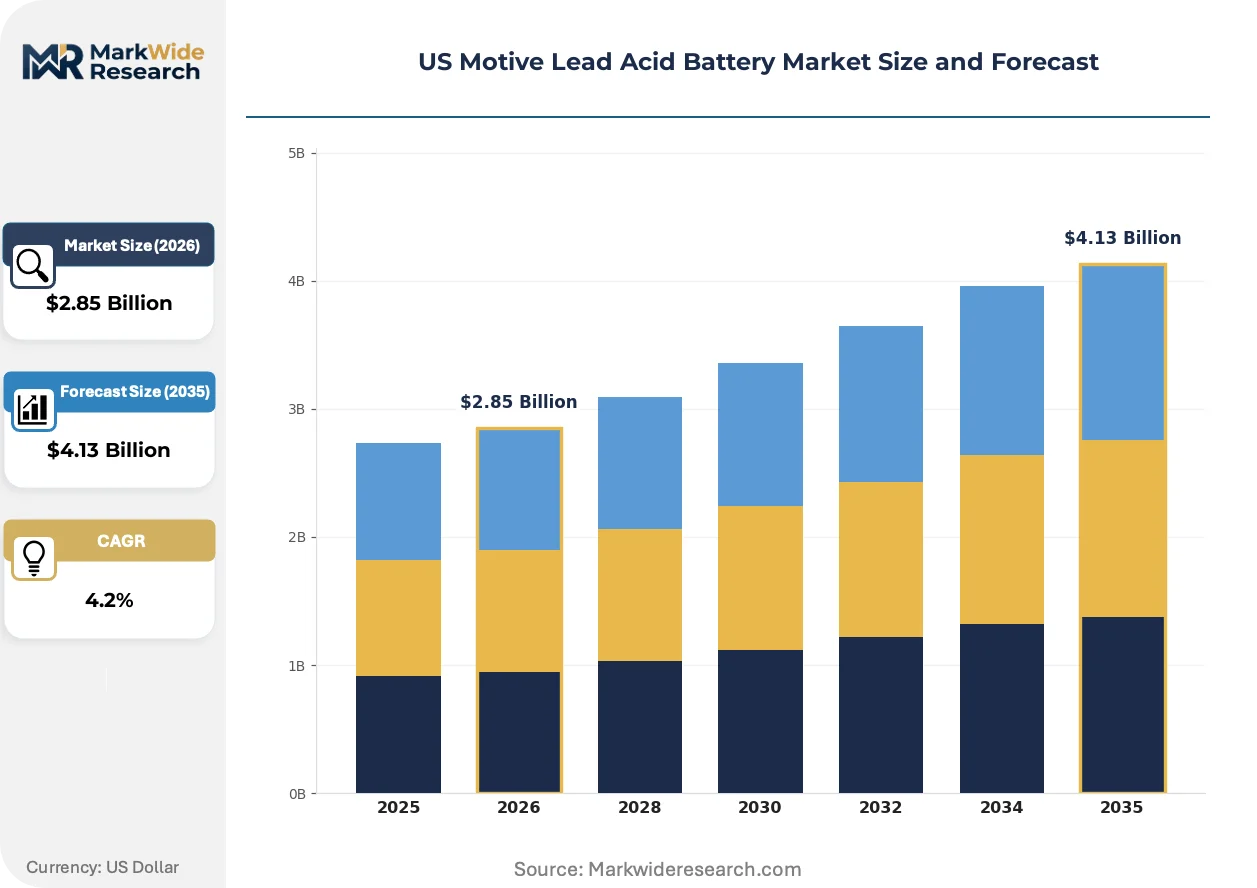
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded, AGM, Gel, Spiral-Wound End User: Golf Carts, Forklifts, Electric Vehicles, Railways Application: Transportation, Warehouse Operations, Renewable Energy, Backup Power Technology: Lead-Acid, Lithium-Ion, Hybrid Systems, Recycling Methods |
| Companies Covered | Clarios, EnerSys, East Penn Manufacturing, Crown Battery, C&D Technologies, Exide Industries, GS Yuasa International Ltd., U.S. Battery Manufacturing, MK Battery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Motive Lead Acid Battery Market Trends and Innovations
Technology trajectories in US motive power are bifurcating between premium sealed systems and cost-optimized flooded designs, with regulatory pressure and labor economics driving divergent investment patterns across warehouse operator segments.
Opportunity-charging AGM configurations are automating battery status monitoring through embedded sensors that communicate state-of-health data to fleet management systems. Third-party logistics operators with 24-hour throughput requirements are adopting these systems fastest to eliminate manual watering labor. This capability is automating maintenance scheduling and compressing total cost of ownership calculations that previously favored flooded alternatives.
EPA enforcement of the Universal Waste Rule is tightening documentation requirements for spent battery cradle-to-grave tracking. Interstate fleet operators now face elevated compliance costs for multi-state shipping manifests and recycler certification verification. Cold-storage warehouse operators in California and Texas are most affected, accelerating migration toward sealed designs that reduce hazardous material handling frequency.
Equipment leasing companies are unbundling battery service from forklift rental agreements, creating standalone power-as-a-service contracts with performance guarantees. This model displaces capital purchase decisions by regional warehouse operators and shifts technical risk to suppliers with diagnostic capabilities. The pattern is most visible in Ohio and Pennsylvania manufacturing clusters where fleet standardization pressures favor outsourced maintenance.
US Motive Lead Acid Battery Market Segmentation
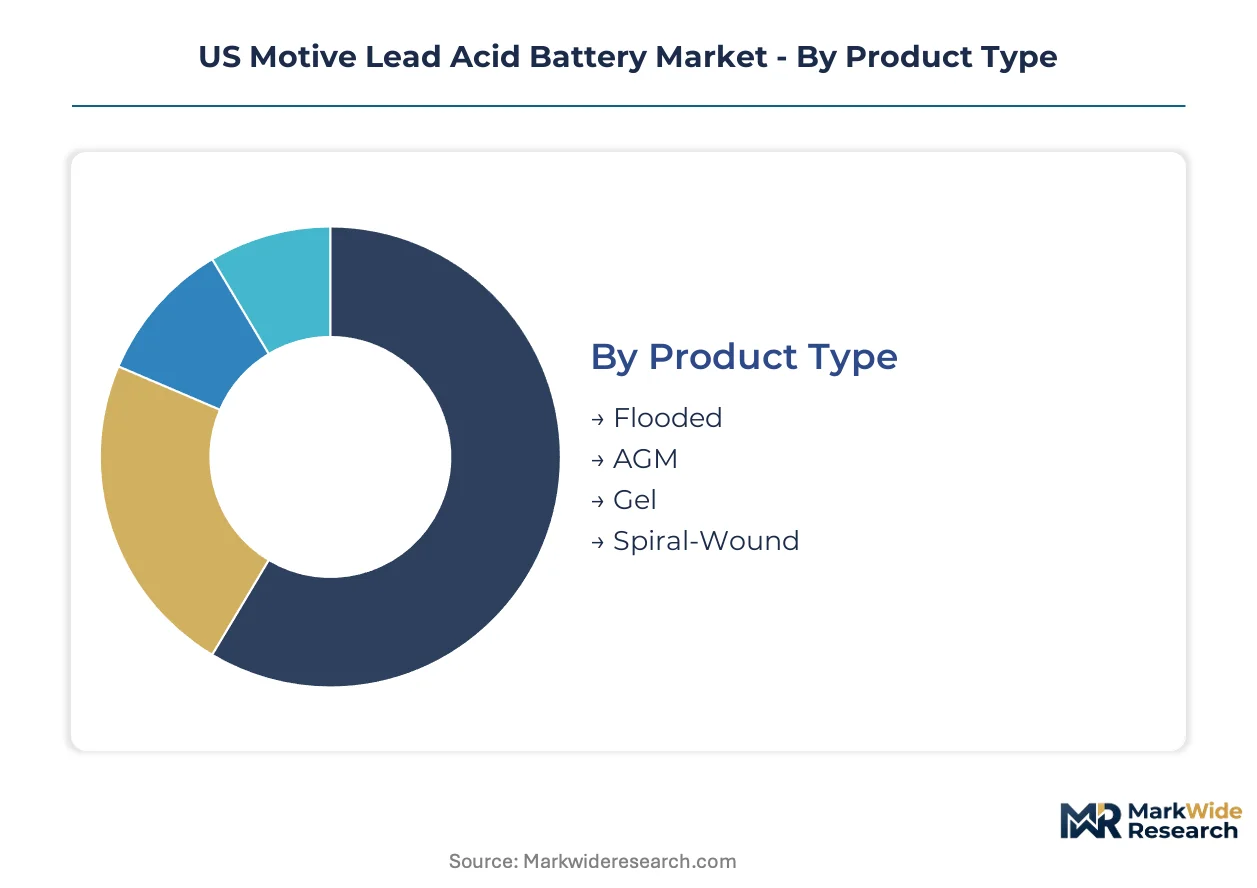
Segmentation in the US motive lead acid battery market tracks how fleet operators balance upfront capital constraints against lifecycle operating costs across diverse equipment types. Understanding these splits reveals where lithium-ion substitution pressure concentrates and where lead acid retains structural advantages through service infrastructure density.
Product Type:
Replacement cycles diverge sharply between maintenance-intensive flooded systems and sealed alternatives that reduce labor exposure to OSHA-mandated safety protocols.
- Flooded:These batteries use liquid sulfuric acid electrolyte requiring regular watering and ventilation infrastructure. Demand concentrates among cost-sensitive forklift operators in Ohio and Pennsylvania manufacturing clusters where in-house maintenance capabilities persist and capital budgets favor lowest first-cost procurement.
- AGM:Absorbed glass mat construction immobilizes electrolyte in fiberglass separators, enabling sealed operation and opportunity charging. Cold-storage warehouses across California and Texas absorb these units fastest as OSHA compliance costs and restricted maintenance access reshape total cost calculations.
- Gel:Silica-thickened electrolyte provides vibration resistance and deep discharge recovery for electric vehicle builds with irregular usage patterns.
- Spiral-Wound:Cylindrical plate geometry delivers high burst current for railway signaling applications where space constraints and orientation flexibility override energy density requirements.
Volume placements concentrate in Flooded; the faster expansion belongs to AGM.
End User:
Equipment utilization intensity determines whether lead acid's cycle life limitations become prohibitive relative to lithium-ion alternatives.
- Forklifts:Three-shift distribution centers in Illinois and Indiana drive replacement demand as e-commerce fulfillment networks expand. Multi-shift operations with opportunity charging compatibility favor AGM configurations that compress downtime versus flooded alternatives requiring cooldown periods.
- Electric Vehicles:Low-speed neighborhood electric vehicles and campus transport fleets in retirement communities and university settings favor lead acid for purchase price sensitivity and established recycler networks.
- Golf Carts:Private course operators and resort fleets in Florida and Arizona absorb flooded units for seasonal usage patterns with off-peak charging windows.
- Railways:Signaling and switchgear applications require gel and spiral-wound variants for vibration tolerance and extended float service life in remote trackside installations.
Shipments concentrate in Forklifts; Golf Carts face the steepest share erosion from lithium-ion encroachment.
Application:
Operating environment constraints—emissions restrictions, maintenance access, and duty cycle predictability—shape chemistry selection across use cases.
- Warehouse Operations:Enclosed distribution centers across the Midwest and Southeast absorb motive power units as automation expands. OSHA ventilation requirements and multi-shift labor economics tilt procurement toward sealed AGM systems in newer facilities.
- Transportation:Electric shuttle fleets and campus transport in California face state-level zero-emission mandates that create interim compliance pathways for advanced lead acid while full electrification timelines extend.
- Backup Power:Uninterruptible power supplies for critical warehouse management systems favor AGM for float service reliability and minimal maintenance during standby periods.
- Renewable Energy:Off-grid solar storage for remote material handling equipment uses flooded batteries where daily cycling depth remains moderate and cost minimization dominates.
Deployment concentrates in Warehouse Operations; Transportation is gaining share fastest under regulatory pressure.
Technology:
Power system architecture decisions increasingly incorporate lifecycle recycling economics as EPA enforcement tightens cradle-to-grave documentation requirements.
- Lead-Acid:Mature electrochemistry with established recycling infrastructure capturing over 99% of lead content. Suppliers with captive smelting operations in the Great Lakes region leverage this closed-loop economics against lithium-ion cost erosion.
- Recycling Methods:Pyrometallurgical and hydrometallurgical recovery processes determine secondary lead feedstock quality and compliance certification value for sustainability-conscious logistics operators.
- Hybrid Systems:Lead acid-lithium combinations target cold-storage applications where lead acid handles base loads and lithium manages peak shaving.
- Lithium-Ion:Competing chemistry capturing high-cycle warehouse fleets where opportunity charging and weight reduction justify premium pricing.
Installed base concentrates in Lead-Acid; Hybrid Systems are climbing the fastest as operators seek transitional risk mitigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors the densest concentration of motive lead acid battery demand through its sprawling distribution corridor linking the Great Lakes manufacturing belt to national logistics networks.
Texas
The Dallas-Fort Worth metroplex absorbs motive power units at accelerated rates as third-party logistics operators expand fulfillment footprints. EPA Universal Waste Rule enforcement elevates recycler certification requirements for interstate fleet operators based in the state. Houston's petrochemical corridor hosts battery service depots supporting port material handling equipment under tightening emissions protocols.
California
Cold-storage warehouses across the Central Valley drive sealed AGM adoption as OSHA ventilation mandates reshape total cost calculations for enclosed facilities. State-level zero-emission procurement standards for ports and inland distribution centers create compliance pathways for advanced lead acid systems. The Inland Empire logistics cluster concentrates replacement battery demand from e-commerce fulfillment networks operating 24-hour throughput cycles.
Ohio
Manufacturing clusters around Cleveland and Cincinnati sustain flooded battery demand among cost-sensitive forklift operators with in-house maintenance capabilities. Department of Transportation hazardous materials classifications elevate shipping compliance costs for multi-state fleet operators headquartered in the state. The Columbus distribution corridor anchors regional service infrastructure for battery suppliers defending share against lithium-ion substitution.
Illinois
Three-shift distribution centers in the Chicago metro area compress replacement cycles as e-commerce fulfillment intensity rises. OSHA workplace safety mandates compel fleet operators toward sealed systems that reduce technician exposure during watering operations. Rockford's manufacturing belt supports captive recycling infrastructure that controls secondary lead feedstock costs for regional suppliers.
Pennsylvania
The Lehigh Valley logistics corridor concentrates battery manufacturing capacity that supplies northeastern warehouse operations. Great Lakes supplier concentration creates geographic supply risk for western fleet operators, elevating freight costs for replacement units shipped cross-country. Pittsburgh's industrial heritage sustains vocational training programs that replenish the certified technician pool required for flooded battery maintenance.
US Motive Lead Acid Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across recycling infrastructure depth and regional service density rather than technology differentiation alone. The vendor base organizes into three tiers: vertically integrated majors with captive smelting operations, mid-scale regional fabricators with dense service networks, and specialty producers targeting narrow application niches. Competitive positioning hardens around EPA compliance certification value and fast-turn replacement program reach. Consolidation pressure concentrates among mid-tier operators lacking backward integration into secondary lead supply.
Within the integrated-major tier, Clarios and EnerSys exemplify archetypes that leverage closed-loop recycling economics against lithium-ion cost erosion. East Penn Manufacturing anchors the regional-fabricator segment with manufacturing concentration in the Great Lakes corridor. These three structures represent how competitive positioning fragments across recycling depth, geographic service density, and product format specialization rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Clarios |
| EnerSys |
| East Penn Manufacturing |
| Crown Battery |
| C&D Technologies |
| Exide Industries |
| GS Yuasa International Ltd. |
| U.S. Battery Manufacturing |
| MK Battery |
| Others |
Pricing and Supply Chain Analysis
OSHA's tightening workplace safety mandates for battery watering operations are compelling fleet operators toward sealed AGM systems that reduce technician exposure, forcing suppliers to recalibrate production mixes and absorb higher manufacturing costs for fiberglass separator materials versus commodity flooded designs.
Pricing Analysis
Uptime guarantees and cycle-life performance anchor value-based pricing for premium AGM configurations serving multi-shift distribution centers. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified recycling-backed units from commodity flooded alternatives and entry-level gel formulations. Cost compression in flooded segments is intensifying because Great Lakes manufacturing clusters face freight cost penalties serving western logistics hubs. Price-sensitive buyers concentrate among Ohio and Pennsylvania manufacturing operators with in-house maintenance capabilities, while California cold-storage warehouses show lowest sensitivity due to OSHA compliance cost differentials.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national forklift fleet operators, while regional service depots manage replacement cycles for independent warehouse operators. Domestic manufacturing concentrates in Pennsylvania, Ohio, and Wisconsin, with secondary lead feedstock drawn from captive smelting operations in the Great Lakes corridor. Raw material dependencies center on LME-traded primary lead, sulfuric acid from Gulf Coast chemical producers, and fiberglass mat from specialized textile suppliers. Single-source vulnerability in secondary lead supply creates exposure when EPA enforcement disrupts recycler certification timelines. Distribution runs through battery service depots positioned within four-hour drive time of major logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over secondary lead feedstock and captive smelting infrastructure determines margin survival against lithium-ion substitution.
For Market Incumbents: Cement recycling infrastructure advantages by expanding captive smelting capacity near Great Lakes manufacturing clusters, insulating against LME lead price volatility that squeezes non-integrated competitors. Deepen diagnostic service capabilities through telematics integration to lock in recurring revenue streams as equipment leasing companies unbundle power-as-a-service contracts. Lithium-ion encroachment in high-cycle cold-storage applications demands defensive positioning through hybrid system development. For New Entrants and Emerging Players: Southeast logistics corridor warehouse operators represent an underserved buyer archetype lacking dense regional service infrastructure as Georgia, Tennessee, and South Carolina distribution centers multiply. Fast-turn replacement programs with guaranteed four-hour response windows offer penetration leverage against established Great Lakes suppliers burdened by cross-country freight costs. Target opportunity-charging AGM configurations for third-party logistics operators with 24-hour throughput requirements. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional fabricators possessing dense service networks but lacking backward integration into secondary lead supply, given EPA enforcement tightening cradle-to-grave documentation requirements. Acquisition targets should demonstrate recycler certification value and fast-turn replacement program reach across at least three state logistics corridors. Watch for inflection when lithium-ion pack costs cross threshold levels in high-cycle forklift applications.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Smelting Capacity Expansion | Secondary lead feedstock control insulates margin pools against LME price volatility. |
| Telematics-Enabled Service Contracts | IoT state-of-health monitoring shifts revenue from unit sales to recurring diagnostics. |
| Southeast Regional Depot Buildout | Georgia and Tennessee logistics corridors lack dense battery service infrastructure. |
| Hybrid Lead Acid-Lithium Systems | Peak-shaving configurations defend position in California cold-storage applications. |
| EPA Compliance Certification Investment | Universal Waste Rule documentation creates procurement preference among sustainability-conscious operators. |
Research Methodology
Multi-period observation of forklift fleet replacement cycles, battery chemistry adoption patterns, and recycler certification timelines anchored the trend analysis, supplemented by interviews with maintenance directors at third-party logistics operators, OEM procurement teams at forklift manufacturers, battery service depot managers, and EPA compliance officers. Secondary validation drew from OSHA enforcement records, EPA Universal Waste Rule filings, LME lead price databases, and SEC disclosures from publicly traded battery manufacturers. Bottom-up triangulation across regional service depot capacity and top-down validation against national forklift shipment data ensured consistency.
Input-output matrices modeled unit placements across product type, end-use equipment, application environment, and technology format dimensions over the projection horizon. CAGRs were derived from regression analysis against macroeconomic indicators and industry-specific drivers including e-commerce fulfillment intensity and warehouse automation penetration. Forecast inputs incorporated OSHA enforcement trajectory assumptions and lithium-ion cost curve projections.
Revisions become necessary when lithium-ion pack cost declines accelerate beyond modeled trajectories or EPA enforcement disrupts secondary lead supply chains. Forecasts reflect assumptions about regulatory stability and substitution elasticity that warrant monitoring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Maintainer Market
Batteries
India Micro Batteries Market
Batteries
Italy SLI Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Battery Separators Market
Batteries
Nas Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Global Marine Battery Market
Batteries
Global Zinc Air Batteries Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
South Asia Battery Market
Batteries
Forklift Battery Charger Market