
 Middle-East and Africa Consumer Battery Market | 2026-2036
Middle-East and Africa Consumer Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Consumer Battery Market Foresight
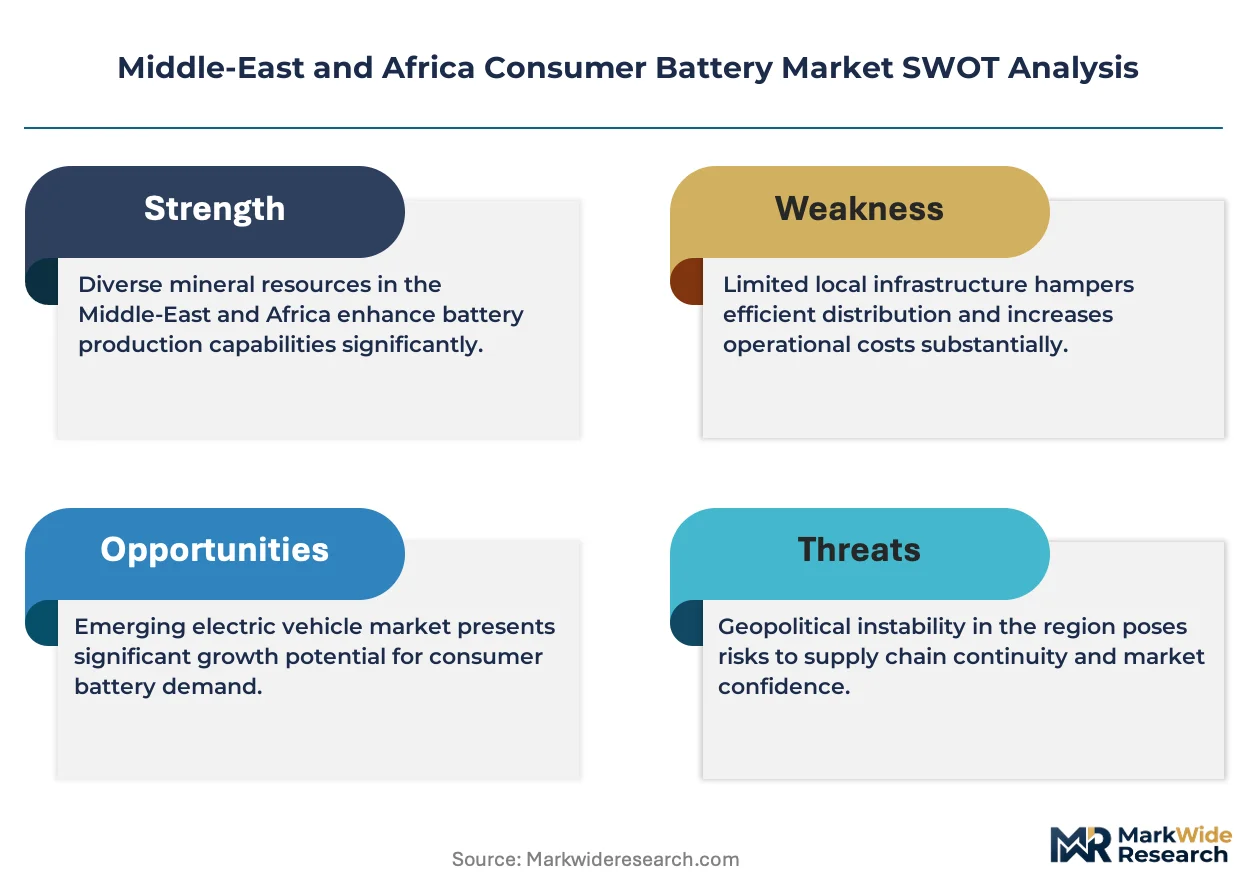
Project finance and pay-as-you-go leasing for solar-home systems is fragmenting the traditional distributor-led battery channel across East and West Africa. Energizer Holdings leverages its brand strength to anchor premium alkaline shelf space in South African retail chains. Duracell competes through aggressive channel control in Nigerian open-air markets and formal electronics stores. Anker Innovations positions its lithium-ion power bank portfolio to capture smartphone-dependent users lacking grid reliability.
Middle-East and Africa consumer batteries encompass primary and rechargeable electrochemical cells designed for household and personal use, typically operating at 1.5V to 3.7V nominal voltage with alkaline manganese dioxide, lithium cobalt oxide, or nickel metal hydride chemistries, manufactured through jellyroll winding or stacked electrode assembly to deliver portable power for devices without grid connection. Alkaline cells dominate unit volume across price-sensitive mass markets while lithium-ion chemistry captures value concentration in smartphone and laptop applications where energy density requirements are paramount. The cylindrical form factor leads in flashlight and power tool replacement cycles, whereas button cells sustain margin pools in medical device and hearing aid channels across aging populations in Israel and South Africa.
South Africa's National Regulator for Compulsory Specifications enforces SANS battery safety standards that restrict non-compliant imports, while the UAE's Emirates Authority for Standardization and Metrology mandates ECAS certification for consumer electronics batteries entering Dubai and Abu Dhabi duty-free zones. Saudi Arabia's Saudi Standards, Metrology and Quality Organization has tightened lithium-ion transport and storage rules ahead of Vision 2030 electronics manufacturing localization targets. Stakeholders must monitor how Gulf states harmonize battery circularity requirements with EU Battery Regulation technical precedents to avoid stranded inventory in regional free trade zones.
Market Dynamics
Pay-as-you-go solar leasing is fragmenting traditional distributor-led battery channels across East and West Africa, forcing manufacturers to build direct-to-installer relationships that bypass legacy wholesale networks.
Growth Catalysts
- Portable electronics proliferation:Smartphone penetration in Nigeria and Kenya is accelerating alkaline and lithium-ion cell consumption among first-time device owners.
- IEC battery safety standards:South Africa's SANS enforcement is raising import barriers that favor certified suppliers with testing infrastructure.
- Vision 2030 localization:Saudi Arabia's electronics manufacturing targets are stimulating lithium-ion transport and storage rule harmonization ahead of domestic assembly investments.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress margins for rechargeable cell producers serving price-sensitive Gulf markets.
- Import concentration risk:Duty-free zone dependence in Dubai and Abu Dhabi creates single-point exposure to ECAS certification delays.
- Alkaline shelf-life limitations:High-temperature storage conditions across the Gulf Cooperation Council corridor accelerate capacity fade in manganese dioxide cells.
Strategic Opportunities
- Medical device channels:Aging populations in Israel and South Africa are expanding hearing aid and glucose monitor battery replacement cycles.
- EU Battery Regulation harmonization:Gulf states adopting circularity precedents from Brussels create first-mover advantage for compliance-ready suppliers.
- Power tool lithium-ion conversion:Kenyan construction and South African mining sectors are transitioning from nickel-cadmium to higher-density cylindrical packs.
Industry Challenges
- Electrochemical engineering talent scarcity:Battery pack design and thermal management expertise remains concentrated in East Asian and European labor pools.
- Dual certification timelines:ECAS and SASO lithium-ion approvals require sequential testing that extends product launch windows by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Consumer Battery Market |
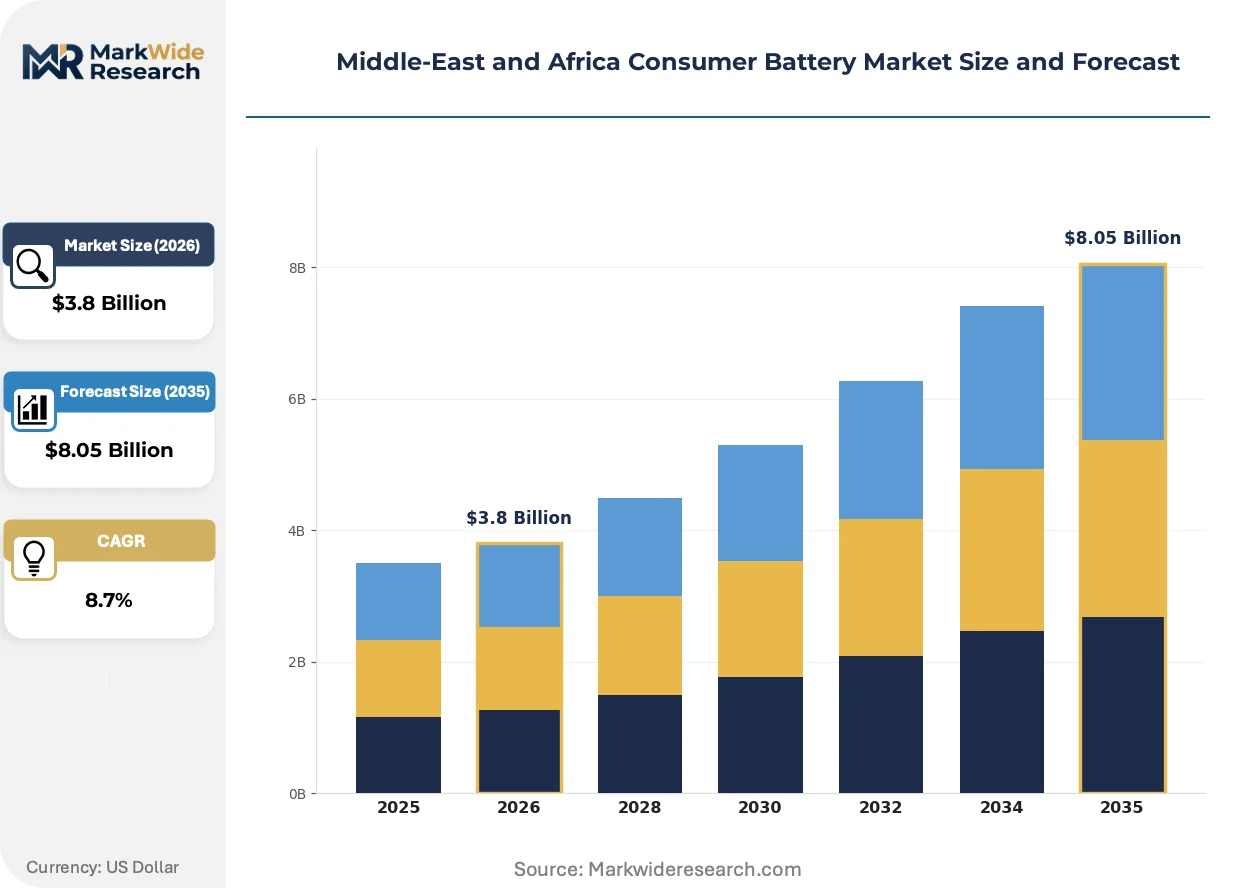
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Alkaline, Lithium-Ion, Nickel Metal Hydride, Lead Acid End User: Consumer Electronics, Automotive, Industrial, Portable Devices Form Factor: Cylindrical, Prismatic, Button Cell, Packaged Application: Smartphones, Laptops, Electric Vehicles, Power Tools |
| Companies Covered | Panasonic Corporation, Koninklijke Philips N.V., VARTA Consumer Batteries GmbH & Co KGaA, Energizer Holdings, Inc., Duracell Inc., Anker Innovations Technology Co Ltd, GP Batteries International Limited, Electrocomponents PLC, Camelion Battery Co Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Consumer Battery Market Shifts & Advancements
Electrochemistry, regulatory architecture, and procurement models are converging to reshape how cells reach end-users across Middle-East and Africa markets.
Lithium cobalt oxide chemistry is migrating from premium smartphone power banks toward mid-tier feature phones and solar-home system controllers in Nigerian and Kenyan off-grid households. Distributors report faster inventory turns on 3.7V cylindrical formats than on legacy sealed lead-acid replacements. This chemistry shift is compressing alkaline manganese dioxide value capture in segments above 500mAh capacity requirements.
The Emirates Authority for Standardization and Metrology tightened ECAS certification protocols for consumer electronics batteries entering Dubai duty-free zones. Importers now face mandatory UN 38.3 transport testing documentation before customs clearance. East African distributors are responding by pre-positioning certified inventory in Jebel Ali bonded warehouses to avoid demurrage during approval delays.
East African solar-home system operators are unbundling battery replacement from hardware sales, offering cell-swap subscriptions that shift ownership risk to lessors. This model displaces upfront retail purchases in Kenyan and Tanzanian peri-urban zones. Nigerian open-air market vendors report declining alkaline bulk sales as pay-as-you-go providers capture household power budgets through mobile money-linked leasing.
Middle-East and Africa Consumer Battery Market Segmentation
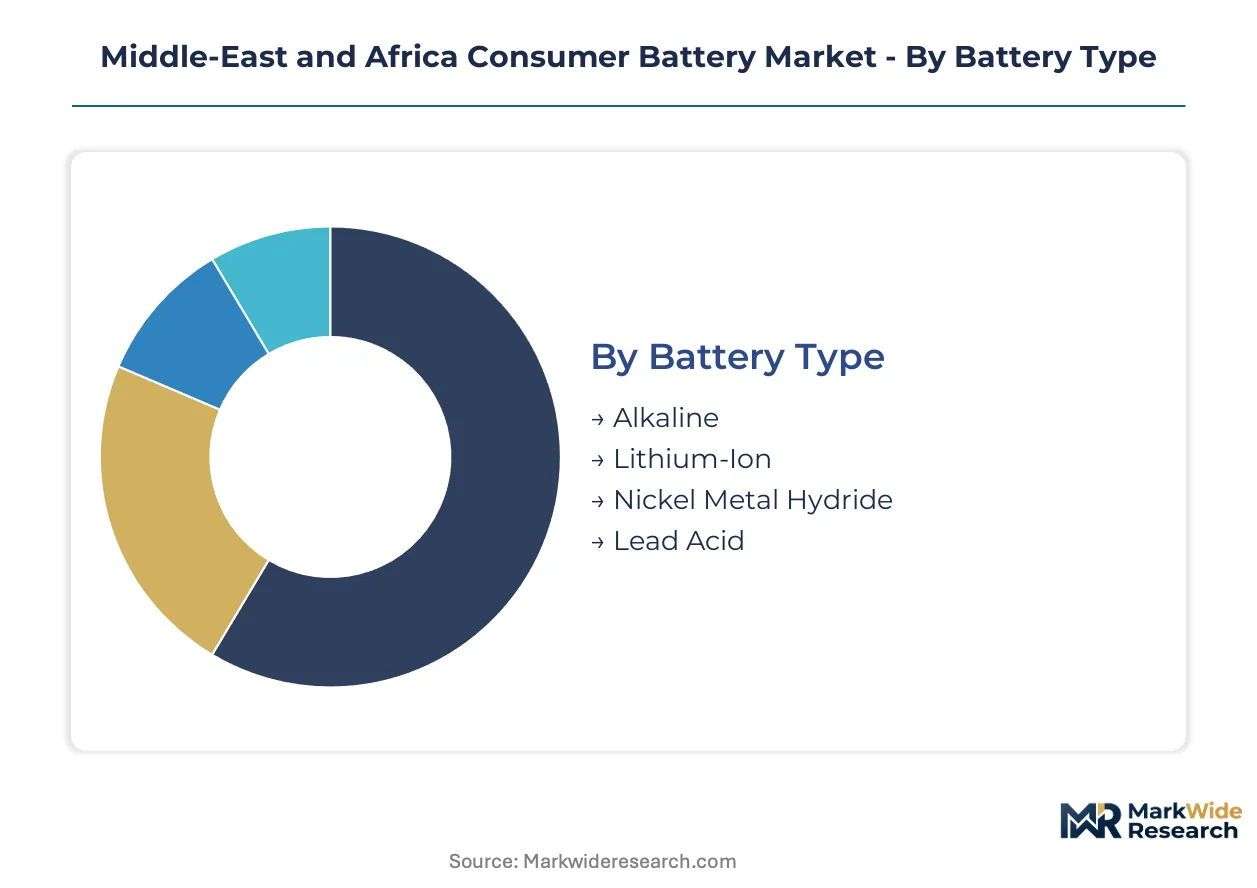
Battery segmentation across the Middle-East and Africa reveals distinct procurement patterns between mature alkaline channels and emerging lithium-ion applications. Understanding these divides enables suppliers to align certification investments and distribution partnerships with actual consumption clusters.
Battery Type:
Mature alkaline chemistry dominates mass-market throughput while emerging lithium-ion formats capture value concentration in premium electronics segments.
- Alkaline:Manganese dioxide cells with zinc anodes deliver 1.5V nominal output for price-sensitive flashlight and remote control replacement cycles. Nigerian open-air markets and South African retail chains move the highest unit volumes, though Gulf Cooperation Council storage conditions accelerate shelf-life degradation.
- Lithium-Ion:Cobalt oxide cathodes enable 3.7V energy density for smartphone power banks and solar-home system controllers. Kenyan and Tanzanian pay-as-you-go leasing operators are displacing sealed lead-acid with cylindrical lithium formats in peri-urban installations.
- Nickel Metal Hydride:Rechargeable chemistry retains niche presence in cordless phone and emergency lighting backup applications across Israeli healthcare facilities.
- Lead Acid:Sealed variants persist in budget solar-home systems and automotive starter applications, though lithium substitution is climbing fastest in East African markets.
Alkaline handles the majority of throughput; lithium-ion is the fastest mover on share.
End User:
Customer type segmentation tracks the divergence between household replacement purchasing and institutional procurement with technical compliance requirements.
- Consumer Electronics:Household replacement demand for remote controls, wireless peripherals, and personal audio devices. South Africa's SANS enforcement raises import barriers that favor certified suppliers with testing infrastructure.
- Portable Devices:Smartphone-dependent users lacking grid reliability drive power bank and feature phone battery consumption in Nigerian and Kenyan urban corridors.
- Automotive:Aftermarket starter and auxiliary power applications, concentrated in South African vehicle service networks and Gulf vehicle import hubs.
- Industrial:Mining equipment and construction power tool packs, where Kenyan building activity and South African extraction operations are converting from nickel-cadmium to lithium-ion cylindrical formats.
Consumer electronics commands the widest distribution footprint; portable devices shows the steepest expansion trajectory among end-user categories.
Form Factor:
Physical configuration dictates packaging economics and replacement frequency across divergent use cases.
- Cylindrical:Standardized 18650 and 21700 formats dominate flashlight, power tool, and solar controller applications. East African solar leasing operators report faster inventory turns on cylindrical lithium than on legacy lead-acid replacements.
- Button Cell:Compact zinc-air and silver oxide formats serve hearing aid and glucose monitor channels across aging populations in Israel and South Africa.
- Prismatic:Pouch and flat cell geometries enable slim-profile smartphone and laptop battery designs, concentrated in UAE electronics retail.
- Packaged:Pre-assembled battery packs with integrated management systems for solar-home systems and medical devices, requiring ECAS certification for Dubai duty-free zone entry.
Cylindrical formats sustain the highest replacement velocity; button cells defend the strongest margin pools per unit volume.
Application:
Use-case segmentation reveals where energy density requirements override price sensitivity in procurement decisions.
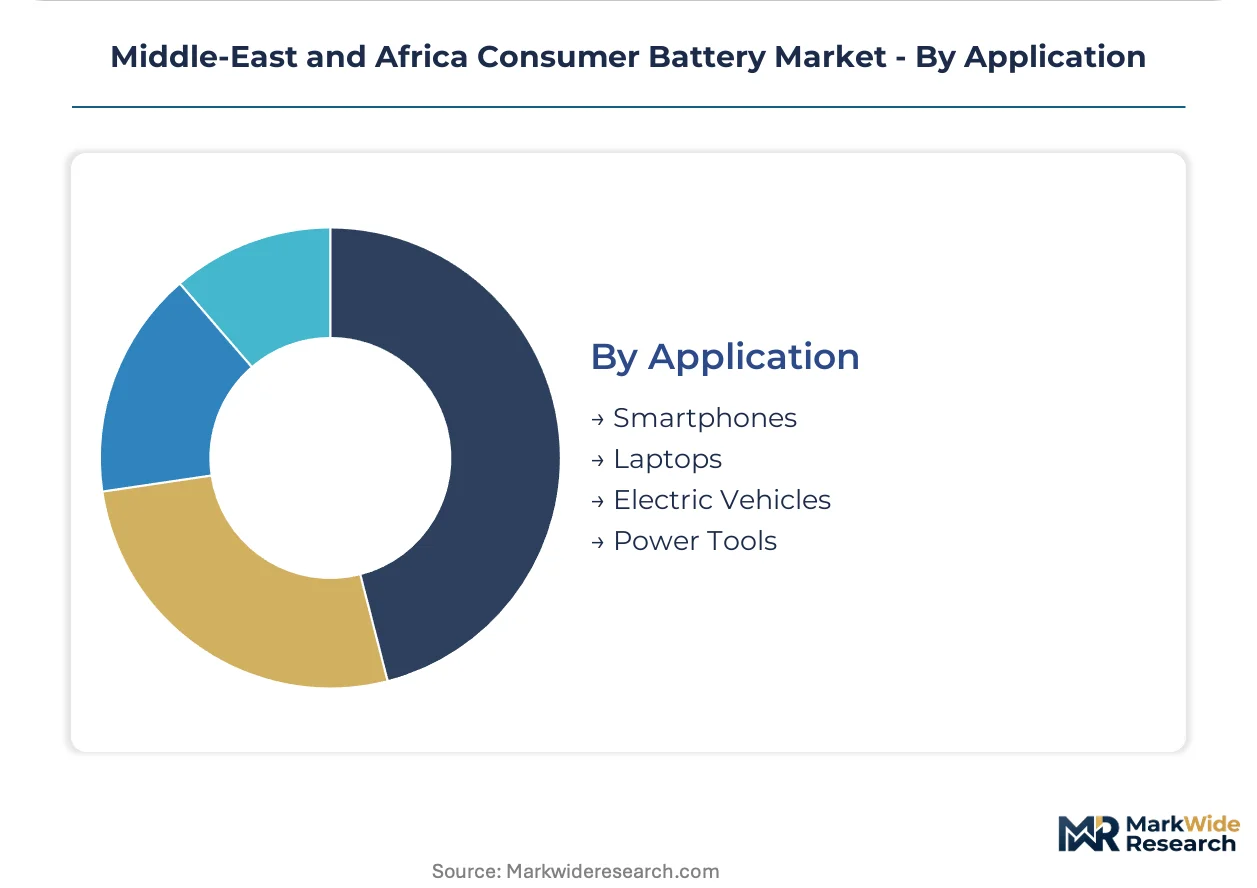
- Smartphones:High-cycle lithium-ion packs with cobalt cathodes for premium and mid-tier devices. Nigerian and Kenyan first-time device owners are accelerating cell consumption through power bank intermediation.
- Power Tools:High-discharge cylindrical packs for cordless construction and mining equipment. South African mining procurement is transitioning fleet specifications from nickel-cadmium to lithium-ion.
- Laptops:Prismatic lithium-polymer cells for portable computing, concentrated in UAE and Saudi Arabia business equipment channels.
- Electric Vehicles:Emerging traction battery demand in Gulf Cooperation Council pilot fleets and South African urban mobility trials, constrained by lithium carbonate price volatility.
Smartphones anchors current volume concentration; power tools is gaining share fastest as industrial lithium conversion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium lithium-ion cells command Gulf pricing premiums while East African alkaline markets operate on compressed distributor margins. The UAE and Saudi Arabia concentrate value capture through certification-gated import channels. Nigeria and Kenya drive volume throughput via informal retail networks and pay-as-you-go solar leasing.
United Arab Emirates
Dubai's electronics retail corridors anchor premium power bank and smartphone battery distribution across the Gulf Cooperation Council. The Emirates Authority for Standardization and Metrology enforces ECAS certification protocols with mandatory UN 38.3 transport documentation. Jebel Ali bonded warehouses pre-position certified inventory to circumvent customs clearance delays.
Saudi Arabia
Vision 2030 localization targets stimulate lithium-ion transport and storage rule harmonization ahead of domestic electronics assembly investments. The Saudi Standards, Metrology and Quality Organization tightened cylindrical cell warehousing requirements for industrial procurement. Riyadh and Dammam logistics clusters consolidate inbound battery shipments for redistribution across the Peninsula.
South Africa
SANS enforcement through the National Regulator for Compulsory Specifications restricts non-compliant imports and favors certified suppliers with testing infrastructure. Johannesburg retail chains and Cape Town automotive service networks concentrate alkaline and lead-acid replacement demand. Mining procurement in the Platinum Belt converts nickel-cadmium power tool specifications to lithium-ion cylindrical formats.
Nigeria
Lagos open-air markets and formal electronics stores move the highest alkaline unit volumes across West Africa. Portable electronics proliferation among first-time smartphone owners accelerates power bank intermediation. Kano and Port Harcourt distribution hubs fragment as pay-as-you-go solar operators bypass legacy wholesale networks through direct-to-installer relationships.
Kenya
Nairobi peri-urban zones and Mombasa port corridors anchor East African solar-home system battery deployment. Mobile money-linked leasing displaces upfront retail purchases through cell-swap subscription models. Tanzanian border markets extend Kenyan distributor reach into secondary East African Community territories.
Middle-East and Africa Consumer Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell chemistry and form factor supply. The market structures around three tiers: multinational brand houses with retail shelf-space dominance, regional distributors with bonded warehouse positioning, and emerging solar-leasing operators with captive battery demand. Strategic archetypes include certification-heavy import specialists, pay-as-you-go hardware lessors, and alkaline volume players in informal retail channels. Competitive moves concentrate on ECAS pre-certification warehousing and direct-to-installer channel bypass.
Among the multinational brand houses, Energizer Holdings, Duracell Inc., and Anker Innovations Technology Co Ltd occupy distinct positioning vectors. Energizer exemplifies the premium alkaline archetype with formal retail chain penetration. Duracell represents aggressive channel control in open-air market environments. Anker Innovations sits within the lithium-ion power bank specialization tier, capturing smartphone-dependent users in grid-unreliable segments. Panasonic Corporation and VARTA Consumer Batteries GmbH & Co KGaA anchor the component specialist tier upstream.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Koninklijke Philips N.V. |
| VARTA Consumer Batteries GmbH & Co KGaA |
| Energizer Holdings, Inc. |
| Duracell Inc. |
| Anker Innovations Technology Co Ltd |
| GP Batteries International Limited |
| Electrocomponents PLC |
| Camelion Battery Co Ltd |
| Others |
Supply & Pricing Matrix
Jebel Ali bonded warehouse corridors anchor freight cost dynamics that compress distributor margins in Dubai while amplifying price differentiation between certified and uncertified battery tiers downstream. This logistics chokepoint concentrates supply-side power among importers with pre-positioned ECAS-certified inventory, forcing price stratification across Gulf Cooperation Council retail channels.
Pricing Analysis
The customization-premium spread separates configured-to-order lithium-ion packs for solar-home system operators from standard alkaline blister packs in Nigerian open-air markets. Pricing stratifies across premium, standard, and economy tiers driven by IEC certification grade and volume procurement scale. Pricing pressure stems from lithium carbonate volatility compressing margins for rechargeable cell producers serving price-sensitive East African leasing operators. Informal retail channels in Lagos and Kano exhibit the highest price sensitivity, while UAE electronics retailers absorb premium markups for UN 38.3-certified power banks.
Supply Chain Analysis
Supplier-financing facilities extended by Chinese cylindrical cell manufacturers enable East African solar leasing operators to defer payment until mobile money collections materialize. Manufacturing concentration rests on China, South Korea, and Japan for lithium-ion cell production, with South Africa and Nigeria serving as regional packaging and distribution hubs. Raw material dependencies center on lithium carbonate, cobalt sulfate, and manganese dioxide feedstocks. Single-source vulnerability runs through Shanghai-to-Jebel Ali maritime lanes. Distribution runs through Dubai duty-free zones for Gulf markets and Mombasa port corridors for East African Community penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pay-as-you-go solar leasing fragments traditional battery distribution across Middle-East and Africa markets, creating niche entry points for specialized suppliers and certification-ready incumbents.
For Market Incumbents: Pre-empt channel bypass by solar leasing operators through direct-to-installer partnership programs in Kenyan and Tanzanian peri-urban zones. Lock in Jebel Ali bonded warehouse capacity ahead of ECAS certification queue congestion. Deepen backward integration into cylindrical cell sourcing to offset lithium carbonate margin compression from spot market volatility. For New Entrants and Emerging Players: Medical device battery replacement cycles in Israeli and South African hearing aid channels represent the most penetrable entry point for button cell specialists lacking alkaline volume scale. Nigerian pay-as-you-go solar operators' unmet demand for 18650 cylindrical packs offers a second white-space target. Pursue white-label supply agreements with East African leasing platforms rather than competing for retail shelf space. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underperforming battery divisions lacking Gulf certification infrastructure. Long-term viability hinges on regulatory compliance capabilities rather than manufacturing scale alone. Watch for SASO lithium-ion warehousing rule harmonization as the signal indicating which portfolio companies can capture Saudi Vision 2030 localization contracts.| Strategic Initiative | Industry Significance |
|---|---|
| ECAS Pre-Certification Warehousing | Jebel Ali bonded positioning circumvents Dubai customs delays for consumer electronics battery importers. |
| Direct-to-Installer Channel Partnership | Pay-as-you-go solar operators in Kenya bypass legacy Nigerian wholesale networks through captive procurement. |
| Lithium-Ion Cylindrical Conversion | South African mining procurement shifts nickel-cadmium power tool specifications to higher-density packs. |
| Medical Device Battery Specialization | Aging populations in Israel and South Africa expand hearing aid and glucose monitor replacement revenue pools. |
| EU Battery Regulation Harmonization | Gulf states adopting Brussels circularity precedents create first-mover advantage for compliance-ready suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from solar-home system operators, ECAS certification consultants, and East African distribution channel managers and refined through secondary validation. Primary fieldwork encompassed Nigerian open-air market vendors, South African retail chain procurement leads, and UAE bonded warehouse operators. Secondary sources included Emirates Authority for Standardization and Metrology regulatory filings, SANS battery safety standard documentation, and UN 38.3 transport testing records. Bottom-up cell consumption estimates were triangulated against top-down market value reconstructions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed battery chemistry tier, end-user procurement archetype, form factor configuration, and Gulf versus East African regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical certification timeline data and solar leasing deployment trajectories. Forecast inputs incorporated lithium carbonate price volatility scenarios and pay-as-you-go subscriber penetration curves.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability, maritime freight rates, or Gulf hydrocarbon revenue allocation would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline standardization and solar leasing platform consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
China Battery Market
Batteries
Advanced Batteries Market
Batteries
West Europe Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
South Europe Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
PVT Battery Panel Market
Batteries
South Asia Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Leisure Battery Market