
 India Lead-Acid Battery Market | 2026-2036
India Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
India Lead-Acid Battery Market Outlook
Domestic lead-acid cell production is decoupling from imported raw lead dependence as smelter investments in Rajasthan and Odisha mature. Exide Industries Ltd anchors the automotive aftermarket through its dense dealer network spanning tier-2 and tier-3 cities. Amara Raja Batteries Ltd differentiates via its technology leadership in VRLA designs for telecom tower applications. HBL Power Systems Ltd specializes in industrial-grade flooded batteries for Indian Railways and defense procurement channels.
A lead-acid battery electrochemically stores energy through reversible reactions between lead dioxide cathodes, sponge lead anodes, and sulfuric acid electrolyte with nominal cell voltage of 2.0 volts, serving as a cost-effective rechargeable power source for engine starting, deep-cycle motive power, and stationary backup applications. The VRLA segment leads value capture due to its maintenance-free operation in telecom and UPS installations where remote monitoring limits service access. The automotive end-user category sustains the largest volume footprint, though renewable integration applications for solar microgrids and rural electrification represent the fastest-growing demand pool as DISCOMs deploy decentralized storage.
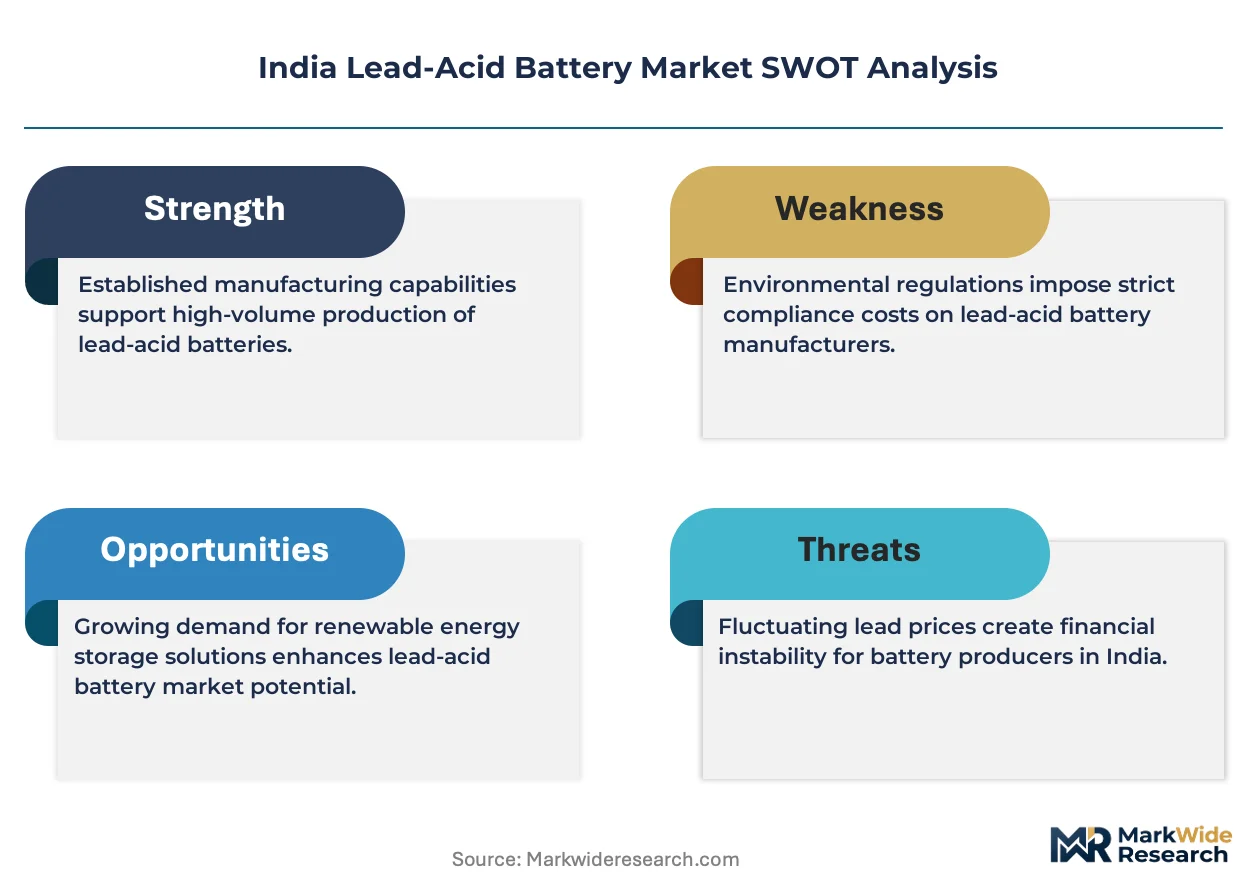
BIS standards enforcement and the Central Electricity Authority's battery safety guidelines shape product certification timelines and testing expenditures for manufacturers seeking market access. India's PLI scheme for advanced chemistry cells indirectly pressures lead-acid producers to defend cost positions against lithium-ion substitution in premium segments. Stakeholders must monitor how CEA grid-code revisions for energy storage mandate performance benchmarks that could accelerate technology transition timelines in select applications.
Market Dynamics
The India Lead-Acid Battery Market faces structural pressure from the PLI scheme for advanced chemistry cells, which indirectly accelerates lithium-ion substitution in premium automotive and stationary storage segments while forcing incumbent manufacturers to defend cost positions in volume applications.
Growth Catalysts
- Telecom Tower Electrification:Towercos are replacing diesel generators with VRLA battery banks across Maharashtra and Tamil Nadu, driven by TRAI mandates for green energy adoption in telecom infrastructure.
- BIS Certification Enforcement:Mandatory BIS standards for battery safety and performance are consolidating the unorganized sector, creating volume opportunities for compliant manufacturers in the automotive OEM replacement channel.
- Rural Solar Microgrids:DISCOMs are deploying decentralized lead-acid storage for village electrification, with Rajasthan and Odisha leading state-level procurement for off-grid installations.
Market Restraints
- Raw Lead Price Volatility:Global lead price fluctuations compress margin buffers for manufacturers dependent on imported concentrate, despite maturing domestic smelter capacity in Rajasthan.
- Lithium-Ion Cost Convergence:Falling lithium-ion pack prices threaten lead-acid dominance in two-wheeler and premium four-wheeler applications where weight and cycle life matter.
- CEA Grid-Code Stringency:Central Electricity Authority battery safety guidelines impose extended certification timelines and testing expenditures that disadvantage smaller producers.
Strategic Opportunities
- Defense and Railway Procurement:Indian Railways' electrification push and defense sector tenders for industrial-grade flooded batteries create insulated demand pools with multi-year contracts.
- Recycling Integration:Smelter investments in Rajasthan and Odisha enable backward integration into secondary lead production, reducing import dependence and raw material cost exposure.
- Tier-3 Distribution Penetration:Dense dealer networks in underserved tier-2 and tier-3 cities offer channel expansion potential as vehicle ownership penetrates beyond metropolitan centers.
Industry Challenges
- BIS Testing Bottlenecks:Certification backlogs at Bureau of Indian Standards laboratories delay product launches, compressing effective selling seasons for seasonal automotive demand.
- Electrochemical Talent Scarcity:Shortage of skilled technicians for VRLA maintenance and grid-scale battery installation limits service network expansion in remote telecom and solar installations.
- Legacy System Integration:Compatibility friction between new battery management systems and existing inverter-charger infrastructure in UPS installations slows technology refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Lead-Acid Battery Market |
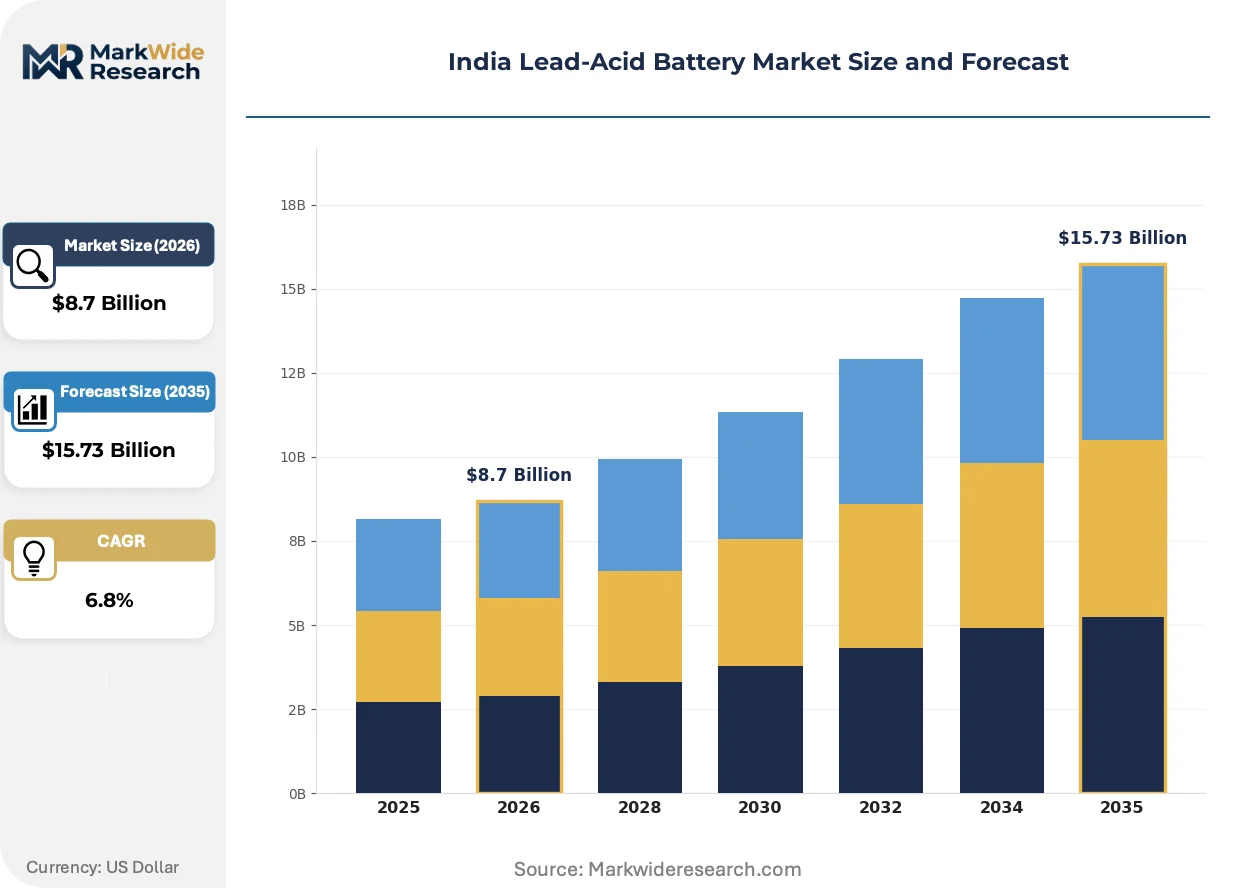
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLA, VRLA, Flooded, AGM End User: Automotive, Industrial, UPS, Telecom Application: Energy Storage, Transportation, Backup Power, Renewable Integration Distribution Channel: Wholesale, Retail, Direct Sales, Online |
| Companies Covered | HBL Power Systems Ltd, Jayachandran Industries (P) Ltd, Exide Industries Ltd, Su-Kam Power Systems Ltd, Livguard Energy Technologies Pvt Ltd, Amara Raja Batteries Ltd, Okaya Power Pvt Ltd, Microtex Energy Private Limited, Luminous Power Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Lead-Acid Battery Market Strategic Shifts
VRLA technology diffusion is reshaping competitive positioning across stationary applications, while regulatory pressure from the PLI scheme and CEA mandates accelerates performance benchmarking. Three forces are restructuring the market's technology and commercial architecture.
Valve-regulated lead-acid designs are decentralizing maintenance requirements across telecom tower installations. Towercos in Tamil Nadu and Maharashtra are adopting maintenance-free VRLA banks to reduce site visit frequency in remote locations. This technology is decentralizing service infrastructure investment away from centralized technician depots toward distributed monitoring systems.
CEA battery safety guidelines are tightening thermal runaway testing protocols for grid-connected storage installations. Manufacturers must now submit extended cycle-life documentation and abuse-test data before receiving interconnection approvals. The stationary UPS and solar microgrid segments are responding by accelerating in-house testing facility investments to compress pre-certification timelines.
Channel consolidation is compressing distributor margins in the automotive aftermarket. Large multi-brand battery retailers are displacing single-brand dealers in tier-2 cities, unbundling installation and warranty services from product margins. Karnataka and Gujarat exhibit the fastest channel transformation, with organized retailers capturing share from traditional dealer networks through bundled financing and doorstep delivery.
India Lead-Acid Battery Market Segmentation
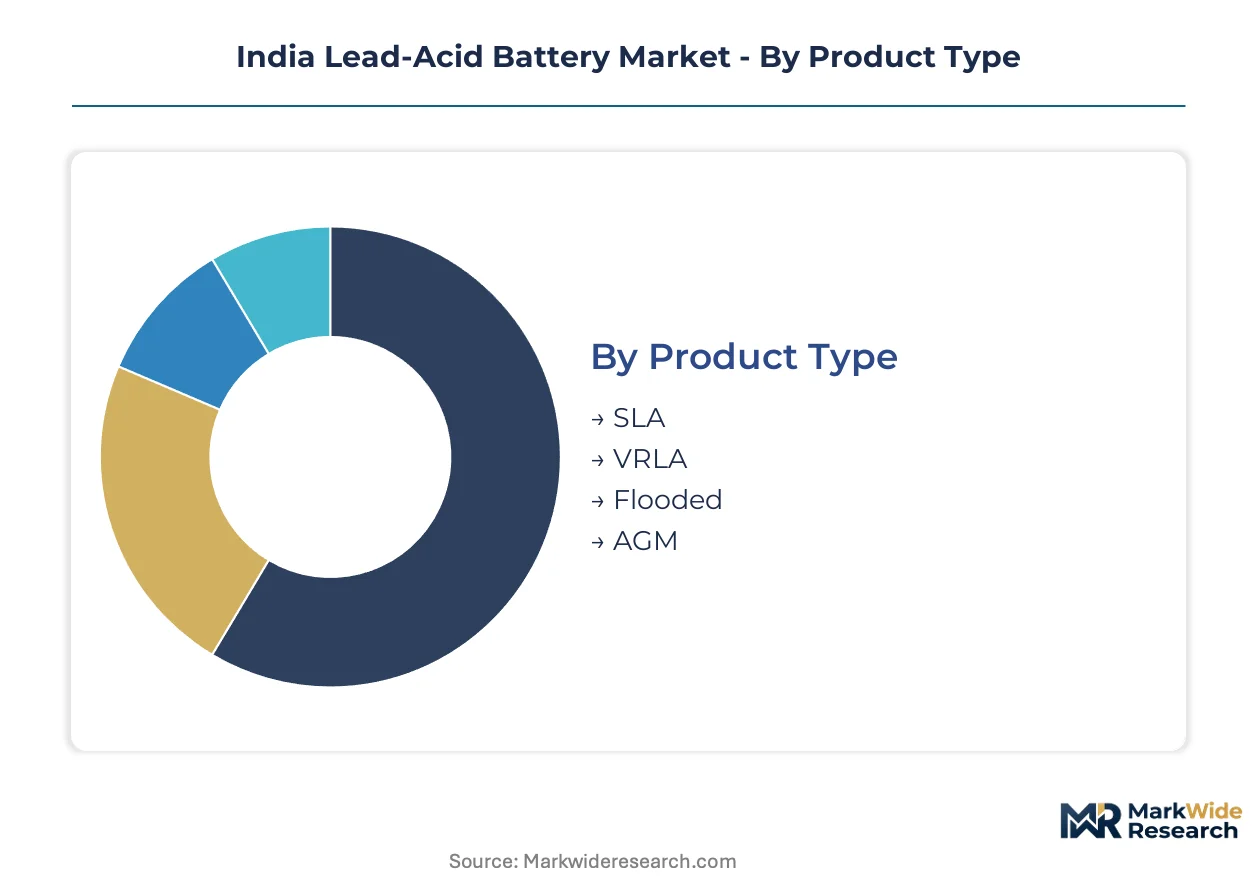
Segmentation reveals how capital deployment, regulatory exposure, and channel economics vary across battery technologies and customer verticals. Manufacturers allocate R&D and certification budgets differently depending on which segments anchor their revenue mix.
Product Type:
VRLA and AGM variants demand the heaviest upfront investment in precision casting equipment and sealed-cell assembly lines, while flooded batteries rely on more conventional tank formation infrastructure.
- SLA:Sealed lead-acid designs utilize immobilized electrolyte in gel or absorbent glass mat configurations, eliminating spillage risk. Maharashtra's telecom tower operators favor SLA banks for rooftop installations where maintenance access is restricted and vibration tolerance is essential.
- VRLA:Valve-regulated construction incorporates pressure-release vents that recombine hydrogen and oxygen internally, enabling upright or horizontal mounting. Tamil Nadu's tower infrastructure operators are replacing diesel generators with VRLA banks under TRAI green energy mandates, driving procurement volume through organized tenders.
- Flooded:Conventional vented designs with liquid electrolyte remain dominant in automotive cranking applications where cost minimization outweighs maintenance burden.
- AGM:Absorbent glass mat separators enable higher compression ratios and faster charge acceptance for start-stop vehicle systems.
VRLA absorbs the bulk of installed capacity; AGM is expanding most quickly as automakers adopt micro-hybrid architectures.
End User:
Capital recovery timelines stretch longest in industrial procurement channels where qualification cycles and warranty reserves tie up working capital.
- Automotive:OEM replacement demand concentrates in tier-2 and tier-3 cities where vehicle ownership is penetrating beyond metropolitan centers. BIS certification enforcement is consolidating the unorganized sector, creating volume opportunities for compliant manufacturers in this channel.
- Industrial:Indian Railways and defense procurement channels specify industrial-grade flooded batteries with multi-year contract structures. Rajasthan's smelter investments enable backward integration for producers serving this insulated demand pool.
- UPS:Data center and commercial building installations require VRLA configurations with 10-15 year design life.
- Telecom:Towercos across Maharashtra and Tamil Nadu are deploying battery banks as diesel replacement under regulatory pressure.
Automotive channels move the highest unit volumes; telecom procurement is climbing the fastest as green energy mandates harden.
Application:
Application segmentation determines which performance certifications and abuse-testing protocols manufacturers must satisfy before market entry.
- Energy Storage:Grid-connected installations face CEA thermal runaway testing protocols that extend certification timelines. DISCOMs in Rajasthan and Odisha are procuring decentralized storage for village electrification, creating procurement concentration in off-grid segments.
- Transportation:Two-wheeler and commercial vehicle starting applications sustain the largest volume footprint, though lithium-ion substitution is pressuring premium four-wheeler segments.
- Backup Power:Commercial and residential UPS installations demand maintenance-free operation with remote monitoring compatibility.
- Renewable Integration:Solar microgrid deployments in rural electrification programs require deep-cycle durability under partial state-of-charge operation.
Transportation applications dominate current shipments; renewable integration is gaining share fastest as DISCOM procurement accelerates.
Distribution Channel:
Channel selection dictates margin structure and customer acquisition cost, with direct sales requiring field engineering investment and online channels demanding logistics infrastructure.
- Wholesale:Bulk procurement by OEMs and industrial buyers concentrates volume through negotiated annual contracts with price adjustment clauses tied to lead commodity indices.
- Retail:Multi-brand battery retailers are displacing single-brand dealers in tier-2 cities, unbundling installation and warranty services from product margins in Karnataka and Gujarat.
- Direct Sales:Railway and defense tenders bypass distributor networks through specialized procurement cells with extended qualification requirements.
- Online:E-commerce penetration remains limited to replacement batteries in metropolitan markets where doorstep delivery and bundled financing attract convenience-oriented buyers.
Retail channels handle the greatest transaction volume; direct sales are expanding most quickly in institutional procurement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan's lead smelter belt anchors domestic raw material supply for battery manufacturers across India. State-level industrial policies and BIS certification requirements reshape regional production economics.
Maharashtra
Automotive manufacturing clusters in Pune and Chakan drive OEM replacement demand for flooded batteries. The state's BIS enforcement infrastructure accelerates certification timelines for compliant manufacturers. Towercos in Mumbai and Nagpur deploy VRLA banks under TRAI green energy mandates, replacing diesel generators at rooftop installations.
Tamil Nadu
Chennai's automotive corridor sustains volume absorption for starting-lighting-ignition batteries. CEA grid-code compliance costs concentrate testing facility investments in Sriperumbudur industrial zones. Telecom infrastructure operators across Coimbatore and Madurai tender for maintenance-free VRLA configurations under renewable integration targets.
Rajasthan
Secondary lead smelters in Jaipur and Udaipur reduce import dependence for battery-grade lead. The state's mineral processing incentives attract backward integration investments from industrial battery producers. Off-grid solar microgrid procurement by Rajasthan DISCOMs creates demand concentration for deep-cycle storage in rural electrification programs.
Gujarat
Chemical processing hubs in Vadodara and Ahmedabad supply sulfuric acid electrolyte to regional battery fabricators. The state's industrial park policies enable co-location of formation tank facilities with automotive component suppliers. Organized battery retailers in Surat and Rajkot displace traditional dealer networks through bundled financing offers.
Karnataka
Bengaluru's data center expansion drives UPS battery procurement for commercial backup installations. The state's electronics manufacturing incentives support VRLA assembly line investments in Hosur industrial corridors. Multi-brand retail formats penetrate tier-2 cities faster here than in northern states, compressing distributor margins.
India Lead-Acid Battery Market Competitive Environment
Global technology licensors compete with domestic integrated manufacturers across product certification and channel density. The market structures around three tiers: vertically integrated smelter-battery producers, technology-focused VRLA specialists, and regional aftermarket distributors. Dominant competitive moves include backward integration into secondary lead production and expansion of tier-3 dealer networks beyond metropolitan centers.
Within the integrated producer tier, Exide Industries Ltd and Amara Raja Batteries Ltd exemplify scale-driven archetypes with nationwide distribution infrastructure. HBL Power Systems Ltd occupies a position in industrial-grade flooded batteries for defense and railway procurement channels. These three anchors represent contrasting strategic postures: mass-market aftermarket penetration, technology leadership in sealed designs, and insulated institutional contracting.
| Leading Market Players |
|---|
| HBL Power Systems Ltd |
| Jayachandran Industries (P) Ltd |
| Exide Industries Ltd |
| Su-Kam Power Systems Ltd |
| Livguard Energy Technologies Pvt Ltd |
| Amara Raja Batteries Ltd |
| Okaya Power Pvt Ltd |
| Microtex Energy Private Limited |
| Luminous Power Technologies |
| Others |
Value Chain & Pricing Dynamics
VRLA technology maturation in Indian telecom installations simultaneously compresses manufacturing cost curves and concentrates supply among certified producers capable of meeting BIS thermal runaway protocols. This dual effect reshapes how battery-grade lead flows from Rajasthan smelters to finished cell assemblers, with compliance-capable manufacturers capturing pricing power over unorganized competitors.
Pricing Analysis
Warranty bundling separates organized manufacturers from unorganized competitors in the automotive aftermarket. Three-tier pricing structure across premium AGM, standard VRLA, and economy flooded levels tracks certification grade and after-sales service inclusion. Pricing pressure stems from lithium-ion cost convergence in two-wheeler applications, compressing margins in the most price-sensitive consumer segment. Industrial procurement through Indian Railways tenders exhibits lowest price sensitivity due to multi-year contract structures and technical qualification barriers.
Supply Chain Analysis
Domestic content mandates under India's PLI scheme for advanced chemistry cells reshape lead-acid sourcing strategies despite scheme targeting lithium-ion alternatives. Battery-grade lead draws from domestic smelters in Rajasthan and Odisha, with sulfuric acid electrolyte sourced from Gujarat chemical processing hubs. Single-source vulnerability concentrates in imported lead concentrate for high-purity applications. Distribution runs through multi-brand retailers in tier-2 cities and direct sales channels for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India lead-acid battery market occupies a technology-transition phase as lithium-ion systems displace legacy flooded designs in premium automotive and stationary storage segments.
For Market Incumbents: Anticipate lithium-ion substitution pressure in two-wheeler and passenger vehicle applications by accelerating backward integration into Rajasthan smelter capacity and deepening VRLA technology leadership for telecom tower mandates. Certification investment in CEA grid-code compliance creates defensive moats against unorganized sector competition. For New Entrants and Emerging Players: E-commerce platforms for doorstep battery replacement in Bengaluru and Hyderabad metro markets offer white-space penetration with bundled financing and installation services. Tier-3 cities in Madhya Pradesh and Uttar Pradesh present underexploited automotive aftermarket demand with lower incumbent dealer density. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated industrial conglomerates seeking battery storage capabilities. Long-term viability hinges on producers' ability to defend cost positions in volume applications while capturing premium margins in VRLA telecom and defense procurement. Monitor PLI scheme disbursement acceleration as inflection signal for lithium-ion substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Lead Smelting | Rajasthan smelter investments reduce import exposure and stabilize raw material cost structures for battery producers. |
| VRLA Certification Investment for Telecom Applications | BIS and TRAI compliance enables access to tower electrification tenders replacing diesel generators across Maharashtra. |
| Tier-3 Distribution Network Expansion | Dense dealer penetration in Madhya Pradesh and Uttar Pradesh captures vehicle ownership growth beyond metropolitan centers. |
| Defense and Railway Procurement Qualification | Industrial-grade flooded battery contracts with Indian Railways create insulated demand pools with multi-year revenue visibility. |
| Recycling Loop Integration | Captive secondary lead production from spent battery collection compresses input costs and satisfies emerging environmental mandates. |
Study Parameters
Industry association filings, BIS certification databases, and Central Electricity Authority grid-code documentation formed the secondary backbone for this analysis. Primary interviews with battery manufacturing executives, telecom tower procurement managers, and automotive aftermarket distributors validated demand assumptions. Bottom-up shipment estimates by product type and end-use application triangulated against top-down lead consumption data from Rajasthan and Odisha smelter disclosures.
Historical trendline analysis of automotive production volumes, telecom tower electrification mandates, and DISCOM solar microgrid procurement established baseline growth trajectories. The analytical framework modeled segmentation across VRLA, AGM, and flooded product architectures; automotive, industrial, telecom, and UPS end-user categories; and wholesale, retail, direct, and online distribution channels. CAGR derivation incorporated lead price volatility indices and lithium-ion substitution elasticity assumptions across the projection horizon.
The model holds under stable BIS enforcement intensity and continued TRAI green energy mandates; deviation in PLI scheme disbursement acceleration or CEA grid-code stringency would shift technology transition timelines. Forecasts reflect documented assumptions regarding raw material cost trajectories and regulatory compliance burdens. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Smart Battery Charger Market
Batteries
Wireless Power Bank Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Utility Battery Market
Batteries
North America Rechargeable Battery Market
Batteries
Watch Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
Lithium Starters Market
Batteries
North Africa Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Lithium-Based Battery Charger Market
Batteries
Lithium Battery Testing System Market
Batteries
South America Battery Cell Market
Batteries
Military Battery Market