
 Construction Films Market | 2026-2036
Construction Films Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Films Market Analysis
The EU Green Deal is repositioning construction films toward lower-carbon formulations across European building envelopes. Berry Global, Inc. leverages vertical integration across resin compounding and film extrusion to secure supply continuity. Saint-Gobain anchors its position through specialized vapor barrier membranes engineered for energy-efficient retrofits. DuPont differentiates via fluoropolymer-based barriers that sustain performance under extreme moisture loads.
Construction films are polymer-based sheet materials, typically 0.1 to 2.0 mm in thickness, manufactured through extrusion or blown film processes to control air, moisture, and thermal transfer in built environments. Their primary commercial purpose spans weatherization, environmental containment, and controlled agriculture infrastructure. Polyethylene dominates volume production for temporary protection and greenhouse covers due to cost scalability, while blown film technology leads in barrier property customization for high-performance building wraps where moisture control determines structural longevity. Laminated film structures command premium positioning in landfill liner applications where chemical resistance and seam integrity prevent environmental leakage.
REACH regulates phthalate plasticizer content in PVC construction films across Europe, compelling reformulation toward bio-based or non-phthalate alternatives. The EPA's stormwater management guidelines influence geomembrane specifications for US landfill and containment projects. China's GB standards mandate flame retardancy ratings in public building applications, reshaping additive packages for polycarbonate and polypropylene films. Stakeholders must track evolving extended producer responsibility frameworks that will determine cost recovery models for post-consumer agricultural and construction film waste streams.
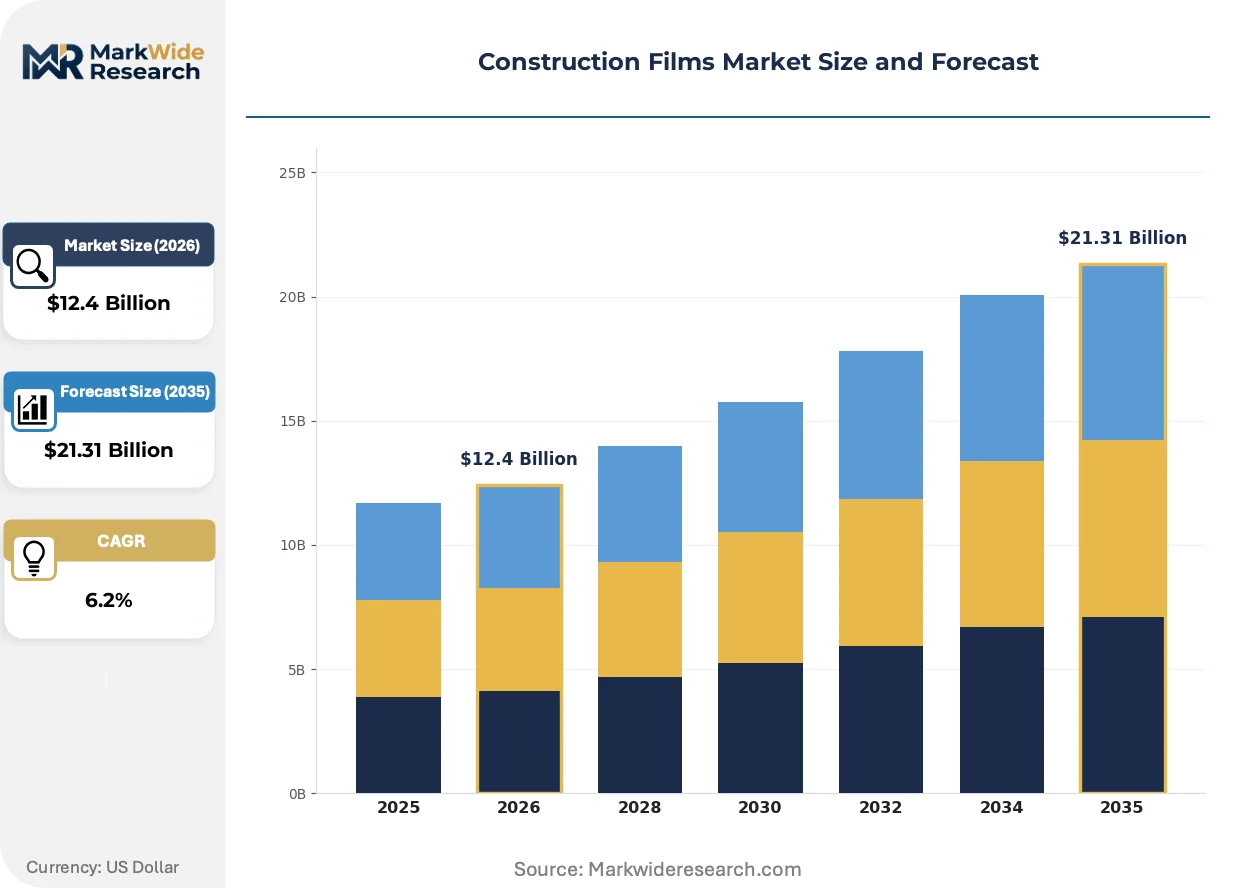
Market Dynamics
The EU Green Deal's embodied carbon rules are compressing demand toward lower-carbon film formulations, forcing resin suppliers and extruders to requalify product lines for European building envelope specifications.
Growth Catalysts
- Passive house retrofits:Germany's building stock renovation mandates are pulling multilayer vapor barrier films into residential energy efficiency projects at scale.
- REACH plasticizer restrictions:Phthalate limitations in PVC construction films are accelerating bio-based plasticizer adoption across European greenhouse and containment applications.
- Blown film barrier customization:Advances in coextrusion control are enabling moisture-specific membrane engineering for high-humidity climate zones.
Market Restraints
- Resin supply concentration:Polyethylene feedstock availability clusters around Gulf Coast petrochemical complexes, exposing film extruders to hurricane-related disruption risk.
- Technical performance ceilings:Standard polyethylene greenhouse covers degrade under UV exposure within 3-4 growing seasons, limiting replacement cycle extension.
- Geomembrane certification friction:EPA stormwater management guidelines impose extended testing timelines for landfill liner approvals, delaying project revenue recognition.
Strategic Opportunities
- Fluoropolymer barrier convergence:Combining PTFE membranes with nanofiber substrates is opening extreme-moisture applications in tropical commercial construction.
- Extended producer responsibility frameworks:Emerging EU waste recovery mandates for agricultural films are creating closed-loop recycling service revenue streams.
- India's building code evolution:BIS standards for energy-efficient envelopes are pulling vapor barrier specifications into commercial real estate development.
Industry Challenges
- Coextrusion technician scarcity:Multilayer blown film operation requires specialized polymer rheology expertise that outpaces vocational training program output.
- Legacy system integration:Smart membrane sensors for moisture monitoring face interoperability friction with established building management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Films Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $21.31 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Polycarbonate Application: Building Wrap, Vapor Barrier, Landfill Liner, Greenhouse Cover Technology: Extrusion, Blown Film, Cast Film, Laminated Film End User: Contractors, Architects, Builders, Engineers |
| Companies Covered | Berry Global, Inc., Raven Industries, Saint-Gobain, Eastman Chemical Company, DuPont, RKW Group, Mitsubishi Chemical Corporation, Toray Industries, Inc., Polifilm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Films Market Emerging Trajectories
Material science advances and regulatory carbon accounting are converging to redefine performance specifications across construction film categories, with formulation transparency becoming a procurement gate.
Multilayer coextrusion with nanoclay reinforcement is electrifying barrier property customization for high-performance building wraps. Passive house certifiers in Germany and Austria are specifying these structures for retrofit envelopes. The technology is compressing the performance gap between commodity polyethylene and fluoropolymer membranes in moderate climate applications.
REACH authorization procedures for phthalate alternatives are tightening compliance documentation requirements for PVC film importers. ECHA's substance evaluation timelines are extending reformulation validation cycles by 12-18 months. Small and mid-scale extruders without dedicated regulatory affairs capacity are exiting the European greenhouse cover segment.
Building envelope specifiers are unbundling membrane procurement from general contractor packages, establishing direct manufacturer relationships for performance-guaranteed vapor barriers. This disintermediation concentrates in Germany's EnerPHit retrofit market where warranty terms determine financing approval. Distributors are responding with certified installer networks to retain specification influence.
Construction Films Market Segmentation
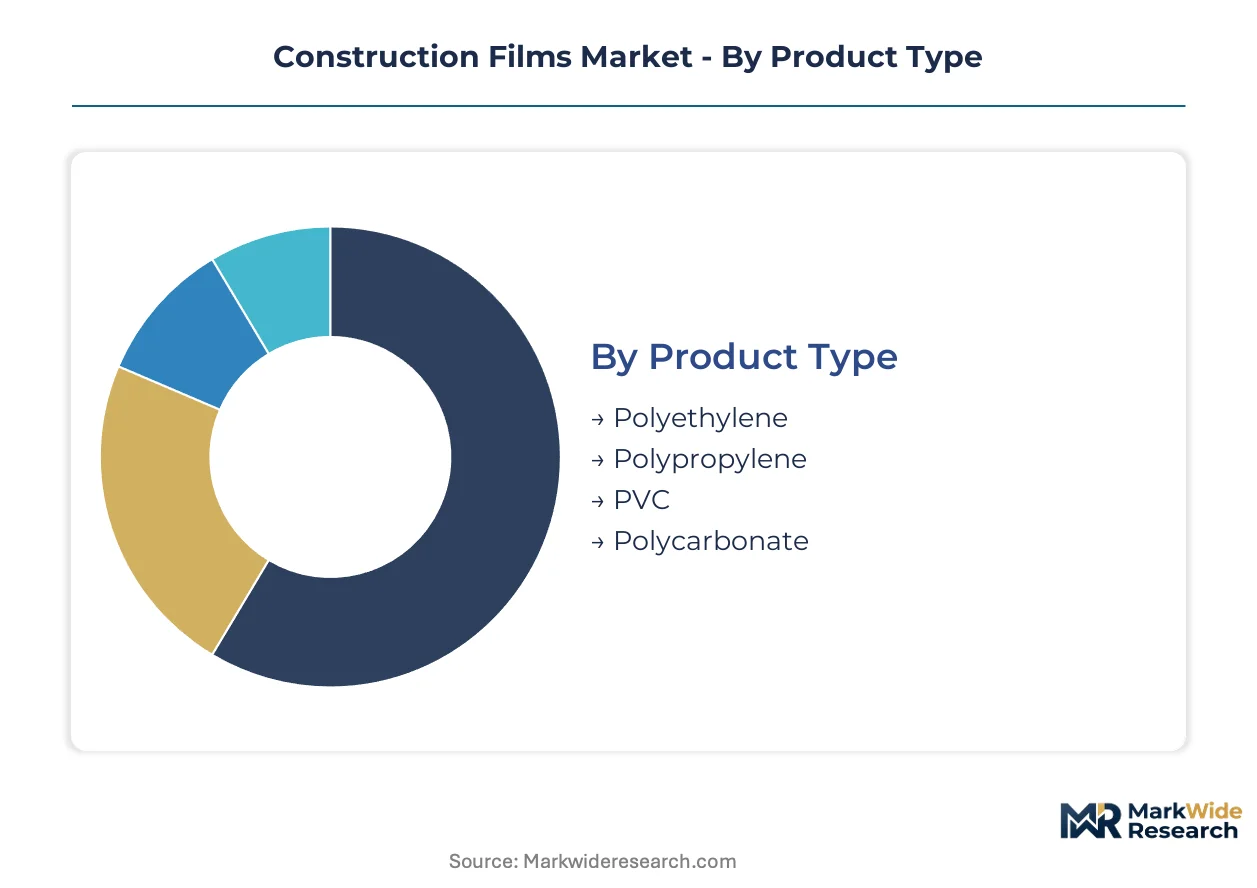
Construction films serve divergent performance requirements across building envelopes, containment infrastructure, and controlled agriculture. Segmentation reveals how resin chemistry, manufacturing process, and installation context determine specification pathways and certification obligations.
Product Type:
REACH authorization procedures and EPA stormwater guidelines impose distinct compliance burdens on each resin family, with phthalate restrictions reshaping PVC formulations and embodied carbon rules pressuring polyethylene sourcing.
- Polyethylene:Linear low-density and high-density grades dominate temporary protection and greenhouse covers through cost scalability and UV-stabilized masterbatch customization. Germany's passive house retrofit sector pulls multilayer blown film structures into energy-efficient building envelopes, though Gulf Coast resin concentration exposes supply continuity to hurricane disruption.
- Polycarbonate:Rigid sheet configurations deliver impact resistance and optical clarity for daylighting applications and protective glazing. China's GB standards mandate flame retardancy ratings in public building applications, forcing additive package reformulation for compliance.
- Polypropylene:Biaxially oriented films offer moisture resistance and dimensional stability for geomembrane applications.
- PVC:Flexible calendered sheets face REACH phthalate plasticizer restrictions, accelerating bio-based alternative adoption.
Polyethylene sits at the top of the volume ranking, with polycarbonate climbing the fastest on energy-efficient building code adoption.
Application:
Installation environment dictates performance tier and margin structure, with below-grade containment commanding premium pricing against above-grade weatherization.
- Greenhouse Cover:Diffused light transmission films with anti-drip surface treatments optimize photosynthetic efficiency for commercial horticulture operations. The EU Green Deal's agricultural sustainability criteria are pulling recyclable mono-material structures into Dutch and Spanish greenhouse clusters.
- Landfill Liner:High-density polyethylene geomembranes with textured surfaces ensure slope stability and seam integrity for leachate containment. EPA stormwater management guidelines impose extended testing timelines, delaying project revenue recognition for certification-dependent contractors.
- Building Wrap:Permeable housewraps balance bulk water exclusion with vapor permeability for wall assembly durability.
- Vapor Barrier:Multilayer coextruded membranes control moisture diffusion in high-performance envelopes.
Building wrap maintains volume leadership across new residential construction, while greenhouse cover gains share fastest on commercial grower expansion.
Technology:
Process selection determines barrier property tunability and capital intensity, with blown film lines requiring specialized technician expertise that outpaces vocational training output.
- Blown Film:Coextrusion control enables moisture-specific membrane engineering through layer thickness distribution and polymer rheology management. Germany's EnerPHit retrofit market specifies these structures for warranty-backed energy performance guarantees.
- Laminated Film:Adhesive or extrusion lamination combines dissimilar substrates for chemical resistance and puncture toughness in aggressive containment environments. Landfill liner applications command premium positioning where seam integrity prevents environmental leakage.
- Extrusion:Cast and sheet extrusion deliver dimensional precision for rigid architectural glazing.
- Cast Film:Chill-roll casting produces optical clarity for daylighting and display applications.
Blown film leads volume production, with laminated film expanding most quickly on containment infrastructure investment.
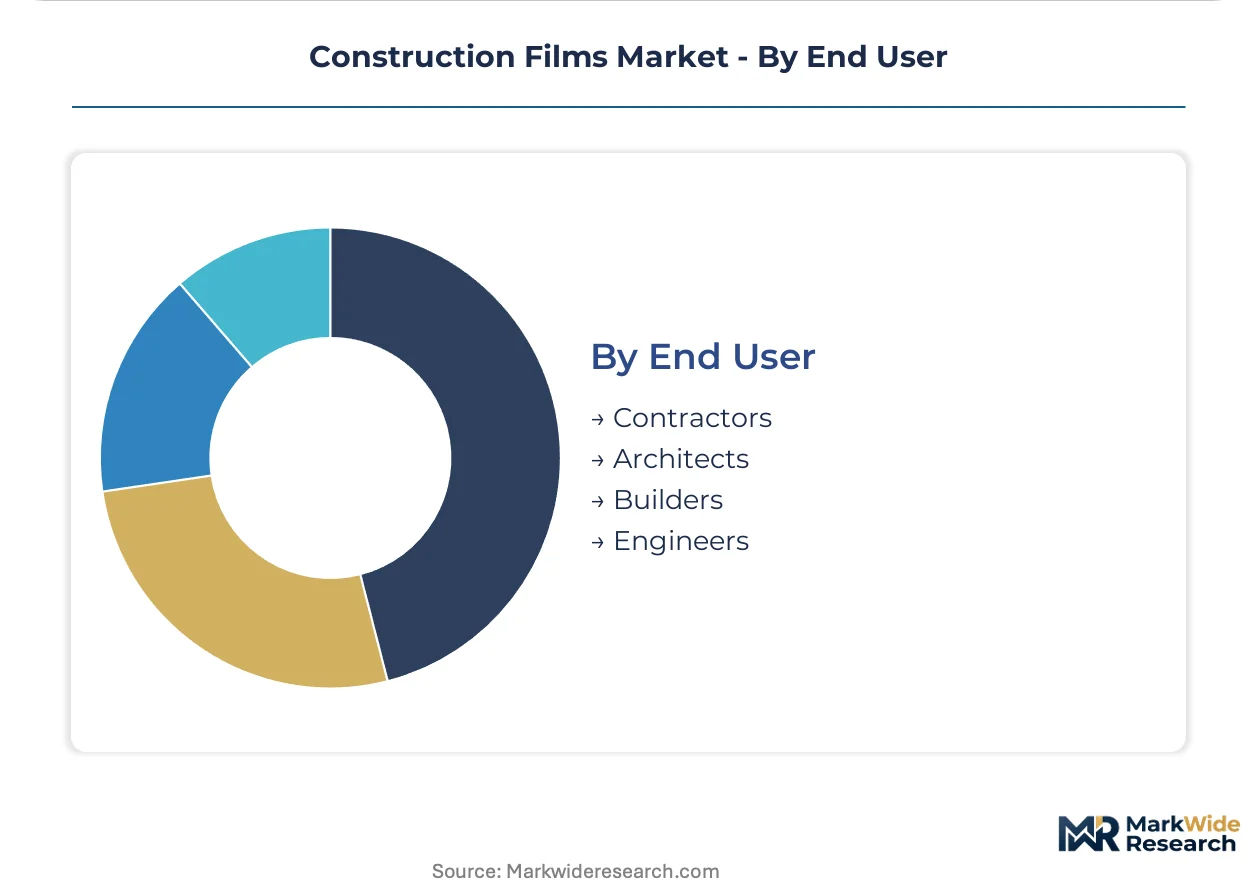
End User:
Procurement authority concentration varies by project delivery method, with design-build contracts consolidating specification influence versus traditional bid-build fragmentation.
- Architects:Building envelope specifiers unbundle membrane procurement from general contractor packages, establishing direct manufacturer relationships for performance-guaranteed vapor barriers. This disintermediation concentrates in Germany's EnerPHit market where warranty terms determine financing approval.
- Contractors:Installation crews prioritize field flexibility and seam reliability over material sophistication, driving demand for heat-weldable and self-adhered membrane formats.
- Builders:Production home construction favors cost-optimized commodity films with established code compliance.
- Engineers:Infrastructure projects specify geomembranes through performance-based procurement with extended testing protocols.
Contractors represent the largest addressable base by project count, with architects gaining specification influence fastest on energy code stringency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered vapor barrier engineering for passive house construction during the 1990s EnerPHit program, establishing technical protocols that now propagate through EU building codes. This heritage shapes contemporary demand patterns across high-performance building envelopes.
Germany
EnerPHit retrofit mandates pull multilayer blown film structures into residential energy efficiency projects at scale. REACH authorization procedures for phthalate alternatives tighten compliance documentation requirements for PVC film importers. The Rhine-Main industrial corridor hosts extrusion specialists serving warranty-backed vapor barrier specifications for financing-approved renovations.
United States
EPA stormwater management guidelines influence geomembrane specifications for landfill and containment projects across municipal infrastructure. Hurricane exposure along Gulf Coast petrochemical complexes concentrates polyethylene feedstock availability, exposing film extruders to supply disruption risk. The Houston Ship Channel anchors resin compounding capacity serving domestic blown film operations.
China
GB standards mandate flame retardancy ratings in public building applications, reshaping additive packages for polycarbonate and polypropylene films. Dual carbon goals pressure embodied carbon accounting in construction material procurement. The Yangtze River Delta clusters film extrusion capacity serving domestic greenhouse cover demand from commercial horticulture expansion.
India
BIS standards for energy-efficient envelopes pull vapor barrier specifications into commercial real estate development in metro corridors. Extended producer responsibility frameworks for agricultural film waste streams remain under central ministry consultation. Gujarat's petrochemical belt supplies polyethylene resin to domestic calendering and blown film operations.
Netherlands
EU Green Deal agricultural sustainability criteria pull recyclable mono-material structures into Dutch greenhouse clusters for commercial grower compliance. ECHA substance evaluation timelines extend reformulation validation cycles for imported PVC formulations. The Westland region concentrates horticulture infrastructure demanding diffused light transmission films with anti-drip surface treatments.
Construction Films Market Vendor Landscape
Premium-margin players sit above commodity-margin players across barrier property customization and certification depth. The vendor base organizes into three tiers: integrated resin-to-film operators capturing supply continuity premiums, specialized membrane engineers commanding specification authority in retrofit markets, and regional extruders competing on lead time and minimum order flexibility. Dominant competitive moves include backward integration into resin compounding and certified installer network development to retain specification influence.
Within the integrated resin-to-film tier, Berry Global, Inc. and DuPont occupy positions securing captive supply chains against feedstock volatility. Saint-Gobain anchors the specialized membrane engineering segment through its heritage in building envelope performance guarantees. These three entities exemplify how vertical control over resin qualification and extrusion precision determines access to warranty-dependent procurement channels in Germany's EnerPHit market.
| Leading Market Players |
|---|
| Berry Global, Inc. |
| Raven Industries |
| Saint-Gobain |
| Eastman Chemical Company |
| DuPont |
| RKW Group |
| Mitsubishi Chemical Corporation |
| Toray Industries, Inc. |
| Polifilm |
| Others |
Supply Flow & Price Mechanics
Coextrusion technician scarcity in Germany's Rhine-Main industrial corridor widens labor-cost differentials between premium-certified membrane producers and commodity extruders, compressing pricing-tier spreads as warranty-backed specifications concentrate specification power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and resin qualification rigor. Price differentiation hinges on REACH compliance documentation and EnerPHit warranty backing versus commodity polyethylene grades. Pricing pressure stems from resin feedstock volatility along Gulf Coast petrochemical corridors. Production home builders exhibit highest price sensitivity; passive house certifiers and infrastructure engineers demonstrate lowest.
Supply Chain Analysis
Polyethylene feedstock rests on Gulf Coast petrochemical complexes in the United States, German resin compounding capacity along the Rhine-Main corridor, and Gujarat's petrochemical belt in India. Key inputs include linear low-density polyethylene resin, UV-stabilized masterbatches, and bio-based plasticizer alternatives. Single-source vulnerability concentrates around hurricane-exposed Gulf Coast production. Distribution runs through certified installer networks and direct manufacturer relationships in Germany's retrofit market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compliance costs and Indian BIS standard adoption curves, with embodied carbon accounting in Europe compressing margin structures faster than emerging market code evolution.
For Market Incumbents: Anticipate REACH authorization timeline extensions for phthalate alternatives by accelerating bio-based plasticizer R&D partnerships. Deepen backward integration into resin compounding to secure supply continuity against Gulf Coast disruption. Certification investment in India's BIS standards represents the critical lever for early-mover positioning as commercial real estate codes tighten.
For New Entrants and Emerging Players: Nanoclay-reinforced multilayer coextrusion technology offers a technology-first wedge into Germany's passive house retrofit segment where technician scarcity limits incumbent capacity expansion. Target Dutch greenhouse clusters demanding recyclable mono-material structures under EU Green Deal agricultural criteria. Pursue direct-specification relationships with architects unbundling membrane procurement from general contractor packages.
For Investors and Strategic Acquirers: Specialized membrane engineers with captive resin qualification capabilities are the most active acquirer targets in this space, as integrated resin-to-film operators seek specification authority in warranty-dependent procurement channels. Long-term viability favors entities controlling both formulation transparency and certified installer network density. Watch ECHA substance evaluation timeline compression as the inflection signal for regulatory-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates against Gulf Coast hurricane disruption for German extruders. |
| Certified Installer Network Development | Distributor retention of specification influence counters architect-led disintermediation in EnerPHit markets. |
| Bio-Based Plasticizer Reformulation | REACH phthalate restrictions force PVC film requalification, accelerating alternative adoption timelines. |
| Nanoclay Reinforcement R&D Investment | Multilayer coextrusion advances compress the performance gap between polyethylene and fluoropolymer membranes. |
| Direct Manufacturer-Archetype Relationships | Building envelope specifiers unbundle procurement from general contractors for warranty-backed vapor barriers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blown film extrusion plant managers, REACH regulatory affairs specialists, passive house certifiers, and greenhouse procurement directors with secondary validation through ECHA authorization databases, EPA stormwater guideline filings, customs and trade data, and BIS standard evolution records. Bottom-up resin consumption modeling and top-down construction spending triangulation anchored volume estimates.
Historical reference periods established baseline penetration rates for multilayer vapor barrier specifications across Germany's EnerPHit retrofit wave, with projections extending across the analysis window through segmented modeling by resin chemistry, manufacturing process technology, application environment, and end-user procurement authority. CAGRs derived from regression against building code adoption curves and agricultural sustainability mandate implementation schedules. Industry-specific inputs included coextrusion line capacity utilization rates and ECHA substance evaluation pipeline status.
The model holds under stable REACH authorization timelines and Gulf Coast petrochemical operational continuity; deviation in ECHA evaluation acceleration or hurricane-induced resin supply disruption would shift volume and value trajectories. A small set of named triggers—ECHA phthalate alternative approval compression, India BIS enforcement escalation, and extended producer responsibility mandate finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Mylar Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Global Strapping Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Stick Packaging Market
Packaging Materials
Finish Foils Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Lid Laminates Market
Packaging Materials
US Packaging Market