
 Packaging Primers Market | 2026-2036
Packaging Primers Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Primers Market Analytics
Flexible packaging converters is redrawing procurement priorities across the Packaging Primers Market as e-commerce-ready formats displace rigid alternatives. BASF SE leverages its acrylic resin backbone to supply primer systems with verified low-migration profiles for food-contact laminates. PPG Industries anchors North American supply through dedicated coil and packaging coating facilities with in-house resin synthesis. Henkel AG & Co. KGaA competes on reactive hotmelt and water-based primer platforms tailored to high-speed converting lines.
Packaging primers are thin-film adhesion promoters, typically 0.1–2.0 µm dry thickness, formulated from acrylic, epoxy, or polyurethane chemistries to bridge dissimilar substrates such as oriented polypropylene and aluminum foil in multilayer flexible structures. Their primary purpose is to prevent delamination under thermal stress, moisture ingress, and mechanical flexing during distribution. Water-based primers now lead volume growth as converters retrofit solvent-recovery systems to comply with emissions rules, while epoxy systems retain margin concentration in retort and aseptic applications requiring sterilization resistance. Acrylic primers dominate standard flexible packaging where cost-per-square-meter and line speed dictate supplier selection.
EPA NESHAP standards for hazardous air pollutants and EU REACH restrictions on isocyanate-containing formulations are forcing reformulation investments across supplier labs. FDA food-contact notification requirements and EFSA migration limits determine market access for primer systems sold into regulated food packaging channels. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify dual-compliant product lines.
Market Dynamics
Water-based primer systems are accelerating their displacement of solvent-borne formulations as converters face mounting compliance costs under EPA NESHAP and EU REACH frameworks, forcing simultaneous capital deployment into drying infrastructure and resin chemistry.
Growth Catalysts
- Retort packaging expansion:Epoxy primer demand climbs as sterilizable pouches replace metal cans in ready-meal applications, with converters in Germany and China installing dedicated coating lines.
- REACH Annex XVII restrictions:Regulatory pressure on isocyanate-containing systems is pulling investment toward acrylic-urethane hybrids with verified low-migration profiles for food-contact laminates.
- E-commerce fulfillment formats:High-barrier flexible structures with primer-bonded aluminum layers are capturing share from rigid containers in snack and pet food distribution.
Market Restraints
- Acrylic monomer volatility:Feedstock cost swings for 2-EHA and butyl acrylate compress formulation margins, particularly for spot-market buyers without backward-integrated resin supply.
- Specialty resin concentration:Three German chemical groups control over 60% of global waterborne acrylic resin capacity for packaging primers, creating supply vulnerability during force majeure events.
- Migration testing burden:EFSA food-contact notification requirements and FDA FCN processes extend qualification timelines to 18-24 months for new primer chemistries.
Strategic Opportunities
- India flexible packaging buildout:FSSAI harmonization with EU migration limits and domestic PLI scheme incentives are attracting primer suppliers to Gujarat and Maharashtra film production clusters.
- Mono-material recyclable structures:Primer systems enabling polypropylene-to-polypropylene bonding without aluminum foil interlayers address EU Packaging and Packaging Waste Regulation recyclability mandates.
- Digital print primer compatibility:Corona-treated primer surfaces optimized for UV inkjet adhesion are opening specification wins with narrow-web converters serving craft beverage segments.
Industry Challenges
- Formulation chemist scarcity:Expertise in low-migration acrylic-epoxy hybrid design concentrates among retiring specialists at major resin houses, constraining new product development velocity.
- Legacy solvent line retrofit costs:Converters with 1990s-era coating towers face $2-4 million per line capital requirements for aqueous primer conversion, extending payback periods.
- Dual-jurisdiction compliance:Primer suppliers must maintain parallel inventory for FDA-compliant and EFSA-compliant variants, complicating supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Primers Market |
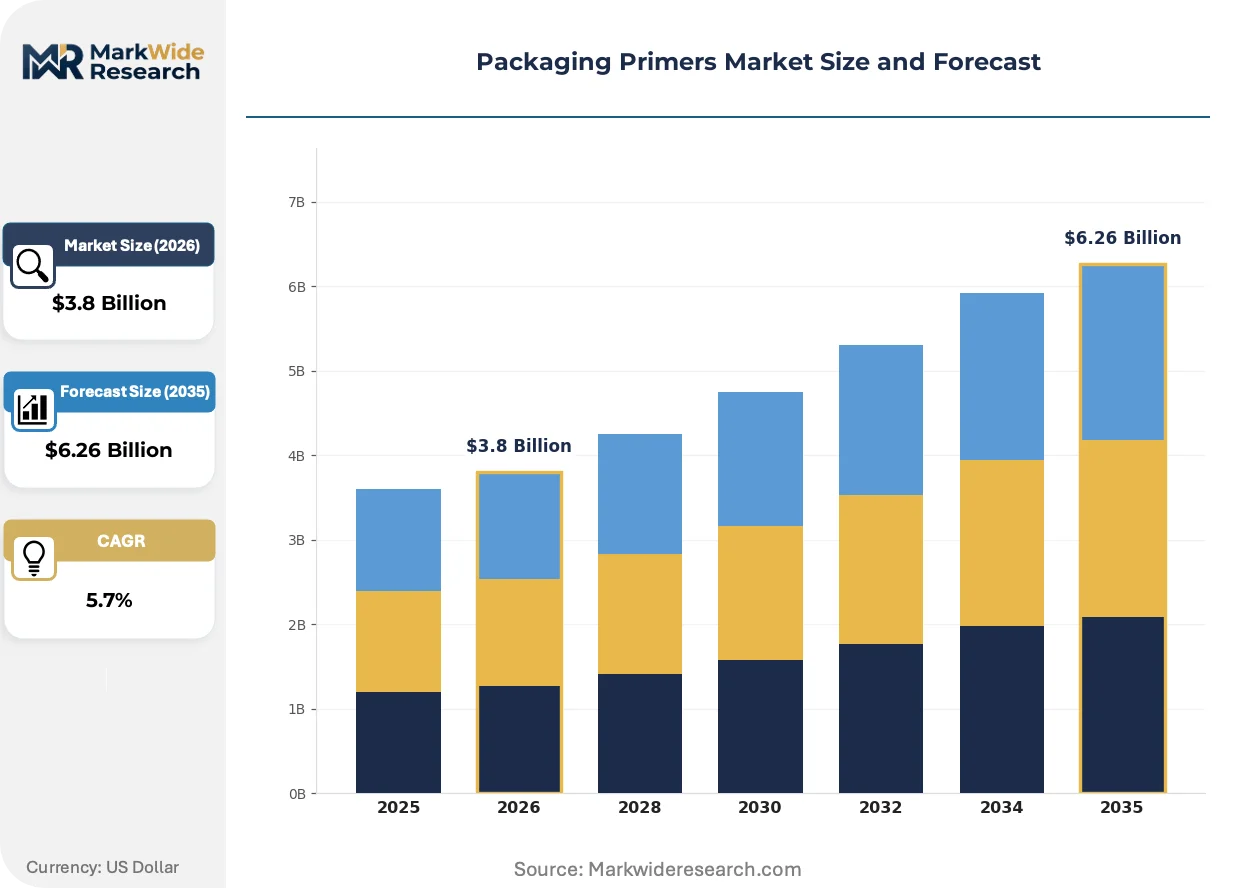
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Water-Based Application: Food & Beverage, Personal Care, Electronics, Industrial End User: Manufacturers, Distributors, Retailers, Packaging Companies Material: Plastic, Metal, Glass, Paper |
| Companies Covered | BASF SE, The Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., Axalta Coating Systems, DIC Corporation, ACTEGA Terra GmbH, Henkel AG & Co. KGaA, National Paints Factories Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Primers Market Evolving Landscape
Formulation chemistry and application hardware are converging to eliminate solvent recovery infrastructure while maintaining bond performance under aggressive thermal and mechanical stress conditions.
Ultraviolet-curable primer systems are supplanting thermal-dry waterborne formulations in high-speed gravure lines serving snack film converters. These energy-cured chemistries eliminate natural gas-fired drying tunnels, cutting line energy intensity by 40-50% while enabling thinner dry-film deposition. European flexible packaging specialists in Italy and Spain are retrofitting existing presses with LED-UV curing modules to capture this operational advantage.
EU REACH restrictions on aromatic amine catalysts are forcing polyurethane primer reformulation toward aliphatic isocyanate adducts with extended pot-life stability. The industrial consequence is elevated raw material cost and reformulated viscosity profiles requiring recalibrated anilox engraving specifications. Retort pouch manufacturers in France and the Netherlands are qualifying these next-generation systems under accelerated aging protocols to maintain shelf-life guarantees.
Specification consolidation among multinational food brands is compressing approved primer vendor lists from 8-12 suppliers to 3-4 strategic partners per converting group. Category managers at these buyers now mandate unified global formulations with regional manufacturing footprints, displacing locally sourced specialty primers. This pattern is most visible in North American and Western European dairy packaging supply chains where Nestlé and Danone have implemented centralized technical approval processes.
Packaging Primers Market Segmentation
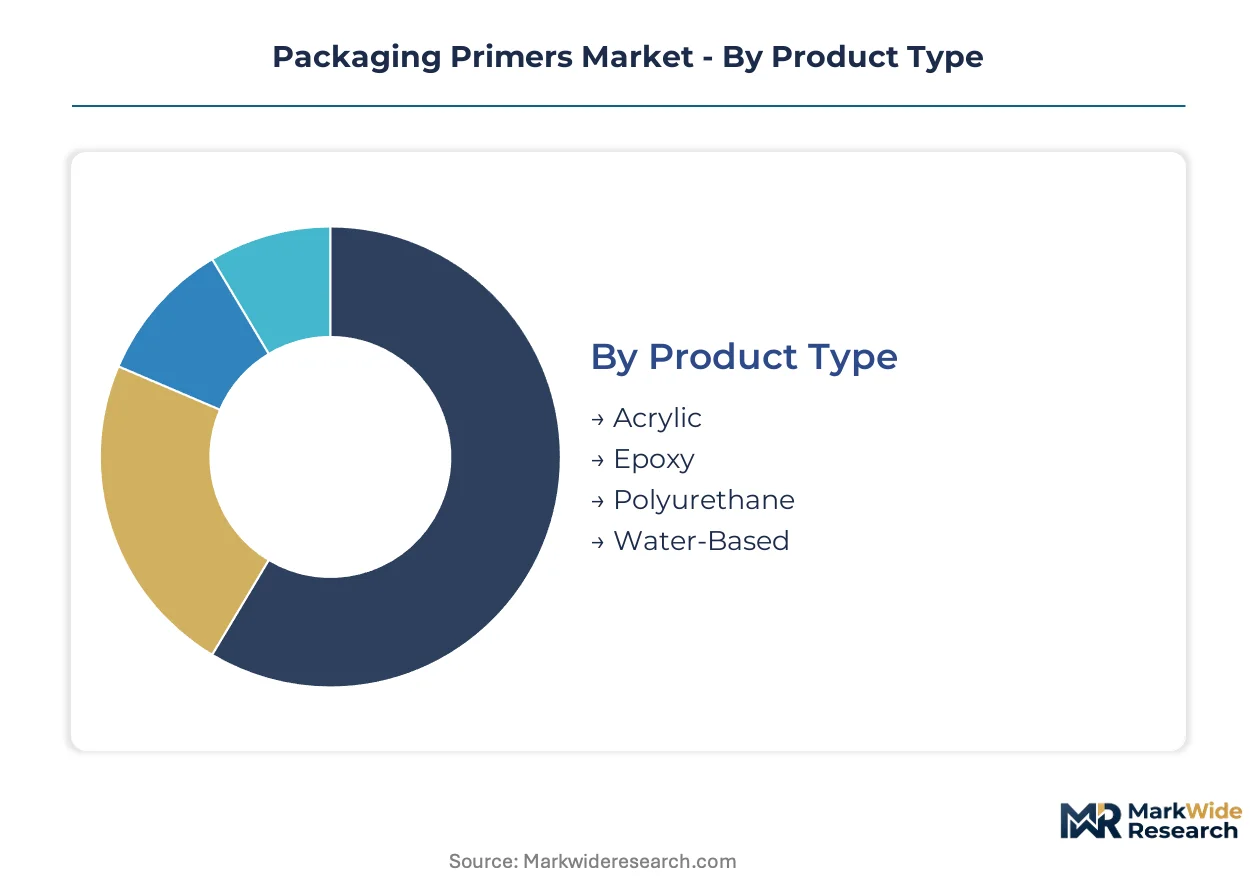
Primer specification varies sharply by substrate chemistry and end-use regulatory exposure. Converters select formulations based on migration limits, sterilization requirements, and line speed constraints rather than unit cost alone.
Product Type:
REACH Annex XVII and FDA food-contact rules split demand between low-migration acrylics and high-performance epoxies.
- Acrylic:Waterborne acrylic dispersions dominate standard flexible packaging with verified low-migration profiles for food-contact laminates. German and US converters specify these for high-speed gravure lines running snack films where thermal drying constraints limit solvent-borne alternatives.
- Epoxy:Two-component epoxy systems bond dissimilar substrates under retort sterilization conditions exceeding 121°C. Demand concentrates in France and the Netherlands where ready-meal pouch manufacturers qualify formulations under accelerated aging protocols.
- Polyurethane:Aliphatic isocyanate adducts replace aromatic-catalyzed systems under EU amine restrictions.
- Water-Based:Emulsion polymers eliminate solvent recovery infrastructure for EPA NESHAP compliance.
Acrylic handles the majority of throughput; water-based formulations are gaining share fastest as converters retrofit legacy lines.
Application:
Migration testing burdens and shelf-life requirements create four distinct specification tiers.
- Food & Beverage:EFSA and FDA notification processes extend qualification timelines. Retort pouches for ready-meals and high-barrier snack films drive epoxy and acrylic specification respectively.
- Personal Care:Cosmetic packaging demands UV-curable primers for digital print compatibility on narrow-web lines serving craft segments.
- Electronics:Anti-static primer systems protect sensitive components during flex circuit lamination.
- Industrial:Heavy-duty adhesive promoters bond metal-to-polymer interfaces in chemical-resistant drum liners.
Food & beverage commands volume leadership; personal care shows the steepest expansion trajectory as digital print adoption accelerates.
End User:
Procurement sophistication varies by integration depth and regulatory exposure.
- Manufacturers:Integrated film producers in Germany, China, and the United States specify primers at the extrusion coating stage.
- Distributors:Regional stockists serve mid-tier converters without backward-integrated resin supply.
- Retailers:Private-label brands mandate approved primer vendor lists from 8-12 suppliers down to 3-4 strategic partners.
- Packaging Companies:Independent converters face $2-4 million per line retrofit costs for aqueous primer conversion.
Manufacturers drive standard-setting; packaging companies are expanding most quickly in India under FSSAI harmonization and PLI incentives.
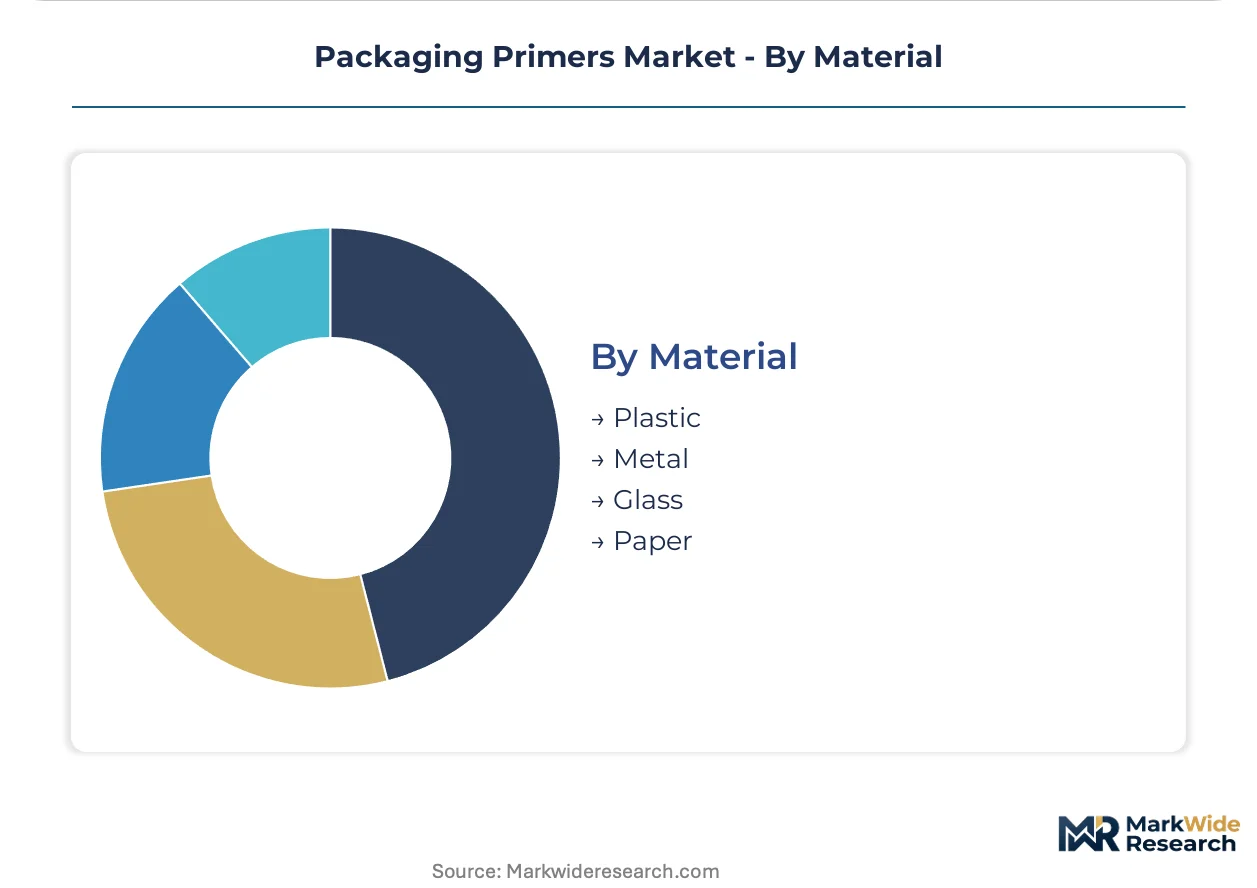
Material:
Surface energy and thermal expansion coefficients dictate primer chemistry selection.
- Plastic:Corona-treated oriented polypropylene requires acrylic primers for aluminum foil lamination in multilayer flexible structures.
- Metal:Coil-coated aluminum for aseptic beverage cartons demands epoxy systems with sterilization resistance.
- Glass:Silane-modified primers bridge organic coatings to inorganic substrates for premium cosmetic bottles.
- Paper:Water-based acrylics enable polyethylene extrusion coating for moisture-resistant folding cartons.
Plastic substrates absorb the highest primer volumes; paper applications are climbing fastest on recyclable packaging mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three German chemical groups control over 60% of global waterborne acrylic resin capacity for packaging primers, concentrating supply vulnerability in Western Europe. Converter demand clusters in Germany, China, and the United States where integrated film production operates at scale.
United States
Flexible packaging converters in the Midwest and Southeast are retrofitting solvent-recovery systems to meet EPA NESHAP standards for hazardous air pollutants. FDA food-contact notification requirements extend qualification timelines for new primer chemistries entering regulated channels. Chicago and Atlanta film production clusters drive specification consolidation among multinational food brands.
Germany
REACH Annex XVII restrictions on isocyanate-containing formulations are pulling investment toward acrylic-urethane hybrids with verified low-migration profiles. Retort pouch manufacturers in Bavaria and North Rhine-Westphalia qualify epoxy systems under accelerated aging protocols for ready-meal applications. Frankfurt and Munich serve as technical approval hubs for centralized European procurement.
China
Domestic flexible packaging buildout in Jiangsu and Zhejiang provinces is absorbing water-based primer capacity as converters eliminate solvent recovery infrastructure. SAMR and GB standards for food-contact materials are tightening migration limits parallel to EU frameworks. Shanghai and Shenzhen film production clusters operate dedicated coating lines for high-barrier snack and pet food formats.
India
FSSAI harmonization with EU migration limits and domestic PLI scheme incentives are attracting primer suppliers to Gujarat and Maharashtra film production clusters. Converters in Ahmedabad and Mumbai face 18-24 month qualification timelines for new food-contact chemistries. Waterborne acrylic dispersions are displacing solvent-borne alternatives as retrofit capital becomes available.
France
Ready-meal pouch manufacturers in the Île-de-France and Auvergne-Rhône-Alpes regions drive epoxy primer demand for sterilization resistance exceeding 121°C. EFSA migration limits determine market access for laminates sold into regulated dairy and beverage packaging channels. Lyon and Paris converting facilities are consolidating approved vendor lists from 8-12 suppliers to 3-4 strategic partners.
Packaging Primers Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized coating suppliers. The vendor base spans three tiers: integrated resin producers with backward control over acrylic backbone supply, independent formulators purchasing specialty monomers on contract, and regional distributors serving mid-tier converters without technical specification capabilities. Strategic moves center on dual-jurisdiction compliance investments and aqueous primer line retrofits for EPA and REACH alignment.
Among European-based chemical groups, BASF SE and Henkel AG & Co. KGaA occupy positions within the integrated resin producer tier, exemplifying archetypes with captive acrylic dispersion capacity. PPG Industries, Inc. anchors the North American supply vector through dedicated coil and packaging coating infrastructure. These three entities represent the dominant competitive anchors as specification consolidation compresses approved vendor lists across multinational food brand supply chains.
| Leading Market Players |
|---|
| BASF SE |
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| DIC Corporation |
| ACTEGA Terra GmbH |
| Henkel AG & Co. KGaA |
| National Paints Factories Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Water-based primer substitution for solvent-borne systems is redrawing supply geography toward Germany and China while compressing formulation margins through acrylic monomer volatility. This chemistry transition simultaneously forces capital deployment into aqueous drying infrastructure and restructures procurement leverage across converter tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates converter procurement, with epoxy retort systems commanding premium positioning against commodity acrylic snack-film grades. Price differentiation hinges on FDA/EFSA certification tier and backward-integrated resin supply. Pricing pressure stems from 2-EHA and butyl acrylate feedstock swings that squeeze spot-market buyers without captive dispersion capacity. Mid-tier converters in India and Southeast Asia exhibit highest price sensitivity, while integrated German and US film producers absorb volatility through long-term monomer contracts.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion elevate landed resin prices for Atlantic-facing converters, particularly for specialty aliphatic isocyanate adducts qualified under EU amine restrictions. Supply concentrates in Germany, China, and the United States, with three German chemical groups anchoring waterborne acrylic backbone capacity. Raw material dependencies span acrylic monomers, epoxy curing agents, and polyurethane catalysts. Single-source vulnerability from force majeure at major resin houses constitutes primary structural risk. Distribution runs through integrated film producers with direct supplier relationships, bypassing regional stockists for high-volume specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII acceleration and UV-curable chemistry maturation are compressing qualification windows and creating asymmetric upside for compliant first-movers. This regulatory-technological inflection rewards dual-jurisdiction formulation capability and aqueous line retrofit readiness.
For Market Incumbents: Shield market position through captive waterborne acrylic resin capacity and parallel FDA-EFSA inventory maintenance. Accelerate qualification of aliphatic isocyanate adducts ahead of aromatic amine phase-outs. Defensive consolidation around technical specification consolidation at Nestlé and Danone-tier accounts protects against mid-tier converter disintermediation.
For New Entrants and Emerging Players: Lead with digital print primer compatibility as the narrow-web craft beverage segment lacks incumbent technical coverage. Target Gujarat and Maharashtra film clusters in India where FSSAI harmonization and PLI incentives reduce qualification friction. White-space capture in mono-material recyclable polypropylene-to-polypropylene bonding systems addresses EU Packaging and Packaging Waste Regulation mandates with limited qualified supplier lists.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin producers with backward acrylic dispersion control over independent formulators. Long-term viability across the projection horizon rests on dual-jurisdiction compliance infrastructure and aqueous line retrofit service capability. Acquisition targets should demonstrate verified low-migration profiles and active SAMR or FSSAI qualification pipelines. The signal to watch is specification consolidation velocity at multinational food brand technical approval hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin | Captive dispersion capacity insulates German and US incumbents from 2-EHA monomer volatility. |
| Aqueous Line Retrofit Service | Converters face $2-4 million per line capital requirements, creating equipment-financing partnership opportunities. |
| Dual-Jurisdiction Formulation Qualification | Parallel FDA and EFSA compliance reduces stranded inventory risk for multinational food brand supply chains. |
| UV-Curable Primer Platform Launch | LED-UV curing modules cut line energy intensity by 40-50% for Italian and Spanish snack film specialists. |
| Mono-Material Bonding System Development | Polypropylene-to-polypropylene primer systems address EU recyclability mandates without aluminum foil interlayers. |
Research Methodology
Initial hypotheses were tested against primary input from flexible packaging converters, resin house R&D directors, regulatory affairs specialists at food-contact material suppliers, and procurement leads at multinational dairy brands, then refined through secondary validation. Sources included EFSA migration limit databases, FDA food-contact notification filings, EPA NESHAP compliance records, customs trade data on acrylic monomer flows, and SEC disclosures from diversified chemical conglomerates. Bottom-up volume estimates from coating line utilization rates were triangulated against top-down market sizing from resin capacity utilization.
Variance decomposition across chemistry type, substrate material, end-use regulatory exposure, and regional production cluster shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro converter capacity expansion plans. Industry-specific inputs incorporated SAMR food-contact standard tightening trajectories, EU REACH Annex XVII amendment timelines, and PLI scheme incentive disbursement patterns in India.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity, acrylic monomer supply stability, or converter retrofit capital availability would require recalibration. Forecasts reflect documented assumptions regarding REACH implementation velocity and FSSAI-EU harmonization completion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Face Stock Films Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Strip Pack Market
Packaging Materials
Collagen Sausage Casings Market