
 Aerosol Packaging Market | 2026-2036
Aerosol Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Packaging Market Analysis
Aluminum is shifting from a premium position to a baseline material across aerosol packaging as lightweighting mandates intensify. Ball Corporation leverages captive aluminum supply to sustain cost advantages in beverage-aerosol crossover formats. Crown Holdings anchors its position through steel recycling infrastructure that competes on circularity credentials with plastic alternatives.
Aerosol packaging denotes pressurized container systems that store and dispense products through a valve-and-actuator mechanism, typically employing hydrocarbon or compressed gas propellants at 2-8 bar operating pressure for controlled particle-size distribution. Personal care applications lead volume throughput due to deodorant and hair-spray ubiquity, while food and beverage aerosols command margin pools owing to barrier-lamination complexity and sterilization-grade material requirements. Aluminum dominates structural share as a material category given its draw-redraw manufacturing compatibility and corrosion resistance against aggressive propellant chemistries.
The EPA regulates volatile organic compound emissions from consumer aerosols under Clean Air Act Title VI, constraining propellant formulation choices for US-manufactured products. REACH and the EU F-Gas Regulation jointly determine import eligibility and material composition standards for European market access, with ECHA substance-of-very-high-concern listings directly affecting valve-seal polymer selections. Stakeholders must monitor evolving propellant-phaseout schedules and pre-approve next-generation compressed gas alternatives before existing formulation licenses expire.
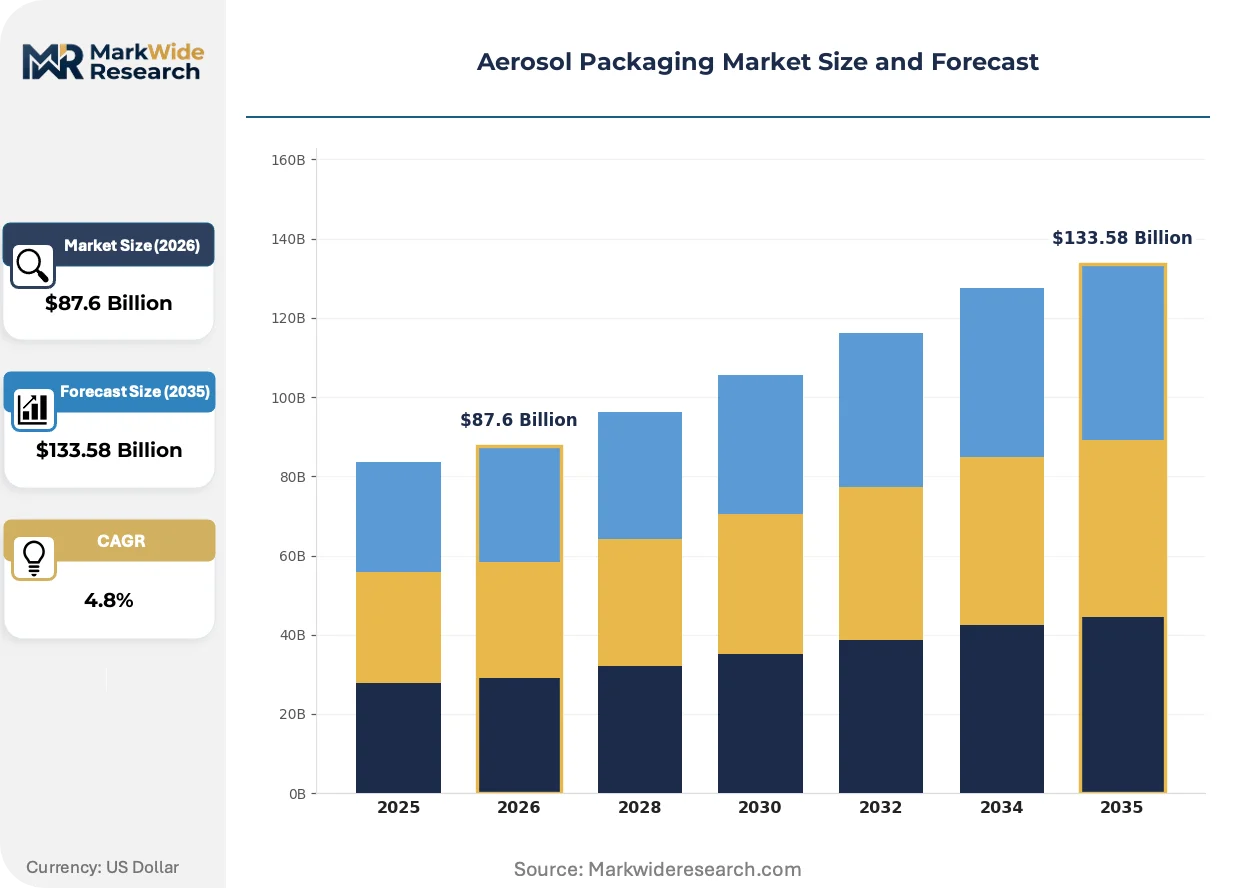
Market Dynamics
Aluminum lightweighting mandates are compressing material hierarchies across aerosol packaging, forcing steel and plastic alternatives to compete on circularity metrics rather than cost alone. This structural pressure redistributes margin pools toward integrated suppliers with captive metal supply chains.
Growth Catalysts
- REACH SVHC listings:European valve-seal polymer restrictions are accelerating fluoropolymer substitution programs, creating pull for next-generation elastomer formulations.
- Compressed gas propellants:Hydrocarbon phaseout timelines under the EU F-Gas Regulation are compressing R&D investment into nitrogen and compressed air dispensing systems.
- São Paulo cosmetics corridor:Brazilian personal care manufacturing concentration is generating localized demand for high-volume aluminum monobloc can supply.
Market Restraints
- Aluminum ingot price volatility:LME aluminum fluctuations transmit directly to can manufacturing cost structures, compressing margin predictability for non-integrated converters.
- Propellant formulation lock-in:EPA Clean Air Act Title VI compliance creates path dependency that slows compressed gas transition timelines for US-manufactured consumer products.
- Steel recycling infrastructure concentration:European steel aerosol circularity depends on fragmented municipal collection systems that fail to guarantee food-grade recycled content streams.
Strategic Opportunities
- Refillable aerosol systems:Latin American personal care brands are piloting deposit-return schemes that separate valve hardware from disposable can bodies.
- Barrier-laminated food aerosols:Sterilization-grade multilayer structures for cooking sprays and whipped cream command margin premiums unavailable in commodity personal care applications.
- EU Green Deal packaging targets:Mandatory recycled content thresholds for 2030 are positioning steel aerosols with verified circularity documentation ahead of virgin aluminum alternatives.
Industry Challenges
- Valve-actuator integration complexity:Precision molding tolerances for next-generation compressed gas valves require capital equipment upgrades that strain mid-cap converters.
- Cross-regulatory compliance staffing:Simultaneous EPA, REACH, and ANVISA filing requirements create bottlenecked approval timelines for multinational product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Packaging Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care, Household, Food & Beverage, Industrial Material: Aluminum, Steel, Plastic, Glass End User: Cosmetics Industry, Food Industry, Chemical Industry, Pharmaceutical Sector Capacity: Small Size, Medium Size, Large Size, Extra Large Size |
| Companies Covered | Ball Corporation, Crown Holdings, Trivium Packaging, Aptar Group Inc., Berry Global, Silgan Holdings, Coster Group, Lindal Group, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Packaging Market Emerging Trajectories
Active propellant chemistry transitions and material lightweighting protocols are restructuring competitive advantage around regulatory anticipation rather than manufacturing scale alone. These forces favor suppliers with integrated formulation and packaging capabilities.
Compressed nitrogen dispensing systems are integrating into personal care aerosol architectures as hydrocarbon propellants face phasedown schedules. European deodorant manufacturers are piloting these systems at pilot-line scale ahead of 2027 compliance deadlines. The technology is integrating quality control protocols that were previously unnecessary for inert hydrocarbon systems, raising barrier-to-entry for contract manufacturers.
The EU F-Gas Regulation is tightening propellant compliance requirements for imports through scheduled hydrofluorocarbon phaseout milestones. This industrial consequence redirects formulation R&D toward compressed gas and dimethyl ether alternatives. Food-grade aerosol applications face the steepest compliance burden, with barrier-laminated structures requiring revalidation against new propellant chemistries.
Buyer consolidation among multinational personal care brands is compressing supplier qualification cycles from multi-year to single-year timelines. Tier-one converters are displacing fragmented regional suppliers through bundled valve-can-actuator procurement contracts. Brazil's cosmetics manufacturing corridor exhibits this concentration most visibly, with São Paulo-based brands consolidating aerosol sourcing among three integrated suppliers.
Aerosol Packaging Market Segmentation
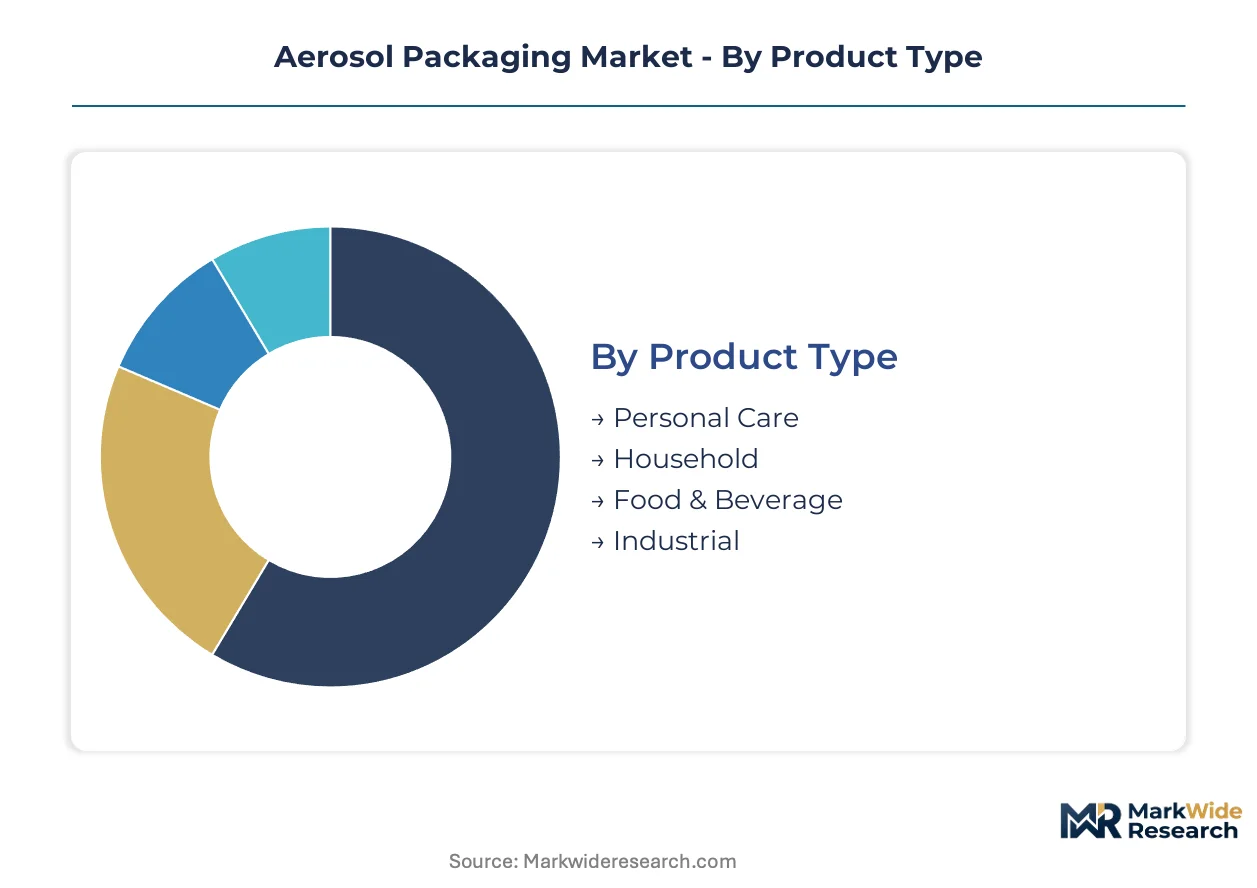
Aerosol packaging segmentation reveals divergent upgrade cycles across material and application categories. Replacement timelines for compressed gas valve systems now compress traditional product refresh windows, forcing converters to align capacity investments with regulatory phaseout schedules rather than consumer demand alone.
Product Type:
Personal care brands in Brazil and Mexico are accelerating reformulation cycles as hydrocarbon propellant deadlines approach, compressing the upgrade window for compatible packaging formats.
- Personal Care:Deodorant and hair-spray applications dominate aluminum monobloc consumption with standardized 150-200ml capacities. São Paulo-based cosmetics manufacturers are consolidating sourcing among integrated valve-can suppliers to secure compressed gas-compatible actuation hardware ahead of ANVISA alignment with EU F-Gas schedules.
- Household:Insecticide and air-freshener aerosols rely on steel tinplate for cost-sensitive volume segments, though barrier-laminated aluminum variants are penetrating premium disinfection sprays. European REACH SVHC restrictions on valve-seal polymers are forcing simultaneous material and propellant transitions that extend qualification timelines.
- Food & Beverage:Cooking sprays and whipped cream demand sterilization-grade multilayer structures with hydrocarbon-compatible barrier laminations.
- Industrial:Lubricant and coating aerosols tolerate higher propellant variability, extending replacement cycles.
Volume placements concentrate in Personal Care; the faster expansion belongs to Food & Beverage as barrier-lamination premiums attract converter investment.
Material:
Cost tier differentiation now tracks circularity verification rather than virgin material pricing alone, with recycled content thresholds restructuring procurement priorities.
- Aluminum:Draw-redraw manufacturing compatibility and corrosion resistance against aggressive propellant chemistries sustain structural dominance. Ball Corporation's captive supply integration insulates beverage-aerosol crossover formats from LME volatility, while independent converters face margin compression during ingot price spikes.
- Steel:Tinplate and TFS substrates compete on EU Green Deal packaging targets through verified recycling documentation. Crown Holdings anchors circularity claims through European steel recycling infrastructure, though fragmented municipal collection systems fail to guarantee food-grade recycled content streams.
- Plastic:PET and barrier-nylon laminations serve niche pharmaceutical applications with transparency requirements.
- Glass:Limited to fragrance and premium cosmetic segments where pressure tolerance constraints exclude propellant dispensing.
Steel commands the steepest circularity premium; aluminum maintains volume leadership through manufacturing flexibility.
End User:
Customer-type procurement patterns diverge between multinational qualification cycles and regional spot-market purchasing.
- Cosmetics Industry:Brazilian and Mexican personal care brands are piloting refillable deposit-return schemes that separate valve hardware from disposable can bodies. Unilever and Natura consolidation in São Paulo compresses supplier qualification timelines from multi-year to single-year windows, favoring bundled valve-can-actuator procurement contracts.
- Food Industry:Sterilization-grade requirements for cooking sprays and whipped cream command margin premiums unavailable in commodity personal care applications. Revalidation against compressed gas and dimethyl ether alternatives imposes the steepest compliance burden under EU F-Gas phasedown milestones.
- Chemical Industry:Industrial lubricant and coating manufacturers tolerate longer propellant transition timelines.
- Pharmaceutical Sector:Inhaler and topical spray applications face FDA and EMA dual filing requirements.
Cosmetics Industry concentrates procurement leverage; Pharmaceutical Sector offers the steepest margin expansion trajectory.
Capacity:
Volume scale determines manufacturing line allocation and propellant transition capital requirements.
- Small Size:Pharmaceutical inhalers and travel-format personal care products require precision valve-actuator integration with compressed gas quality control protocols.
- Medium Size:Standard 150-200ml deodorant and hair-spray formats absorb the majority of aluminum monobloc capacity in Brazil's cosmetics corridor.
- Large Size:Household insecticide and industrial lubricant applications favor steel tinplate for cost-sensitive positioning.
- Extra Large Size:Food-service cooking sprays and bulk industrial coatings face the slowest compressed gas transition adoption.
Medium Size dominates line utilization; Small Size is gaining share fastest through pharmaceutical and premium cosmetic demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone tax incentives concentrate aluminum can manufacturing capacity, drawing integrated suppliers to the northern Amazon basin while São Paulo's cosmetics corridor absorbs the majority of domestic valve-actuator demand.
United States
EPA Clean Air Act Title VI enforcement constrains hydrocarbon propellant formulations for deodorant and hair-spray manufacturers. The agency's volatile organic compound emission limits compress reformulation timelines for consumer product brands. Chicago and New Jersey chemical corridors host compressed gas propellant R&D facilities serving North American aerosol converters.
Germany
ECHA REACH substance-of-very-high-concern listings accelerate fluoropolymer substitution in valve-seal polymers for personal care applications. The EU F-Gas Regulation's hydrofluorocarbon phaseout redirects formulation investment toward dimethyl ether alternatives. Cologne's packaging technology cluster houses testing laboratories validating next-generation compressed gas dispensing systems.
Brazil
ANVISA alignment with EU F-Gas schedules compresses supplier qualification windows for São Paulo-based cosmetics manufacturers. The regulator's propellant compliance timelines force simultaneous material and hardware transitions. The São Paulo cosmetics manufacturing corridor concentrates demand for high-volume aluminum monobloc can supply among three integrated valve-can suppliers.
China
MIIT lightweighting mandates for consumer packaging accelerate draw-redraw aluminum can capacity expansion. GB standards for pressurized container safety impose testing protocols that extend qualification timelines for imported valve-actuator hardware. Yangtze River Delta manufacturing zones host domestic aerosol component fabrication serving Asian personal care brands.
India
BIS certification requirements for pressurized containers create entry barriers for imported aerosol packaging formats. The PLI scheme for specialty chemicals attracts propellant formulation investment to Gujarat chemical parks. Maharashtra's industrial corridor concentrates contract manufacturing for deodorant and household insecticide brands serving domestic and export markets.
Aerosol Packaging Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated metal suppliers commanding personal care volume and independent converters capturing niche pharmaceutical and food-grade applications. The vendor base organizes around three strategic archetypes: captive aluminum producers with beverage crossover capabilities, steel circularity specialists with European recycling infrastructure, and precision valve-actuator engineers serving compressed gas transitions. Consolidation pressure intensifies as multinational personal care brands compress supplier qualification cycles from multi-year to single-year timelines. Geographic expansion and bundled procurement contracts represent the dominant competitive moves, with tier-one converters displacing fragmented regional suppliers through integrated valve-can-actuator offerings.
Among North American metal packaging specialists, Ball Corporation and Crown Holdings exemplify divergent material strategies. Ball Corporation's captive aluminum supply insulates beverage-aerosol crossover formats from LME volatility, while Crown Holdings anchors circularity positioning through European steel recycling infrastructure. Trivium Packaging occupies a position between these archetypes with dual-material capabilities serving regional brand requirements.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Trivium Packaging |
| Aptar Group Inc. |
| Berry Global |
| Silgan Holdings |
| Coster Group |
| Lindal Group |
| CCL Industries |
| Others |
Supply Flow & Price Mechanics
LME aluminum ingot volatility transmits directly through draw-redraw can manufacturing cost structures, compressing margin predictability for independent converters while integrated suppliers with captive metal supply buffer tier-one pricing from spot-market turbulence. This upstream cost dynamic stratifies procurement leverage across personal care brand archetypes, with São Paulo-based cosmetics manufacturers consolidating volumes to extract contract-based stability against commodity-indexed spot purchases.
Pricing Analysis
Short lead-time premiums compress standard contract differentials as ANVISA alignment deadlines accelerate compressed gas valve-actuator procurement cycles. Three-tier pricing structure across premium sterilization-grade, standard personal care, and economy household segments tracks barrier-lamination complexity and circularity certification rather than virgin material cost alone. Pricing pressure stems from hydrocarbon propellant phaseout timelines forcing simultaneous hardware and formulation revalidation investments. Multinational cosmetics brands exhibit lowest price sensitivity given bundled valve-can-actuator procurement contracts; regional household insecticide manufacturers face acute margin compression during aluminum ingot spikes.
Supply Chain Analysis
Direct-to-OEM channels handle compressed gas valve-actuator demand from São Paulo's consolidated cosmetics manufacturers, while distributor networks serve fragmented regional household brands. Primary aluminum smelting concentrates in Brazil, China, and Russia; valve-actuator precision molding anchors in Germany and China. Raw material dependencies span LME-traded aluminum ingot, fluoropolymer elastomer formulations, and tinplate steel substrates. Single-source vulnerability concentrates in European fluoropolymer substitution programs as REACH SVHC listings accelerate next-generation seal material transitions. Distribution runs through integrated converter direct contracts for tier-one personal care volumes and spot-market intermediaries for industrial lubricant applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive aluminum supply and in-house valve-actuator engineering capabilities determine pricing power and qualification cycle capture.
For Market Incumbents: Cement aluminum supply security through long-term offtake agreements with Brazilian smelters or backward integration into recycling infrastructure, insulating against LME volatility that compresses independent converter margins. Deepen compressed gas valve engineering capabilities ahead of EU F-Gas and ANVISA alignment deadlines, as hydrocarbon propellant phaseouts accelerate hardware replacement cycles and disqualify non-integrated suppliers from bundled procurement contracts. For New Entrants and Emerging Players: Mid-cap Brazilian cosmetics brands underserved by the three integrated São Paulo suppliers present white-space entry points through flexible minimum-order-quantity contracts and ANVISA pre-approval investment. Barrier-laminated food aerosol segments command sterilization-grade margin premiums with less consolidated buyer power than personal care; target cooking spray and whipped cream applications with compressed gas-compatible multilayer validation capabilities as the fastest-penetrable niche. For Investors and Strategic Acquirers: Distressed-cycle entries favor European steel aerosol specialists with verified circularity documentation ahead of EU Green Deal recycled content thresholds, as fragmented municipal collection systems strain food-grade recycled content guarantees and compress valuations for non-integrated tinplate converters. Monitor ECHA substance-of-very-high-concern listing announcements as inflection indicators for fluoropolymer-dependent valve-seal manufacturers facing accelerated substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Supply Integration | Ball Corporation's upstream control insulates beverage-aerosol crossover formats from LME volatility that strains independent converters. |
| Compressed Gas Valve Engineering Investment | Precision molding capabilities for nitrogen dispensing systems qualify suppliers for EU F-Gas and ANVISA-aligned procurement contracts. |
| Steel Recycling Infrastructure Expansion | Crown Holdings' European circularity documentation positions tinplate aerosols ahead of EU Green Deal recycled content mandates. |
| Refillable System Pilot Programs | Latin American deposit-return schemes separate valve hardware from disposable can bodies, extending customer lifetime value. |
| Barrier-Laminated Food Aerosol Validation | Sterilization-grade multilayer structures for cooking sprays command margin premiums unavailable in commodity personal care applications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of aerosol converter plant managers, personal care brand procurement leads, valve-actuator R&D directors, and ANVISA regulatory affairs specialists. Bottom-up volume modeling triangulated against top-down aluminum can consumption data from metal packaging associations and propellant formulation disclosures under EPA Clean Air Act Title VI and EU F-Gas Regulation compliance databases.
Segment-level granularity modeled material tiers, application categories, capacity formats, and end-user procurement patterns across the projection horizon. CAGRs derived from regression analysis of historical aluminum can shipment data and regulatory phaseout schedule impacts on replacement cycle compression. Industry-specific forecast inputs incorporated REACH SVHC listing timelines and ANVISA alignment milestones with EU F-Gas schedules.
Revisions become necessary when ECHA substance-of-very-high-concern listings accelerate beyond modeled fluoropolymer substitution timelines, or when LME aluminum volatility exceeds historical bands and compresses independent converter viability assumptions. Practitioners should monitor ANVISA propellant compliance announcements and EU Green Deal recycled content threshold clarifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Bulb Packaging Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Desiccant Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Strip Pack Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
EPE Liner Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Global Anti-Static Films Market