
 Finish Foils Market | 2026-2036
Finish Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Finish Foils Market Analytics
Modular surface finishing is rebalancing how OEMs procure decorative layers, shifting from in-house coating to pre-finished foil supply. Schattdecor leverages vertical integration across base paper and impregnation to control cost and color consistency. SURTECO Group anchors European demand through dedicated logistics hubs serving furniture clusters. Interprint competes via digital print infrastructure that shortens design-to-production cycles for batch-one customization.
Finish foils are thin decorative laminates, typically 30–80 micrometers, composed of printed and lacquered paper or polymer substrates that bond to MDF, particleboard, or plastic profiles through heat and pressure activation. Their primary purpose is to deliver abrasion-resistant, chemically stable surface aesthetics without the material cost or processing energy of solid wood or metal veneers. Cold foil commands the volume lead in packaging applications where inline application on offset presses eliminates tooling setup, while hot stamping foil retains margin concentration in cosmetics and premium spirits where tactile embossing and holographic security features justify higher unit economics. Specialty foil, encompassing conductive and barrier-functional variants, represents the fastest-expanding category as electronics manufacturers adopt foil-based electromagnetic shielding for consumer devices.
REACH in Europe and GB standards in China restrict phthalate plasticizers and heavy metal pigments in decorative foil formulations, forcing reformulation investments that favor suppliers with captive chemical testing laboratories. FDA indirect food contact rules in the United States govern foil migration limits for food and beverage packaging substrates, creating compliance thresholds that exclude smaller regional converters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
Modular surface finishing is dismantling traditional in-house coating operations as OEMs outsource decorative layer production to specialized foil converters with captive impregnation lines and digital print infrastructure.
Growth Catalysts
- GB standards evolution:China's tightening chemical composition rules for decorative substrates are accelerating domestic reformulation investments, creating captive demand for compliant foil supply chains serving kitchen and furniture manufacturers.
- Electronics shielding adoption:Conductive foil variants are displacing metal enclosures in consumer device electromagnetic interference management, with specialty converters scaling barrier-functional production lines.
- Germany automotive integration:Specialized converters in Baden-Württemberg and Bavaria maintain direct supply relationships with interior trim OEMs, anchoring premium foil demand through just-in-time logistics hubs.
Market Restraints
- Titanium dioxide volatility:Pigment cost swings in decorative paper formulations compress converter margins during contract renegotiation cycles with furniture manufacturers.
- Base paper supply concentration:European specialty paper mills in Finland and Sweden control critical substrate supply, exposing foil printers to force majeure risks during pulp production disruptions.
- Phthalate substitution complexity:REACH-mandated plasticizer phase-outs require multi-year reformulation timelines that strand non-compliant inventory in cross-border distribution.
Strategic Opportunities
- India furniture manufacturing:PLI scheme incentives for domestic wood processing are attracting foil converters to establish impregnation facilities near emerging particleboard clusters in Gujarat and Punjab.
- Digital print convergence:Drop-on-demand inkjet systems integrated with lacquering lines enable batch-one customization for interior design studios, collapsing design-to-delivery cycles from weeks to days.
- Cold foil packaging expansion:Inline application systems on narrow-web flexo presses are penetrating craft beverage and specialty food segments previously served by hot stamping.
Industry Challenges
- Colorimetric calibration expertise:Delta-E control across heat-activated bonding processes requires specialized technicians that converter training programs struggle to produce at scale.
- Migration testing infrastructure:FDA indirect food contact certification demands capital-intensive laboratory equipment that excludes smaller regional players from beverage packaging supply chains.
- Legacy press integration:Retrofitting digital front-ends onto existing gravure lines for hybrid production creates workflow friction and quality consistency gaps during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finish Foils Market |
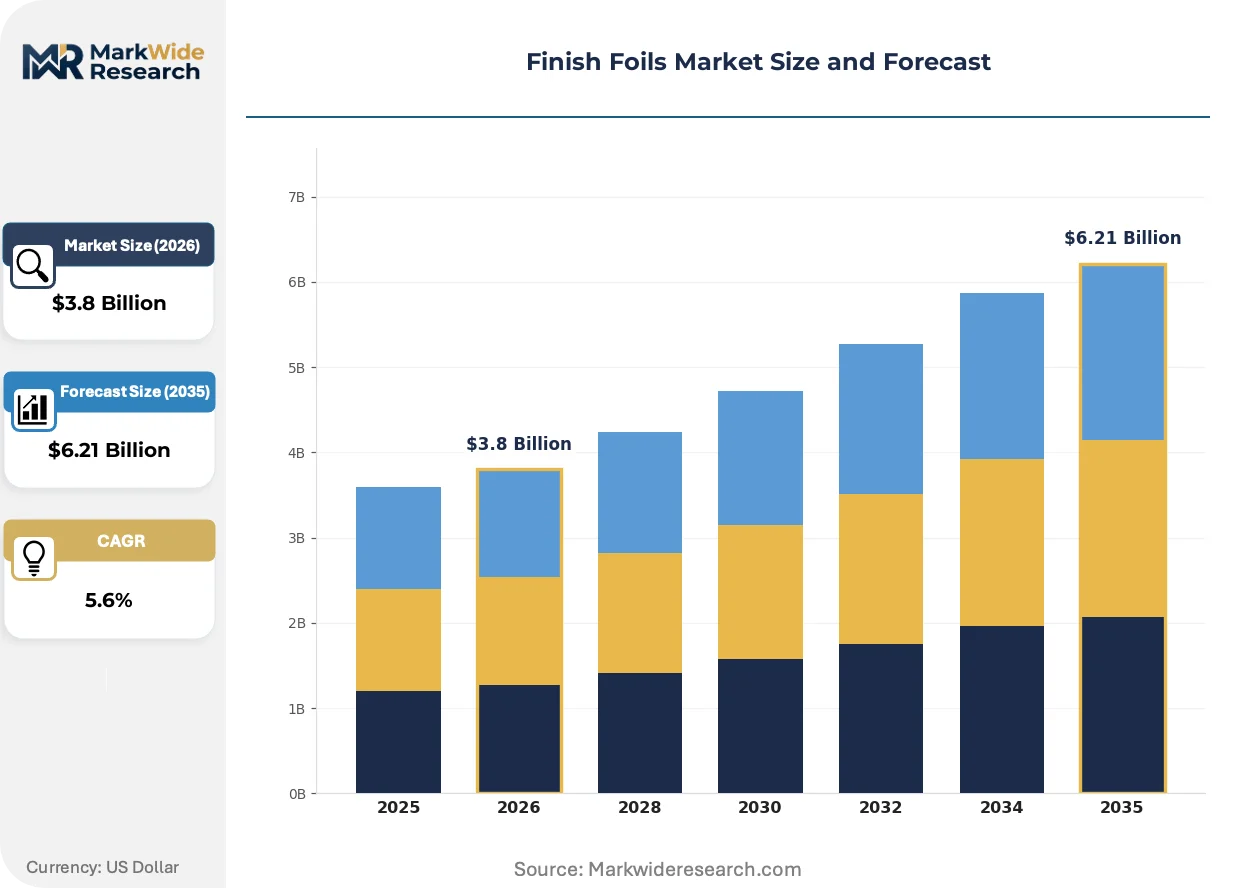
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Foil, Hot Stamping Foil, Transfer Foil, Specialty Foil Material: Polyester, Polypropylene, PET, Paper End User: Packaging, Printing, Labeling, Decorative Arts Application: Cosmetics, Food & Beverages, Electronics, Pharmaceuticals |
| Companies Covered | Ahlstrom-Munksjo, Schattdecor, SURTECO Group, Interprint, Neodecortech, Toppan Holdings Inc, Taghleef Industries, Kronoplus Limited, Brushfoil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finish Foils Market Evolving Landscape
Finish foil production is bifurcating between mass-customization digital infrastructure and high-throughput gravure systems, with technology choices locking converters into distinct competitive postures for the next equipment lifecycle.
Water-based UV-curable lacquers are rewriting surface durability standards for decorative laminates. Kitchen cabinet manufacturers in Germany and Austria are specifying these formulations for high-humidity environments. The technology is compressing solvent-based coating market share in premium furniture segments where emission regulations tighten fastest.
REACH authorization procedures for chromium-based pigments are forcing decorative paper printers toward complex inorganic alternatives. The industrial consequence is extended color-matching timelines and higher raw material minimum order quantities. Automotive interior suppliers in the EU are absorbing these costs through long-term supply agreements that lock in reformulated specifications.
Design studios are consolidating vendor relationships around converters offering integrated sampling-to-production workflows. Traditional specification through separate design agencies and material brokers is contracting in favor of direct digital collaboration platforms. This concentration is most visible in Netherlands and Denmark residential furniture markets where lead-time compression determines contract awards.
Finish Foils Market Segmentation
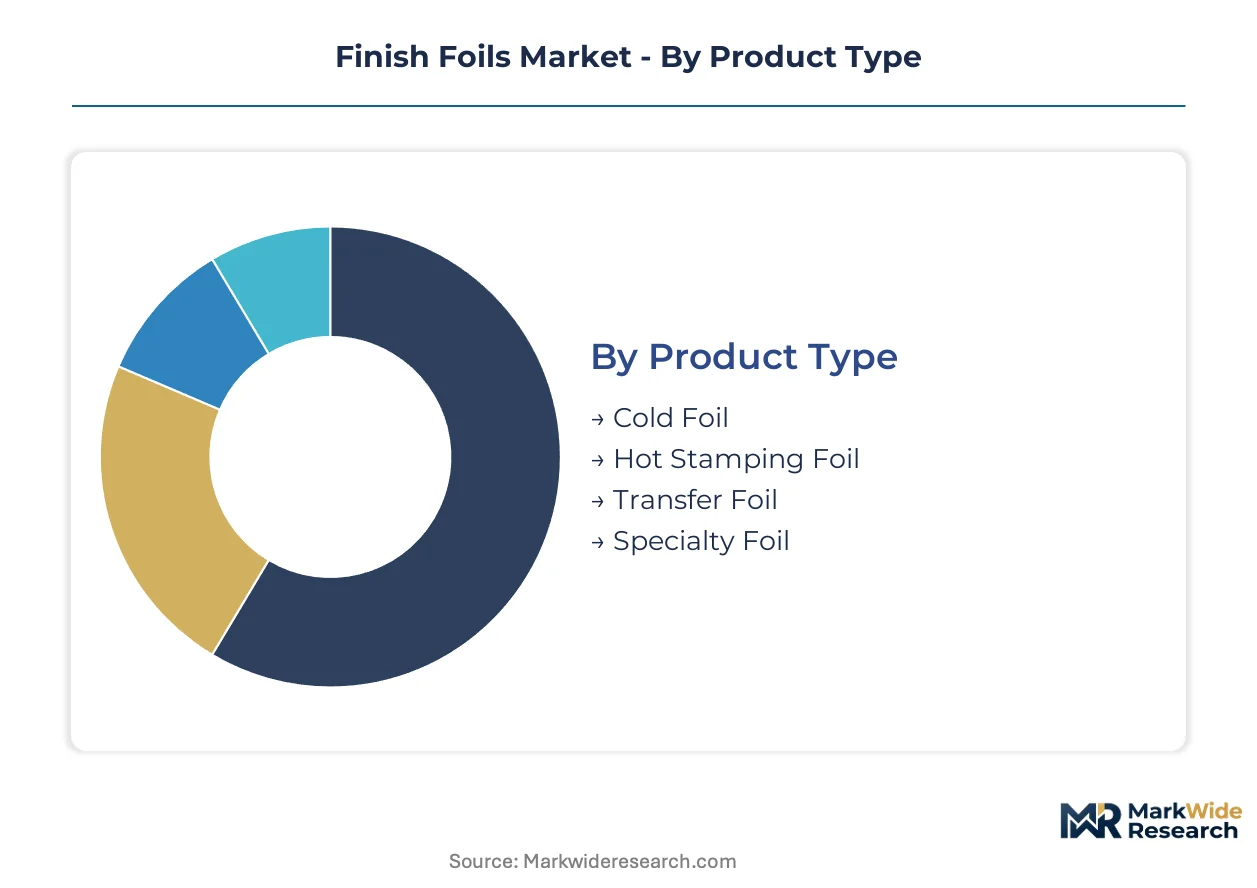
Finish foil procurement patterns diverge sharply between high-volume packaging converters and precision-driven specialty manufacturers. Understanding these segment boundaries clarifies where margin pools concentrate versus where scale economics dominate competitive positioning.
Product Type:
Cold foil commands volume leadership through inline application efficiency, while hot stamping foil anchors premium positioning via tactile differentiation capabilities.
- Cold Foil:Thin metallic or pigmented layers applied without heat through adhesive transfer on offset and flexo presses. Demand concentrates in folding carton converters serving craft beverage brands in Germany and the United States, driven by elimination of stamping dies and setup waste.
- Hot Stamping Foil:Carrier-backed films requiring heated dies for transfer, enabling precise embossing and holographic security elements. Cosmetic packaging houses in France and Switzerland specify these formulations for premium fragrance and skincare lines where tactile surface quality justifies unit cost premiums.
- Transfer Foil:Decal-based systems for three-dimensional substrate coverage. Automotive interior trim suppliers in Bavaria utilize these for curved dashboard components.
- Specialty Foil:Functional variants including conductive, barrier, and temperature-sensitive formulations. Electronics manufacturers in South Korea and Japan are scaling shielding-grade production for consumer device electromagnetic interference management.
Mature deployment sits with cold foil in high-throughput packaging. Newer deployment is concentrated in specialty foil for electronics shielding applications.
Material:
Substrate selection tracks end-use durability requirements, with polymer films dominating moisture-critical applications and paper substrates retaining cost-sensitive decorative segments.
- Polyester:High tensile strength and thermal stability for demanding lamination cycles. REACH-compliant formulations from Finnish mills supply kitchen cabinet manufacturers in Austria and Germany facing humidity exposure specifications.
- Polypropylene:Lower density and improved flexibility for conformable label applications. Italian wine label converters specify biaxially oriented grades for bottle contour adhesion.
- PET:Optical clarity and barrier properties for electronics and pharmaceutical blister packs. Japanese pharmaceutical packaging regulations favor PET substrates for moisture-sensitive drug protection.
- Paper:Cellulose-based carriers for decorative laminates and cost-optimized packaging. Swedish specialty paper mills control premium base paper supply for furniture foil impregnation lines.
Backward integration into base paper production favors established European converters. Polymer film supply chains concentrate with petrochemical processors in Asia-Pacific manufacturing hubs.
End User:
Customer type determines specification complexity, with packaging converters driving standardization and decorative arts buyers demanding batch-level customization.
- Packaging:Folding carton, flexible film, and rigid container manufacturers. German automotive parts suppliers specify abrasion-resistant foils for under-hood component identification labels.
- Printing:Commercial print houses and security document producers. Dutch currency and passport printers utilize holographic hot stamping foils with centralized government procurement.
- Labeling:Pressure-sensitive and in-mold label converters. Indian pharmaceutical exporters require FDA-compliant migration-tested foils for US-bound generic drug packaging.
- Decorative Arts:Furniture, interior design, and architectural surface specialists. Danish residential furniture studios are consolidating vendor relationships around digital sampling-to-production workflows.
Specification authority rests with packaging procurement teams. Design influence concentrates with decorative arts studios specifying aesthetic outcomes.
Application:
End-use verticals impose distinct regulatory and performance thresholds, with food contact and pharmaceutical applications demanding certified migration compliance.
- Cosmetics:Premium packaging for fragrance, skincare, and color cosmetics. French luxury houses specify tactile embossed foils with metallic luster for shelf differentiation.
- Food & Beverages:Direct and indirect food contact packaging substrates. FDA indirect food contact rules govern foil migration limits for US-bound craft beverage can labels.
- Electronics:Electromagnetic shielding, thermal management, and circuit protection. Chinese consumer device manufacturers are adopting conductive foil barriers under MIIT electromagnetic compatibility directives.
- Pharmaceuticals:Blister packs, compliance packaging, and anti-counterfeiting elements. EMA serialization requirements drive holographic security foil adoption for European prescription drug packaging.
Regulatory certification burdens favor large converters with captive testing laboratories. Smaller regional players face exclusion from food and pharmaceutical supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Punjab are concentrating foil converter investments as India's PLI scheme for wood processing matures. These designated manufacturing corridors offer accelerated depreciation and duty exemptions that reduce capital recovery timelines for impregnation facilities.
Germany
Automotive interior trim specifications from Bavarian OEMs sustain premium foil demand through just-in-time logistics hubs in Baden-Württemberg. REACH authorization procedures for chromium-based pigments force extended color-matching timelines across automotive supply chains. Specialized converters in Stuttgart and Munich maintain direct supply relationships with tier-one interior component manufacturers.
China
MIIT electromagnetic compatibility directives accelerate conductive foil adoption for consumer device shielding applications. Evolving GB standards for decorative substrates mandate phthalate-free formulations that strand non-compliant inventory in cross-border distribution. Manufacturing clusters in Guangdong and Zhejiang provinces are scaling barrier-functional production lines for electronics OEMs.
United States
FDA indirect food contact rules govern foil migration limits for craft beverage can labels and flexible food packaging. Folding carton converters in Wisconsin and Pennsylvania specify cold foil systems to eliminate stamping die setup waste. Regional players face capital-intensive laboratory equipment requirements that exclude smaller converters from certified supply chains.
India
PLI scheme incentives for domestic wood processing attract foil converters to establish impregnation facilities near emerging particleboard clusters. BIS certification requirements for decorative laminates create compliance thresholds that favor integrated producers with captive testing infrastructure. Gujarat and Punjab manufacturing corridors concentrate new capacity investments closest to raw material sourcing nodes.
Japan
METI industrial standards for electronics packaging drive PET substrate specifications for moisture-sensitive pharmaceutical protection. Pharmaceutical blister pack manufacturers in Osaka and Tokyo prefectures favor holographic security foils under serialization mandates. Domestic converters maintain specialized barrier-functional production lines for regional device OEMs.
Finish Foils Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated base paper producers controlling upstream substrate supply, digital print specialists compressing design-to-production cycles, and functional foil developers serving electronics shielding applications. Dominant competitive moves include backward integration into impregnation lines and strategic partnerships with furniture OEMs for captive specification authority.
Among European-integrated producers, Schattdecor exemplifies the captive supply archetype through base paper and impregnation control, while SURTECO Group anchors logistics proximity to furniture manufacturing clusters. Interprint occupies a position within the digital infrastructure tier, representing batch-one customization capabilities for design studio workflows. These three players illustrate how technology choices lock converters into distinct competitive postures across equipment lifecycles.
| Leading Market Players |
|---|
| Ahlstrom-Munksjo |
| Schattdecor |
| SURTECO Group |
| Interprint |
| Neodecortech |
| Toppan Holdings Inc |
| Taghleef Industries |
| Kronoplus Limited |
| Brushfoil |
| Others |
Value Network & Pricing Analysis
Digital print infrastructure adoption is simultaneously compressing design-to-production cycle costs and concentrating specification authority among converters with integrated sampling workflows. This technology shift rewards capital-intensive players while marginalizing regional brokers dependent on legacy gravure economics.
Pricing Analysis
Short lead-time premiums command pricing power in decorative arts segments where Danish furniture studios collapse design-to-delivery cycles from weeks to days. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA-compliant migration-tested foils capturing margin concentration in pharmaceutical packaging. Cost compression in standard-grade decorative laminates is intensifying because titanium dioxide volatility squeezes converter margins during contract renegotiations. Packaging converters exhibit highest price sensitivity due to commoditized cold foil specifications, while automotive interior trim buyers prioritize colorimetric consistency over unit cost.
Supply Chain Analysis
Reverse logistics for reformulated inventory stranded by REACH-mandated phthalate phase-outs creates working capital drag across European distribution networks. Geographic supply concentration centers on Finland and Sweden for specialty base paper, Germany for automotive-grade converters, and China for barrier-functional polymer films. Raw material dependencies draw from titanium dioxide pigments, phthalate-free plasticizers, and chromium-based pigment alternatives. Single-source vulnerability sits with European specialty paper mills controlling critical substrate supply. Distribution runs through just-in-time logistics hubs serving furniture manufacturing clusters in Baden-Württemberg and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH authorization procedures for chromium-based pigments erect barrier-to-entry moats favoring converters with captive chemical testing laboratories.
For Market Incumbents: To counter margin erosion from titanium dioxide volatility, Schattdecor and SURTECO Group should deepen backward integration into base paper production while locking long-term supply agreements with automotive OEMs that absorb reformulation costs through specification premiums. Certification investment in FDA-compliant migration testing infrastructure excludes smaller regional competitors from beverage packaging supply chains.
For New Entrants and Emerging Players: Capture white-space opportunity in India's PLI scheme corridors where Gujarat and Punjab manufacturing clusters lack integrated impregnation facilities near emerging particleboard production. Target digital print convergence for batch-one customization workflows serving Netherlands and Denmark residential furniture studios. Go-to-market angle should emphasize integrated sampling-to-production platforms that collapse lead times for design-driven buyers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified materials conglomerates seeking decorative surface exposure. Long-term viability favors converters with hybrid digital-gravure production flexibility and captive regulatory compliance infrastructure. The signal to watch is MIIT electromagnetic compatibility directive enforcement accelerating conductive foil adoption for Chinese consumer device manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Paper Production | Finnish and Swedish specialty paper mills control substrate supply critical to foil impregnation economics. |
| Digital Print Infrastructure Deployment | Drop-on-demand inkjet systems enable batch-one customization for Danish and Netherlands furniture studios. |
| FDA Migration Testing Laboratory Investment | Capital-intensive certification requirements exclude regional converters from craft beverage can label supply chains. |
| Conductive Foil Production Line Scaling | MIIT electromagnetic compatibility directives in China accelerate barrier-functional adoption for device shielding. |
| Just-in-Time Logistics Hub Expansion | Baden-Württemberg and Bavaria hubs anchor premium automotive interior trim specifications through proximity. |
Research Methodology
Independent corroboration across converter procurement directors, furniture OEM specification engineers, and regulatory compliance officers underwrites the qualitative findings presented in this analysis. Primary fieldwork engaged technical R&D directors at impregnation facilities, distribution channel partners serving kitchen manufacturing clusters, and plant managers at specialty paper mills. Secondary validation drew from ECHA REACH authorization databases, BIS certification registries for Indian decorative laminates, and customs trade data tracking base paper flows. Bottom-up demand modeling triangulated against top-down production capacity assessments across European and Asia-Pacific manufacturing hubs.
Rate-of-change decomposition across product type, material substrate, end-user vertical, and application sector generates segment-specific growth trajectories over the projection horizon. The analytical framework models cold foil, hot stamping foil, transfer foil, and specialty foil demand separately, with electronics shielding applications treated as a distinct growth vector. CAGRs derive from installed equipment capacity, regulatory compliance timelines, and design studio procurement pattern shifts. Industry-specific forecast inputs include REACH authorization procedure timelines for chromium-based pigment alternatives and PLI scheme disbursement schedules for Indian wood processing investments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium dioxide supply disruptions, REACH plasticizer substitution complexity, and MIIT electromagnetic compatibility enforcement intensity. Practitioners should monitor GB standards evolution in China, FDA indirect food contact rule revisions, and automotive interior trim specification shifts toward water-based UV-curable lacquers for early signals of trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Composite Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Card Films Market
Packaging Materials
Fanfold Market
Packaging Materials
United States Single Use Packaging Market