
 US Packaging Market | 2026-2036
US Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Packaging Market Insights
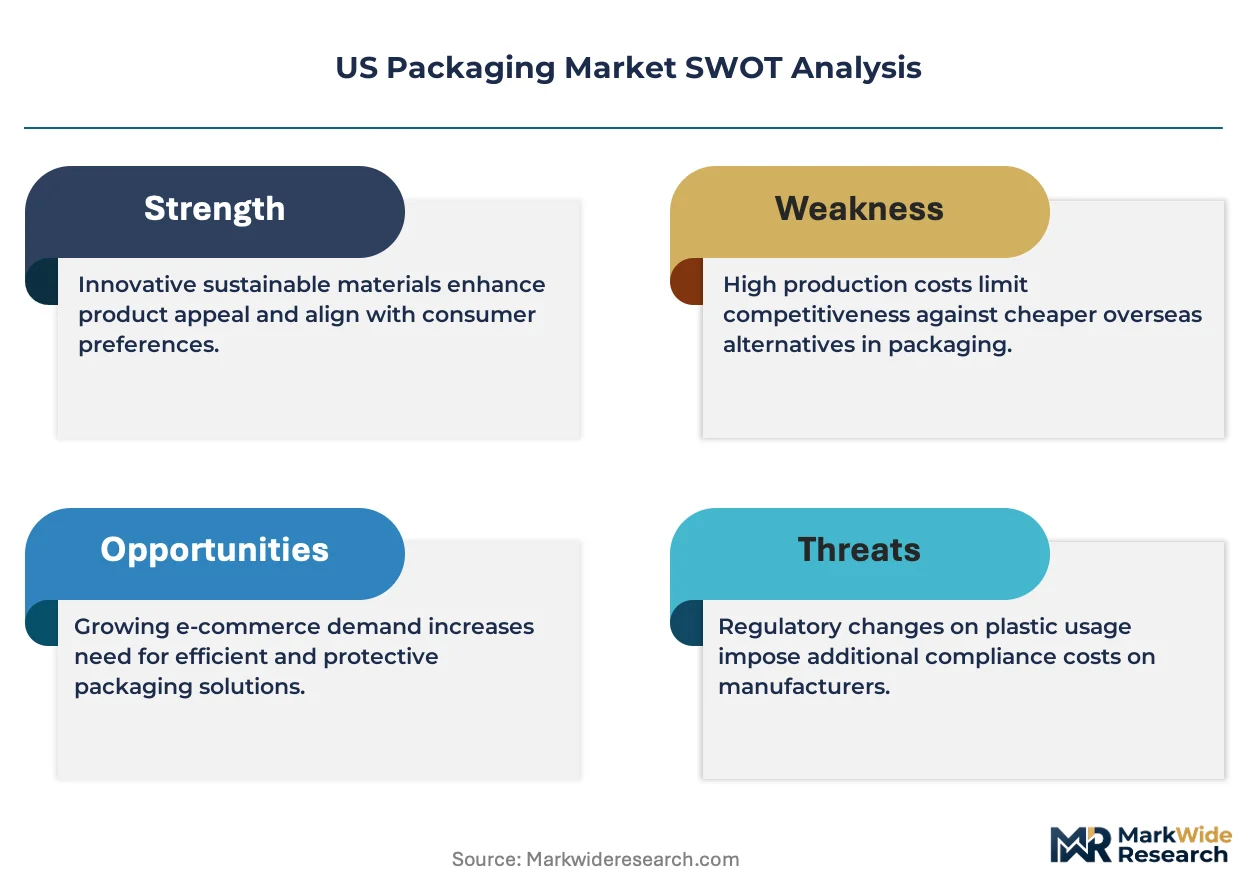
Smart packaging integration with QR-enabled traceability and temperature-sensitive indicators is tilting capital allocation across the sector. WestRock leverages its corrugated automation network to serve e-commerce fulfillment centers with precision-cut protective designs. International Paper Co. sustains massive containerboard capacity across the Southeastern mill corridor. Berry Global specializes in multi-layer flexible films for pharmaceutical barrier applications.
Packaging encompasses engineered enclosures manufactured from paper, plastic, glass, or metal substrates, designed to protect, preserve, transport, and inform across supply chains; specifications include burst strength, moisture vapor transmission rates, and migration limits for food-contact materials. Flexible packaging commands expanding share in snack and frozen food segments due to lightweighting and shelf-life extension properties. Rigid plastic bottles dominate beverage and personal care dispensing formats where dimensional stability and resealability matter. Glass containers retain premium positioning in spirits and craft segments where inertness and recyclability signal quality.
The EPA regulates recycled fiber content under Comprehensive Procurement Guidelines while OSHA sets workplace exposure limits for adhesive and solvent operations in converting facilities. State-level extended producer responsibility frameworks in California, Oregon, and Maine are shifting cost accountability upstream to brand owners and converters. Stakeholders must monitor how post-consumer resin qualification standards and right-to-repair packaging disclosure rules reshape material specifications and capital deployment priorities.
Market Dynamics
EPA recycled content mandates and state-level extended producer responsibility laws are forcing converters to reengineer material specifications and capital deployment timelines across corrugated and flexible film operations.
Growth Catalysts
- E-commerce fulfillment expansion:Protective corrugated demand concentrates in California and Texas logistics hubs where automated sortation systems require precision-cut protective designs.
- Smart packaging integration:QR-enabled traceability and temperature-sensitive indicators are digitizing quality assurance protocols for pharmaceutical and perishable supply chains.
- Extended Producer Responsibility frameworks:California, Oregon, and Maine regulations shift cost accountability upstream to brand owners, accelerating post-consumer resin qualification investments.
Market Restraints
- Containerboard supply concentration:Southeastern mill corridor dominance creates vulnerability to pulp fiber cost volatility and transportation bottlenecks.
- Multi-layer flexible film technical limitations:Current mechanical recycling infrastructure cannot separate incompatible polymer layers, constraining circularity claims.
- OSHA workplace exposure compliance:Adhesive and solvent operations in converting facilities face escalating monitoring costs and engineering control mandates.
Strategic Opportunities
- Pharmaceutical barrier applications:Multi-layer flexible films with migration limit compliance capture shelf-life extension contracts from generic drug manufacturers.
- Right-to-repair packaging disclosure rules:Emerging state mandates create first-mover advantage for converters integrating disassembly instructions and material provenance data.
- Temperature-sensitive indicator convergence:Integration of printed electronics with conventional substrates enables premium positioning in cold-chain logistics.
Industry Challenges
- Post-consumer resin qualification timelines:FDA food-contact notification processes for recycled content extend 18-24 months, delaying product launches.
- Legacy ERP integration with traceability platforms:Smart packaging data streams require middleware development that strains mid-tier converter IT budgets.
- Migration limit testing capacity:Third-party laboratory bottlenecks for food-contact compliance certification extend go-to-market schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Packaging Market |
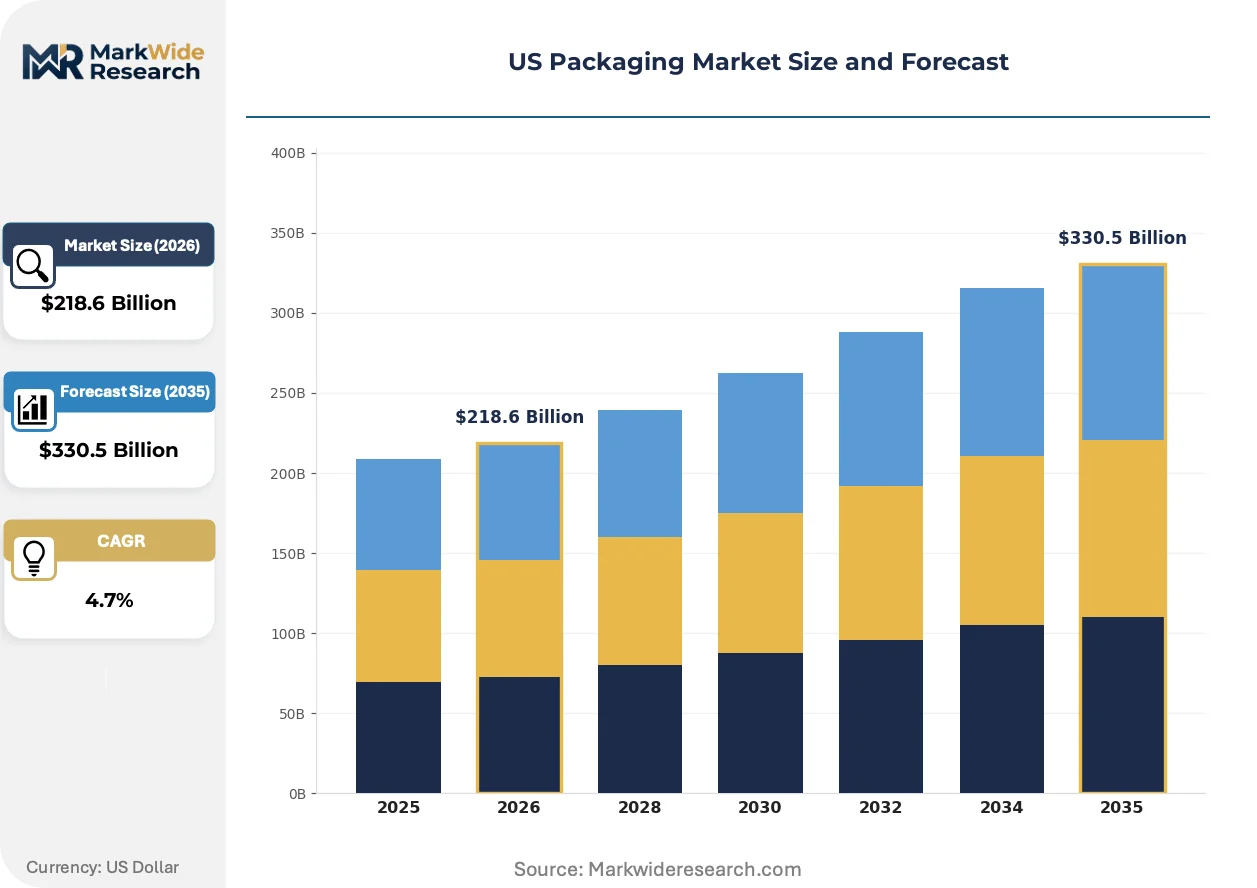
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $330.5 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Glass Containers, Metal Containers Material: Plastic, Paper, Glass, Metal End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Packaging Type: Bottles, Bags, Boxes, Pouches |
| Companies Covered | WestRock, International Paper Co., Ball Corporation, Berry Global, Crown Holdings, Graphic Packaging International, Packaging Corporation of America, Sonoco, Sealed Air, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Packaging Market Trends and Innovations
Active and intelligent packaging technologies are compressing quality assurance timelines while regulatory pressure on circularity accelerates material science investment across substrate categories.
Printed sensor arrays embedded in corrugated and flexible formats is digitizing real-time condition monitoring for temperature-sensitive pharmaceuticals and fresh produce. Cold-chain distributors in the Midwest and Southeast are piloting these systems at scale. The technology is compressing insurance claim cycles and enabling outcome-based logistics contracts.
EPA Comprehensive Procurement Guidelines for recycled fiber content are tightening federal purchasing specifications. Converters serving institutional foodservice and military supply contracts must certify minimum post-consumer percentages. The corrugated segment is responding with mixed-pulp formulations that maintain burst strength thresholds.
Direct-to-brand procurement models are displacing traditional distributor relationships in e-commerce packaging. Fulfillment operators in California and Texas now specify exact flute profiles and print registration tolerances through vendor-managed inventory arrangements. This pattern concentrates volume with automated converters capable of sub-48-hour turnaround.
US Packaging Market Segmentation
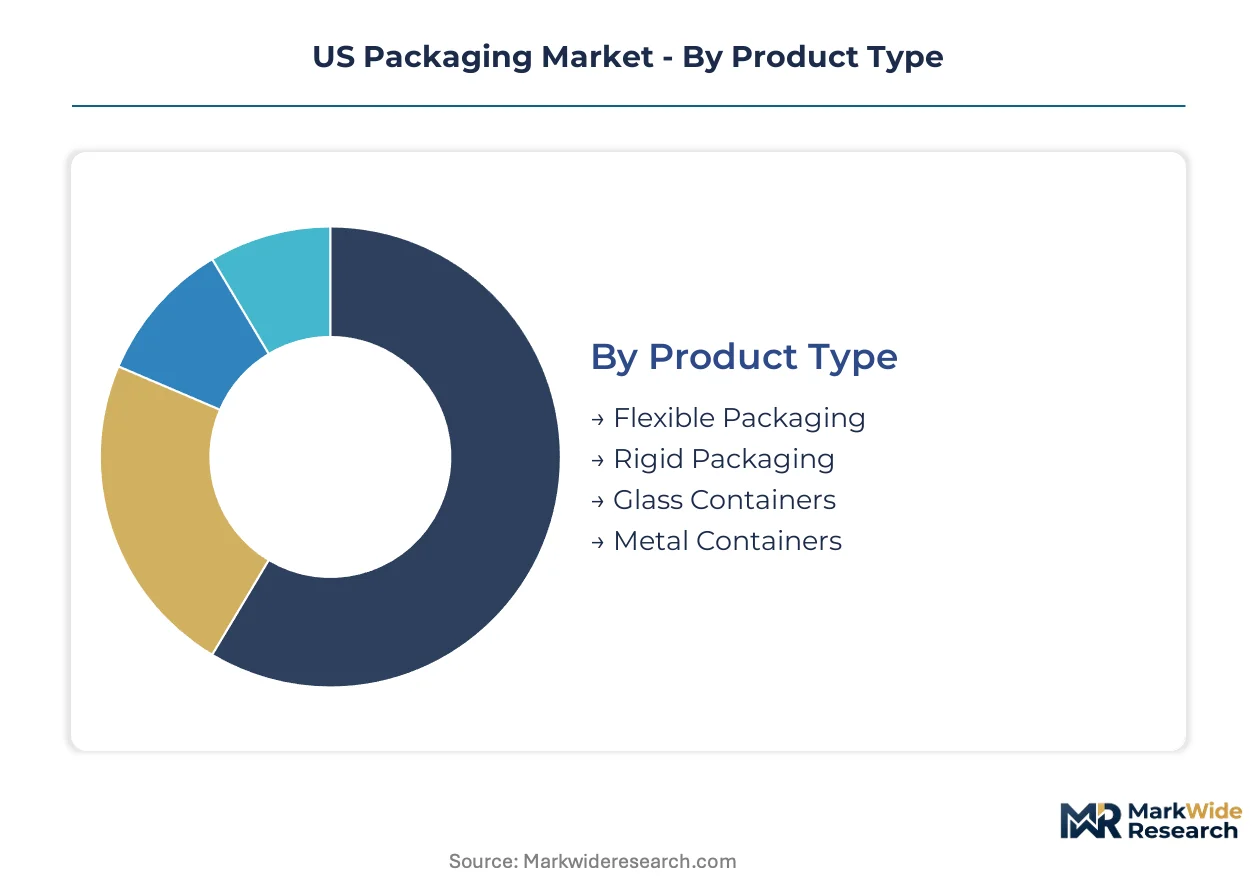
Material specifications and end-use compliance requirements fragment the US packaging landscape into distinct procurement channels. Each segmentation axis carries unique regulatory exposure and margin profiles that reshape converter capital allocation priorities.
Product Type:
Converters engineer solutions across a use-case spectrum spanning shelf-stable barrier protection to premium dispensing aesthetics.
- Flexible Packaging:Multi-layer polymer films with controlled moisture vapor transmission rates dominate snack and frozen food segments. California and Texas logistics hubs concentrate demand where lightweighting reduces dimensional weight shipping penalties.
- Rigid Packaging:Injection-molded and thermoformed containers deliver dimensional stability for beverage and personal care dispensing formats. FDA food-contact notification timelines for recycled content integration constrain material innovation cycles.
- Glass Containers:Inert borosilicate and soda-lime formulations retain premium positioning in spirits and craft segments where recyclability signals quality to regulatory-conscious consumers.
- Metal Containers:Tinplate and aluminum canstock provide hermetic sealing for shelf-stable food and aerosol applications.
Established volume favors rigid formats; emerging adoption favors flexible solutions.
Material:
Raw material selection determines regulatory jurisdiction and circularity pathway viability.
- Plastic:PE, PP, PET, and multi-layer barrier structures face EPA recycled content mandates and state-level extended producer responsibility cost shifts.
- Paper:Containerboard and kraft grades serve corrugated protective applications with burst strength specifications tied to e-commerce fulfillment automation requirements.
- Glass:Silica-based substrates command premium positioning where inertness and infinite recyclability meet California and Maine disclosure rule compliance.
- Metal:Aluminum and steel canstock provide magnetic separation advantages in municipal recycling streams.
Procurement gravity centers on plastic; sustainability premiums accelerate paper substitution.
End Use Industry:
Compliance intensity and shelf-life requirements stratify converter capabilities across vertical markets.
- Food & Beverage:Migration limit testing and FDA food-contact certification dominate material qualification protocols. Cold-chain distributors in the Midwest pilot printed sensor arrays for temperature-sensitive produce.
- Pharmaceuticals:USP Class VI and barrier integrity standards govern multi-layer flexible film specifications for generic drug manufacturers.
- Personal Care:Resealability and dispensing precision drive rigid bottle and tube formats.
- Household Products:Chemical resistance and child-resistant closure compatibility shape HDPE and PP container design.
Pharmaceutical margins attract specialized capacity; food and beverage volume anchors mill utilization.
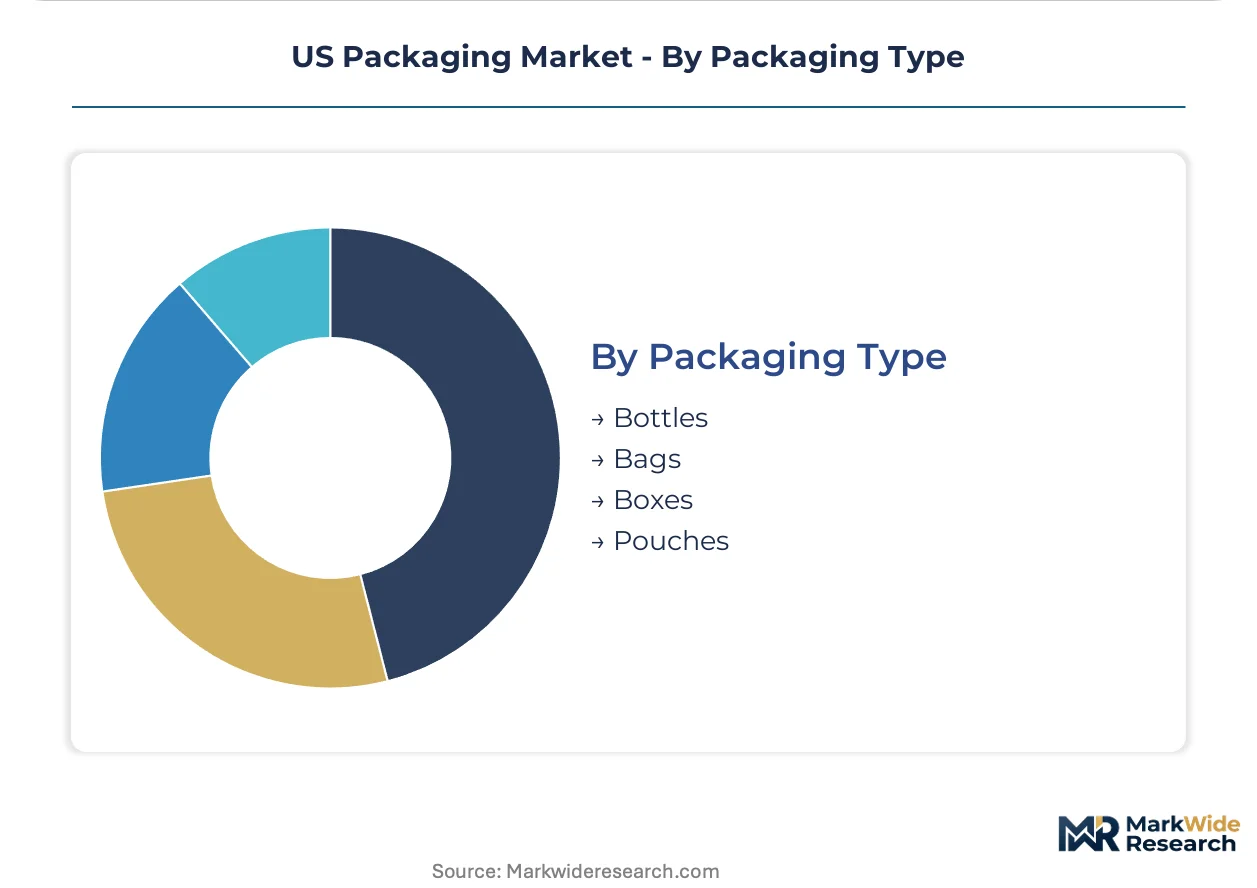
Packaging Type:
Form factor selection aligns with automated handling infrastructure and retail shelf presentation requirements.
- Bottles:Blow-molded PET and HDPE containers with precision neck finish tolerances integrate with high-speed capping lines.
- Bags:Side-seal and bottom-gusseted flexible formats reduce material intensity for dry goods distribution.
- Boxes:Corrugated RSC and die-cut designs with specified flute profiles serve automated sortation systems in California and Texas fulfillment centers.
- Pouches:Stand-up and flat formats with fitment integration capture shelf-space efficiency advantages in frozen and snack segments.
Boxed volume sustains corrugated investment; pouch formats gain share fastest in frozen food.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brand owners and third-party logistics operators concentrate procurement authority in coastal and border-adjacent states where port access and fulfillment automation density intersect.
California
Los Angeles and Long Beach port complexes anchor Pacific Rim import flows that feed automated fulfillment centers across the Inland Empire. CalRecycle's extended producer responsibility regulations mandate post-consumer resin minimums for rigid containers sold statewide. Sacramento Valley food processors contract precision-cut corrugated specifications for direct-to-consumer produce subscriptions.
Texas
Dallas-Fort Worth and Houston logistics corridors absorb containerboard volume for e-commerce sortation facilities serving central and southeastern population centers. State environmental agencies coordinate with EPA regional offices on recycled fiber procurement guidelines for institutional purchasers. Corpus Christi petrochemical complexes supply virgin resin feedstock for multi-layer flexible film converters.
Southeast
Georgia and South Carolina pulp mill corridors sustain containerboard capacity that ships via Savannah and Charleston ports to European and Latin American destinations. OSHA regional enforcement prioritizes adhesive exposure monitoring in converting facilities across the Carolinas. Atlanta distribution hubs specify flute profiles optimized for automated palletizing systems.
Midwest
Chicago and Detroit industrial clusters demand temperature-sensitive pharmaceutical packaging for generic drug distribution networks. FDA district offices in Minneapolis and Chicago oversee food-contact notification reviews that delay recycled content product launches. Ohio River Valley converters serve Procter & Gamble and other Cincinnati-headquartered brand owners with rigid bottle and tube formats.
Northeast
Maine's extended producer responsibility framework shifts cost accountability to brand owners for post-consumer packaging recovery. New Jersey and Pennsylvania pharmaceutical corridors require USP Class VI certified barrier films for sterile drug packaging. Boston-area biotech incubators pilot printed sensor arrays for cold-chain cell therapy logistics.
US Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement channels where scale, customization speed, and regulatory compliance credentials determine contract allocation. The vendor base separates into integrated mill-to-box operators, regional converting specialists, and materials-science-focused barrier film developers. Consolidation pressure concentrates volume with automated converters capable of sub-48-hour turnaround for e-commerce fulfillment specifications. Dominant competitive moves include vertical integration into recycled pulp sourcing and strategic partnerships with smart packaging technology licensors.
Among integrated paper-based packaging operators, WestRock and International Paper Co. occupy positions that exemplify scale-driven mill network leverage. Berry Global represents the specialized multi-layer flexible film archetype where pharmaceutical barrier compliance creates margin premiums. These three companies anchor distinct competitive vectors—corrugated automation, containerboard capacity, and barrier film migration limit certification—that collectively illustrate how procurement gravity concentrates with converters possessing both regulatory documentation depth and geographic proximity to California and Texas logistics hubs.
| Leading Market Players |
|---|
| WestRock |
| International Paper Co. |
| Ball Corporation |
| Berry Global |
| Crown Holdings |
| Graphic Packaging International |
| Packaging Corporation of America |
| Sonoco |
| Sealed Air |
| Others |
Pricing and Supply Chain Analysis
Containerboard mill concentration along the Southeastern US corridor concentrates margin capture upstream with International Paper and WestRock, while converters downstream face compressed spreads on standardized corrugated specifications. FDA food-contact notification timelines for recycled content integration extend 18-24 months, forcing brand owners to absorb premium pricing for certified barrier films or delay product launches.
Pricing Analysis
Cost-plus contracts indexed to RISI pulp and paper price indices dominate containerboard procurement between integrated mills and large-format converters. Price differentiation separates FDA-certified pharmaceutical barrier films from industrial-grade corrugated, with certification tiers commanding 15-30 percent premiums over commodity grades. Pricing pressure stems from post-consumer resin qualification investments required under California and Maine extended producer responsibility frameworks. Small-format converters serving regional food processors exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize compliance over unit cost.
Supply Chain Analysis
Supplier financing facilities extended by Southeastern mill operators to national account converters compress working capital cycles across the value chain. Geographic supply concentration centers on the US Southeast for containerboard, Texas Gulf Coast for virgin resin feedstock, and Midwest pharmaceutical corridors for barrier film converting. Raw material dependencies include OCC recovered fiber, LLDPE resin, and specialty adhesive chemistries. Single-source vulnerability runs through the Savannah-Charleston port corridor for export-bound containerboard. Distribution runs through vendor-managed inventory arrangements direct to California and Texas fulfillment centers, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US packaging market functions as a defensive-moat sector where regulatory entrenchment creates durable competitive positioning. FDA food-contact certification timelines and state-level extended producer responsibility compliance requirements erect switching costs that protect incumbent converters with documented qualification histories.
For Market Incumbents: Pre-empt margin compression by securing captive OCC supply through backward integration into recycling collection networks or long-term municipal contracts. Invest in smart packaging R&D partnerships to capture pharmaceutical cold-chain contracts before generic drug manufacturers consolidate supplier panels. The threat of direct-to-brand procurement models bypassing traditional distributor relationships demands sub-48-hour turnaround capabilities. For New Entrants and Emerging Players: Build out specialized barrier film capacity targeting generic pharmaceutical manufacturers seeking USP Class VI certified alternatives to established suppliers. White-space opportunity concentrates in temperature-sensitive indicator integration for Midwest cold-chain distributors piloting printed sensor arrays. A go-to-market angle anchored to right-to-repair packaging disclosure compliance creates first-mover positioning as Maine and Oregon mandates expand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converting specialists possessing FDA food-contact notification portfolios but lacking smart packaging technology integration. Long-term viability favors converters with geographic proximity to California and Texas logistics hubs combined with documented post-consumer resin qualification capabilities. The signal to watch is acceleration in state-level extended producer responsibility adoption beyond California, Oregon, and Maine, which would force brand owner procurement shifts toward compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Sourcing | Captive OCC supply secures margin stability under EPA recycled content mandates. |
| Smart Packaging Technology Licensing | Printed sensor integration enables premium positioning in pharmaceutical cold-chain logistics. |
| Vendor-Managed Inventory Expansion | Direct-to-brand arrangements with California fulfillment operators displace distributor intermediaries. |
| Post-Consumer Resin Qualification Investment | FDA food-contact notification completion opens California and Maine regulated markets. |
| Regional Capacity Addition in Texas Corridor | Proximity to Houston and Dallas-Fort Worth logistics hubs reduces transportation cost exposure. |
Research Methodology
A spread of perspectives from corrugated plant managers, pharmaceutical packaging procurement leads, FDA regulatory affairs specialists, and brand owner sustainability directors converged on the working assumptions underlying this analysis. Primary interview insights were validated against secondary sources including EPA Comprehensive Procurement Guidelines, state-level extended producer responsibility regulatory filings, RISI pulp and paper price indices, and SEC 10-K disclosures from integrated packaging operators. Bottom-up volume modeling across material grades and end-use segments was triangulated with top-down macroeconomic demand drivers.
Demand-supply-balance dynamics across the projection horizon were assessed through capacity utilization analysis at Southeastern mill corridors and order backlog patterns at Texas and California converting facilities. Segmentation dimensions modeled include material substrate, packaging format, end-use industry vertical, and regional logistics hub proximity. CAGRs were derived from trend extrapolation of historical volume data adjusted for regulatory intervention timelines and technology adoption curves. Industry-specific forecast inputs incorporated e-commerce fulfillment automation capex cycles and pharmaceutical generic drug approval pipelines.
Practitioners should monitor state legislative calendars for extended producer responsibility expansion, FDA recycled content notification backlog developments, and OCC price volatility for early signals of forecast deviation. Macroeconomic contraction in consumer discretionary spending, regulatory delays in post-consumer resin qualification standards, or breakthroughs in multi-layer film mechanical recycling would prompt revision of the underlying assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Thermal Transfer Roll Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Asia - Pacific Disposable Tableware Market
Packaging Materials
Standard Liner Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Packaging Lacquering Market