
 Hot Melt Adhesive Tapes Market | 2026-2036
Hot Melt Adhesive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Melt Adhesive Tapes Market Outlook
Market Context
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Henkel AG & Co. KGaA leverages its European R&D footprint to sustain formulation leadership across automotive and electronics grades. 3M anchors North American supply through deep vertical integration in polymer sourcing and coating technology. Avery Dennison Corporation differentiates via specialty tape portfolios serving medical and industrial bonding niches.
Technical Definition and Segment Structure
Hot melt adhesive tapes are pressure-sensitive backing materials coated with thermoplastic polymers that activate upon heat application and form permanent bonds upon cooling, typically operating at application temperatures between 120°C and 180°C. These tapes serve primary industrial purposes in automated assembly, temporary fixation during manufacturing, and structural bonding where mechanical fasteners prove impractical. Double-sided tapes command premium positioning in electronics lamination and automotive interior assembly where invisible bonding and vibration damping prove critical. Single-sided tapes dominate volume throughput in corrugated box sealing and general packaging workflows. Specialty tapes, including foam-backed and reinforced variants, capture disproportionate margin pools in aerospace gasketing and medical device assembly where failure tolerance approaches zero.
Regulatory Frame and Outlook
EPA emissions guidelines in the United States, REACH chemical restrictions in Europe, and China's GB standards for volatile organic compound limits collectively reshape adhesive formulation roadmaps and testing protocols. Manufacturers must navigate divergent compliance timelines while maintaining cross-border product consistency. Stakeholders should monitor regulatory harmonization talks between OECD members and emerging economy frameworks, as alignment or fragmentation will determine whether regional SKU proliferation becomes a permanent cost structure.
Market Dynamics
Automotive lightweighting mandates are forcing bonding technology transitions across assembly lines, as manufacturers shed mechanical fasteners for adhesive solutions that cut vehicle mass while maintaining structural integrity.
Growth Catalysts
- EPA emissions guidelines:US automotive OEMs face tightening fuel economy standards that reward every gram of weight reduction, accelerating tape adoption in body-in-white and interior modules.
- Electronics lamination:Flexible printed circuit board manufacturers in China and Vietnam are converting from liquid adhesives to double-sided hot melt tapes for cleaner, faster bonding of display stacks and battery packs.
- REACH chemical restrictions:European formulators are retooling solvent-based lines toward 100% solid hot melt systems to maintain market access, creating pull-through demand for compatible tape substrates.
Market Restraints
- Propylene and EVA resin volatility:Feedstock costs for copolymer hot melts swing with crude oil and natural gas pricing, compressing converter margins during upstream spikes.
- Specialty polymer supply concentration:High-performance metallocene polyolefin supply clusters in Texas and Rotterdam, exposing tape coaters to port congestion and force majeure risks.
- Temperature performance ceiling:Standard hot melts soften above 80°C, excluding them from under-hood automotive and power electronics applications where silicone or epoxy tapes dominate.
Strategic Opportunities
- India packaging automation:E-commerce fulfillment centers in Maharashtra and Karnataka are retrofitting carton sealing lines, creating first-mover advantage for tape suppliers offering localized slitting and die-cutting.
- EU Green Deal procurement rules:Public infrastructure projects in Germany and France now specify bio-based content minimums, rewarding suppliers with certified renewable feedstock formulations.
- Medical device miniaturization:Wearable diagnostic manufacturers need ultra-thin, skin-compatible tapes that bond electronics to flexible substrates without irritation.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in rheology control and tackifier compatibility resides with aging specialists in Germany and Japan, constraining new product development pipelines.
- ISO 9001 certification timelines:Automotive tier-one suppliers demand 12-18 month supplier qualification cycles, freezing out mid-size tape converters without dedicated quality engineering staff.
- Legacy coating line retrofits:Solvent-based coaters face seven-figure capital outlays to install nitrogen inerting and thermal oxidizers for hot melt conversion, straining balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Melt Adhesive Tapes Market |
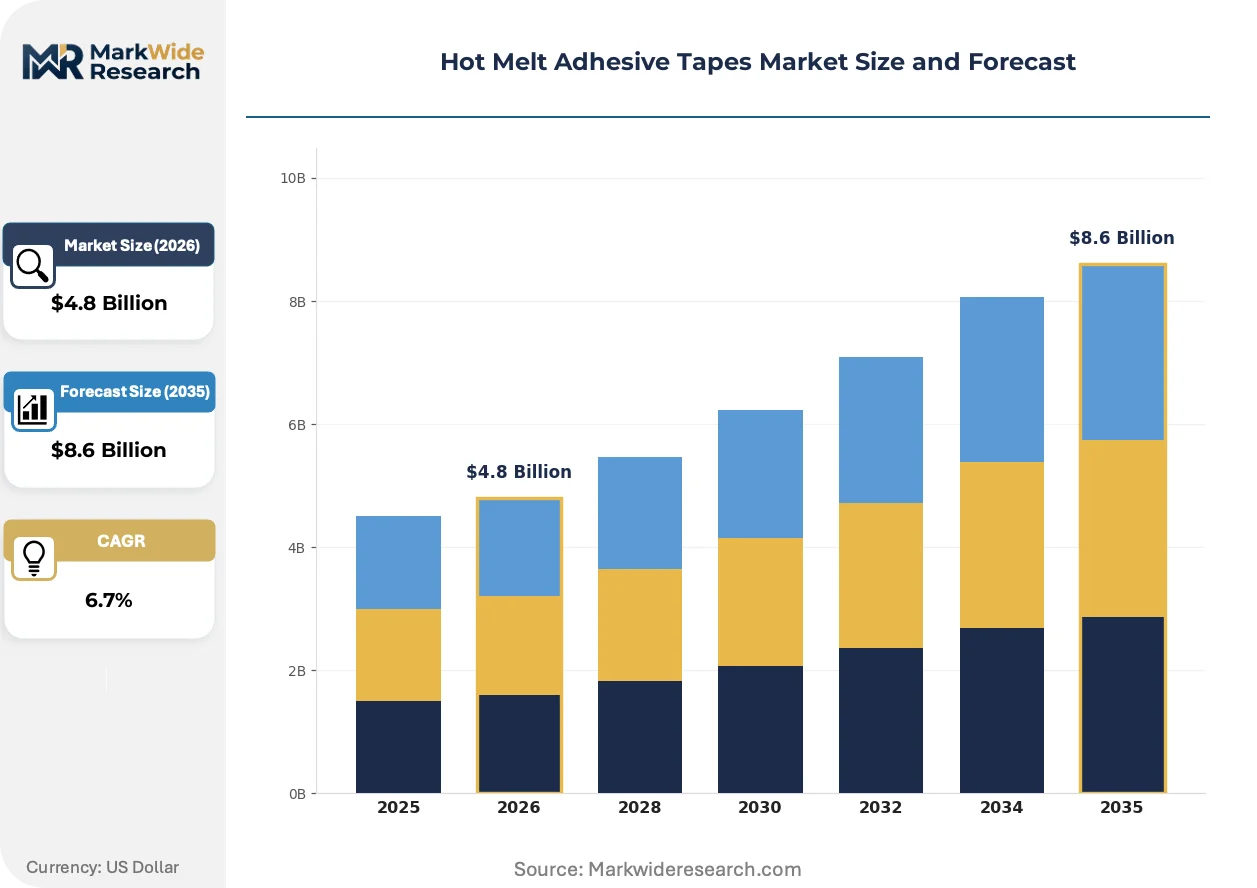
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tapes, Double-Sided Tapes, Transfer Tapes, Specialty Tapes Application: Packaging, Automotive, Electronics, Construction Material: Polyethylene, Polypropylene, PVC, Foam End User: Manufacturers, Retailers, Contractors, DIY Enthusiasts |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Avery Dennison Corporation, H.B. Fuller Company, Intertape Polymer Group, Shurtape Technologies, Nitto Denko Corporation, Scapa Group, Lintec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Melt Adhesive Tapes Market Strategic Shifts
Formulation chemistry and application equipment are converging to expand the addressable temperature window and automation compatibility of hot melt systems, unlocking segments previously closed to pressure-sensitive bonding.
UV-curable hot melt technology is supplanting conventional thermoplastic formulations in electronics assembly workflows. Smartphone and tablet manufacturers in South Korea and China are piloting these systems for display lamination, attracted by instant green strength that eliminates clamping stations. The structural consequence is compression of traditional thermal hot melt volumes in high-value consumer electronics tiers.
REACH authorization requirements for diisocyanates are tightening access to polyurethane hot melt raw materials across European manufacturing. Formulators in Belgium and the Netherlands are accelerating investments in polyolefin and polyester alternatives to maintain product lines. Medical device and automotive interior segments face the steepest compliance curves, with some suppliers exiting the polyurethane category entirely by 2026.
Automotive OEMs are consolidating adhesive specifications across global platforms, collapsing regional tape variants into unified global grades. Tier-one suppliers in Michigan, Stuttgart, and Shanghai now source identical tape constructions for the same vehicle programs, reversing decades of regional customization. This concentration is most visible in electric vehicle battery module assembly, where cell-to-cell bonding tapes must perform identically across climate zones.
Hot Melt Adhesive Tapes Market Segmentation
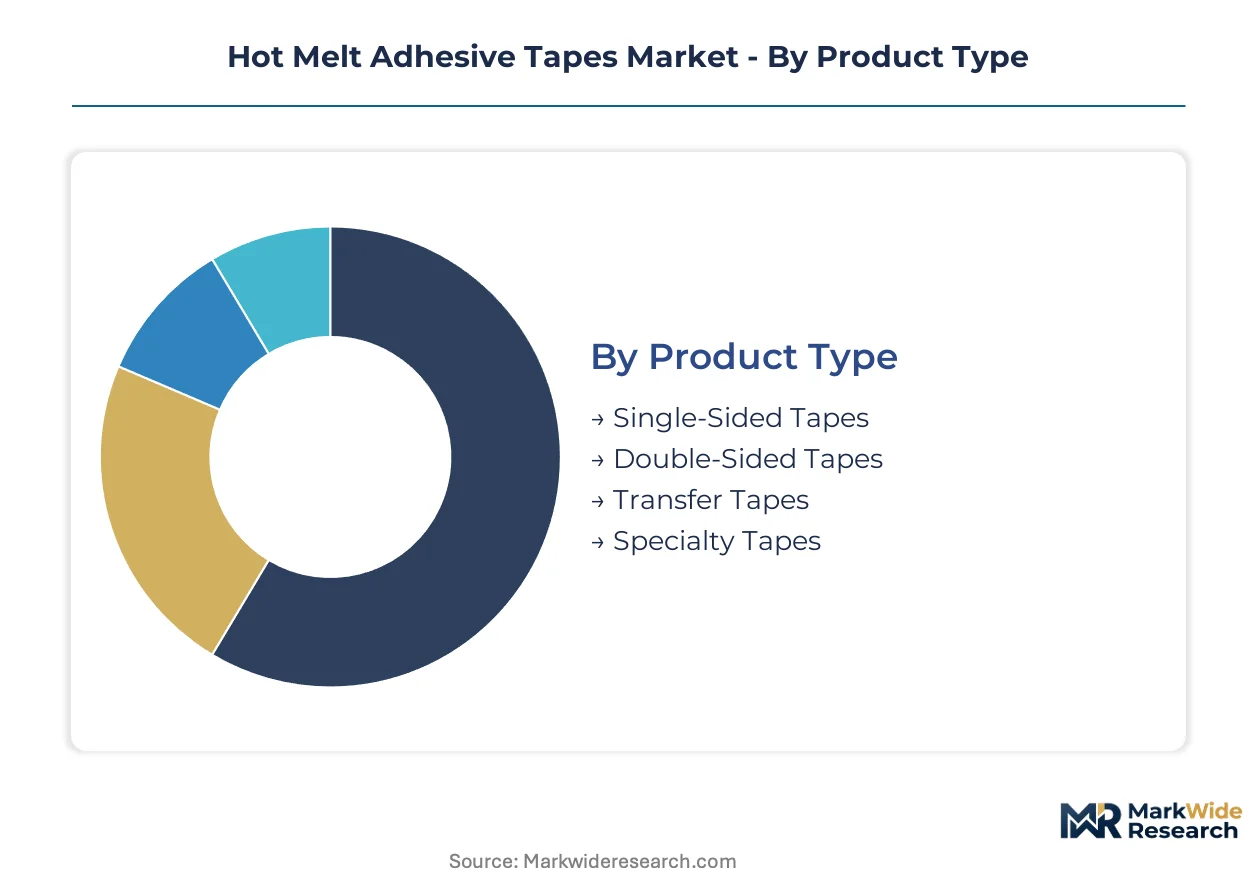
Segmentation in hot melt adhesive tapes reveals divergent margin profiles and qualification barriers across industrial grades. Manufacturers configure coating lines and raw material procurement around specific product-performance tiers rather than pursuing horizontal coverage.
Product Type:
Domestic consumption in China and India concentrates in single-sided and double-sided formats for packaging automation, while specialty and transfer tapes flow disproportionately to export markets serving European automotive and North American medical device assembly.
- Single-Sided Tapes:These constructions carry adhesive on one face of paper, film, or cloth backings, typically formulated with EVA or metallocene polyolefin hot melts for corrugated box sealing and temporary surface protection. Demand clusters in Chinese e-commerce fulfillment centers and Indian logistics hubs where carton throughput volumes justify automated dispensing systems. REACH-compliant solvent-free formulations are displacing legacy acrylic tapes in European export specifications.
- Double-Sided Tapes:Adhesive coats both substrate faces, enabling invisible bonding of automotive interior trim, electronics display stacks, and medical device components where mechanical fasteners fail. German and Japanese automotive OEMs specify these grades for electric vehicle battery module assembly, requiring thermal stability above standard hot melt ceilings. The qualification cycles with Henkel and 3M run 18-24 months for tier-one supplier status.
- Transfer Tapes:Unsupported adhesive films without carrier substrates, ideal for ultra-thin lamination in smartphone and wearable manufacturing.
- Specialty Tapes:Foam-backed, reinforced, or medical-grade constructions serving aerospace gasketing and skin-contact diagnostics with near-zero failure tolerance.
Single-sided tapes command the established base. The steepest expansion runs through double-sided tapes.
Application:
Cost tier differentiation separates high-volume packaging grades from specification-driven automotive and electronics segments where formulation chemistry determines pricing power.
- Packaging:Carton sealing and pallet stabilization dominate volume throughput, with Chinese domestic manufacturers consuming bulk commodity-grade polyethylene and polypropylene tapes. Indian e-commerce growth is accelerating automated line retrofits in Maharashtra and Karnataka fulfillment centers.
- Automotive:Lightweighting mandates in US EPA fuel economy regulations and EU CO2 targets are displacing mechanical fasteners with adhesive bonding in body-in-white and interior modules. Battery cell-to-cell bonding in electric vehicles requires thermal performance beyond standard hot melt limits.
- Electronics:Display lamination and flexible circuit board assembly in South Korea and Vietnam favor UV-curable hot melts for instant green strength.
- Construction:Vapor barrier sealing and temporary fixture applications, concentrated in US residential and German commercial building codes.
Packaging absorbs the volume base. Electronics generates the fastest margin expansion.
Material:
Supply concentration in Texas and Rotterdam for metallocene polyolefin resins creates geographic asymmetry in material access and converter margin stability.
- Polyethylene:Low-density and linear low-density grades dominate commodity packaging tapes for cost-sensitive carton sealing. Chinese domestic producers source from Sinopec and PetroChina facilities, while European converters face feedstock volatility linked to Brent crude pricing.
- Polypropylene:Higher melting points and chemical resistance suit automotive interior applications where temperature cycling exceeds 80°C. German compounders in Ludwigshafen and Leverkusen control formulation expertise for REACH-compliant automotive specifications.
- PVC:Electrical insulation and marking tapes, declining in European markets due to plasticizer regulatory pressure.
- Foam:Polyethylene and polyurethane foam carriers enable gap-filling and vibration damping in automotive and construction joints.
Polyethylene holds the volume foundation. Polypropylene captures the specification premium.
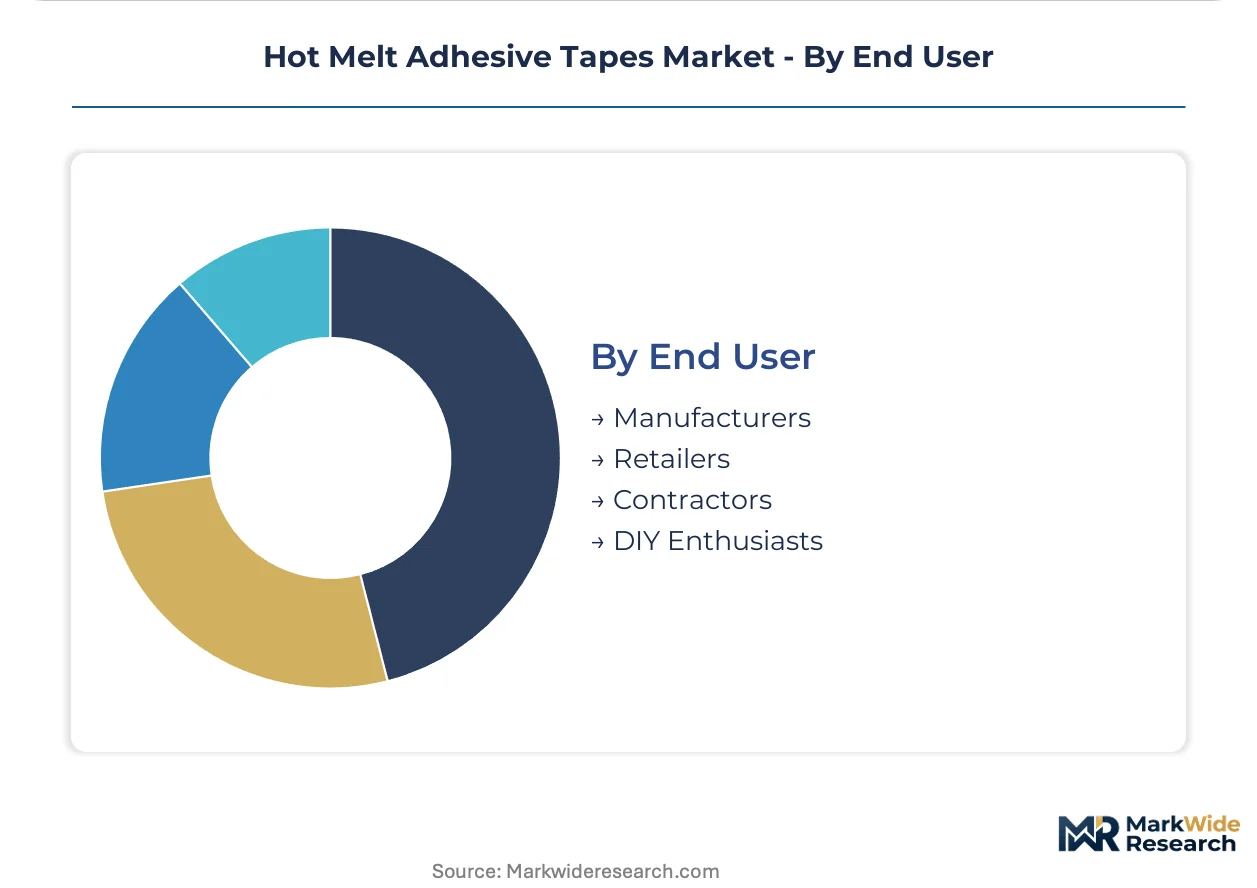
End User:
Customer type determines procurement scale and technical service intensity, with manufacturers demanding application engineering support that retailers and DIY channels cannot justify.
- Manufacturers:Automotive tier-one suppliers and electronics OEMs in Germany, Japan, and China drive formulation co-development and long-term supply agreements. ISO 9001 certification is non-negotiable for qualification.
- Retailers:Big-box and industrial distributors in the US and Europe stock standard packaging and general-purpose grades with minimal technical support.
- Contractors:Construction and MRO procurement favors availability over specification, concentrated in regional distribution networks.
- DIY Enthusiasts:Consumer channels represent marginal volume, served through retail co-branded offerings with limited performance claims.
Manufacturers anchor the revenue base. Retailers provide the volume throughput with minimal service overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and electronics contract manufacturers concentrate procurement decisions in Germany, China, Japan, and the United States, with secondary demand emerging from India's packaging automation investments.
United States
EPA fuel economy standards are accelerating tape adoption in Michigan and Ohio assembly plants as OEMs replace mechanical fasteners to cut vehicle mass. NHTSA safety regulations mandate crash-test-validated bonding solutions for battery enclosures in electric vehicle production. Detroit-area tier-one suppliers now specify identical tape grades for cross-border vehicle programs with Mexican assembly facilities.
Germany
REACH chemical restrictions are redirecting Ludwigshafen and Leverkusen formulators toward 100% solid hot melt systems, eliminating solvent-based legacy production. EU Green Deal procurement rules now require bio-based content minimums for public infrastructure projects. Stuttgart automotive clusters are consolidating adhesive specifications across global EV platforms, collapsing regional variants into unified grades.
China
Domestic packaging and electronics manufacturing scales are concentrating demand in Yangtze River Delta and Pearl River Delta corridors. GB standards for volatile organic compound limits are tightening formulation requirements for export-oriented producers. Shenzhen and Dongguan flexible circuit board manufacturers are converting from liquid adhesives to double-sided hot melt tapes for display stack lamination.
Japan
METI industrial standards are shaping qualification protocols for automotive and electronics bonding applications. Aging formulation expertise in rheology control and tackifier compatibility constrains new product development pipelines. Nagoya and Osaka industrial clusters maintain specification leadership for high-temperature automotive interior applications.
India
E-commerce fulfillment automation in Maharashtra and Karnataka is retrofitting carton sealing lines with localized slitting and die-cutting capabilities. BIS certification requirements are extending qualification timelines for imported tape specifications. Mumbai and Bangalore logistics hubs now represent first-mover opportunities for suppliers establishing regional converting operations.
Hot Melt Adhesive Tapes Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with captive polymer supply and specialized tape converters serving niche qualification tiers. The competitive landscape bifurcates between ISO 9001-certified automotive suppliers and marginal participants frozen out by 18-24 month qualification cycles. Three archetypes dominate: vertically integrated material-science conglomerates, regional converters with slitting and die-cutting capabilities, and specialty formulators focused on medical and aerospace grades. Capacity expansion and backward integration into polymer sourcing represent the dominant competitive moves.
Among diversified chemical conglomerates, 3M and Henkel AG & Co. KGaA exemplify the integrated archetype with European and North American R&D footprints sustaining formulation leadership. Avery Dennison Corporation occupies a position within the specialty tier, differentiated via portfolio concentration in medical and industrial bonding niches. These three anchors represent distinct competitive vectors—materials science depth, geographic coverage, and application specialization—that shape procurement options for automotive OEMs and electronics manufacturers.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Intertape Polymer Group |
| Shurtape Technologies |
| Nitto Denko Corporation |
| Scapa Group |
| Lintec Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Texas and Rotterdam metallocene polyolefin facilities shapes both supply concentration and price floors for tape converters, with automotive OEMs leveraging scale to compress margins on commodity grades while specialty formulations retain pricing power through formulation scarcity.
Pricing Analysis
Cost-plus contracts with propylene and EVA indexation dominate procurement between resin suppliers and tape coaters, insulating converters from crude oil volatility while passing through feedstock spikes to downstream buyers. Three-tier pricing structure across automotive specification, industrial standard, and packaging economy levels separates ISO 9001-certified automotive grades from uncertified commodity tapes. Cost compression in packaging tiers is intensifying because Chinese domestic producers are scaling slitting capacity. E-commerce logistics operators in India exhibit the highest price sensitivity, while German automotive tier-one suppliers prioritize thermal performance over unit cost.
Supply Chain Analysis
Rotterdam port congestion and Houston Ship Channel weather delays expose tape coaters to force majeure risks on metallocene polyolefin feedstock deliveries. High-performance resin supply clusters in Texas, Rotterdam, and Singapore, with specialty tackifier expertise concentrated in Ludwigshafen and Osaka. Raw material dependencies center on propylene derivatives, ethylene-vinyl acetate copolymers, and hydrogenated hydrocarbon tackifiers. Single-source vulnerability runs through metallocene catalyst technology licensed from select German and Japanese chemical conglomerates. Distribution runs through regional slitting and die-cutting converters who serve automotive and electronics OEMs with just-in-time delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEMs consolidating global adhesive specifications, with tier-one suppliers in Michigan, Stuttgart, and Shanghai now demanding unified tape grades across vehicle programs.
For Market Incumbents: Compound formulation leadership in high-temperature automotive grades to defend against silicone and epoxy substitution in battery module assembly. Deepen captive supply of metallocene polyolefin resins through backward integration into polymer sourcing. Prioritize REACH-compliant solvent-free line retrofits before authorization deadlines tighten. ISO 9001 certification investment remains the critical barrier to tier-one supplier status. For New Entrants and Emerging Players: Lead with localized slitting and die-cutting capabilities in Maharashtra and Karnataka to capture Indian e-commerce packaging automation demand. Target medical device miniaturization segments where skin-compatible tape formulations face minimal incumbent saturation. Pursue bio-based content certification under EU Green Deal procurement rules as the primary go-to-market angle for European infrastructure projects. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty formulators serving medical and aerospace qualification tiers with multi-year supply agreements. Long-term viability hinges on exposure to electric vehicle battery bonding specifications rather than commodity packaging volumes. Acquisition target archetype: regional converters with ISO 9001 certification and established automotive supplier relationships. Monitor diisocyanate REACH authorization timelines as the signal to watch for polyurethane hot melt exit decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Sourcing | Captive supply of metallocene polyolefin resins insulates margins from Rotterdam and Texas feedstock volatility. |
| REACH-Compliant Line Retrofit | Solvent-to-hot-melt conversion preserves European market access as ECHA tightens chemical authorization requirements. |
| Medical Grade Certification Investment | ISO 13485 qualification opens wearable diagnostic segments with near-zero failure tolerance and premium pricing. |
| Localized Slitting Capacity Expansion | Maharashtra and Karnataka facilities reduce logistics costs for Indian e-commerce fulfillment automation demand. |
| UV-Curable Hot Melts R&D Partnership | Samsung and LG Display pilot programs signal displacement risk for conventional thermal hot melts in electronics lamination. |
Study Parameters
Desk research of customs trade data, SEC filings from adhesive and polymer producers, and REACH authorization databases preceded structured interviews with automotive tier-one procurement managers, tape coating plant engineers, and medical device supply chain directors. Primary fieldwork with formulation chemists in Germany and Japan supplemented secondary validation of technical specification trends. Bottom-up demand modeling across packaging, automotive, electronics, and medical segments was cross-checked against top-down resin consumption data from Texas and Rotterdam production hubs.
Variance decomposition across product type, application, material grade, and end-user segments anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level demand elasticities and capacity expansion announcements. Industry-specific forecast inputs included EPA fuel economy standard stringency trajectories and GB standards evolution for volatile organic compound limits in Chinese manufacturing.
Forecasts assume regulatory continuity in EPA emissions guidelines, REACH chemical restrictions, and China's GB standards; material policy shifts would require re-modeling of automotive lightweighting adoption curves and electronics lamination technology transitions. Practitioners should keep alternative scenarios live as diisocyanate authorization timelines and UV-curable hot melt penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Reflective Tape Market
Tapes
Tape Banding Machine Market
Tapes
Paper Packaging Tapes Market
Tapes
Hand Wrappers Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Carry Handle Tape Market
Tapes
Tape Stretching Line Market
Tapes
Holographic Tear Tape Market
Tapes
Carbon Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Carton Sealing Tape Market
Tapes
Global Electrical Tapes Market
Tapes
PVC Tapes Market
Tapes
Washi Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market