
 Mylar Market | 2026-2036
Mylar Market Size, Share, and Industry Trends Forecast 2026-2036
Mylar Market Foresight
Direct-to-manufacturer supply channels is rewriting how Mylar converters reach end-users across North America and Asia. DuPont Teijin Films leverages captive resin production and film orientation capabilities to sustain pricing power in specialty grades. Toray Plastics anchors its position through Japan-centered R&D and Southeast Asian toll-coating partnerships. Grafix Plastics competes on short-run customization for prototyping and medical device packaging, where batch flexibility outweighs volume scale.
Mylar is a biaxially oriented polyethylene terephthalate (PET) film manufactured through sequential stretching of extruded polymer at controlled temperatures, yielding tensile strengths exceeding 200 MPa in both machine and transverse directions. The material serves primarily as a dielectric insulator, moisture barrier, and dimensional stabilizer across packaging and electronic applications. Flexible Film dominates volume shipments due to its ubiquity in lamination and converting operations, while Metalized coating variants command premium positioning in barrier-sensitive electronics and aerospace thermal control. Bags represent the fastest-growing product configuration, driven by vacuum-sealed pharmaceutical and precision-component packaging requirements where outgassing control is critical.
FDA food-contact regulations, EU REACH substance restrictions, and ISO 9001 quality management standards collectively shape material certification requirements and customer qualification timelines. REACH compliance costs are pushing smaller European converters toward certified toll coaters rather than in-house formulation. Stakeholders must monitor evolving semiconductor fab specifications in South Korea and Taiwan, where sub-micron cleanliness standards are redefining acceptable particulate thresholds for process-critical films.
Market Dynamics
Semiconductor fabrication specifications in South Korea and Taiwan are compressing particulate thresholds for process-critical films, forcing converter investments in cleanroom coating capacity and sub-micron inspection systems.
Growth Catalysts
- EU REACH substance restrictions:Material purity mandates are accelerating certified toll-coating partnerships across European converter networks, consolidating qualified supply bases.
- Flexible circuit substrates:Electronics manufacturers in East Asia are expanding Mylar adoption for insulation layers in high-density interconnect boards.
- Vacuum-sealed pharmaceutical packaging:Outgassing control requirements in precision-component logistics are driving bag configuration demand.
Market Restraints
- Petroleum-derived feedstock volatility:Purified terephthalic acid and ethylene glycol price swings compress margin predictability for non-integrated converters.
- East Asian supply concentration:China's coastal manufacturing provinces dominate biaxial orientation capacity, creating geographic single-source exposure.
- Metalized barrier substitution:Aluminum oxide-coated polymer films are capturing select electronics barrier applications at lower unit costs.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO and FSSAI compliance investments by domestic converters are opening import substitution potential for medical-grade films.
- Dual carbon goals in China:SAMR energy-efficiency mandates for industrial processes are incentivizing recycled-content PET film development.
- Direct-to-manufacturer channels:Converter-owned e-procurement platforms are disintermediating traditional distribution layers in North American custom runs.
Industry Challenges
- Cleanroom technician scarcity:Sub-micron coating operations face recruitment gaps for qualified process engineers in Taiwan and South Korea fabrication corridors.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and ISO 9001 qualification cycles extend customer onboarding to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mylar Market |
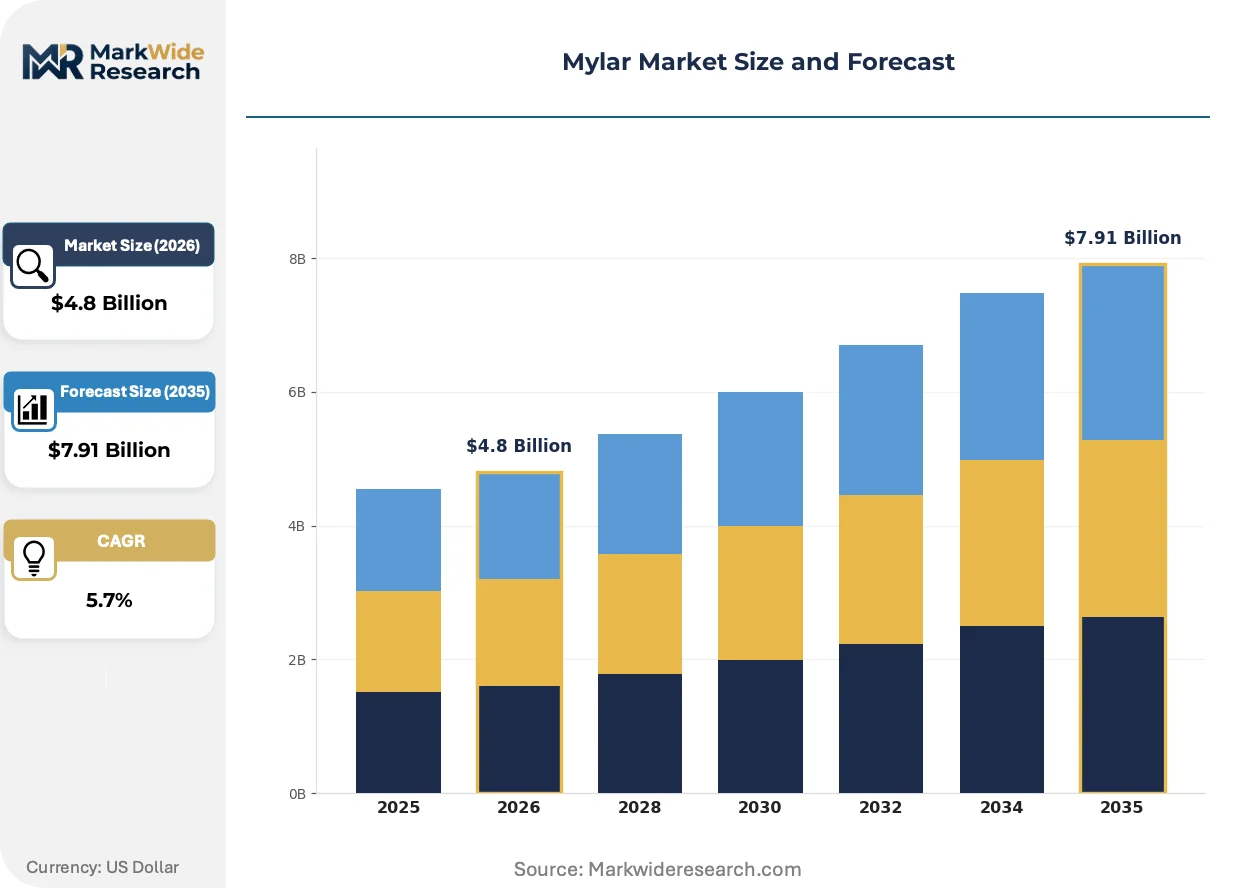
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Film, Rigid Sheet, Bags, Rolls End Use Industry: Packaging, Electronics, Automotive, Aerospace Thickness: 50 Microns, 100 Microns, 250 Microns, 500 Microns Coating Type: Uncoated, Metalized, Adhesive Coated, Transparent |
| Companies Covered | Uline, Grafix Plastics, DuPont Teijin Films, Jarrett Industries, IMPAK CORPORATION, Toray Plastics, FINE PACKAGE CO., LTD., Protective Packaging Corporation, CS Hyde Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mylar Market Shifts & Advancements
Film functionalization is advancing through hybrid coating architectures and precision orientation controls, reshaping how converters differentiate across barrier, thermal, and dielectric performance tiers.
Bio-based PET feedstocks derived from renewable ethylene glycol are hybridizing with conventional petroleum streams, allowing brand owners to meet Scope 3 reduction targets without sacrificing optical clarity or tensile performance. Food and personal care multinationals in Western Europe are piloting these grades at 10-20% blend ratios. The hybridizing supply structure is fragmenting raw material procurement strategies across previously unified resin specifications.
EU F-Gas Regulation phase-down schedules are pressuring aerospace thermal control film specifications, as legacy chlorofluorocarbon-based metalized coating processes face process chemistry redesign. European satellite component suppliers are accelerating qualification of alternative physical vapor deposition chemistries. Metalized Mylar for multilayer insulation blankets carries the highest compliance exposure, with conversion cost premiums projected to persist through the transition window.
Consolidated procurement desks at medical device OEMs are compressing supplier rosters from 6-8 qualified film vendors to 2-3 strategic partners, exchanging volume commitments for dedicated inventory buffers and co-development access. This concentration is visible most acutely in Minnesota and Massachusetts medical device clusters, where sterilization-grade Mylar specifications now require annual supplier audits and captive line dedication clauses.
Mylar Market Segmentation
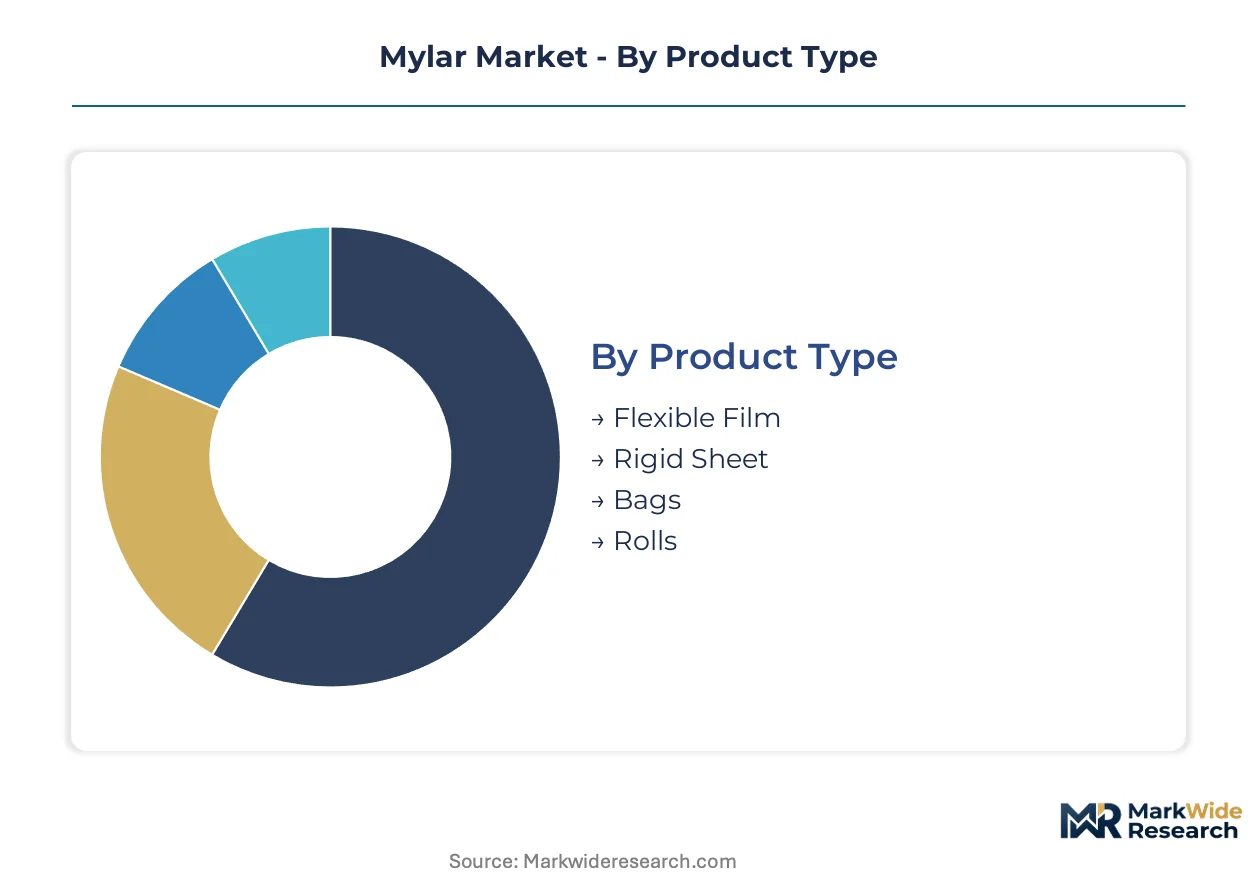
Mylar's performance characteristics vary sharply across thickness, coating, and format specifications, creating distinct procurement patterns between commodity converters and precision end-users. Electronics and pharmaceutical buyers prioritize certified consistency over unit economics, while packaging segments trade barrier performance against lamination yield.
Product Type:
Use-case spectrum spans dielectric insulation to moisture-barrier lamination, with format flexibility determining converter equipment compatibility and order minimums.
- Flexible Film:Biaxially oriented PET film serves as the foundational substrate for lamination, printing, and converting operations across packaging and electronics. Demand concentrates in China's coastal manufacturing provinces where converter networks supply both domestic flexible circuit producers and export-oriented food packaging operations.
- Bags:Pre-formed pouches with heat-sealed seams address vacuum-sealed pharmaceutical and precision-component packaging where outgassing control is critical. Medical device OEMs in Minnesota and Massachusetts clusters are consolidating supplier rosters to 2-3 strategic partners for sterilization-grade specifications.
- Rigid Sheet:Calendered PET sheet with higher crystallinity provides dimensional stability for thermoformed trays and display applications.
- Rolls:Master roll format optimizes slitting economics for high-volume converters with dedicated unwind and rewind lines.
Established volume favors Flexible Film; emerging adoption favors Bags.
End Use Industry:
Margin tier separates process-critical applications with 18-24 month qualification cycles from commodity packaging with spot-market pricing.
- Electronics:Dielectric substrates and insulation layers in flexible circuits require sub-micron cleanliness standards. South Korea and Taiwan semiconductor fabrication corridors face cleanroom technician scarcity for qualified process engineers.
- Packaging:Barrier lamination dominates volume shipments, with food-contact certification driving material purity investments. EU REACH substance restrictions are pushing smaller European converters toward certified toll coaters.
- Aerospace:Metalized multilayer insulation blankets face EU F-Gas Regulation compliance exposure, forcing alternative physical vapor deposition chemistry qualifications.
- Automotive:Wire harness insulation and battery module spacers demand thermal stability across -40°C to 150°C operating ranges.
Process-critical margins concentrate in Electronics; volume scale anchors Packaging.
Thickness:
Performance tier aligns with mechanical strength and dielectric withstand requirements across insulation and barrier applications.
- 50 Microns:Ultra-thin gauge optimized for flexible circuit substrates and high-density interconnect boards where bend radius and weight reduction outweigh puncture resistance.
- 100 Microns:Balanced mechanical and electrical properties serve general-purpose lamination and converting operations.
- 250 Microns:Intermediate gauge provides structural rigidity for medical device packaging and industrial masking applications.
- 500 Microns:Heavy-gauge sheet delivers dimensional stability for thermoformed trays, display fixtures, and battery module separators.
Volume production centers on 100 Microns; specialized qualification drives 50 Microns.
Coating Type:
Functionalization tier separates commodity substrates from barrier-sensitive electronics and aerospace thermal control applications.
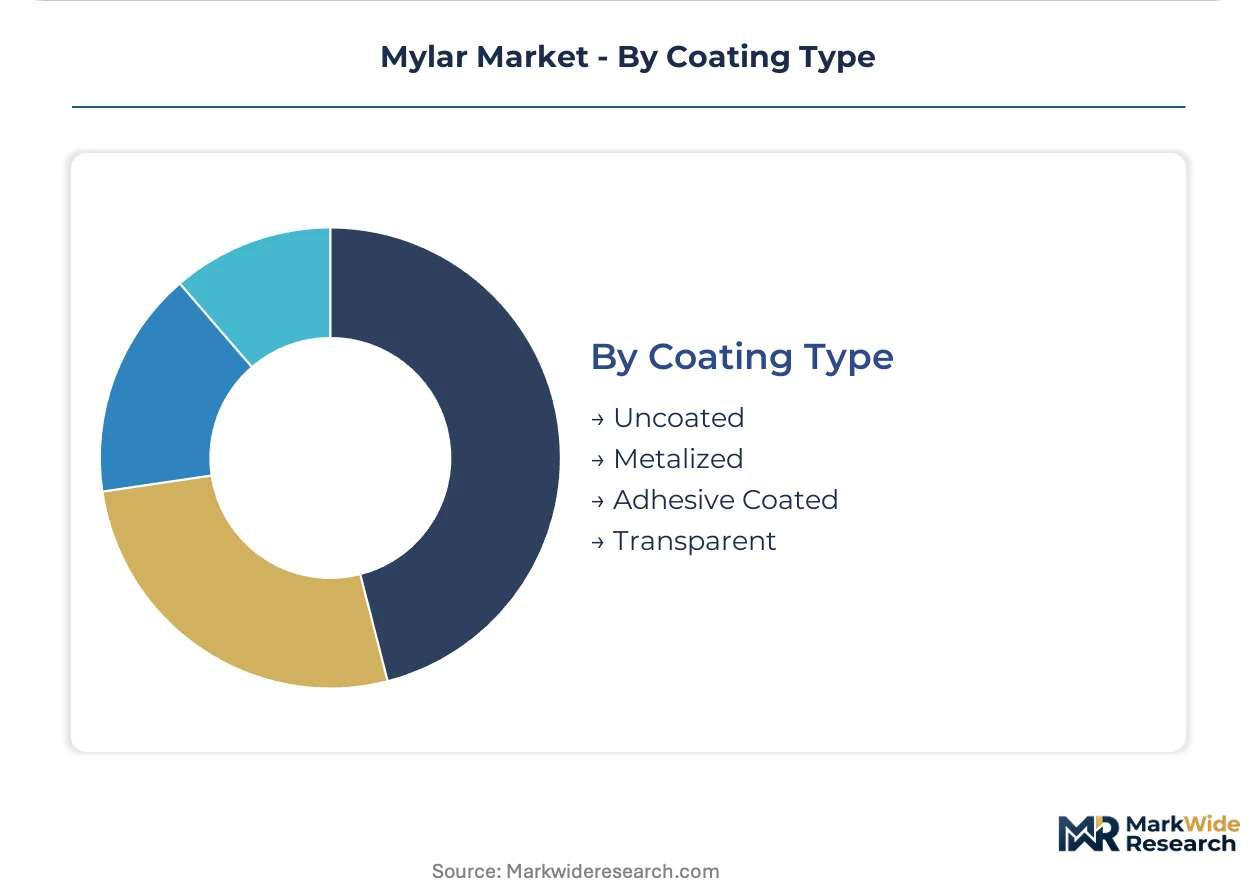
- Metalized:Aluminum vapor-deposited layer achieves oxygen transmission rates below 0.1 cc/m²/day for electronics barrier and multilayer insulation. Aluminum oxide-coated polymer films are capturing select applications at lower unit costs.
- Uncoated:Base PET film without functional layers serves cost-sensitive lamination and printing applications where barrier performance is secondary.
- Adhesive Coated:Pressure-sensitive or heat-activated adhesive layers enable direct bonding to substrates without secondary lamination steps.
- Transparent:Optical-grade clarity coatings maintain haze specifications below 1% for display and photovoltaic applications.
Premium positioning clusters in Metalized; cost-driven procurement favors Uncoated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through captive biaxial orientation capacity, while European converters absorb REACH compliance premiums that compress margin structures relative to Asian competitors.
United States
Medical device OEMs in Minnesota and Massachusetts drive sterilization-grade Mylar procurement, with FDA food-contact regulations governing material qualification timelines. Consolidated procurement desks now mandate annual supplier audits and captive line dedication clauses for qualified vendors.
Germany
Automotive wire harness insulation and battery module applications demand thermal stability across extreme operating ranges, with KBA vehicle safety standards influencing material specifications. Industrial converters in Baden-Württemberg maintain toll-coating partnerships to navigate ECHA REACH substance restrictions.
China
Coastal manufacturing provinces in Jiangsu and Guangdong host converter networks supplying domestic flexible circuit producers and export food packaging operations. SAMR energy-efficiency mandates for industrial processes incentivize recycled-content PET film development under dual carbon goals.
South Korea
Semiconductor fabrication corridors around Seoul and Busan compress particulate thresholds for process-critical films, forcing cleanroom coating investments. MFDS pharmaceutical packaging standards intersect with sub-micron cleanliness requirements from Samsung and SK Hynix fab specifications.
India
Domestic pharmaceutical packaging converters pursue CDSCO and FSSAI compliance investments to capture import substitution opportunities. Maharashtra and Gujarat-based toll coaters are qualifying medical-grade films for export to regulated Western markets.
Mylar Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film orientation and functional coating. The vendor base stratifies between resin-integrated majors, toll-coating networks, and short-run custom converters. Three archetypes dominate: captive resin producers sustaining pricing power, Southeast Asian toll-coating partnerships leveraging regional cost structures, and prototyping specialists trading batch flexibility against volume scale. Consolidation pressures and cleanroom capacity expansion represent the dominant competitive moves across qualification-intensive segments.
Among North American custom converters, Grafix Plastics occupies a position exemplifying short-run specialization for medical device prototyping. DuPont Teijin Films anchors the resin-integrated archetype through captive production capabilities. Toray Plastics represents the Japan-centered R&D model with regional toll-coating partnerships.
| Leading Market Players |
|---|
| Uline |
| Grafix Plastics |
| DuPont Teijin Films |
| Jarrett Industries |
| IMPAK CORPORATION |
| Toray Plastics |
| FINE PACKAGE CO., LTD. |
| Protective Packaging Corporation |
| CS Hyde Company |
| Others |
Supply & Pricing Matrix
Jiangsu and Guangdong provinces anchor biaxial orientation capacity for Mylar substrates, granting coastal Chinese converters leverage over global pricing benchmarks through integrated PET resin supply and toll-coating networks serving electronics and pharmaceutical end-users.
Pricing Analysis
Configured-to-order pricing for medical-grade sterilization films commands substantial premiums over standard lamination grades, with three-tier pricing structure across premium, standard, and economy levels separating FDA-validated batches from general-purpose converting stock. Price differentiation hinges on ISO 9001 certification tier and volume scale, with spot-market buyers in packaging segments exhibiting highest sensitivity while semiconductor fabs absorb premiums for sub-micron cleanliness guarantees. Cost compression in commodity flexible film is intensifying because aluminum oxide-coated substitutes are capturing barrier-sensitive electronics applications.
Supply Chain Analysis
Export-control regimes on advanced coating equipment and sub-micron inspection systems constrain cleanroom capacity expansion outside East Asian fabrication corridors, concentrating qualified supply among Taiwan, South Korea, and China. Raw material flows draw from purified terephthalic acid and ethylene glycol feedstocks tethered to petroleum pricing volatility, while metalized barrier production rests on aluminum vapor-deposition equipment subject to single-source vulnerability from Japanese and German equipment makers. Distribution runs through converter-owned e-procurement platforms disintermediating traditional North American distribution layers for custom runs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mylar adoption sits in early-cycle expansion across pharmaceutical vacuum-sealing and flexible circuit substrates, with semiconductor fab specifications in South Korea and Taiwan driving penetration into process-critical dielectric applications.
For Market Incumbents: Pre-empt aluminum oxide-coated polymer substitution by accelerating qualification of hybrid bio-based PET grades at 10-20% blend ratios for Western European brand owners. Capture toll-coating partnerships in India and Southeast Asia before CDSCO and FSSAI compliance investments mature domestic converter capacity. Lock in dedicated inventory buffers through captive line dedication clauses with Minnesota and Massachusetts medical device clusters.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat pharmaceutical packaging corridors offer underpenetrated white-space for medical-grade film qualification targeting export substitution. CDSCO compliance investments by domestic toll coaters create partnership entry points without cleanroom capital intensity. Target direct-to-manufacturer e-procurement channels for North American prototyping and short-run medical device packaging where batch flexibility outweighs volume scale.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors resin-integrated majors with captive biaxial orientation capacity over non-integrated converters exposed to feedstock volatility. Long-term viability over the projection horizon rests on cleanroom coating asset ownership and multi-jurisdiction certification infrastructure. Monitor EU F-Gas Regulation phase-down schedules as inflection indicator for aerospace thermal control film conversion cost premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | Sub-micron coating investments in Taiwan and South Korea address semiconductor fab particulate thresholds. |
| Backward Integration into PET Resin | Captive purified terephthalic acid supply insulates margin predictability from petroleum feedstock swings. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, REACH, and ISO 9001 qualification accelerates customer onboarding for medical-grade films. |
| Direct-to-Manufacturer E-Procurement Launch | Converter-owned platforms disintermediate distribution layers in North American custom run segments. |
| Bio-Based Feedstock Hybridization | Renewable ethylene glycol blends at 10-20% ratios meet Scope 3 targets without sacrificing optical clarity. |
Research Methodology
A spread of perspectives from biaxial orientation plant managers, pharmaceutical packaging procurement leads, semiconductor fab materials engineers, and medical device OEM supply chain directors converged on the working assumptions shaping demand trajectories. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of resin-integrated majors, ECHA REACH substance restriction updates, and semiconductor equipment capex disclosures. Bottom-up shipment analysis across thickness, coating, and format specifications triangulated against top-down end-use industry consumption patterns.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across product type, end-use industry, thickness tier, coating functionalization, and regional regulatory cluster. CAGRs were derived from slope analysis of historical shipment trajectories adjusted for penetration elasticity in emerging applications. Forecast inputs incorporated SAMR energy-efficiency mandate compliance costs, EU F-Gas Regulation phase-down schedules, and MFDS pharmaceutical packaging standard evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by aluminum oxide-coated film specialists or rapid cleanroom capacity buildout by Indian toll coaters would shift outcomes. Material shifts in semiconductor fab particulate specifications or REACH substance restriction scope expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Window Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Reel in Box Market
Packaging Materials
Global Hot Stamping Foils Market