
 South Korea Packaging Design Services Market | 2026-2036
South Korea Packaging Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Packaging Design Services Market Insights
Cosmetics is pivoting toward premium structural packaging as K-beauty exports expand into Southeast Asia and North America. Amorepacific leverages its in-house design studio to control brand consistency across multiple product tiers. Kolmar Korea Packaging anchors contract manufacturing with integrated design-to-production workflows for mid-tier beauty brands. Yonwoo differentiates through airless pump technology and specialized dispensing closures that reduce preservative loads.
Packaging design services encompass the creative and engineering disciplines that develop protective, communicative, and functional enclosures for consumer and industrial goods, spanning graphic layout, dimensional engineering, material specification, and production-ready prototyping with tolerances typically held to 0.5 millimeters for precision-molded components. Structural design commands the largest share of service revenue as brands invest in shelf differentiation and e-commerce durability, while flexible packaging represents the fastest-growing design format category driven by snack and single-serve food expansion. Graphic design retains stable margins in cosmetics and pharmaceuticals where regulatory label accuracy and multilingual compliance add complexity.
MFDS enforces strict label content and legibility standards for pharmaceuticals and cosmetics, while the Ministry of Environment's extended producer responsibility scheme shapes material selection toward mono-material and easily separable constructions. KBA packaging safety guidelines and ISO 9001 quality certifications operate as baseline qualifications for design vendors seeking contracts with major FMCG and electronics manufacturers. Stakeholders must monitor how Seoul's municipal recycling infrastructure upgrades and the national plastic reduction roadmap will redefine acceptable material palettes and closure systems within the next product development cycle.
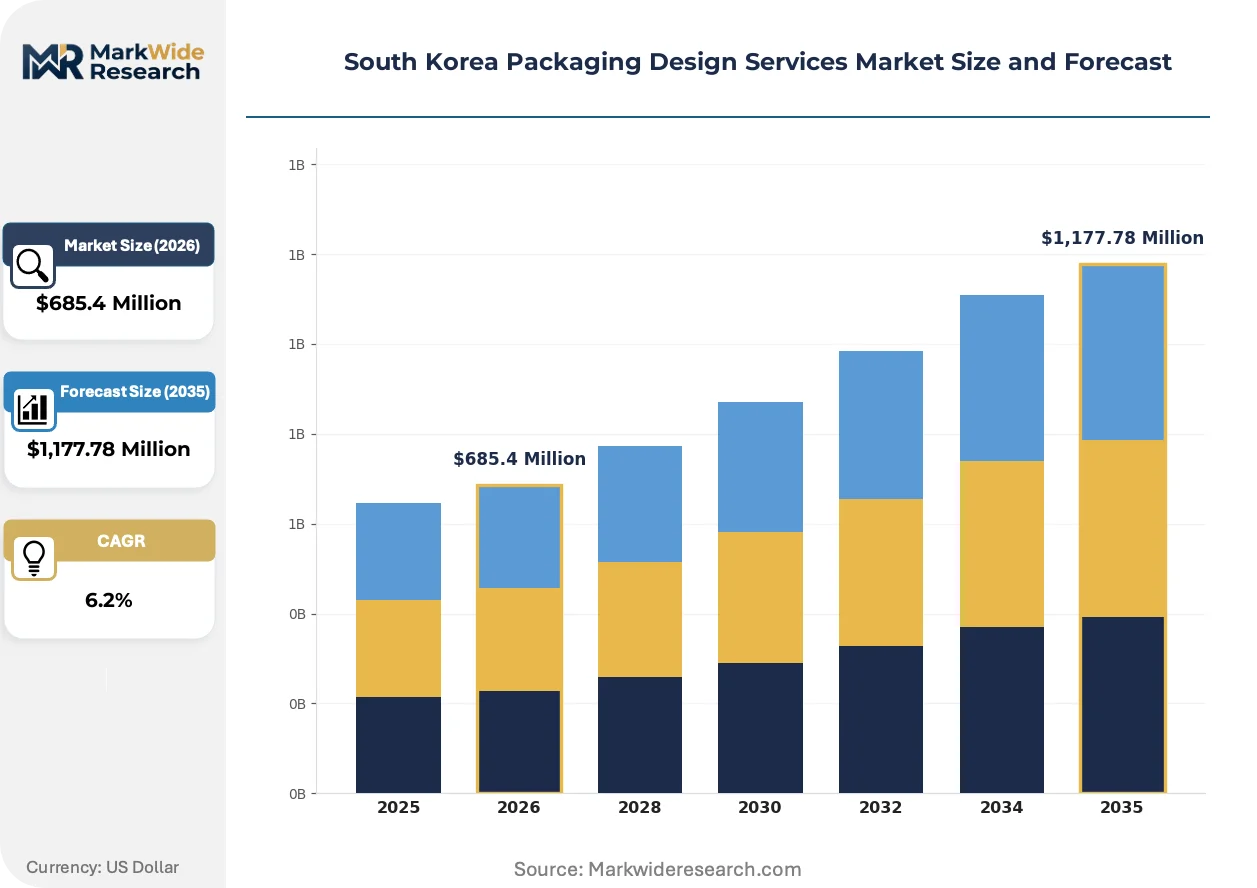
Market Dynamics
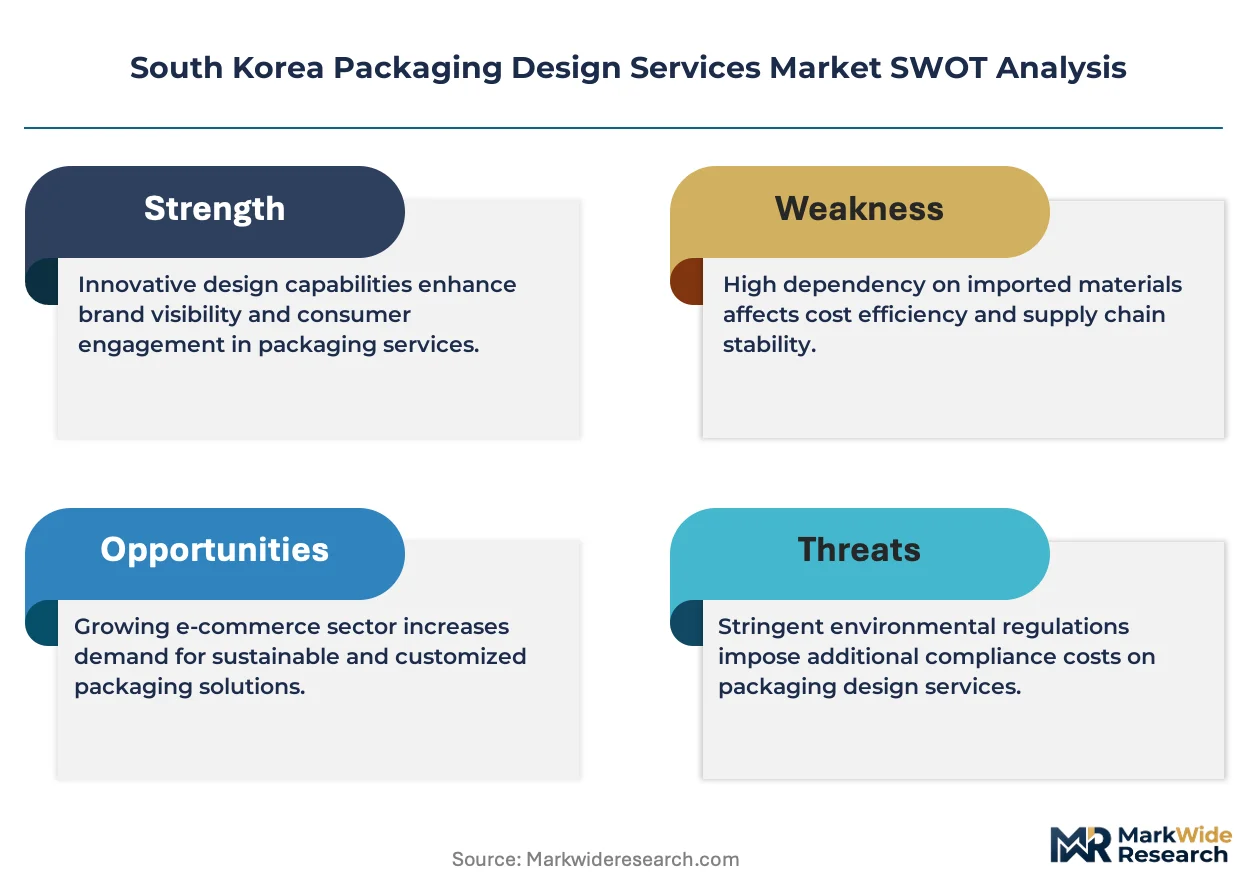
Premiumization across K-beauty exports is forcing structural packaging complexity upward, with brands commissioning multi-component dispensers and mono-material constructions that satisfy both shelf differentiation and the Ministry of Environment's recyclable packaging mandates.
Growth Catalysts
- MFDS Labeling Mandates:Strict content and legibility standards for pharmaceuticals and cosmetics are expanding design service contracts as brands commission multilingual compliance layouts and regulatory review workflows.
- Airless Pump Dispensing:Specialized closure systems that reduce preservative loads are penetrating premium skincare tiers, driving engineering-intensive structural design contracts.
- Seoul Agency Cluster:Concentration of creative talent and production-ready prototyping capabilities in the capital region accelerates turnaround times for mid-tier beauty brands seeking integrated design-to-manufacturing partnerships.
Market Restraints
- Petrochemical Input Volatility:Fluctuating polymer resin costs compress margins on fixed-price design contracts, particularly for polypropylene and polyethylene-based mono-material constructions.
- Single-Region Talent Concentration:Over 70% of specialized structural packaging engineers operate within Greater Seoul, creating bottleneck risks during peak product launch cycles.
- Extended Producer Responsibility:The Ministry of Environment's recyclable packaging rules impose material selection constraints that eliminate certain high-performance barrier films from cosmetic applications.
Strategic Opportunities
- Southeast Asia Export Expansion:K-beauty brands entering Vietnam and Indonesia require localized graphic design adaptation and humidity-resistant structural specifications.
- E-Commerce Durability Specifications:Drop-test certification and compression-resistant geometries are creating new service lines as direct-to-consumer shipment volumes rise.
- Digital Printing Convergence:Integration of short-run digital decoration with structural prototyping enables mass-customization pilots for limited-edition cosmetic releases.
Industry Challenges
- ISO 9001 Certification Timelines:Quality management system audits create 4-6 month vendor qualification delays, freezing design agencies out of major FMCG procurement cycles.
- Legacy CAD System Integration:Mid-tier manufacturers operate incompatible 3D modeling platforms, forcing manual file translation and tolerance errors during prototype handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Packaging Design Services Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Graphic Design, Structural Design, Prototyping, Consulting End User: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals Design Format: 3D Models, Labels, Boxes, Flexible Packaging Material Type: Paper, Plastics, Glass, Metals |
| Companies Covered | Amorepacific, Amcor Korea, Yonwoo, Sealed Air Korea, Berry Global, Kolmar Korea Packaging, LG Household & Health Care, ePac Seol, Samhwa Plastic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Packaging Design Services Market Trends and Innovations
Structural packaging engineering is fragmenting into specialized micro-verticals as digital prototyping tools compress development cycles and regulatory material bans force rapid specification pivots.
Mono-material polyethylene constructions are modularizing cosmetic primary packaging by eliminating multi-layer barrier films and separable closure components. Premium skincare brands adopting these specifications for recyclability compliance are collapsing traditional supplier tiers. The technology is modularizing what were previously integrated material-lamination and assembly workflows into discrete, interchangeable design modules.
MFDS enforcement of expanded label content requirements for functional cosmetics is extending graphic design review cycles by 30-40%. The industrial consequence is mandatory pre-submission regulatory consultation, which design agencies now bundle as a premium service tier. Pharmaceutical and cosmeceutical segments are responding by embedding former MFDS reviewers directly into agency creative teams.
Beauty brand procurement departments are consolidating design vendor rosters from 8-12 suppliers to 3-4 strategic partners capable of end-to-end structural-to-graphic workflows. Boutique agencies lacking in-house engineering capabilities are losing shelf-space presentation contracts to integrated studios. This concentration is most visible in Seoul's Gangnam and Seongsu-dong districts, where premium brand headquarters proximity drives face-to-face prototype iteration demands.
South Korea Packaging Design Services Market Segmentation
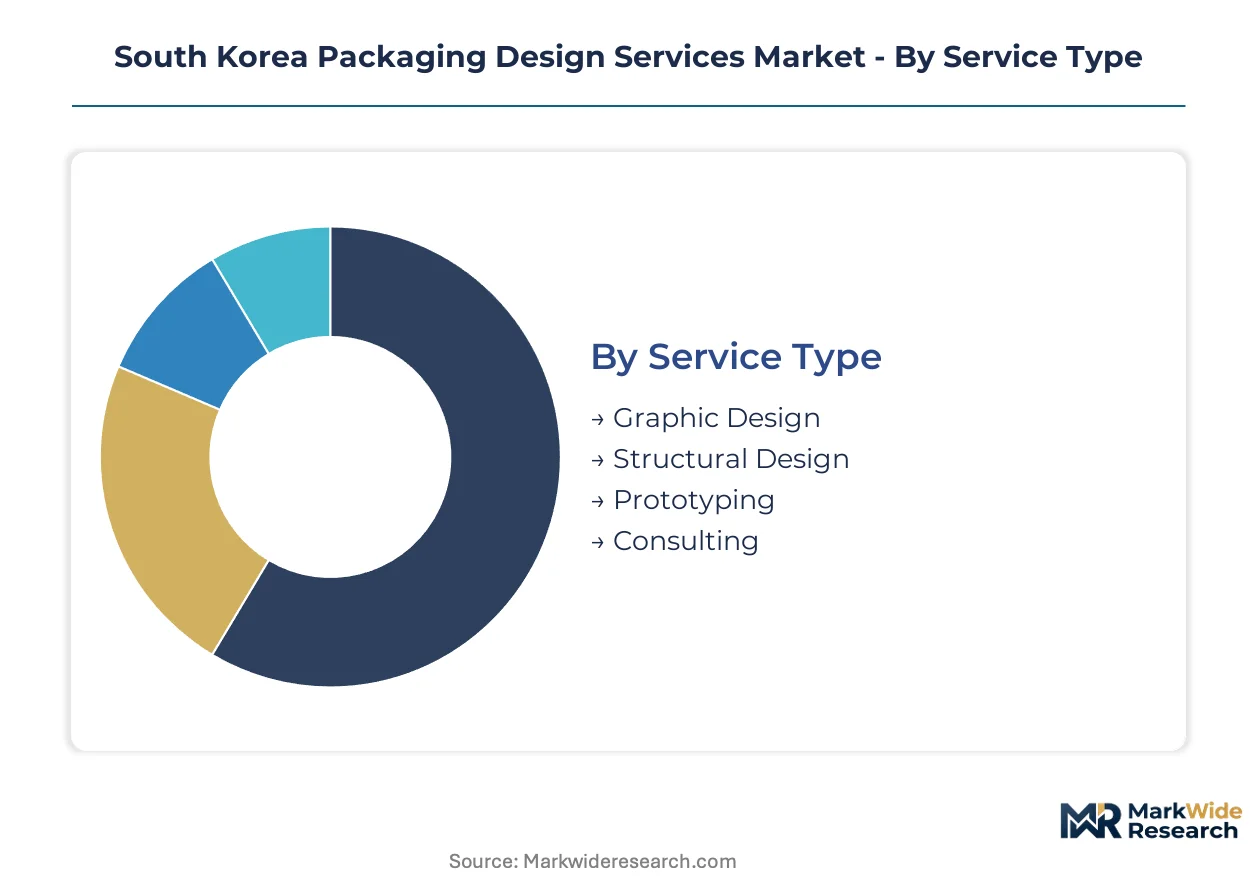
Packaging design services in South Korea fragment across technical disciplines, regulatory exposure, and material specifications. Each segment carries distinct certification burdens and margin profiles that shape vendor selection criteria for brand procurement teams.
Service Type:
ISO 9001 certification operates as a baseline qualifier across all service tiers, though MFDS regulatory review capabilities separate premium consulting engagements from commodity graphic production.
- Structural Design:Dimensional engineering for protective enclosures and shelf-differentiated geometries commands premium pricing due to tolerance requirements of 0.5 millimeters for precision-molded components. Cosmetics brands in Seoul's Gangnam district drive contract concentration here, commissioning multi-component dispensers that satisfy both premiumization goals and Ministry of Environment recyclable packaging mandates.
- Graphic Design:Layout development for regulatory label accuracy and multilingual compliance spans MFDS-mandated pharmaceuticals and export-facing K-beauty products. Stable margins persist in this segment as pre-submission regulatory consultation extends review cycles and agencies bundle compliance review as a premium service tier.
- Prototyping:Production-ready sample development with compressed turnaround times serves mid-tier beauty brands seeking integrated design-to-manufacturing partnerships in the Seoul agency cluster.
- Consulting:Strategic advisory on material selection and regulatory navigation addresses extended producer responsibility constraints and mono-material construction requirements.
Leading the category by volume: Structural Design. Growing fastest: Consulting.
End User:
Customer concentration patterns reveal divergent procurement behaviors, with export-oriented sectors demanding integrated structural-to-graphic workflows while domestic staples tolerate fragmented vendor rosters.
- Cosmetics:K-beauty premiumization and Southeast Asia export expansion fuel demand for humidity-resistant structural specifications and localized graphic adaptation. Amorepacific's in-house studio controls tier-one contracts, while mid-tier brands outsource to Seoul's integrated agencies.
- Food & Beverage:Snack and single-serve categories drive flexible packaging design volume, though petrochemical input volatility compresses margins on fixed-price contracts for polyethylene-based constructions.
- Electronics:Drop-test certification and compression-resistant geometries for direct-to-consumer shipment volumes create specialized e-commerce durability service lines.
- Pharmaceuticals:MFDS label content and legibility standards expand design contracts for multilingual compliance layouts, with former agency reviewers embedded directly into creative teams.
Dominant by contract value: Cosmetics. Steepest expansion trajectory: Electronics.
Design Format:
Format selection tracks downstream manufacturing infrastructure, with digital printing convergence enabling mass-customization pilots for limited-edition releases.
- Flexible Packaging:Film-based constructions for snack and single-serve food applications represent the format category expanding most quickly, driven by material lightweighting and logistics efficiency priorities.
- 3D Models:Digital prototyping tools compress development cycles for structural validation before physical sample commitment.
- Labels:Regulatory label accuracy requirements for MFDS-mandated sectors sustain stable demand for graphic precision and multilingual compliance.
- Boxes:Corrugated and rigid carton specifications serve e-commerce durability requirements and retail shelf presentation needs.
Highest throughput: Boxes. Most rapid technology shift: Flexible Packaging.
Material Type:
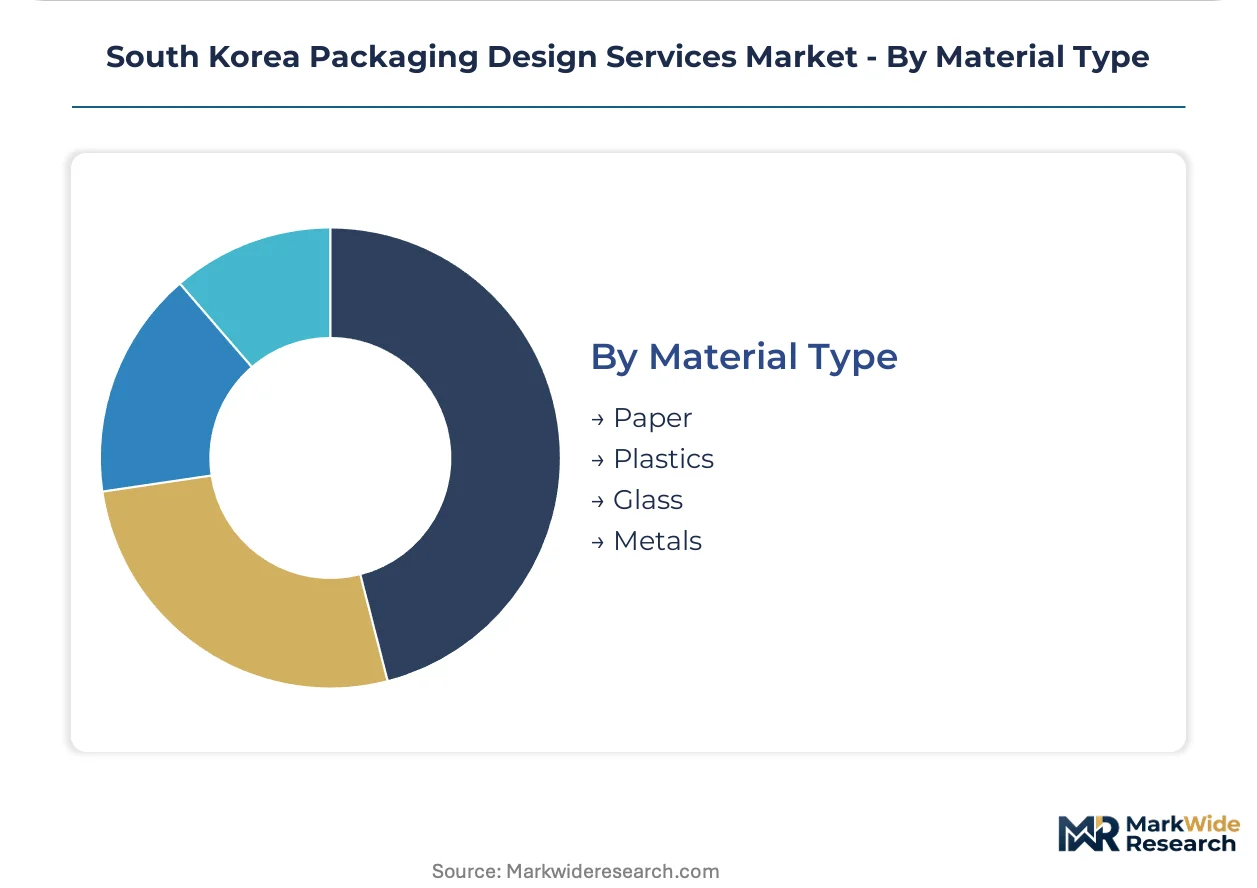
Material palettes are contracting under Ministry of Environment extended producer responsibility schemes that eliminate certain high-performance barrier films from cosmetic applications.
- Plastics:Mono-material polyethylene constructions modularize primary packaging by eliminating multi-layer barrier films, collapsing traditional supplier tiers into discrete interchangeable modules.
- Paper:Recyclable fiber-based substrates gain share in food and cosmetic secondary packaging as brands respond to municipal recycling infrastructure upgrades.
- Glass:Premium skincare and fragrance categories sustain demand for structural complexity in closure systems and decorative finishing.
- Metals:Aluminum and steel specifications concentrate in aerosol dispensers and luxury cosmetic primary packaging with extended shelf-life requirements.
Volume leader: Plastics. Fastest specification pivot: Paper.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area's design agency cluster concentrates contract volume through tax incentives for creative industry SMEs and proximity to premium brand headquarters in Gangnam and Seongsu-dong.
Seoul Capital Area
Cosmetics brands commission multi-component dispensers and mono-material constructions for K-beauty export packaging. MFDS labeling mandates for functional cosmetics extend graphic design review cycles. The Gangnam-Seongsu-dong corridor anchors integrated structural-to-graphic studios serving mid-tier beauty brands.
Busan-Ulsan
Petrochemical feedstock access supports flexible packaging design for snack and single-serve food categories. The Ministry of Environment's extended producer responsibility scheme shapes material selection toward recyclable polyethylene constructions. Ulsan's industrial port infrastructure enables rapid prototype-to-production handoffs for export-bound electronics packaging.
Daegu-Gyeongbuk
Textile and fashion accessory brands drive demand for rigid carton and specialty box specifications. Regional SME support programs subsidize ISO 9001 certification costs for design vendors. Daegu's emerging design studios capture secondary packaging contracts from Seoul-based brands seeking cost-competitive alternatives.
Daejeon-Sejong
Government procurement for public health and agricultural products sustains stable demand for regulatory-compliant label design. Sejong's administrative city status attracts MFDS-affiliated consultants embedding into agency creative teams. Daejeon's research institutes pilot digital printing convergence for mass-customization pilots.
Gwangju-Honam
Food processing clusters generate flexible packaging design contracts for humidity-resistant specifications targeting Southeast Asian export markets. Regional development grants fund prototyping equipment upgrades for mid-tier manufacturers. Gwangju's design schools feed talent into Seoul agencies while retaining boutique studios for local FMCG contracts.
South Korea Packaging Design Services Market Competitive Landscape
Top-tier vendors anchor integrated design-to-manufacturing workflows, while mid-tier boutiques compete on specialized structural engineering or regulatory consulting. The market structure concentrates around three archetypes: in-house studios of major beauty conglomerates, integrated agencies with production partnerships, and specialized engineering firms focused on closure systems and dispensing technology. Dominant competitive moves include vendor roster consolidation by brand procurement departments and backward integration into captive prototyping capabilities.
Within the in-house studio tier, Amorepacific exemplifies vertical control over brand consistency across multiple product tiers. Among integrated packaging specialists, Yonwoo occupies a position emphasizing airless pump technology and specialized dispensing closures, while Kolmar Korea Packaging anchors contract manufacturing relationships with design-to-production workflows. These three represent distinct strategic postures: captive creative control, engineering-led differentiation, and manufacturing-integrated service bundling.
| Leading Market Players |
|---|
| Amorepacific |
| Amcor Korea |
| Yonwoo |
| Sealed Air Korea |
| Berry Global |
| Kolmar Korea Packaging |
| LG Household & Health Care |
| ePac Seol |
| Samhwa Plastic |
| Others |
Pricing and Supply Chain Analysis
Digital printing convergence for mass-customization pilots simultaneously compresses prototyping cost economics and accelerates supplier consolidation around Seoul's integrated agencies. Mono-material polyethylene specification shifts eliminate multi-layer film suppliers, collapsing traditional tier structures into discrete interchangeable modules that reshape both procurement pricing and vendor qualification timelines.
Pricing Analysis
Short lead-time premiums dominate service pricing, with brands paying 15-25% markups for compressed turnaround on MFDS-compliant label iterations. Project-based contracts stratify across ISO 9001 certification tiers, after-sales regulatory bundling, and volume scale commitments. Cost compression in mid-tier structural design intensifies as petrochemical input volatility erodes fixed-price margins. Boutique agencies lacking captive prototyping capabilities face acute price sensitivity, while integrated studios command premium positioning through end-to-end workflow control.
Supply Chain Analysis
Single-source vulnerability sits with Greater Seoul's concentration of specialized structural engineers, where over 70% of talent operates within the capital region. Polymer resin supply draws from South Korea, China, and Japan, with polypropylene and polyethylene feedstock tethered to regional petrochemical complexes. Tariff exposure on imported barrier films compounds material selection constraints under Ministry of Environment extended producer responsibility schemes. Distribution runs through design-to-manufacturing partnerships anchored in the Gangnam-Seongsu-dong corridor, with secondary prototyping nodes emerging in Busan-Ulsan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over prototyping capabilities and regulatory consulting workflows determines contract capture. Players are pursuing downstream integration into production-ready sample development as the decisive competitive lever.
For Market Incumbents: Extend captive prototyping capabilities to defend against Seoul agency cluster consolidation, embedding former MFDS reviewers directly into creative teams to accelerate compliance workflows. Lock in mid-tier beauty brand contracts through integrated design-to-manufacturing partnerships before boutique competitors achieve ISO 9001 certification. Capacity addition in Busan-Ulsan petrochemical corridors secures resin cost advantages for mono-material constructions. For New Entrants and Emerging Players: The price-point gap between premium integrated studios and commodity graphic shops creates white-space opportunity in regulatory consulting bundling and digital printing convergence pilots. Target Daegu-Gyeongbuk regional SME support programs for subsidized certification entry, then leverage cost-competitive rigid carton specifications to capture secondary packaging overflow from Seoul brands. Go-to-market positioning centers on humidity-resistant structural specifications for Southeast Asia export expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by beauty conglomerates seeking captive creative control or integrated packaging specialists pursuing engineering-led differentiation. Long-term viability hinges on regulatory complexity deepening rather than simplifying across the analysis window. Acquisition target archetype: boutique agencies with embedded MFDS expertise and digital prototyping infrastructure. The signal to watch is Ministry of Environment material ban acceleration forcing rapid specification pivots that favor agile mid-tier players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prototyping | Captive sample development compresses turnaround times for mid-tier beauty brands seeking rapid iteration. |
| Regulatory Consulting Bundling | MFDS pre-submission review services command premium pricing as compliance complexity extends design cycles. |
| Digital Printing Convergence | Short-run decoration integration enables mass-customization pilots for limited-edition K-beauty releases. |
| Geographic Expansion to Busan-Ulsan | Petrochemical feedstock proximity reduces resin cost exposure for polyethylene-based mono-material constructions. |
| Certification Investment (ISO 9001) | Quality management credentials unlock major FMCG procurement cycles currently frozen to unqualified vendors. |
Research Methodology
Independent corroboration across packaging design agency principals, cosmetics brand procurement directors, and MFDS regulatory consultants underwrites the qualitative findings. Primary interviews with structural engineers, graphic design leads, and contract manufacturing executives combined with secondary validation from MFDS labeling guidelines, Ministry of Environment extended producer responsibility documentation, and Seoul municipal recycling infrastructure reports. Bottom-up service segmentation sizing and top-down market aggregation triangulate volume estimates.
Rate-of-change decomposition across service type, end-user industry, design format, and material specification dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth trajectories weighted by contract value concentration, with cosmetics premiumization, MFDS enforcement intensity, and mono-material adoption curves as key forecast inputs. Modeling incorporates Seoul agency cluster capacity constraints and regional petrochemical input cost volatility.
Inputs from regulatory filings and industry trade associations were available through the study window; gaps in real-time contract pricing transparency introduce uncertainty bands around service revenue segmentation. Forecasts reflect documented assumptions regarding MFDS labeling mandate expansion and Ministry of Environment material restriction timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Polypropylene Film Market
Packaging
Packaging Testing Equipment Market
Packaging
Silicone Storage Bags Market
Packaging
Europe Plastic Bottles and Containers Market
Packaging
Packaging Solutions Market
Packaging
Circular Industrial Bags Market
Packaging
Collapsible Food Packaging Containers Market
Packaging
Plastic Packaging Market
Packaging
Europe and USA Consumer Electronics Packaging Market
Packaging
Pharmaceutical Plastic Bottles Market
Packaging
Metallized Folding Cartons Market
Packaging
Envelope Paper Market
Packaging
Drink Hoses Market
Packaging
Bag-In-Bottle Market
Packaging
Senior Friendly Packaging Market
Packaging
Intermediate Bulk Container (IBC) Market