
 North America Single-Use Packaging Market | 2026-2036
North America Single-Use Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Single-Use Packaging Market Insights
The North America single-use packaging market is pivoting toward a sharp split between premium sustainable tiers and commodity virgin-material tiers. Novolex leverages its integrated film and bag manufacturing network to control cost positions across multiple substrate categories. Pactiv LLC anchors the foodservice disposables segment through its broad thermoformed and molded fiber portfolio. Dart Container Corporation dominates the insulated cup and container niche with specialized foam and paperboard expertise.
Single-use packaging encompasses disposable containers, wraps, bags, and serviceware engineered from plastics, paper, aluminum, or biodegradable materials for one-time product protection and consumption. These items typically feature barrier coatings, sealant layers, or structural ribs measured in mil thickness to control moisture, oxygen, and thermal transfer during distribution and end use. The plastics segment sustains volume leadership across food and beverage applications despite mounting regulatory pressure, while biodegradable materials compete for premium positioning in quick-service and specialty retail channels. Paper-based formats extend share in cold beverage and dry food segments where grease resistance requirements remain moderate.
The US EPA, state-level extended producer responsibility frameworks, and FDA food contact regulations collectively shape material compliance pathways and recycling infrastructure investment across the region. Canada's Competition Bureau and Health Canada enforce labeling and safety standards that restrict certain perfluorinated chemistries in molded fiber food packaging. Stakeholders must monitor evolving state patchworks in California, New York, and Washington where material bans and recycled content mandates are accelerating faster than federal harmonization efforts.
Market Dynamics
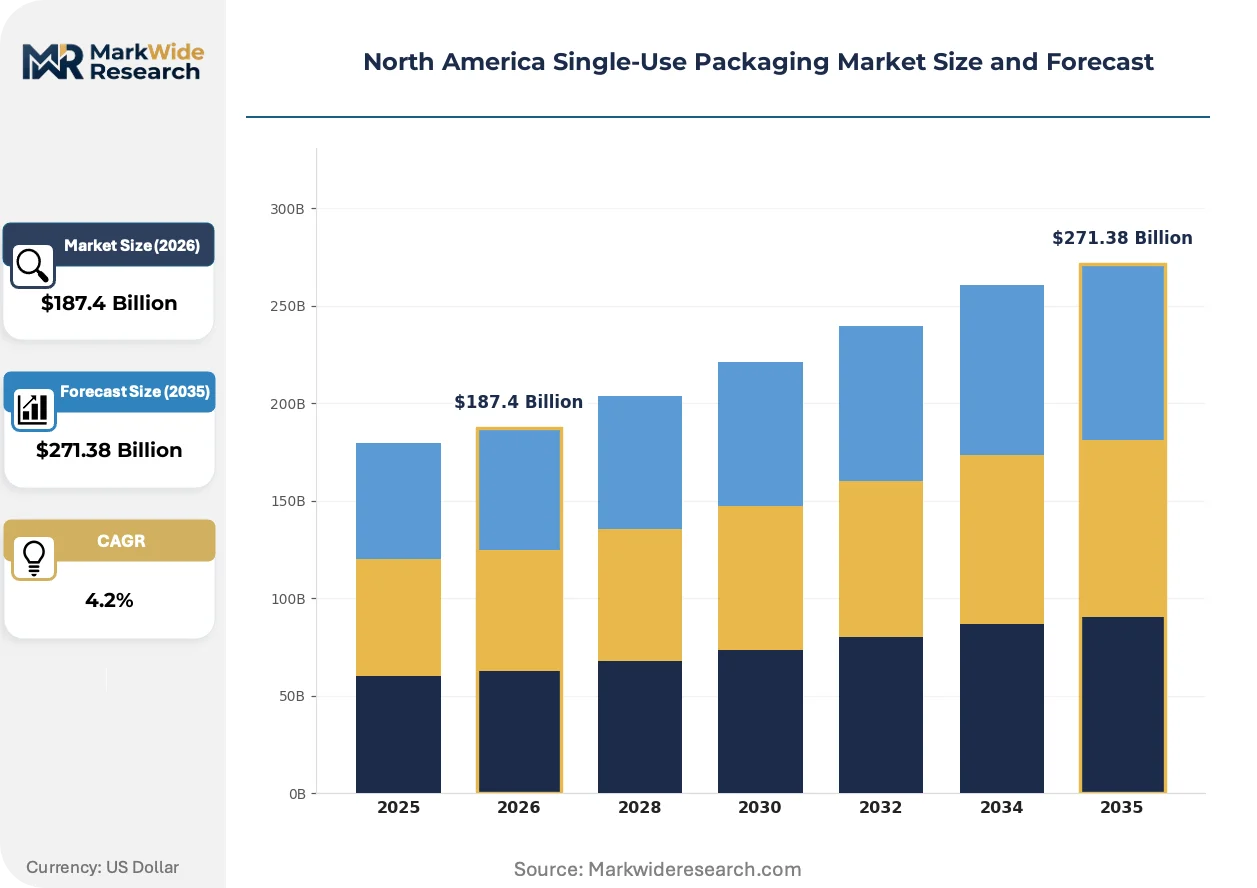
The North America single-use packaging market faces a structural squeeze between state-level material bans and the operational inertia of existing thermoforming and extrusion infrastructure. Extended producer responsibility laws in California, New York, and Washington are forcing capital redeployment toward post-consumer recycled feedstock processing before federal harmonization arrives.
Growth Catalysts
- Quick-service restaurant format expansion:Drive-thru and ghost kitchen proliferation across the US Southeast and Midwest generates sustained pull for disposable containers, wraps, and insulated bags calibrated to meal-kit dimensions.
- Post-consumer recycled content mandates:California's SB 54 and similar frameworks in Oregon and Colorado create compliance-driven demand pull for rPET and recycled paperboard food contact materials.
- Biodegradable barrier coatings:PLA and PHA formulations with enhanced grease resistance are penetrating specialty retail and prepared food channels where premium positioning offsets unit cost premiums.
Market Restraints
- Resin price volatility:Virgin polypropylene and polystyrene feedstock costs swing with natural gas liquids pricing from Gulf Coast petrochemical complexes, compressing margin predictability for thermoformed container producers.
- Molded fiber supply concentration:Domestic wet-lay molded fiber capacity clusters in Georgia and Wisconsin, creating geographic vulnerability to weather-related production interruptions.
- Perfluorinated chemistry restrictions:Health Canada's prohibition on PFAS in molded fiber food packaging and pending EPA action under TSCA Section 6 eliminate legacy grease-proofing solutions before fully scaled replacements achieve cost parity.
Strategic Opportunities
- Canadian provincial EPR acceleration:British Columbia and Ontario implementation timelines for packaging stewardship create first-mover advantage for suppliers with established recycled content verification systems.
- Aluminum cup adoption in stadium and arena channels:Infinitely recyclable aluminum formats are displacing plastic in large-venue beverage service where closed-loop collection infrastructure exists.
- Smart packaging integration:QR-coded traceability layers combining temperature logging with consumer engagement are converging with single-use formats in pharmaceutical cold chain and premium meal delivery segments.
Industry Challenges
- Food contact notification timelines:FDA's pre-market consultation process for novel biodegradable polymers stretches 18-24 months, delaying commercialization of compostable barrier innovations.
- Thermoforming equipment retrofit requirements:Transitioning from amorphous PET to rPET with higher intrinsic viscosity demands screw and dryer modifications that idle production lines for 6-8 weeks.
- Multi-material separation infrastructure:Existing municipal recycling streams lack optical sorting capability for paper-plastic laminate combinations, diverting technically recyclable formats to landfill despite design intent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Single-Use Packaging Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Paper, Aluminum, Biodegradable Materials Application: Food & Beverage, Personal Care, Healthcare, Household Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Retailers, Restaurants, Manufacturers, Service Providers |
| Companies Covered | Novolex, Pactiv LLC, Dart Container Corporation, Winpak Ltd., Berry Global Inc., Amcor Group GmbH, Sealed Air Corporation, Huhtamaki Oyj, Graphic Packaging International, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Single-Use Packaging Market Trends and Innovations
Active intelligence layers and substrate hybridization are displacing commodity specifications across foodservice and retail channels. Material science advances now enable functional performance previously requiring multi-material constructions.
Barrier-coated molded fiber technology is converging with aqueous-based grease-resistant chemistries to displace polyethylene-lined paperboard in hot food applications. Quick-service chains in California and Washington are piloting these formats ahead of 2025 compliance deadlines. The convergence is compressing acceptable performance thresholds for virgin plastic alternatives while elevating price tolerance for certified compostable tiers.
State extended producer responsibility frameworks are fragmenting compliance pathways faster than federal preemption efforts can harmonize them. California's SB 54 mandates 30% recycled content by 2028, while Washington's HB 5022 bans expanded polystyrene outright. Thermoformed container producers are responding with SKU proliferation—region-specific material specifications that multiply inventory complexity but defend market access.
Consolidated buying by third-party delivery platforms is compressing supplier negotiation cycles and unbundling legacy distributor relationships. DoorDash and Uber Eats procurement teams now specify packaging performance standards directly, displacing foodservice operator discretion. Platform-driven standardization is most visible in the Northeast corridor, where density supports dedicated supply agreements with national disposable manufacturers.
North America Single-Use Packaging Market Segmentation
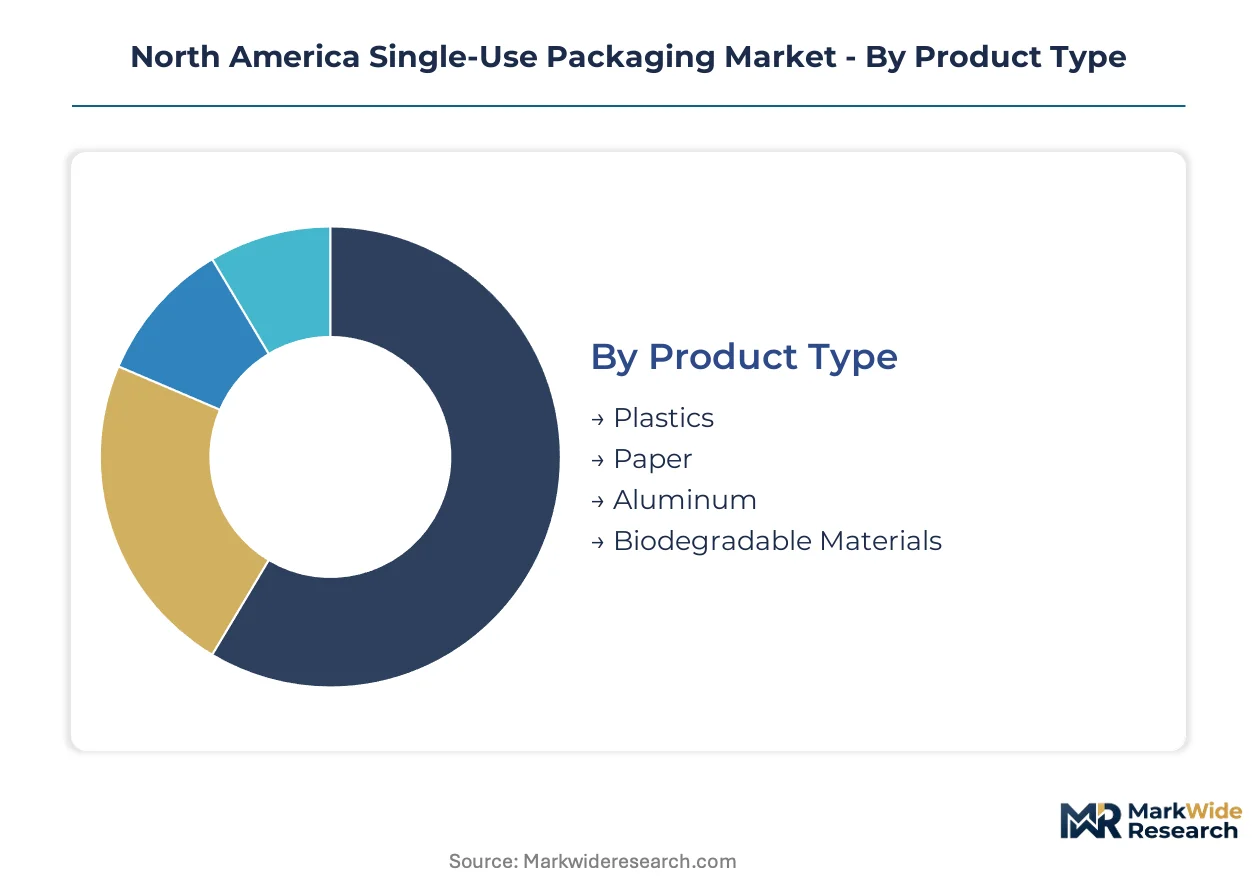
Segmentation in single-use packaging reveals how substrate selection, channel configuration, and end-use requirements fragment procurement patterns. Material specifications diverge sharply between quick-service foodservice and retail shelf applications, while regulatory compliance creates region-specific SKU proliferation.
Product Type:
Integration depth varies significantly across substrate categories, with some materials functioning as standalone solutions and others requiring multi-layer construction to achieve barrier performance.
- Plastics:Polyethylene, polypropylene, and PET formulations dominate thermoformed containers and flexible wraps through calibrated mil thickness and sealant layers. Demand concentrates in the US Southeast, where quick-service restaurant clusters along I-75 and I-95 corridors drive volume for clamshell containers and beverage cups. FDA food contact regulations and state-level recycled content mandates are forcing rapid rPET adoption despite intrinsic viscosity challenges in existing extrusion equipment.
- Paper:Kraft and paperboard substrates with polyethylene or aqueous barrier coatings serve cold beverage cups, dry food cartons, and molded fiber trays. The US Midwest hosts concentrated converting capacity near Wisconsin and Georgia pulp sources, though PFAS restrictions in Canada and pending EPA action under TSCA Section 6 are eliminating legacy grease-proofing chemistries before cost-competitive replacements achieve scale.
- Aluminum:Rolled foil and formed containers provide absolute moisture and oxygen barriers for prepared meals and pharmaceutical blister packs.
- Biodegradable Materials:PLA, PHA, and cellulose-based polymers target premium foodservice channels in California and Washington ahead of compliance deadlines.
Volume placements concentrate in plastics; the faster expansion belongs to biodegradable materials.
Application:
Cost tier stratification separates commodity foodservice specifications from premium healthcare and personal care requirements where barrier integrity commands price tolerance.
- Food & Beverage:Thermoformed containers, flexible wraps, and insulated cups calibrated to meal-kit dimensions and drive-thru formats. Quick-service restaurant expansion across Texas, Florida, and Georgia generates sustained pull, while California's SB 54 mandates reshape material specifications toward post-consumer recycled content.
- Personal Care:Sachets, pouches, and blister packs with moisture barriers for cosmetics and hygiene products.
- Healthcare:Sterile barrier systems and pharmaceutical cold chain packaging with temperature logging integration.
- Household:Trash bags, storage containers, and cleaning product packaging where cost minimization dominates procurement.
Food and beverage captures the dominant volume position; healthcare presents the steepest expansion trajectory as cold chain requirements intensify.
Distribution Channel:
Customer type fragmentation separates platform-driven standardization from legacy distributor relationships, with procurement authority shifting toward consolidated buyers.
- Online Retail:E-commerce platforms specifying performance standards directly, unbundling traditional foodservice distribution in the Northeast corridor where DoorDash and Uber Eats density supports dedicated supply agreements.
- Supermarkets:Private-label prepared food and deli packaging with moderate barrier requirements.
- Specialty Stores:Premium and certified compostable tiers for organic and specialty retail channels.
- Wholesale:Volume contracting for institutional foodservice and manufacturing procurement.
Wholesale retains the largest volume footprint; online retail is climbing the fastest as platform consolidation restructures procurement authority.
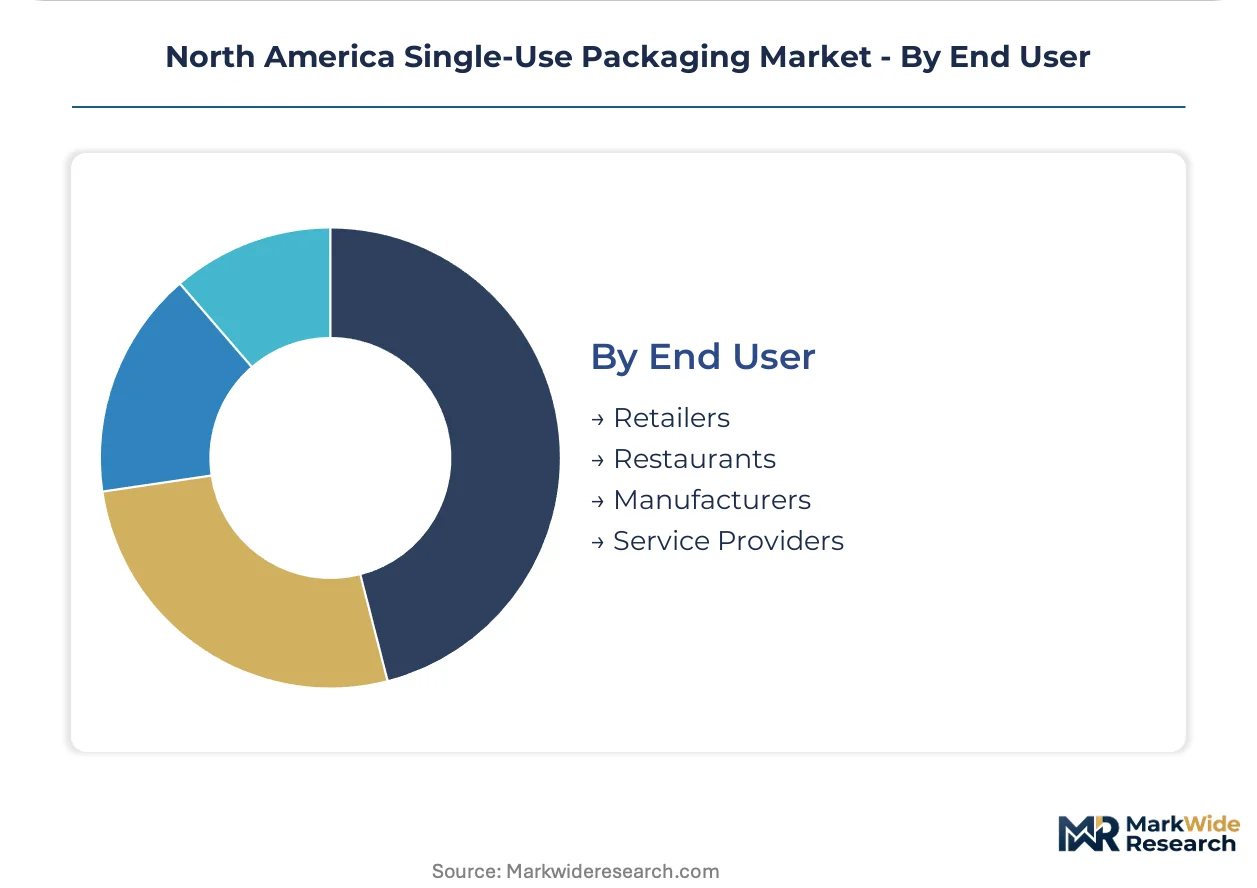
End User:
Geographic concentration of end-use demand follows food processing clusters and logistics corridors, with distinct specification requirements across customer categories.
- Retailers:Private-label packaging for prepared foods and shelf-stable goods, with recycled content mandates driving material transitions in California, New York, and Washington stores.
- Restaurants:Quick-service and full-service operators expanding takeout and ghost kitchen formats across the US Southeast and Midwest.
- Manufacturers:Food processors and consumer goods companies with captive packaging specifications tied to production line speeds.
- Service Providers:Third-party logistics, catering, and institutional foodservice with standardized disposable requirements.
Restaurants command the highest volume placements; retailers are gaining share fastest as extended producer responsibility laws shift compliance burdens upstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta anchors North American single-use packaging demand through its convergence of quick-service restaurant headquarters, distribution hubs along I-75, and converting capacity for thermoformed containers. The metropolitan corridor processes meal-kit volumes for chains expanding drive-thru formats across the Southeast.
United States
California's SB 54 mandates 30% post-consumer recycled content by 2028, forcing rPET adoption in thermoformed clamshells and beverage cups. The EPA's evolving recycling infrastructure grants reshape material compliance pathways nationwide. Texas and Florida quick-service clusters along I-10 and I-95 corridors generate sustained pull for insulated bags and disposable containers calibrated to delivery platform specifications.
Canada
British Columbia and Ontario extended producer responsibility implementation timelines create compliance-driven procurement shifts toward verified recycled content systems. Health Canada and the PMRA enforce PFAS prohibitions in molded fiber food packaging that eliminate legacy grease-proofing chemistries. Quebec's pulp and paper converting capacity near Montreal supplies barrier-coated paperboard for cold beverage applications across Eastern Canada.
Mexico
Nuevo León's manufacturing corridor near Monterrey hosts thermoforming operations supplying quick-service chains expanding across northern Mexico. The country's national environmental regulator accelerates waste management framework updates that align with USMCA trade compliance. Jalisco's Guadalajara metro area concentrates flexible packaging converting for personal care and household product exports to the United States.
North America Single-Use Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification tiers, with post-consumer recycled content verification and compostable certification separating pricing power. The market structure consolidates around integrated film-to-bag manufacturers and specialized thermoformers, with three archetypes dominating: substrate-integrated conglomerates controlling resin-to-converting pipelines, regionally focused foodservice specialists, and sustainability-certified niche players commanding contract premiums. Capacity expansion and strategic partnerships represent the dominant competitive moves, as producers secure rPET feedstock agreements and co-develop barrier coatings with chemical suppliers.
Within the substrate-integrated tier, Novolex and Berry Global exemplify scale-driven positions spanning multiple plastic categories. Pactiv LLC and Dart Container Corporation occupy specialized foodservice niches with thermoformed and molded fiber expertise. Sealed Air Corporation anchors protective and flexible packaging applications where barrier performance commands specification authority.
| Leading Market Players |
|---|
| Novolex |
| Pactiv LLC |
| Dart Container Corporation |
| Winpak Ltd. |
| Berry Global Inc. |
| Amcor Group GmbH |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Graphic Packaging International, LLC |
| Others |
Pricing and Supply Chain Analysis
rPET feedstock premiums cascade through thermoformed container pricing tiers, with California's SB 54 recycled content mandates compressing margins for converters lacking backward integration into post-consumer resin processing. This cost pressure stratifies procurement across quick-service chains, institutional foodservice, and retail private-label channels.
Pricing Analysis
Certified compostable performance anchors value-based pricing for biodegradable barrier coatings in California and Washington compliance-driven channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA food contact certified rPET from virgin polypropylene and unlined molded fiber. Pricing pressure stems from resin price volatility tied to Gulf Coast natural gas liquids. Quick-service restaurant procurement teams show highest price sensitivity, while pharmaceutical cold chain buyers tolerate premiums for temperature-logging integration.
Supply Chain Analysis
Direct-to-foodservice-operator channels handle national quick-service chain demand, while third-party delivery platforms consolidate procurement authority in the Northeast corridor. Wet-lay molded fiber capacity clusters in Georgia and Wisconsin, with thermoforming operations concentrated in Nuevo León's Monterrey corridor. Raw material dependencies center on virgin polypropylene from Gulf Coast petrochemical complexes, Canadian pulp for barrier-coated paperboard, and imported PLA resin. Single-source vulnerability runs through Georgia's molded fiber concentration exposed to hurricane disruption. Distribution runs through legacy broadline distributors and emerging platform-direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-consumer recycled feedstock scarcity props pricing power for integrated resin-to-converting operations, with California's compliance deadlines compressing available rPET supply ahead of capacity expansion.
For Market Incumbents: Anchor market position through captive rPET processing agreements with municipal MRF operators and thermoforming equipment retrofits for higher intrinsic viscosity recycled feedstock. Defend against platform procurement consolidation by embedding directly into DoorDash and Uber Eats specification frameworks. Prioritize barrier coating R&D partnerships with aqueous chemistry suppliers ahead of EPA TSCA Section 6 PFAS restrictions. For New Entrants and Emerging Players: Enter via Canadian provincial EPR implementation windows in British Columbia and Ontario where recycled content verification systems remain underdeveloped. Target aluminum cup formats in stadium and arena channels where closed-loop collection infrastructure supports premium positioning. Pursue co-development agreements with quick-service chains piloting molded fiber alternatives in California ahead of compliance deadlines. For Investors and Strategic Acquirers: FDA food contact notification clearance for novel biodegradable polymers is the leading indicator that compostable barrier innovations will achieve commercial scale. Long-term viability favors substrate-integrated conglomerates with resin-to-converting pipeline control and established post-consumer feedstock relationships. Monitor Health Canada PFAS enforcement timelines as signal for molded fiber chemistry replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Feedstock Integration | Captive post-consumer resin processing locks in California SB 54 compliance cost positions. |
| Barrier Coating Co-Development | Aqueous grease-resistant chemistry partnerships displace PFAS ahead of EPA action. |
| Platform Direct Embedding | DoorDash and Uber Eats procurement integration unbundles legacy distributor relationships. |
| Canadian EPR Pre-Positioning | British Columbia and Ontario stewardship system readiness commands first-mover premiums. |
| Aluminum Cup Format Expansion | Stadium and arena closed-loop infrastructure supports infinitely recyclable premium tiers. |
Research Methodology
Multi-period observation of rPET capacity utilization, state EPR implementation timelines, and quick-service restaurant format expansion anchored the trend analysis, supplemented by interviews with thermoforming plant managers, quick-service procurement directors, pulp and paper technical R&D leads, and third-party delivery platform supply chain specialists. Secondary validation drew from EPA recycling infrastructure grant disclosures, FDA food contact notification databases, California SB 54 regulatory filings, and SEC 10-K disclosures from substrate-integrated packaging conglomerates. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Input-output matrices mapped resin feedstock flows through converting operations to end-use channels across the projection horizon. Segmentation dimensions modeled include substrate category, application barrier requirement, distribution channel configuration, and regional regulatory cluster. CAGRs derived from trend extrapolation of format adoption rates and compliance-driven material substitution elasticities. Forecast inputs incorporated thermoforming equipment retrofit lead times and FDA pre-market consultation duration distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA PFAS prohibition timelines or hurricane disruption of Georgia molded fiber capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
PCR Packaging Market
Packaging Materials
EPE Liner Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Card Films Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Flow Wraps Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
VCI Shrink Films Market