
 Neoprene Coffee Sleeves Market | 2026-2036
Neoprene Coffee Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Neoprene Coffee Sleeves Market Foresight
Aftermarket branding and custom-print programs is reshaping margin capture in neoprene coffee sleeves, shifting value from commodity insulation toward design-led retention tools. Huhtamaki leverages its foodservice packaging scale to bundle sleeves with cup systems for large QSR accounts. WestRock Company anchors its position through integrated fiber-based packaging portfolios that cross-sell into cafe supply chains. Novolex competes by controlling domestic manufacturing footprints that shorten lead times for regional roasters.
Neoprene coffee sleeves are synthetic rubber foam accessories, typically three to five millimeters thick, laminated with polyester or nylon outer layers to provide thermal insulation and grip for disposable and reusable beverage cups. Their primary commercial purpose is brand visibility and user comfort in away-from-home coffee consumption. Reusable sleeves command premium positioning among environmentally positioned cafes, while custom sleeves with logo branding concentrate margin pools in loyalty-driven hospitality segments. Insulated sleeves lead functional demand in high-temperature specialty drink applications.
FDA food-contact material regulations govern neoprene composition and surface treatments for domestic U.S. distribution, while the EU REACH framework restricts certain chemical additives in synthetic rubber articles sold across member states. California's Proposition 65 labeling requirements add compliance layers for products entering West Coast retail channels. Stakeholders must monitor how state-level packaging extended producer responsibility bills reshape cost allocation between sleeve manufacturers and downstream cafe operators.
Market Dynamics
Branded sleeve programs at specialty coffee chains are restructuring procurement relationships, shifting purchasing power from independent distributors toward direct manufacturer partnerships that bundle design services with volume commitments.
Growth Catalysts
- EU Single-Use Plastics Directive:Foodservice operators across member states are redirecting procurement toward reusable neoprene alternatives, creating mandated demand pools for insulated sleeve suppliers.
- Third-wave cafe expansion:Independent roasters in Portland and Seattle are scaling custom-print sleeve programs as customer retention tools, embedding sleeves into loyalty marketing workflows.
- Closed-cell foam lamination:Advances in polyester-nylon bonding are improving thermal performance thresholds, enabling penetration into high-temperature specialty drink applications previously served by double-cupping.
Market Restraints
- Petrochemical feedstock volatility:Neoprene production depends on chloroprene monomer derived from butadiene, exposing manufacturers to crude-linked input cost swings without pass-through mechanisms in fixed-price QSR contracts.
- China-dominant synthetic rubber supply:Chloroprene capacity concentrates in Shandong and Jiangsu provinces, creating geographic concentration risk for Western sleeve fabricators without backward integration into polymer production.
- California Proposition 65 labeling friction:The state's warning requirements for chemical additives in synthetic rubber articles add compliance layers that delay West Coast retail channel entry for non-domestic suppliers.
Strategic Opportunities
- Corporate branded merchandise channel:Tech firms and professional services companies are adopting custom coffee sleeves as conference swag and employee onboarding kits, opening B2B revenue streams outside traditional foodservice.
- EU Green Deal procurement incentives:Public sector catering contracts now prioritize reusable serviceware, positioning neoprene sleeves for municipal concession and institutional foodservice penetration.
- RFID-embedded inventory tracking:Convergence of neoprene fabrication with near-field communication tags enables cafes to monitor sleeve circulation and optimize wash-cycle logistics for reusable programs.
Industry Challenges
- Multi-jurisdiction chemical compliance:Sleeve manufacturers must simultaneously satisfy FDA food-contact rules, EU REACH substance restrictions, and state-level labeling laws, stretching regulatory affairs capacity at mid-tier suppliers.
- Screen-printing color-matching precision:Brand consistency demands across Pantone-specified corporate identities require capital investment in spectrophotometer-equipped production lines that smaller decorators cannot justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neoprene Coffee Sleeves Market |
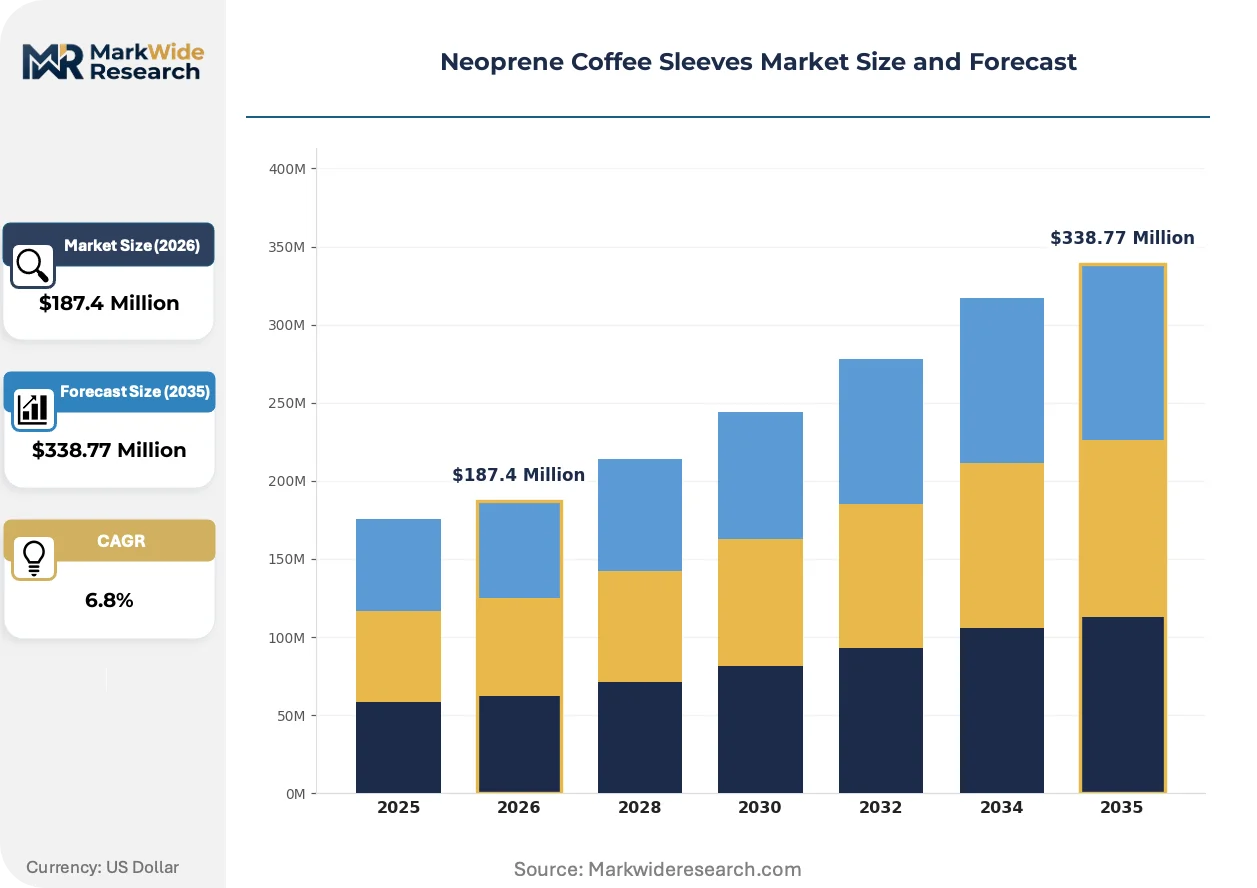
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Sleeves, Disposable Sleeves, Custom Sleeves, Insulated Sleeves End User: Cafes, Restaurants, Retail Stores, Home Users Design Feature: Printed Patterns, Solid Colors, Textured Finish, Logo Branding Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Huhtamaki, Coveris Holdings S.A, Mondi Group, Smurfit Kappa Group, Graphic Packaging International, WestRock Company, Novolex, Sabert Corporation, Genpak, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neoprene Coffee Sleeves Market Shifts & Advancements
Material science advances and regulatory pressure are converging to transform neoprene coffee sleeves from commodity insulation into data-carrying, brand-activated touchpoints. Three developments are restructuring competitive requirements.
Closed-cell neoprene is hybridizing with conductive thread matrices to create temperature-sensing sleeves that communicate with mobile payment systems. High-volume QSR operators in South Korea are piloting these connected accessories to trigger loyalty rewards at point-of-purchase. The technology is compressing the traditional separation between physical serviceware and digital customer engagement infrastructure.
REACH substance restrictions on short-chain chlorinated paraffins are forcing reformulation of neoprene surface treatments used in EU-bound sleeves. German sleeve fabricators are accelerating adoption of water-based adhesives to maintain market access. The regulatory squeeze most affects mid-size decorators without in-house polymer chemistry capabilities, pushing consolidation toward integrated compounders.
Subscription-based sleeve replenishment is displacing spot purchasing among multi-location cafe operators. Roaster-owned retail chains in Australia are bundling sleeve resupply into equipment lease agreements, transferring inventory risk upstream. The model is most visible in Melbourne and Sydney where third-wave coffee density supports logistics network economics for reusable serviceware pooling.
Neoprene Coffee Sleeves Market Segmentation
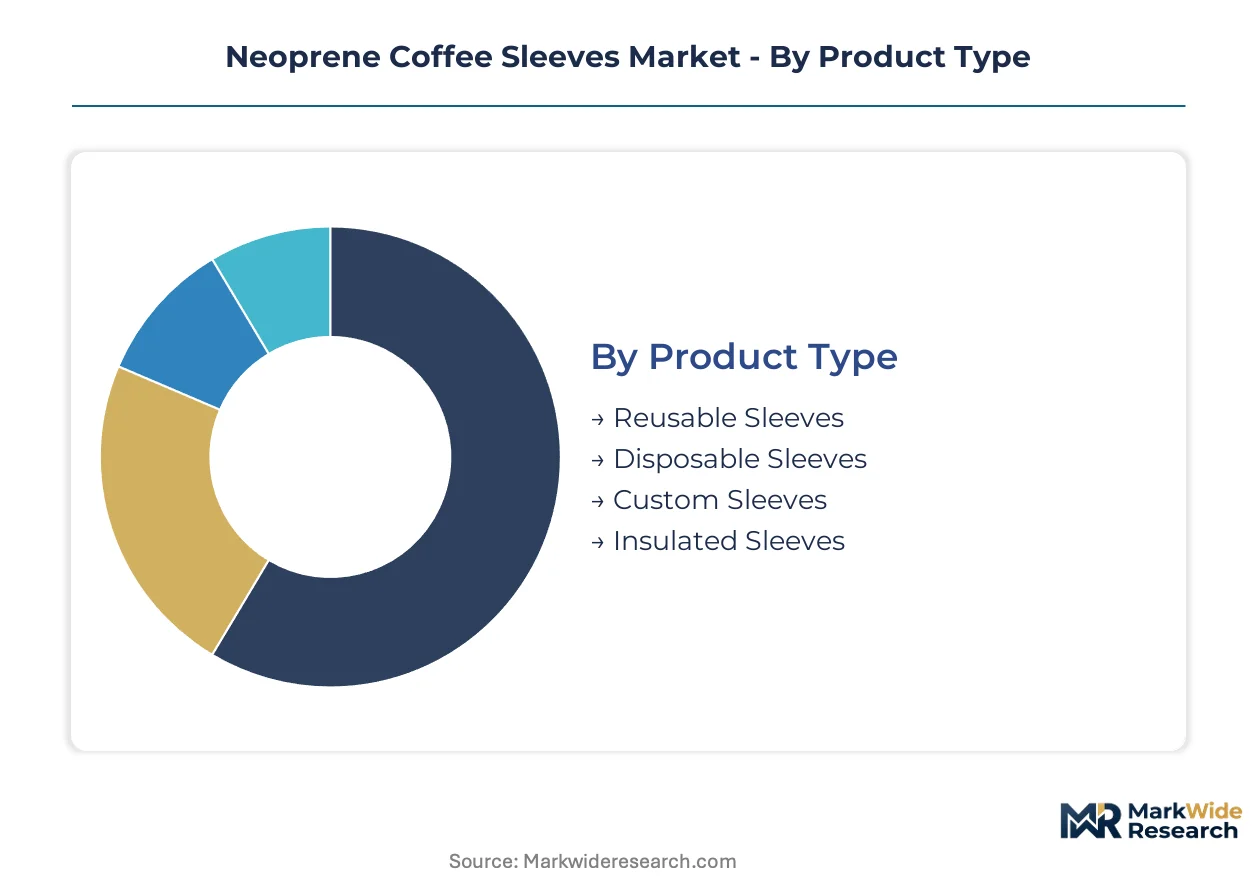
Neoprene coffee sleeve procurement splits sharply between high-frequency operational buyers and episodic consumer purchasers. After-sales intensity varies dramatically across these divides, with commercial accounts demanding design refresh cycles and inventory management support that individual consumers rarely trigger.
Product Type:
After-sales service intensity peaks with reusable and custom programs, where sleeve lifecycles extend across multiple wash cycles and brand refreshes.
- Reusable Sleeves:Constructed from closed-cell neoprene with reinforced stitching and moisture-wicking polyester laminates rated for 500+ wash cycles. Portland and Seattle third-wave cafes are concentrating procurement here, driven by EU Single-Use Plastics Directive compliance mandates and customer retention metrics tied to loyalty program enrollment.
- Custom Sleeves:Feature Pantone-matched screen printing and die-cut shapes specified to corporate identity guidelines. Specialty coffee chains in the Pacific Northwest dominate volume, embedding sleeves into seasonal merchandise drops and limited-edition collaborations with regional roasters.
- Disposable Sleeves:Thin-gauge neoprene alternatives to corrugated cardboard for single-use insulation. QSR operators in high-throughput airport and highway locations specify these for cost containment.
- Insulated Sleeves:Multi-layer constructions with thermal break foams for 180°F+ beverage applications. High-temperature specialty drink operators in South Korea are piloting these for connected loyalty integrations.
By volume, disposable sleeves lead. By growth pace, reusable sleeves are climbing the fastest.
End User:
Cost tier stratification separates premium branded programs from commodity bulk purchasing across buyer categories.
- Cafes:Independent roasters and third-wave operators in Portland and Seattle drive custom sleeve innovation, bundling design services with volume commitments.
- Restaurants:Full-service and fast-casual chains prioritize thermal performance specifications for takeout beverage programs.
- Retail Stores:Grocery and convenience channels stock impulse-purchase sleeves near checkout, favoring solid-color SKUs with minimal SKU complexity.
- Home Users:Direct-to-consumer purchasers through Amazon and specialty kitchen retailers, typically buying single units or small multipacks for personal use.
Cafes command the highest per-account revenue. Home users are expanding most quickly as remote work normalizes personal coffee rituals.
Design Feature:
Application context dictates design selection, with commercial branding requirements diverging sharply from residential aesthetic preferences.
- Logo Branding:Corporate identity applications with vector-art reproduction requirements and color-fastness specifications for commercial laundering.
- Printed Patterns:Seasonal and collaborative designs featuring regional artists or limited-edition motifs for collector-driven demand.
- Solid Colors:Inventory-efficient SKUs for retail distribution and institutional procurement with minimal design approval cycles.
- Textured Finish:Embossed or debossed surface treatments for enhanced grip and tactile differentiation in premium positioning.
Logo branding dominates commercial accounts. Printed patterns are gaining share fastest among independent roasters.
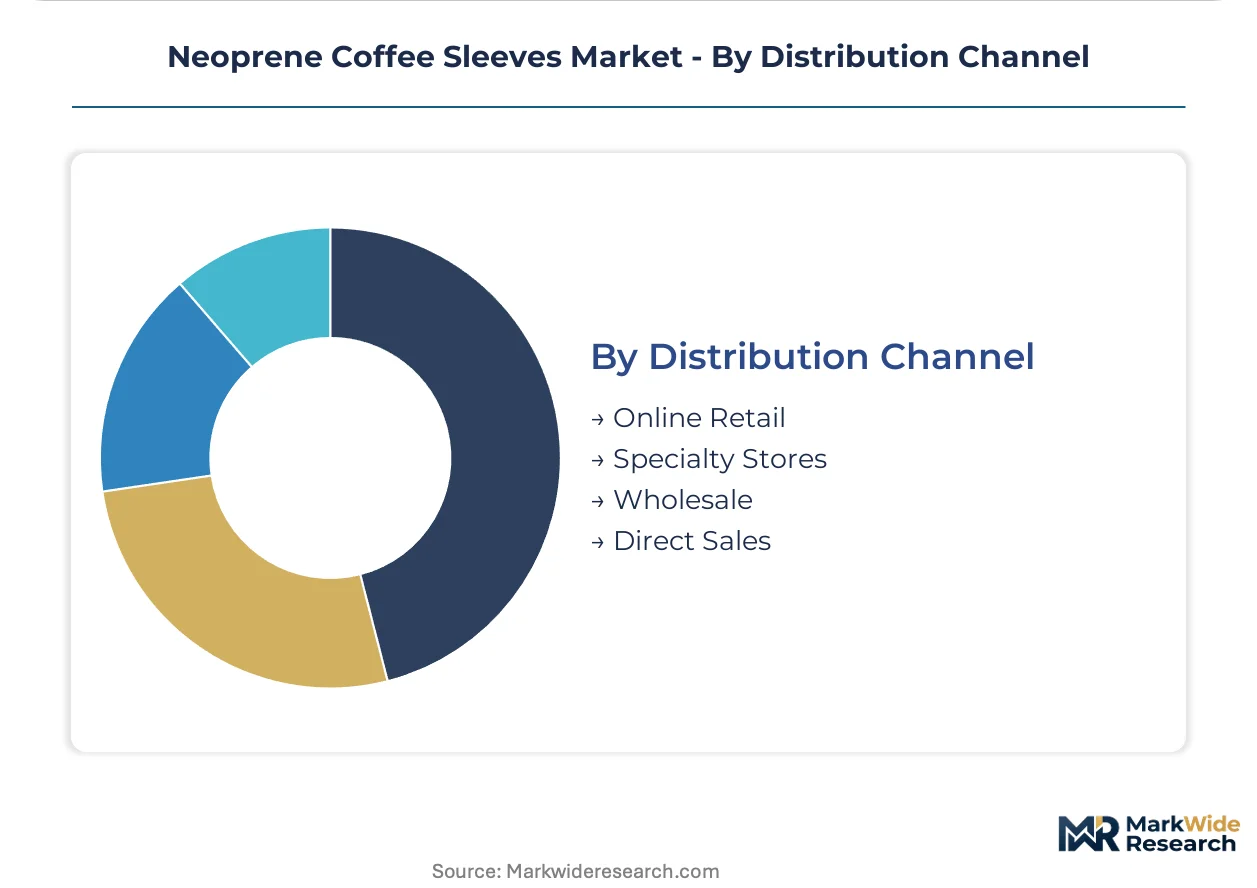
Distribution Channel:
Customer type concentration shapes channel economics, with direct relationships capturing margin from high-volume operators while intermediaries serve fragmented demand.
- Direct Sales:Manufacturer-to-cafe relationships bundling design services, volume pricing, and replenishment scheduling for multi-location operators.
- Wholesale:Foodservice distributors stocking standard SKUs for independent restaurants and smaller cafe chains with irregular reorder patterns.
- Online Retail:Amazon, Etsy, and specialty kitchen sites serving home users and small business purchasers with low minimum order quantities.
- Specialty Stores:Kitchenware boutiques and coffee equipment retailers curating premium and artisanal sleeve selections for enthusiast consumers.
Direct sales lead by revenue concentration. Online retail is expanding most quickly as digital procurement habits solidify among smaller operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chloroprene monomer capacity clusters in Shandong and Jiangsu provinces, concentrating raw material access for Asian fabricators while Western converters absorb transport premiums and currency exposure.
United States
Third-wave cafe operators in Portland and Seattle drive custom sleeve procurement as loyalty program anchors. FDA food-contact regulations govern neoprene composition for interstate distribution. Pacific Northwest roasting clusters embed sleeve design into seasonal merchandise drops with regional artist collaborations.
Germany
REACH substance restrictions on short-chain chlorinated paraffins force reformulation of neoprene surface treatments for EU-bound production. Water-based adhesive adoption accelerates among fabricators serving institutional catering contracts. Bavarian industrial converters supply municipal concession operators prioritizing reusable serviceware under Green Deal procurement.
South Korea
High-volume QSR operators pilot RFID-embedded sleeves triggering mobile payment loyalty rewards. MFDS food-contact standards regulate synthetic rubber articles for domestic distribution. Seoul Capital Area cafe chains compress physical-digital engagement through temperature-sensing sleeve prototypes.
Australia
Roaster-owned retail chains in Melbourne and Sydney bundle sleeve resupply into equipment lease agreements. National packaging extended producer responsibility frameworks reshape cost allocation between manufacturers and operators. Victoria-based third-wave coffee density supports logistics network economics for reusable serviceware pooling.
Canada
Health Canada regulates food-contact synthetic rubber under Division 23 of the Food and Drug Regulations. British Columbia and Ontario independent cafes import Pacific Northwest design aesthetics for branded sleeve programs. Toronto roasting clusters leverage cross-border supplier relationships with US converters for Pantone-matched corporate identity reproduction.
Neoprene Coffee Sleeves Market Competitive Landscape
Integrated packaging conglomerates and specialized fabricators split the market into divergent margin capture models. Tiered concentration persists: multinational foodservice suppliers bundle sleeves with cup systems for QSR accounts, while regional decorators serve independent roasters with shorter lead times. Three archetypes dominate—scale-driven bundlers, speed-focused regionalists, and design-led specialists. Capacity expansion and direct manufacturer partnerships represent the dominant competitive vectors as procurement power shifts from distributors toward brand-direct relationships.
Among scale-driven bundlers, Huhtamaki and WestRock Company exemplify the integrated foodservice packaging archetype, leveraging cross-category portfolios to anchor large-account relationships. Novolex occupies a position within the speed-focused tier, with domestic manufacturing footprints shortening replenishment cycles for regional operators. These three represent divergent strategic postures: bundling breadth, fiber-based integration, and geographic proximity respectively.
| Leading Market Players |
|---|
| Huhtamaki |
| Coveris Holdings S.A |
| Mondi Group |
| Smurfit Kappa Group |
| Graphic Packaging International |
| WestRock Company |
| Novolex |
| Sabert Corporation |
| Genpak, LLC |
| Others |
Supply & Pricing Matrix
Chloroprene monomer capacity clustering in Shandong and Jiangsu provinces anchors raw material access for Asian fabricators, compressing margin pools for Western converters who absorb transport premiums and currency exposure while competing on design services and replenishment speed.
Pricing Analysis
California Proposition 65 dictates the pricing tier structure for neoprene coffee sleeves entering West Coast retail channels. Three-tier pricing stratifies across premium custom programs with Pantone-matched corporate identities, standard reusable sleeves for EU compliance-driven procurement, and economy disposable alternatives for high-throughput QSR locations. Price differentiation hinges on certification grade for FDA food-contact compliance and volume scale in direct manufacturer partnerships. Cost compression in the economy tier is intensifying because petrochemical feedstock volatility lacks pass-through mechanisms in fixed-price contracts. Independent roasters show least price sensitivity, prioritizing design refresh cycles and loyalty program integration over unit economics.
Supply Chain Analysis
Supply-chain finance facilities with extended payment terms have become critical competitive tools for neoprene sleeve fabricators serving multi-location cafe operators. Manufacturing gravity centers on China, Vietnam, and Germany, with Shandong province dominating chloroprene polymer production. Raw material dependencies rest on butadiene-derived chloroprene monomer, polyester-nylon laminates, and water-based adhesive formulations. Single-source vulnerability concentrates in Chinese chloroprene capacity, exposing Western converters to geographic concentration risk without backward integration into polymer production. Distribution runs through direct manufacturer-to-cafe relationships for volume accounts, supplemented by foodservice distributors for fragmented independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
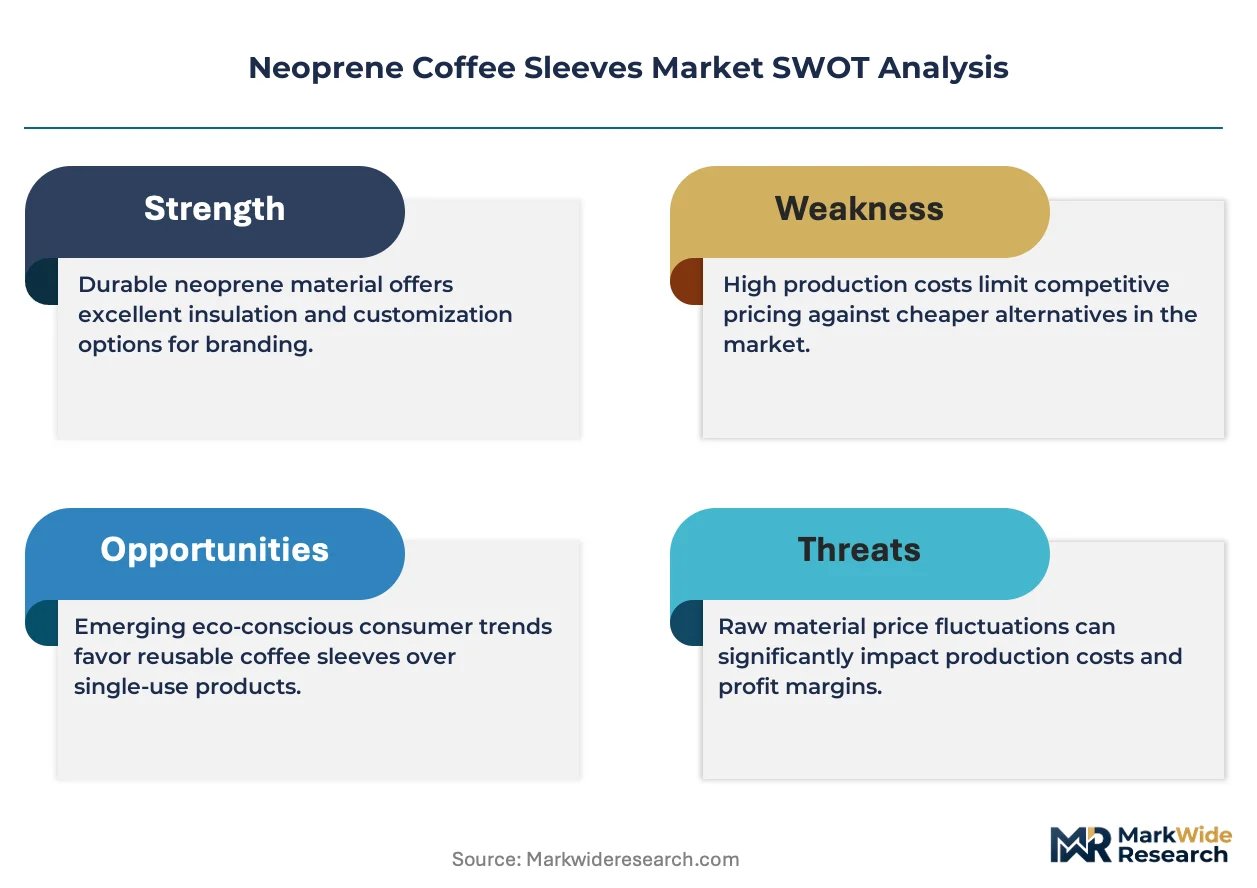
Neoprene coffee sleeves function as a service-attach opportunity where design refresh subscriptions and wash-cycle logistics management are expanding faster than hardware unit sales, shifting value capture toward recurring revenue architectures.
For Market Incumbents: Build switching-cost moats through embedded RFID inventory tracking systems that lock cafes into proprietary replenishment platforms. Consolidate position by acquiring regional decorators with spectrophotometer-equipped production lines to eliminate Pantone color-matching bottlenecks. Threat from REACH substance restrictions on short-chain chlorinated paraffins demands accelerated water-based adhesive R&D investment. Channel control through direct manufacturer partnerships represents the critical defensive lever against distributor disintermediation.
For New Entrants and Emerging Players: Corporate branded merchandise channels at tech firms and professional services companies represent the most penetrable entry point, with conference swag and employee onboarding kits opening B2B revenue streams outside saturated foodservice procurement. Municipal concession operators under EU Green Deal procurement incentives offer institutional white-space with lower competitive intensity than third-wave cafe strongholds. Go-to-market angle should emphasize subscription-based sleeve replenishment bundled into equipment lease agreements, transferring inventory risk upstream while capturing recurring revenue.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier decorators with in-house polymer chemistry capabilities positioned to capture consolidation forced by REACH reformulation requirements. Long-term viability across the five-to-ten year window favors suppliers integrating design services with logistics infrastructure for reusable program management. Signal to watch is RFID-embedded sleeve pilot scale-up among South Korean QSR operators, indicating technology maturation timing for Western market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Design Service Integration | Bundles Pantone-matched screen printing with volume commitments, locking Pacific Northwest roasters into multi-year relationships. |
| Water-Based Adhesive Transition | Maintains EU market access as REACH restrictions eliminate short-chain chlorinated paraffin surface treatments. |
| RFID Embedding Capability | Enables temperature-sensing sleeves that trigger mobile payment loyalty rewards at Seoul QSR locations. |
| Subscription Replenishment Model | Transfers inventory risk to manufacturers while capturing recurring revenue from Melbourne equipment lease agreements. |
| Domestic Manufacturing Footprint | Shortens lead times for regional roasters, defending against Shandong-based chloroprene supply concentration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact guidance documents, EU REACH substance restriction databases, and SEC filings from integrated packaging conglomerates. Primary interviews engaged procurement directors at Pacific Northwest third-wave cafe chains, regulatory affairs leads at neoprene fabricators, and design managers at specialty coffee roasters. Secondary validation drew from customs trade data on chloroprene monomer flows, foodservice distributor inventory reports, and state-level extended producer responsibility bill tracking. Bottom-up demand modeling from cafe operator procurement patterns triangulates against top-down market sizing from synthetic rubber article trade classifications.
Forecast inputs span reusable versus disposable sleeve adoption curves, EU Single-Use Plastics Directive implementation timelines across member states, and closed-cell foam lamination technology penetration rates. Segmentation dimensions include product type, end-user category, design feature complexity, and distribution channel structure, with regional regulatory cluster as an additional modeled variable. CAGRs derive from weighted scenario analysis across the projection horizon, incorporating petrochemical feedstock volatility assumptions and third-wave cafe expansion trajectories in Portland, Seattle, Melbourne, and Sydney.
Stress conditions across chloroprene monomer price volatility, REACH substance restriction expansion scope, and QSR contract renewal rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EU Green Deal procurement incentive durability and RFID-embedded sleeve technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Mailer Packaging Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Urn Liners Market
Packaging Materials
VCI Films Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Reel in Box Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Construction Films Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
EPE Liner Market
Packaging Materials
Cold Form Foil Market