
 Stick Packaging Market | 2026-2036
Stick Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Stick Packaging Market Analysis
ISO 15378 certification for primary packaging materials is bifurcating the competitive field into qualified pharmaceutical suppliers and generalist converters. Amcor plc leverages its global film extrusion network to sustain multi-region supply agreements for stick pack laminates. Catalent, Inc. anchors its position through integrated formulation-fill-finish services that pair drug development with dedicated stick packaging lines. Constantia Flexibles competes via specialized aluminum-barrier structures that extend shelf life for moisture-sensitive active ingredients.
Stick packaging denotes a narrow, sealed flexible pouch format, typically 10–40 mm in width, formed from laminated film or foil composites on vertical form-fill-seal machines to deliver precise single-unit doses of powders, liquids, or semi-solids. The format minimizes material use versus bottles or jars while enabling on-the-go consumption across food, pharmaceutical, and personal care applications. Single-serve configurations dominate volume in instant beverage and nutraceutical channels where portion control drives repeat purchase behavior. Composite materials command margin premiums due to multi-layer barrier engineering that satisfies oxygen and moisture ingress specifications for pharmaceutical stability.
FDA cGMP guidelines and EU MDR requirements govern pharmaceutical stick packaging validation, while REACH and EU Packaging and Packaging Waste Regulation constrain material composition and end-of-life obligations for consumer formats. These frameworks elevate compliance costs for entrants but protect incumbent investments in qualified production assets. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based film performance benchmarks to align capital allocation with regulatory trajectory.
Market Dynamics
Precision filling equipment manufacturers around Düsseldorf and Cologne are consolidating technical expertise, creating geographic chokepoints that constrain capacity expansion for pharmaceutical-grade stick packaging lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material recovery mandates for single-serve formats are accelerating converter investment in recyclable laminate structures.
- Instant beverage channels:Portion-controlled powder formats are displacing bulk canisters in on-the-go consumption occasions.
- Aluminum-barrier engineering:Multi-layer foil composites are extending shelf life specifications for moisture-sensitive active pharmaceutical ingredients.
Market Restraints
- Aluminum foil supply concentration:European rolling mill capacity limits constrain laminate availability for high-barrier pharmaceutical applications.
- ISO 15378 certification timelines:Validation protocols for primary packaging materials extend qualification cycles for new market entrants.
- Flexible pouch substitution:Three-side-seal sachets compete on equipment compatibility in lower-specification food segments.
Strategic Opportunities
- Bio-based film convergence:Cellulose-derived barriers paired with conventional aluminum layers are opening pharmaceutical sustainability positioning.
- Oral dissolvable films:Thin-film drug delivery formats are migrating from blister packs to stick-compatible geometries.
- Extended producer responsibility schemes:Deposit-return pilots in Germany are creating first-mover advantages for recyclable mono-material structures.
Industry Challenges
- Electromechanical integration:Servo-driven filling systems require specialized maintenance capabilities scarce in contract packaging networks.
- Legacy equipment retrofit:Mechanical form-fill-seal machines demand substantial modification to handle sustainable film substrates with divergent sealing profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stick Packaging Market |
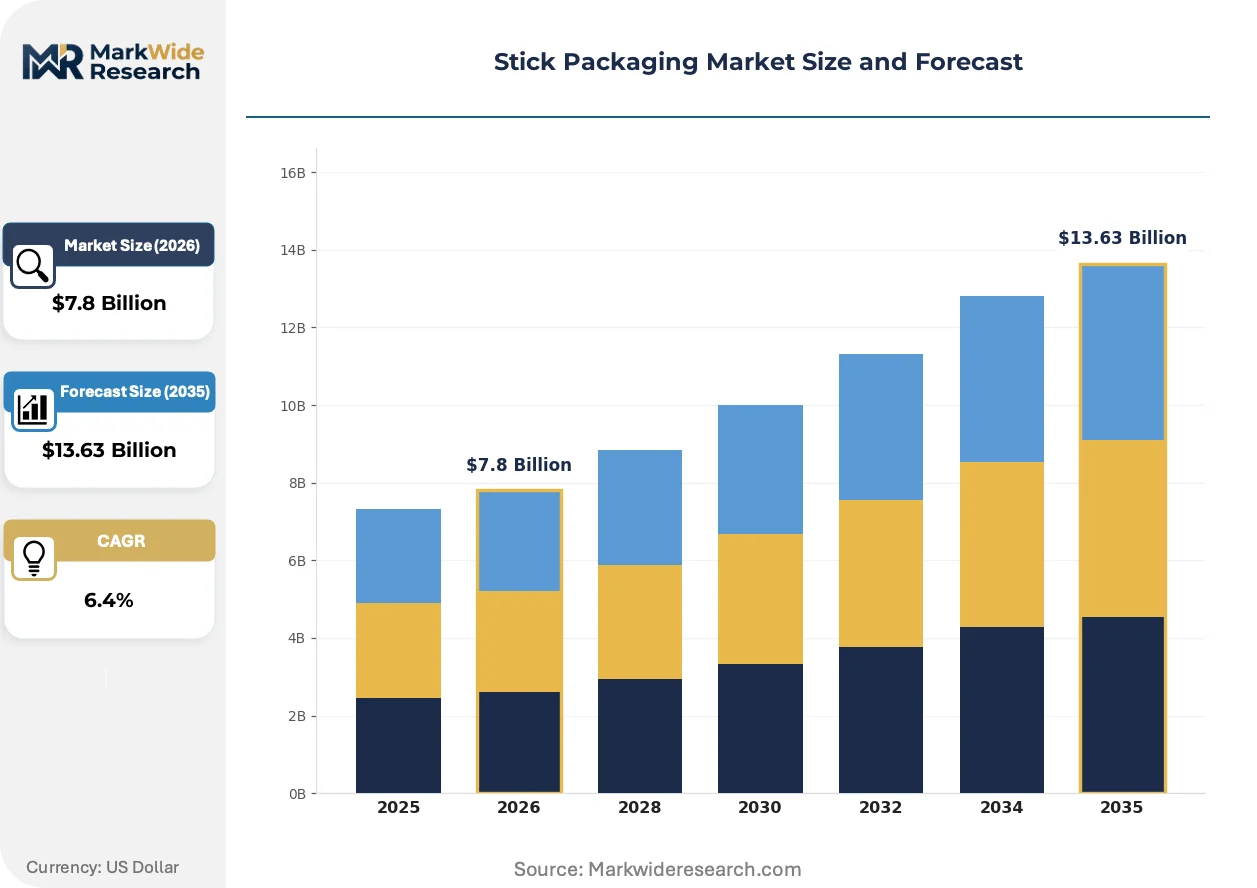
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve, Multi-Serve, Sachets, Tubes Material: Plastic, Aluminum, Paper, Composite End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Packaging Type: Flexible, Rigid, Vacuum Sealed, Resealable |
| Companies Covered | ProAmpac, Catalent, Inc., Amcor plc, ePac Holdings, LLC, Taghleef Industries, Constantia Flexibles, Glenroy, Inc., Winpak Ltd., Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stick Packaging Market Emerging Trajectories
Active pharmaceutical ingredient stability requirements are forcing laminate engineers to reconsider barrier hierarchies, while sustainability mandates compress acceptable material portfolios.
High-speed laser scoring for easy-open functionality is bifurcating equipment specifications between pharmaceutical cleanroom environments and standard food-grade production floors. Nutraceutical contract manufacturers are adopting scored stick packs to differentiate adult nutrition products. The technology is bifurcating capital allocation between validated pharmaceutical lines and flexible food-grade installations.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy greaseproof coatings from laminate specifications. Converters must reformulate heat-seal layers without fluorinated performance additives. Pharmaceutical applications in Germany face the tightest compliance timelines as notified bodies prioritize MDR-aligned packaging assessments.
Hospital procurement coalitions are consolidating stick pack purchasing for unit-dose analgesics and electrolyte replacements, displacing fragmented pharmacy buying. Group purchasing organizations are negotiating multi-year supply agreements with integrated formulation-fill-finish providers. This concentration is most pronounced in German acute care networks seeking inventory reduction through direct-to-ward delivery models.
Stick Packaging Market Segmentation
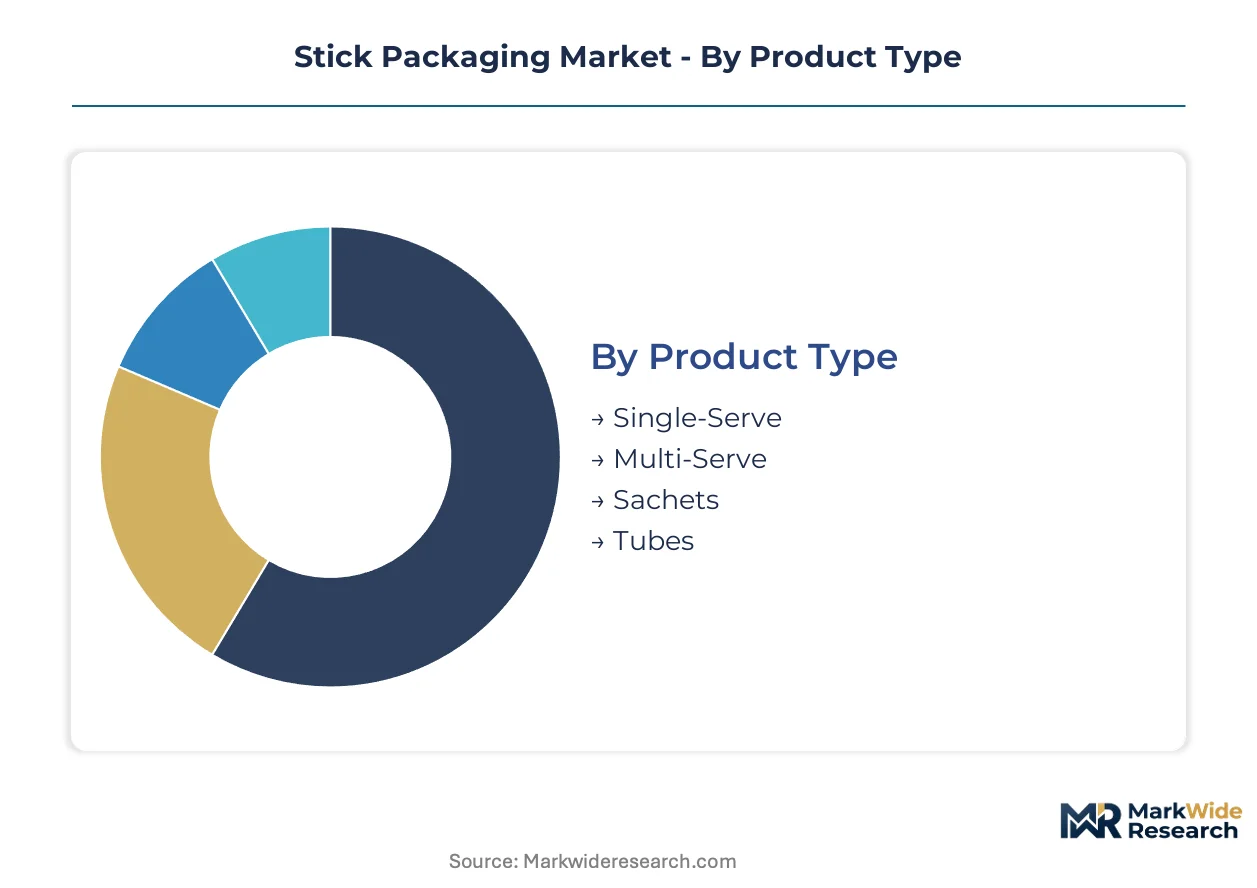
Segmentation in stick packaging reveals how material choices, portion formats, and end-use specifications create divergent margin structures. Manufacturers optimize line configurations around these boundaries to capture premium positions in pharmaceutical stability applications versus high-volume food service channels.
Product Type:
Margin pools concentrate in precision-dose formats where filling accuracy commands equipment premiums and technical service fees.
- Single-Serve:Narrow 10–40 mm pouches formed on vertical form-fill-seal machines deliver exact unit doses of powders, liquids, or semi-solids. Pharmaceutical contract manufacturers in Germany cluster filling lines around Düsseldorf and Cologne to supply hospital procurement coalitions with unit-dose analgesics and electrolyte replacements.
- Multi-Serve:Extended-length sticks contain 2–5 servings for household pantry stocking, common in instant beverage channels where portion-controlled formats displace bulk canisters. Food brands leverage this format for trial-size conversion while maintaining production compatibility with single-serve lines.
- Sachets:Three-side-seal flat pouches compete directly with stick formats in lower-specification food segments, offering equipment compatibility advantages for contract packers with legacy machinery.
- Tubes:Cylindrical extruded formats accommodate semi-solid and paste contents in personal care applications, requiring specialized sealing heads that limit line flexibility.
The dominant share belongs to Single-Serve, while Multi-Serve is closing the gap fastest.
Material:
Barrier engineering intensity determines cost tier positioning, with multi-layer structures capturing pharmaceutical premiums.
- Plastic:Mono-material polyethylene and polypropylene films dominate food-grade volumes, though REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of heat-seal layers without fluorinated additives.
- Aluminum:Foil layers provide oxygen and moisture barriers essential for active pharmaceutical ingredient stability. European rolling mill capacity constraints limit laminate availability for high-barrier applications, creating supply chokepoints.
- Paper:Cellulose-based substrates support sustainability positioning in nutraceutical channels, though moisture sensitivity restricts applications without complementary barrier coatings.
- Composite:Multi-layer laminates combining plastic, aluminum, and paper command the highest margins by satisfying pharmaceutical stability specifications while enabling recyclable structure design under EU Packaging and Packaging Waste Regulation targets.
Composite structures hold the revenue concentration, though Plastic retains the volume lead.
End User:
Regulatory validation requirements fragment the competitive field between qualified pharmaceutical suppliers and generalist converters.
- Food & Beverage:Instant beverage channels drive repeat purchase behavior through portion-controlled powder formats. On-the-go consumption occasions favor stick packs over bulk canisters for convenience and freshness perception.
- Pharmaceuticals:FDA cGMP guidelines and EU MDR requirements govern validation protocols for primary packaging materials. ISO 15378 certification timelines extend qualification cycles, protecting incumbent investments in qualified production assets.
- Personal Care:Scored stick packs with laser-cut easy-open functionality differentiate adult nutrition products, though this technology bifurcates capital allocation between validated pharmaceutical lines and flexible food-grade installations.
- Household:Unit-dose detergents and cleaning agents leverage stick formats for portion control and reduced storage footprint, competing with rigid pod alternatives on sustainability metrics.
Pharmaceuticals commands the premium tier, with Food & Beverage scaling fastest.
Packaging Type:
Equipment flexibility and sealing technology maturity shape competitive positioning across format categories.
- Flexible:Film-based stick packs minimize material use versus bottles or jars, forming the core volume driver across all end-use segments.
- Rigid:Semi-rigid structures accommodate crush-sensitive contents in personal care, requiring modified forming shoulders on standard form-fill-seal machines.
- Vacuum Sealed:Oxygen exclusion extends shelf life for oxidation-sensitive ingredients, common in nutraceutical applications with polyunsaturated fatty acids.
- Resealable:Zipper or adhesive closure additions serve multi-serve formats, adding cost and complexity that limits adoption to premium household and personal care segments.
Flexible formats dominate unit economics, while Resealable features are gaining traction in household applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement coalitions in Germany concentrate purchasing for unit-dose pharmaceuticals, while instant beverage brands in the United States and Japan drive food-grade volume. Regulatory divergence between FDA cGMP guidelines and EU MDR requirements shapes converter qualification strategies across major demand centers.
Germany
Precision filling equipment manufacturers cluster around Düsseldorf and Cologne to supply pharmaceutical contract manufacturers with high-output stick packaging lines. The EU Packaging and Packaging Waste Regulation tightens material recovery targets for single-serve formats, accelerating investment in recyclable laminate structures. Hospital procurement coalitions in North Rhine-Westphalia consolidate purchasing for unit-dose analgesics and electrolyte replacements.
United States
Instant beverage channels displace bulk canisters with portion-controlled powder formats for on-the-go consumption. FDA cGMP guidelines govern validation protocols for pharmaceutical stick packaging, extending qualification cycles for new market entrants. Contract packaging networks in the Northeast and Midwest face capability gaps for servo-driven filling system maintenance.
Japan
Oral dissolvable films migrate from blister packs to stick-compatible geometries in nutraceutical applications. METI standards and PMDA regulations align packaging assessments with pharmaceutical stability requirements. Industrial concentrations in the Kanto and Kansai regions support precision-dose manufacturing for adult nutrition products.
China
Domestic instant beverage brands scale stick pack adoption for single-serve coffee and tea powders. NMPA regulations and GB standards constrain material composition for pharmaceutical-grade laminates. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta expand vertical form-fill-seal capacity for export markets.
India
Nutraceutical contract manufacturers adopt scored stick packs to differentiate products in adult nutrition channels. CDSCO and FSSAI regulations fragment compliance requirements between pharmaceutical and food-grade formats. Production facilities in Maharashtra and Gujarat invest in laser-scoring equipment for easy-open functionality.
Stick Packaging Market Vendor Landscape
Player mix skews toward integrated packaging conglomerates with global film extrusion networks and specialized pharmaceutical contract manufacturers with dedicated formulation-fill-finish capabilities. Tiered competitive dynamics separate ISO 15378-certified suppliers serving stability-critical applications from generalist converters in food-grade segments. Two strategic archetypes dominate: multi-region laminate suppliers leveraging scale economies, and precision-dose specialists capturing technical service premiums. Dominant competitive moves include capacity expansion in pharmaceutical-grade barrier structures and strategic partnerships between equipment manufacturers and contract packagers.
Within the integrated conglomerate tier, Amcor plc and Constantia Flexibles occupy positions defined by global film extrusion infrastructure and specialized aluminum-barrier engineering respectively. Catalent, Inc. anchors the pharmaceutical specialist archetype through integrated services that pair drug development with dedicated stick packaging lines. These three companies exemplify the bifurcation between scale-driven material supply and qualification-intensive pharmaceutical services.
| Leading Market Players |
|---|
| ProAmpac |
| Catalent, Inc. |
| Amcor plc |
| ePac Holdings, LLC |
| Taghleef Industries |
| Constantia Flexibles |
| Glenroy, Inc. |
| Winpak Ltd. |
| Huhtamaki |
| Others |
Supply Flow & Price Mechanics
Ninety-day aluminum foil lead times from European rolling mills concentrate pricing power among laminate converters with qualified pharmaceutical inventory positions, while ISO 15378 certification timelines extend payback periods for new capacity investments. Cost-plus contracts indexed to LME aluminum and resin futures dominate pharmaceutical-grade stick packaging, compressing margins for generalist converters lacking backward integration into film extrusion.
Pricing Analysis
Cost-plus contracts with quarterly aluminum and polymer indexation dominate pharmaceutical stick packaging agreements, insulating qualified suppliers from raw material volatility while locking in thin conversion margins. Three-tier pricing structure across ISO 15378-certified pharmaceutical, food-grade laminated, and commodity mono-material tiers reflects certification investment recovery and barrier engineering intensity. Pricing pressure stems from REACH-driven reformulation costs for fluorine-free heat-seal layers, with food-grade converters facing acute compression. Hospital procurement coalitions exhibit lowest price sensitivity due to inventory reduction mandates, while instant beverage brands drive hard volume negotiations.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes elevate landed costs for cellulose-derived barrier films sourced from Nordic suppliers. Aluminum foil supply concentrates in Germany, France, and Belgium, while precision filling equipment clusters around Düsseldorf and Cologne. Raw material dependencies span aluminum rolling mill output, biaxially oriented polypropylene films, and specialized heat-seal adhesives. Single-source vulnerability sits with European rolling mill capacity for high-barrier pharmaceutical laminates. Distribution runs through converter-direct hospital procurement coalitions and branded food manufacturer specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stick packaging represents a service-attach opportunity where technical validation support and formulation-fill-finish integration expand recurring revenue faster than commodity laminate sales. Aftermarket maintenance contracts for servo-driven filling systems and ISO 15378 compliance auditing services capture margin premiums beyond hardware.
For Market Incumbents: Consolidate around Düsseldorf-Cologne equipment clusters to capture pharmaceutical contract manufacturing expansion, while deepening captive supply of aluminum-barrier laminates against European rolling mill constraints. Defensive priority rests on securing multi-year hospital procurement coalition agreements before oral dissolvable film formats displace unit-dose powders. Certification investment in bio-based film validation creates switching costs against generalist converters. For New Entrants and Emerging Players: Technical service gaps in servo-driven equipment maintenance across US contract packaging networks offer white-space entry points. Target nutraceutical scored stick packs in India and Japan where laser-scoring adoption outpaces qualified local supply. Penetrate through equipment-leasing bundled with validation consulting, avoiding capital-intensive laminate manufacturing. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because pharmaceutical qualification assets compound competitive moats while food-grade segments commoditize. Acquisition focus centers on ISO 15378-certified converters with hospital procurement coalition relationships and integrated formulation capabilities. Signal to monitor: German deposit-return pilot expansion into pharmaceutical single-serve formats, which would revalue recyclable mono-material capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foil Rolling | Captive supply secures pharmaceutical laminate availability against European capacity constraints. |
| ISO 15378 Certification Investment | Qualification timelines protect incumbent positions in FDA and EU MDR-governed pharmaceutical channels. |
| Servo-Driven Equipment Leasing Programs | Service-attach revenue streams penetrate contract packer networks with scarce maintenance capabilities. |
| Bio-Based Film Validation Partnerships | Cellulose-derived barrier positioning aligns with EU Packaging and Packaging Waste Regulation recovery targets. |
| Hospital Procurement Coalition Direct Contracts | Group purchasing organization relationships lock in multi-year unit-dose pharmaceutical volumes. |
Methodological Framework
Desk research of EU Packaging and Packaging Waste Regulation filings, FDA cGMP guidance documents, and REACH substance restriction precedents preceded structured interviews with pharmaceutical contract manufacturing executives, precision filling equipment engineers, hospital procurement coalition managers, and laminate converter technical directors. Secondary validation drew from aluminum rolling mill capacity disclosures, vertical form-fill-seal equipment shipment data, and ISO 15378 certification registries. Bottom-up volume estimates triangulated against top-down pharmaceutical packaging expenditure benchmarks.
Variance decomposition across material composition tiers, end-use regulatory clusters, and geographic equipment concentrations shaped the analytical framework over the projection horizon. Modeled segmentation spanned product type, barrier engineering intensity, and regional regulatory stringency tiers. CAGRs derived from elasticity-adjusted demand curves for instant beverage portion control and pharmaceutical unit-dose conversion. Forecast inputs incorporated aluminum foil supply constraints and servo-driven equipment adoption curves.
Material uncertainties — EU MDR packaging assessment prioritization shifts, REACH perfluoroalkyl substance restriction enforcement timelines, and German deposit-return pilot scalability — sit outside the modeled envelope. Forecasts reflect assumptions regarding hospital procurement coalition consolidation velocity and oral dissolvable film format migration rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Flow Wraps Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market