
 Sanitizer Packaging Market | 2026-2036
Sanitizer Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitizer Packaging Market Analytics
Buyer concentration across hospital systems and institutional purchasers is expanding as group purchasing organizations consolidate sanitizer procurement contracts. Berry Global Group leverages its North American blow-molding footprint to supply high-density polyethylene bottles at scale. Amcor anchors flexible pouch production for travel-size and single-use sanitizer formats. AptarGroup specializes in precision pump-dispenser closures that reduce product waste in clinical settings.
Sanitizer packaging encompasses primary containers, closures, and delivery systems engineered to preserve alcohol-based and quaternary ammonium formulations while enabling controlled dispensing. Most sanitizer bottles use polyethylene terephthalate or high-density polyethylene with barrier additives to prevent alcohol evaporation and maintain shelf stability above sixty percent concentration. Plastic bottles dominate volume across healthcare and personal care end users, though pump dispensers command premium positioning due to dosing accuracy requirements in clinical environments. Composite materials represent the fastest-growing material segment as brand owners pursue lightweighting targets without sacrificing chemical compatibility.
The FDA regulates sanitizer packaging under over-the-counter drug monograph requirements, mandating child-resistant closures for certain alcohol concentrations and precise labeling of active ingredients. The EPA oversees antimicrobial claims on sanitizer labels, directly influencing packaging copy and instructional panel design. REACH compliance in Europe restricts specific plasticizers and additives, compelling reformulation of closure seals and bottle resins. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based content mandates as these regulations increasingly dictate material selection and supplier qualification criteria.
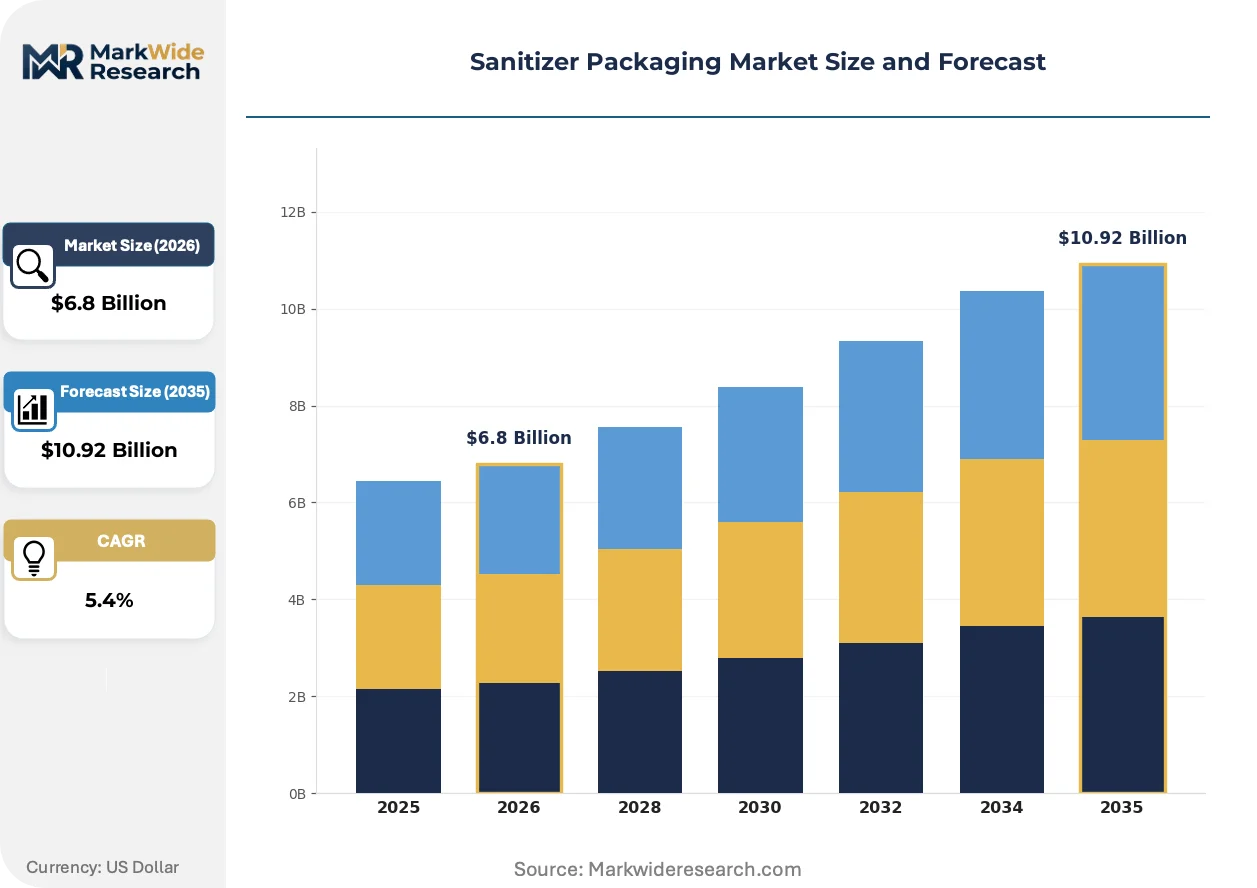
Market Dynamics
Healthcare procurement consolidation and the EU's Single-Use Plastics Directive are compressing supplier margins while accelerating material transitions across sanitizer packaging supply chains. These dual pressures favor converters with integrated recycling capabilities and regional regulatory expertise.
Growth Catalysts
- REACH compliance deadlines:European formulators are reformulating closure seals and bottle resins ahead of restricted substance phase-outs, creating replacement demand for compliant packaging components.
- Pump-dispenser protocols:United States hospital systems are mandating precision dosing formats for infection control, pulling specialized closure capacity toward clinical-grade specifications.
- Domestic manufacturing incentives:India's PLI scheme for packaging materials is scaling local bottle production, reducing import dependency for sanitizer brands serving South Asian markets.
Market Restraints
- Recycled PET supply scarcity:Post-consumer feedstock availability lags brand owner commitments, forcing converters to absorb premium pricing or delay sustainability transitions.
- Barrier additive cost volatility:Specialty oxygen scavengers and UV stabilizers required for alcohol compatibility expose blow-molders to petrochemical derivative swings.
- Closure precision tolerances:Clinical pump mechanisms demand tighter manufacturing controls than commodity dispensers, limiting qualified supplier pools and extending qualification timelines.
Strategic Opportunities
- Travel-size flexible formats:Single-use pouch demand from aviation and hospitality sectors remains underpenetrated relative to bottle dominance in institutional channels.
- Bio-based polymer mandates:France's AGEC law and similar national frameworks are creating procurement preference for packaging with certified renewable content.
- Closed-loop collection systems:Retail pharmacy chains are piloting take-back programs for sanitizer bottles, enabling converters to secure captive recycled feedstock streams.
Industry Challenges
- Multilayer separation complexity:Composite bottles combining barrier layers with structural resins complicate mechanical recycling, requiring investment in advanced sorting infrastructure.
- Cross-jurisdictional labeling:Harmonizing FDA drug monograph requirements with EPA antimicrobial claim rules demands dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitizer Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Pouches, Jars, Dispensers Material: Plastic, Glass, Metal, Composite Closure Type: Screw Caps, Pump Dispensers, Flip Tops, Sachets End User: Healthcare, Personal Care, Food Service, Retail |
| Companies Covered | AptarGroup, Berry Global Group, ALPLA Group, Silgan Holdings, Guala Closures Group, Amcor, Unilever, Procter & Gamble, Reckitt Benckiser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitizer Packaging Market Evolving Landscape
Material lightweighting and regulatory-driven substitution are converging to reshape competitive positioning in sanitizer packaging. Technical differentiation now centers on barrier performance per gram of resin rather than conventional durability metrics.
Barrier-coated PET is overtaking multilayer HDPE constructions for alcohol-based sanitizer bottles. European personal care brands are adopting plasma-deposited silicon oxide coatings to achieve oxygen transmission rates below 0.1 cc per day. This technology is overtaking conventional co-injection molding by eliminating adhesive layers and enabling monomaterial recycling streams.
REACH restrictions on phthalate plasticizers are forcing reformulation of pump dispenser seals across European supply chains. ECHA's 2025 sunset dates for specific substances are accelerating migration to bio-based elastomers. Closure manufacturers serving EU markets are requalifying entire product lines ahead of enforcement windows.
Group purchasing organizations are consolidating sanitizer procurement across United States hospital networks. Three-year sole-source contracts are displacing fragmented spot purchasing, concentrating volume with converters offering integrated bottle-and-closure platforms. This concentration is most visible in the Southeast, where health system mergers have reduced qualified vendor lists by half.
Sanitizer Packaging Market Segmentation
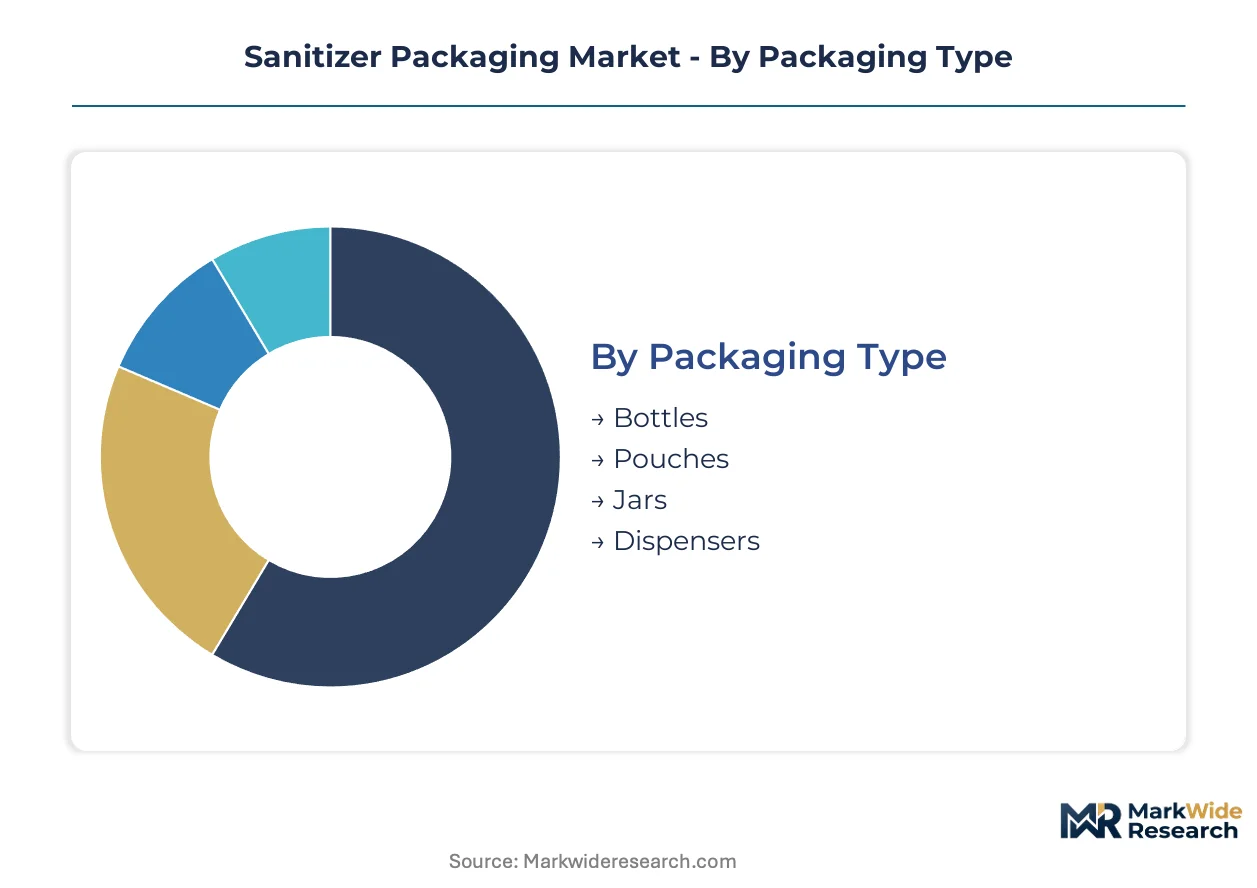
Sanitizer packaging segments diverge sharply in margin structure and regulatory exposure. Material selection and closure precision determine supplier qualification tiers, while end-user channel dictates volume scale and contract duration.
Packaging Type:
Blow-molding capacity concentrates in North American and Indian manufacturing clusters, with converter investments tracking hospital procurement consolidation and aviation sector recovery patterns.
- Bottles:Polyethylene terephthalate and high-density polyethylene containers incorporate oxygen scavengers and UV stabilizers to maintain alcohol concentrations above sixty percent through shelf life. Demand concentrates in United States hospital systems mandating pump-compatible cylindrical formats for infection control protocols.
- Pouches:Flexible laminated structures serve single-use aviation and hospitality applications, with multilayer coextrusion enabling alcohol barrier performance at sub-gram resin weights. European personal care brands are piloting monomaterial polyethylene variants to align with extended producer responsibility frameworks.
- Jars:Wide-mouth polypropylene containers target institutional bulk refills and food service counter placements, prioritizing stackability and label adhesion over barrier sophistication.
- Dispensers:Integrated bottle-closure systems for wall-mounted and countertop installations require precision molding tolerances that limit qualified supplier pools to converters with dedicated cleanroom capacity.
Today's leader: Bottles. Tomorrow's challenger: Pouches.
Material:
Cost tiers separate commodity resins from engineered barrier constructions, with sustainability premiums compressing mid-tier positioning.
- Plastic:PET and HDPE dominate volume through blow-molding efficiency and chemical compatibility with quaternary ammonium and alcohol-based formulations. India's PLI scheme for packaging materials is scaling domestic resin conversion capacity.
- Glass:Borosilicate and soda-lime containers serve premium personal care positioning and pharmaceutical-grade requirements where inertness outweighs weight and fragility penalties.
- Metal:Aluminum aerosol cans and collapsible tubes occupy niche sanitizing foam and spray applications, with European supply chains migrating toward recycled content certification under France's AGEC law.
- Composite:Multilayer structures combining barrier polymers with structural resins are expanding most quickly as brand owners pursue lightweighting targets without sacrificing shelf stability; mechanical recycling complexity remains the primary constraint.
Plastic commands current volume. Composite structures are gaining share fastest through material substitution mandates.
Closure Type:
Application requirements dictate precision tiers, with clinical dosing accuracy separating premium mechanisms from commodity formats.
- Screw Caps:Standard threaded closures for refill bottles and bulk containers, produced at high throughput with minimal tolerance requirements.
- Pump Dispensers:Precision-engineered mechanisms with calibrated stroke volumes for clinical infection control; REACH restrictions on phthalate plasticizers are forcing seal reformulation across European supply chains ahead of ECHA sunset dates.
- Flip Tops:Hinged polypropylene closures for personal care travel sizes, balancing one-handed operation with child-resistant compliance where required by FDA over-the-counter drug monograph.
- Sachets:Heat-sealed flexible film packets for single-use aviation and hospitality distribution, with tear-notch engineering and printed dosing instructions replacing molded closure functions.
Pump dispensers anchor clinical contracts. Sachets are climbing the fastest through aviation sector recovery and single-use hygiene protocols.
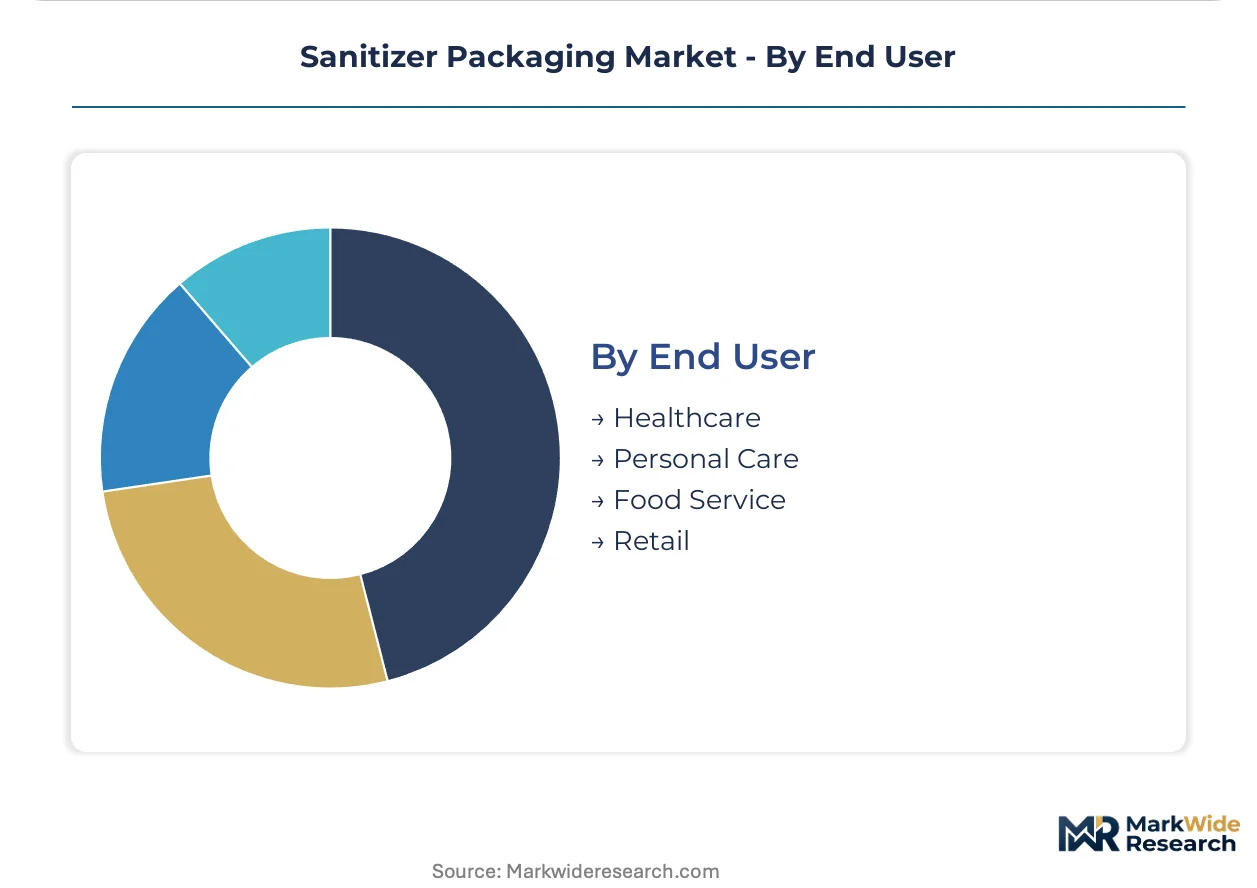
End User:
Customer type determines contract structure, with institutional procurement consolidation favoring integrated platform suppliers over specialized component vendors.
- Healthcare:United States hospital systems and group purchasing organizations are consolidating three-year sole-source contracts for bottle-and-closure platforms, with Southeast health system mergers reducing qualified vendor lists by half.
- Personal Care:Brand owners prioritize shelf differentiation through tactile finishes and sustainable material narratives, with European markets demanding certified bio-based content under national frameworks.
- Food Service:Countertop dispensers and refill pouches for restaurant and institutional kitchen applications, with NSF International certification requirements influencing material selection.
- Retail:Pharmacy chains are piloting closed-loop collection systems for sanitizer bottles, enabling converters to secure captive recycled PET feedstock streams independent of post-consumer scarcity.
Healthcare drives contract concentration. Retail collection infrastructure is emerging as the challenger channel through circular economy pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and polymer chemists cluster in industrial corridors across five countries where healthcare procurement and regulatory mandates are reshaping sanitizer container supply chains.
United States
Hospital system mergers in the Southeast are consolidating sanitizer procurement under group purchasing organizations, reducing qualified vendor lists by half. FDA over-the-counter drug monograph requirements mandate child-resistant closures for alcohol concentrations above sixty percent. Blow-molding capacity concentrates in Ohio and Indiana, where converters supply pump-compatible cylindrical formats for infection control protocols.
Germany
REACH compliance deadlines are forcing reformulation of closure seals and bottle resins ahead of ECHA's 2025 sunset dates for restricted phthalate plasticizers. The country's national chemical regulator maintains strict oversight of additive migration limits for alcohol-based formulations. Production gravity centers on North Rhine-Westphalia, where converters integrate recycled PET streams under extended producer responsibility frameworks.
India
Domestic manufacturing of sanitizer bottles is scaling under the PLI scheme for packaging materials, reducing import dependency for brands serving South Asian markets. BIS certification requirements for food-contact plastics now extend to sanitizer containers with incidental hand-contact exposure. Maharashtra and Gujarat host expanding blow-molding clusters where local resin conversion capacity tracks aviation sector recovery patterns.
France
AGEC law mandates are creating procurement preference for packaging with certified bio-based content, accelerating migration toward renewable polymers. ECHA restrictions on specific plasticizers compel reformulation of pump dispenser seals across European supply chains. The Île-de-France region anchors flexible pouch production for travel-size formats targeting hospitality sector recovery.
China
Dual carbon goals are pressuring converters to demonstrate recycled content ratios in export-bound sanitizer packaging. SAMR oversight of food-contact materials increasingly influences specifications for alcohol-based formulation containers. Yangtze River Delta manufacturing clusters supply barrier-coated PET bottles with plasma-deposited silicon oxide layers achieving oxygen transmission rates below 0.1 cc per day.
Sanitizer Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that rewards integrated bottle-and-closure platforms over component vendors. Tier-one suppliers anchor long-term contracts with hospital systems and personal care brand owners, while mid-scale converters compete on regional regulatory expertise and sustainability certification speed. Two strategic archetypes dominate: integrated packaging platforms spanning resin conversion through precision molding, and specialized closure manufacturers with dedicated cleanroom capacity for clinical-grade pump mechanisms. Competitive moves center on backward integration into recycled feedstock streams and geographic expansion through regional regulatory qualification.
Among North American-based diversified packaging conglomerates, Berry Global Group and AptarGroup exemplify contrasting strategic positions. Berry Global Group occupies a position as a scale-driven blow-molding supplier with continental manufacturing footprint, while AptarGroup represents the precision closure specialist archetype with concentration in dosing accuracy technologies. European converter ALPLA Group anchors the recycled content integration tier, having built captive post-consumer PET processing capabilities ahead of EU mandate timelines. Amcor sits within the flexible format specialization vector, with pouch production capacity aligned to aviation and hospitality sector recovery demand. These four companies collectively illustrate the competitive segmentation between resin-scale efficiency and clinical-precision specialization that defines supplier qualification tiers.
| Leading Market Players |
|---|
| AptarGroup |
| Berry Global Group |
| ALPLA Group |
| Silgan Holdings |
| Guala Closures Group |
| Amcor |
| Unilever |
| Procter & Gamble |
| Reckitt Benckiser |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up blow-molding specialists in North America and India have consolidated regional capacity, tightening pricing discipline through volume commitments to hospital group purchasing organizations while squeezing margin at mid-tier converters lacking integrated closure platforms.
Pricing Analysis
Bundled bottle-and-closure platforms command premium positioning against unbundled component sourcing. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade pump dispensers with REACH-compliant seals from commodity screw-cap bottles and bulk refill formats. Pricing pressure stems from recycled PET feedstock scarcity forcing converters to absorb resin premiums or delay sustainability transitions. Healthcare procurement officers show lowest price sensitivity due to infection control protocol mandates, while aviation and hospitality purchasers negotiate aggressively on single-use pouch volumes.
Supply Chain Analysis
Single-source vulnerability sits with Chinese suppliers of plasma-deposited silicon oxide barrier coating equipment essential for oxygen transmission performance below 0.1 cc per day. Blow-molding capacity concentrates in the United States, Germany, and India, with resin conversion feeding from petrochemical derivatives in the Gulf Coast and Middle East. Supply chain risk centers on ECHA sunset dates for phthalate plasticizers disrupting European pump seal availability. Distribution runs through group purchasing organization contracts directly to hospital systems, bypassing traditional wholesale channels for institutional volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
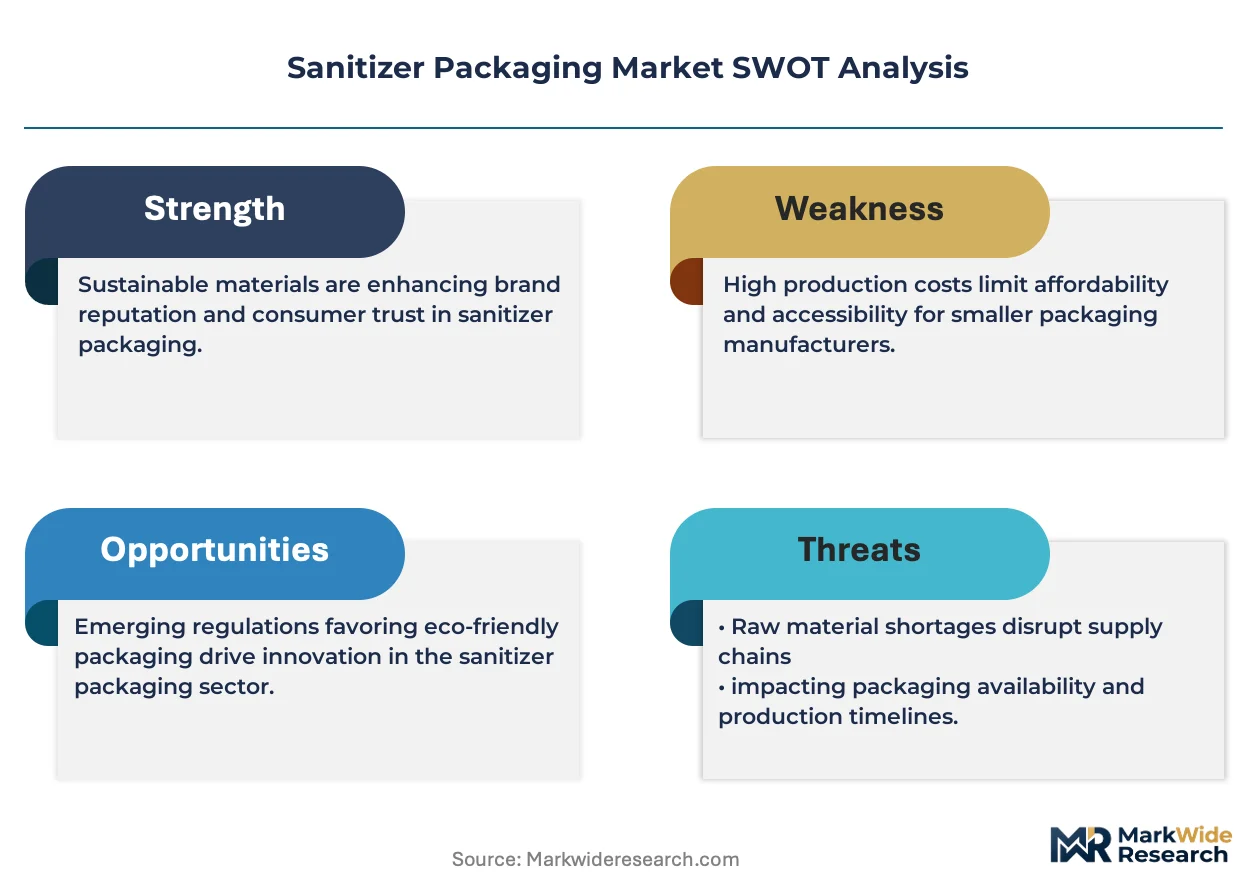
This market reads as a geographic-arbitrage play between India's PLI-subsidized domestic manufacturing and Europe's regulatory-driven material substitution premiums, with cost differentials exceeding compliance investment thresholds for export-oriented converters.
For Market Incumbents: Lock in three-year sole-source contracts with Southeast United States health systems before merger-driven vendor consolidation completes. Backward integration into captive recycled PET processing secures feedstock against post-consumer scarcity while REACH compliance investments in bio-based elastomer seals defend European market access against ECHA enforcement windows. For New Entrants and Emerging Players: Capture underpenetrated flexible pouch demand from aviation sector recovery and single-use hospitality protocols. France's AGEC law creates procurement preference for certified bio-based content, opening white-space for renewable polymer specialists. Direct sales to airline procurement departments bypass established bottle converter relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European converters with recycled content infrastructure but limited closure precision capabilities. Five-to-ten year viability hinges on regulatory qualification speed rather than scale. Watch for group purchasing organization contract renewal cycles as inflection indicators for vendor list consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Captive PET streams insulate converters from post-consumer scarcity premiums under EU mandates. |
| Precision Closure Platform Acquisition | Clinical-grade pump mechanisms qualify vendors for sole-source hospital contracts in the United States. |
| Regional Regulatory Qualification Expansion | REACH-compliant seal reformulation opens European procurement channels ahead of ECHA sunset dates. |
| Flexible Pouch Capacity Addition | Aviation sector recovery pulls demand toward sub-gram resin weight single-use formats. |
| Bio-Based Polymer Certification Investment | France's AGEC law creates procurement preference for renewable content verification. |
Research Methodology
Bottom-up healthcare procurement modeling reconciled against top-down blow-molding capacity tracking forms the analytical core of this study. Primary interviews with group purchasing organization contract managers, hospital infection control officers, blow-molding plant engineers, and regulatory affairs specialists at closure manufacturers were validated against secondary sources including FDA over-the-counter drug monograph filings, ECHA restricted substance databases, BIS certification records, and Indian PLI scheme disbursement reports.
Historical trendline analysis of bottle and closure production volumes across material categories established baseline growth patterns. Segmentation modeling spanned packaging type, material composition, closure precision tier, and end-user channel across the analysis window. CAGRs were derived from regression analysis of procurement contract values and converter capacity utilization rates, with inputs from aviation sector passenger recovery indices and hospital merger completion timelines.
Regulatory enforcement timing, recycled feedstock availability shocks, and health system consolidation velocity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about REACH compliance cost pass-through and PLI scheme continuation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Skin Packaging Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Trifold Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Standard Liner Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Fanfold Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Mylar Market
Packaging Materials
Global Food Processing Seals Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
Twist Tie Market
Packaging Materials
Book Wraps Market