
 Middle East and Africa Package Testing Market | 2026-2036
Middle East and Africa Package Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Package Testing Market Foresight
Saudi Arabia's King Abdullah Economic City is rewriting regional logistics infrastructure, drawing testing laboratories closer to Red Sea export corridors. Intertek Group Plc leverages its Jeddah facilities to anchor pharmaceutical cold-chain validation across the Gulf. Bureau Veritas SA competes through environmental simulation capabilities that sustain compliance with Gulf Standardization Organization protocols. SGS SA dominates food-contact migration testing, extending its Cairo laboratory network into East African trade routes.
Middle East and Africa package testing evaluates structural integrity, barrier performance, and shelf-life stability of containers, primary wraps, and transport configurations through controlled stress protocols including compression, vibration, and accelerated aging at specified temperature-humidity profiles. Its primary commercial purpose is certifying that packaged goods withstand distribution hazards while meeting jurisdiction-specific safety and labeling mandates. Non-destructive testing leads service revenue due to pharmaceutical and electronics sector demand for intact sample retention, while environmental testing registers the fastest expansion as Gulf exporters confront escalating thermal stress from extended summer logistics. Flexible packaging commands disproportionate testing volume because film-laminate structures require specialized permeation and seal-strength analysis.
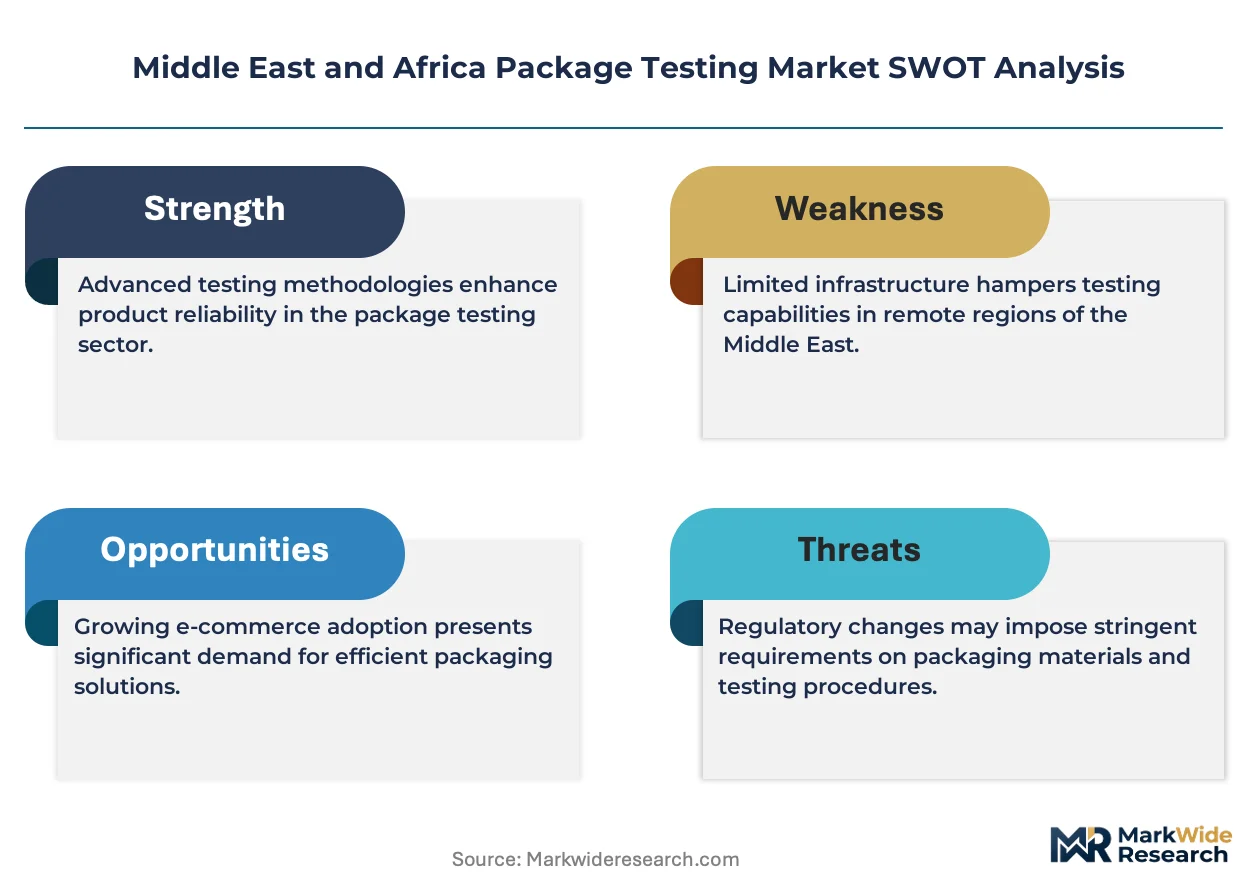
GSO conformity assessment requirements and South African National Accreditation System (SANAS) laboratory standards shape market access by mandating third-party validation for packaged imports across Gulf Cooperation Council and Southern African Customs Union territories. Egypt's Egyptian Organization for Standardization and Quality (EOS) enforcement of food-contact material regulations is redirecting informal testing demand toward accredited providers. Stakeholders must monitor harmonization gaps between Gulf and African standardization regimes as regional trade agreements deepen cross-border packaging compliance obligations.
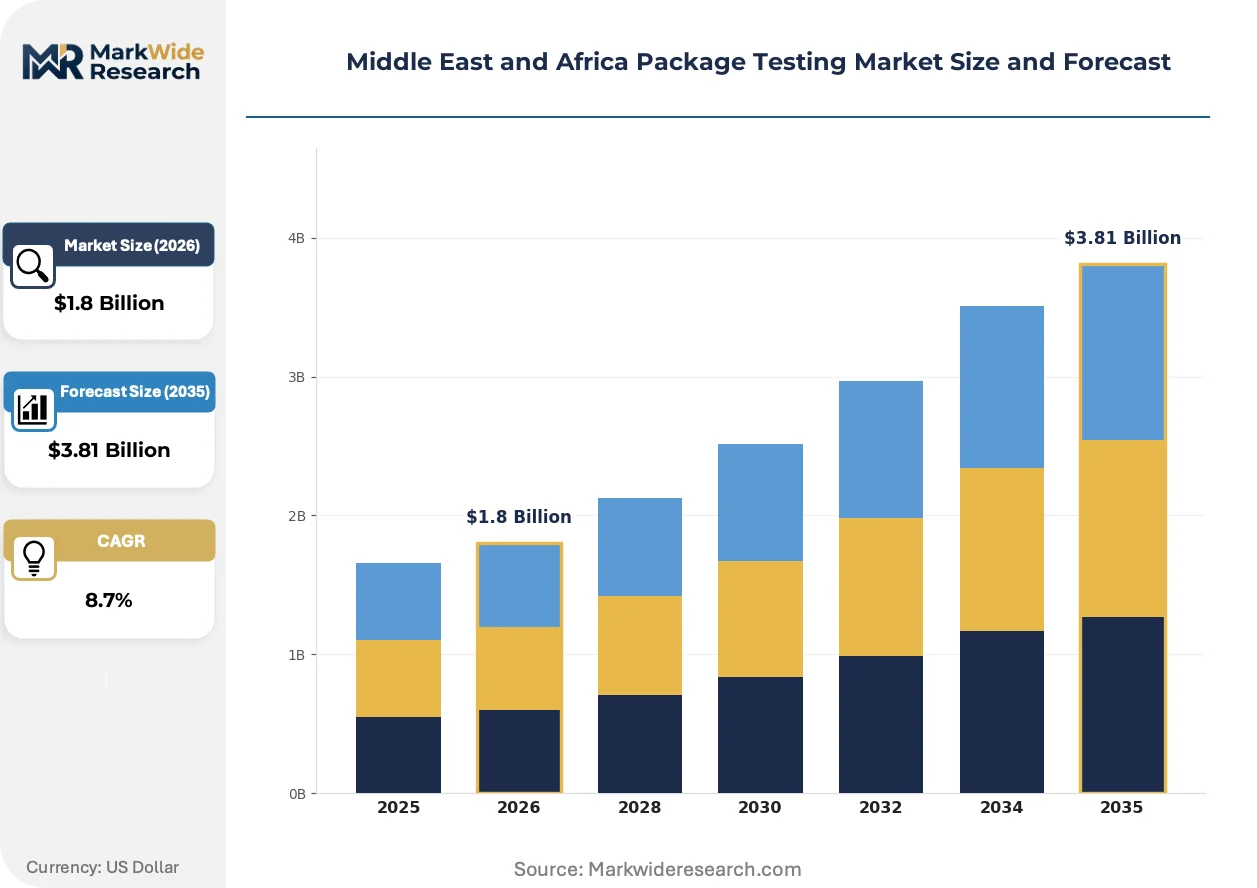
Market Dynamics
Gulf Standardization Organization conformity mandates are compressing testing timelines for cross-border packaged goods, forcing laboratories to co-locate with Saudi Arabia's Red Sea logistics corridors and Egypt's food export zones.
Growth Catalysts
- Pharmaceutical cold-chain expansion:South African and Gulf state manufacturers are validating temperature-controlled packaging for biologics distribution, creating sustained demand for thermal profiling services.
- GSO protocol harmonization:The UAE's adoption of unified Gulf conformity requirements is eliminating redundant testing loops for packaged imports across GCC territories.
- Food export hub concentration:Saudi Arabia's industrial cities are requiring accelerated shelf-life testing capacity to support Red Sea corridor agri-export growth.
Market Restraints
- Accreditation cost barriers:SANAS and EOS laboratory certification requirements impose capital-intensive quality infrastructure that filters informal testing providers from formal market participation.
- Equipment import dependency:Environmental simulation chambers and permeation analyzers concentrate supply with German and Japanese manufacturers, exposing testing facilities to currency fluctuation and extended lead times.
- Technical limitation in non-destructive validation:Current thermal imaging and acoustic emission methods cannot fully substitute destructive seal-strength testing for high-barrier pharmaceutical laminates.
Strategic Opportunities
- East African trade route penetration:Cairo-based laboratories are extending service networks into Ethiopia and Kenya to capture pre-shipment inspection demand for Gulf-bound agricultural exports.
- Flexible packaging specialization:Film-laminate structures for snack and pharmaceutical sachets require dedicated permeation and burst testing protocols that generalist providers underserve.
- Digital test reporting integration:Blockchain-anchored certificates are emerging as a procurement requirement among Saudi Arabian and Emirati distributors seeking real-time compliance verification.
Industry Challenges
- Specialized technician scarcity:Thermal chamber operation and accelerated aging protocol design require trained personnel that Gulf and North African labor markets undersupply relative to demand growth.
- Multi-jurisdiction certification timelines:Harmonization gaps between GSO standards and Southern African Customs Union requirements force redundant testing cycles for packaged goods transshipping through both zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Package Testing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Destructive Testing, Non-Destructive Testing, Environmental Testing, Compliance Testing End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Packaging Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Labeling Material: Paper, Plastic, Metal, Glass |
| Companies Covered | Intertek Group Plc, SGS SA, Bureau Veritas SA, Eurofins Scientific SE, DDL, Inc., CSZ Testing Services Laboratories, Advance Packaging, Nefab AB, National Technical Systems, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Package Testing Market Shifts & Advancements
Digital validation protocols and automated environmental simulation are compressing traditional testing cycles while regulatory digitization is rewriting certificate authentication workflows across Gulf and African trade corridors.
Non-destructive evaluation technology is collapsing the historical trade-off between sample preservation and validation thoroughness. Thermal imaging and acoustic seal inspection systems allow pharmaceutical and electronics manufacturers to retain intact units for commercial use. Gulf-based cold-chain exporters are adopting these methods at accelerated rates. The technology is collapsing testing backlogs that previously constrained high-value product release schedules.
Gulf Standardization Organization electronic conformity marking requirements are mandating machine-readable certificate integration for all packaged imports entering GCC territories. Industrial consequence includes laboratory investment in blockchain-anchored documentation systems. Food-contact and pharmaceutical packaging segments face the steepest compliance curves, with Saudi Arabian and Emirati importers now rejecting paper-based test reports at port entry.
Buyer consolidation among Saudi Arabian food export conglomerates is compressing vendor qualification timelines and unbundling testing from logistics contracts. Previously integrated 3PL providers are losing captive testing volume to independent laboratories with specialized environmental simulation capabilities. This procurement restructuring is most visible in King Abdullah Economic City, where direct laboratory contracts are displacing bundled service arrangements for shelf-life validation.
Middle East and Africa Package Testing Market Segmentation
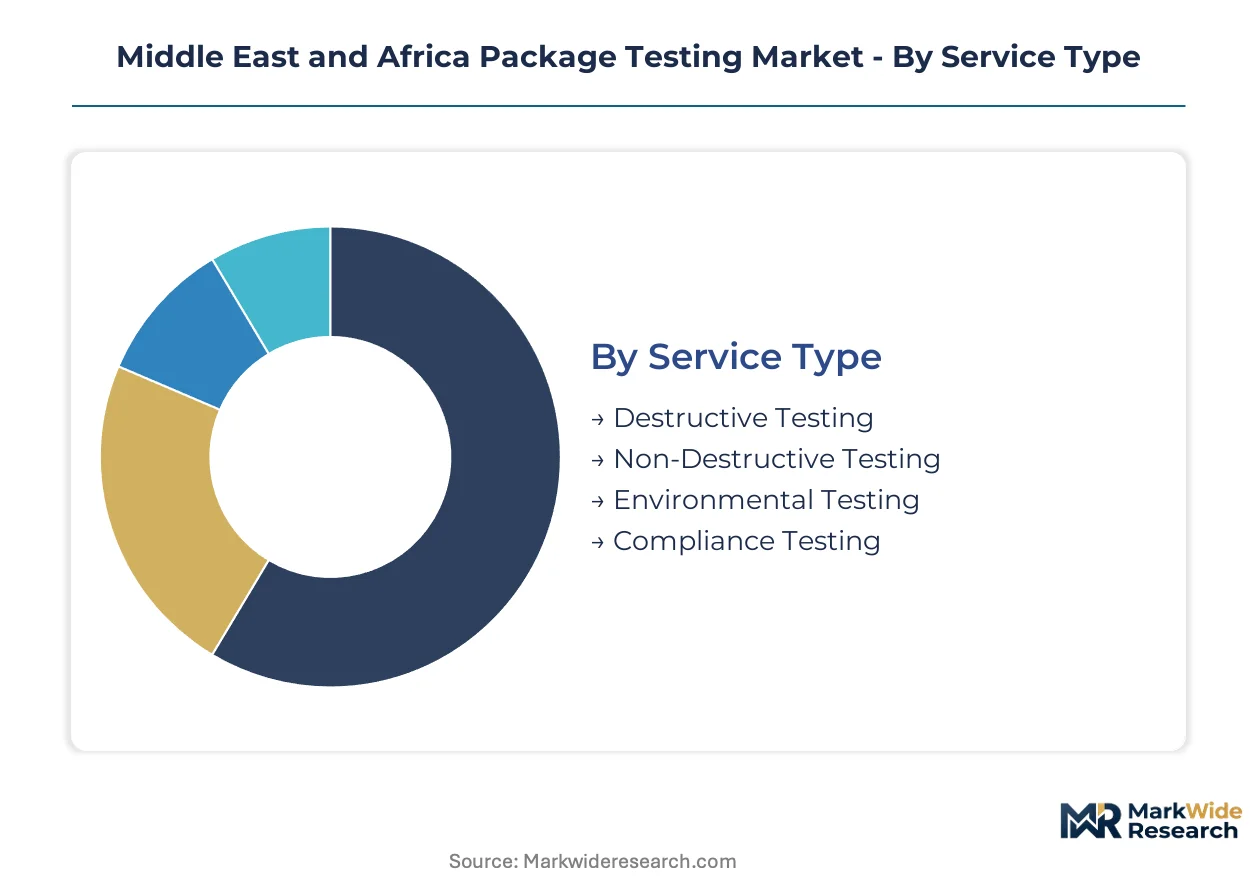
Package testing laboratories across the Middle East and Africa configure service portfolios around distinct technical protocols, end-use risk profiles, and material specifications. Each segmentation axis shapes capital allocation decisions for thermal chambers, permeation analyzers, and accreditation scope.
Service Type:
After-sales-service intensity varies sharply across testing modalities, with environmental simulation requiring continuous calibration support and on-site technician deployment.
- Non-Destructive Testing:Thermal imaging, acoustic emission, and X-ray inspection methods preserve sample integrity for pharmaceutical and electronics manufacturers. Saudi Arabian cold-chain exporters prioritize these protocols to release high-value biologics without unit destruction. Demand concentrates in Jeddah and Dubai logistics corridors where product retention carries commercial premium.
- Environmental Testing:Accelerated aging, thermal cycling, and humidity exposure protocols validate packaging performance under Gulf summer distribution stress. Cairo-based laboratories are expanding chamber capacity to capture Ethiopian and Kenyan agricultural export pre-shipment demand. This modality commands premium pricing due to equipment intensity and protocol complexity.
- Destructive Testing:Compression, burst, and seal-strength validation remain essential for high-barrier pharmaceutical laminates where non-destructive substitutes prove insufficient.
- Compliance Testing:GSO conformity assessment and SANAS-accredited validation for cross-border trade documentation, increasingly digitized through blockchain-anchored certificates.
By volume, Non-Destructive Testing leads. By growth pace, Environmental Testing is ahead.
End User:
Customer concentration patterns diverge across application verticals, with pharmaceutical and food export hubs driving geographic clustering of laboratory facilities.
- Pharmaceuticals:Temperature-controlled packaging validation for biologics distribution dominates service mix in South Africa and Gulf states. Cold-chain protocol design requires thermal profiling across ISTA 7E and WHO PQS standards. King Abdullah Economic City laboratories anchor regional capacity.
- Food & Beverage:Shelf-life stability and migration testing for Red Sea corridor agri-exports. Egyptian food-contact material regulations under EOS redirect informal testing toward accredited Cairo providers.
- Electronics:Vibration and drop testing for consumer device distribution, with non-destructive methods preferred for high-value unit retention.
- Consumer Goods:General merchandise packaging integrity validation, typically lower protocol complexity than pharmaceutical or food segments.
Pharmaceuticals generates highest revenue per test. Food & Beverage shows steepest volume expansion.
Packaging Type:
Structural complexity determines testing protocol specialization, with film-laminate structures demanding dedicated permeation and burst analysis equipment.
- Flexible Packaging:Multi-layer films, sachets, and pouches require specialized seal-strength, permeation, and burst testing. Snack and pharmaceutical sachet demand in Saudi Arabia and UAE outpaces generalist laboratory capacity. Film-laminate structures command disproportionate testing volume due to barrier performance criticality.
- Rigid Packaging:Bottles, jars, and containers for pharmaceutical and food applications. Compression and drop testing protocols dominate, with lower equipment specialization barriers than flexible formats.
- Semi-Rigid Packaging:Trays, blisters, and clamshells combining structural rigidity with forming flexibility.
- Labeling:Adhesion, print durability, and barcode readability validation for automated supply chain scanning.
Flexible Packaging commands longest test cycles. Rigid Packaging scales most efficiently.
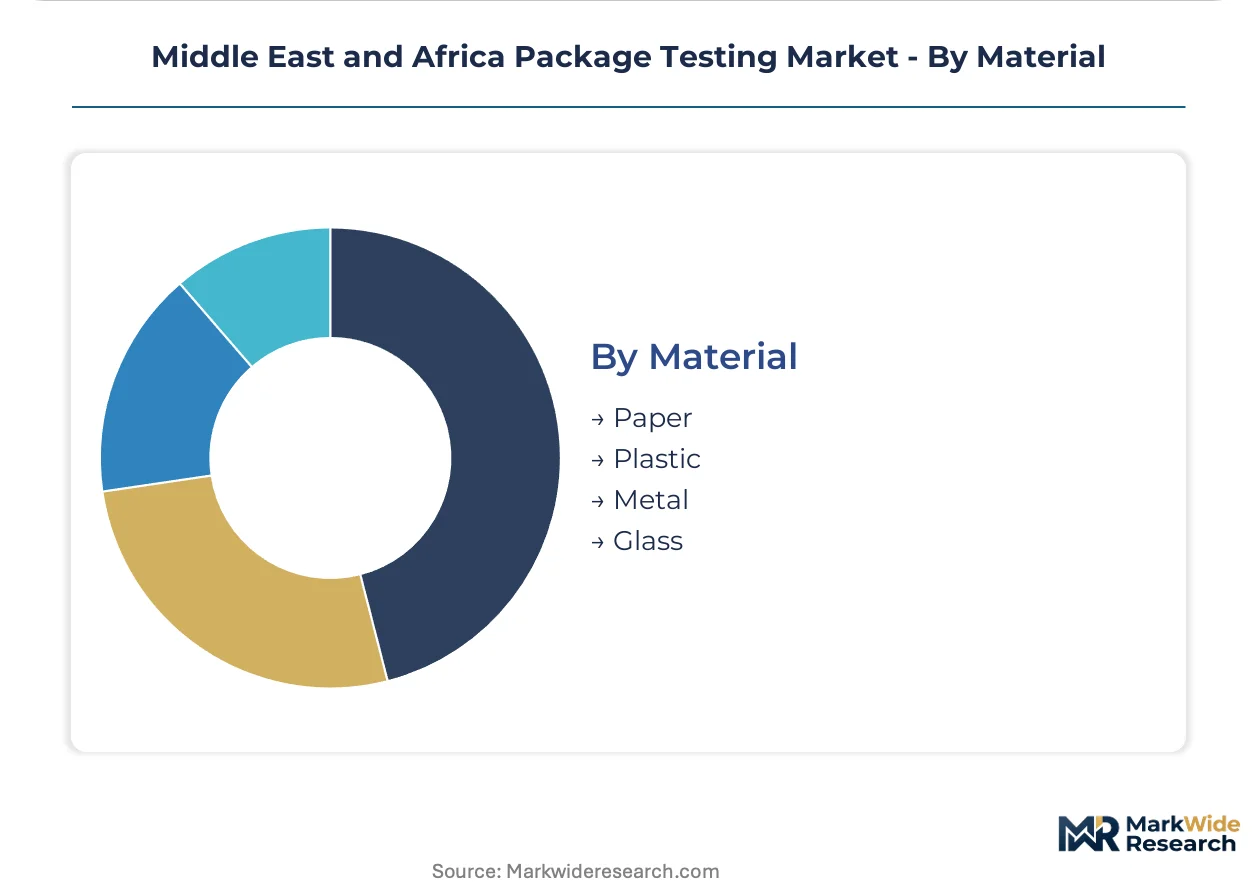
Material:
Substrate selection dictates migration testing requirements and regulatory compliance pathways across Gulf and African jurisdictions.
- Plastic:Polymer films, bottles, and containers dominate testing volume due to food and pharmaceutical packaging prevalence. Migration testing for Gulf-bound exports faces tightening EOS and GSO enforcement. SGS SA's Cairo network specializes in plastic food-contact validation.
- Paper:Fiber-based packaging for sustainable positioning, with moisture barrier and print adhesion testing protocols. Growing substitution demand in UAE and Saudi retail channels.
- Metal:Cans, foils, and closures requiring corrosion and seam integrity validation.
- Glass:Pharmaceutical and premium food containers, with thermal shock and fragment testing for distribution robustness.
Plastic leads in absolute test volume. Paper is climbing fastest on sustainability substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Package testing consumption across the Middle East and Africa splits sharply between Gulf states prioritizing pharmaceutical cold-chain validation and African markets concentrating on food-export compliance infrastructure.
Saudi Arabia
King Abdullah Economic City anchors Red Sea pharmaceutical logistics, driving demand for ISTA 7E thermal profiling services. SFDA enforcement of biologics distribution standards mandates third-party cold-chain validation. Jeddah-based laboratories are expanding environmental simulation capacity to capture transshipment testing from East African trade routes.
United Arab Emirates
Dubai's free zone logistics infrastructure processes re-export packaged goods requiring MOHAP-compliant pharmaceutical packaging validation. GSO electronic conformity marking mandates are forcing laboratory investment in blockchain-anchored certificate systems. Sharjah industrial clusters are drawing specialized flexible packaging permeation testing providers from European networks.
South Africa
Cape Town and Johannesburg pharmaceutical manufacturers are scaling temperature-controlled packaging programs for biologics export to Gulf markets. SANAS laboratory accreditation requirements filter informal testing providers from formal pharmaceutical validation contracts. Durban port logistics corridors are requiring accelerated shelf-life testing for agricultural re-exports to Middle Eastern destinations.
Egypt
Cairo laboratories specialize in food-contact migration testing for Nile Delta agricultural packaging bound for GCC territories. EOS enforcement of plastic food-contact regulations redirects informal testing demand toward accredited providers. Alexandria port zones are requiring pre-shipment package integrity validation for Red Sea corridor exports.
Kenya
Nairobi-based exporters of fresh produce to Gulf markets require accelerated aging protocols for modified-atmosphere packaging. Kenyan Bureau of Standards pre-export certification mandates drive laboratory service demand. Mombasa port logistics clusters are attracting Cairo-based testing networks extending East African coverage.
Middle East and Africa Package Testing Market Competitive Landscape
Capability concentration sits with multinational verification networks possessing GSO and SANAS accreditation scope; scale advantage sits with regional specialists co-located with Saudi and Egyptian export corridors. The market structures around three archetypes: global testing conglomerates with Gulf laboratory networks, European-origin verification firms with environmental simulation specialization, and regional packaging engineers with logistics-integrated service models. Dominant competitive moves include accreditation scope expansion into overlapping GCC and Southern African Customs Union territories, and co-location strategies aligning laboratory capacity with Red Sea port logistics clusters.
Within the multinational verification tier, Intertek Group Plc and SGS SA occupy positions reflecting divergent geographic anchoring strategies. Intertek leverages Jeddah facilities to represent pharmaceutical cold-chain validation capabilities across Gulf logistics corridors. SGS SA exemplifies Cairo-based network extension into East African trade routes, anchoring food-contact migration testing specialization. Bureau Veritas SA sits within the environmental simulation archetype, reflecting GSO protocol compliance positioning. These three entities collectively illustrate how accreditation breadth and logistics proximity determine competitive positioning in cross-border packaged goods validation.
| Leading Market Players |
|---|
| Intertek Group Plc |
| SGS SA |
| Bureau Veritas SA |
| Eurofins Scientific SE |
| DDL, Inc. |
| CSZ Testing Services Laboratories |
| Advance Packaging |
| Nefab AB |
| National Technical Systems |
| Others |
Supply & Pricing Matrix
Red Sea freight corridors compress testing service margins while amplifying price differentiation between Jeddah-co-located laboratories and inland competitors. Saudi Arabia's King Abdullah Economic City logistics concentration forces Cairo-based providers to absorb higher transport costs or cede pharmaceutical cold-chain contracts to proximate rivals.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical cold-chain validation, with annual retainer structures locking in thermal profiling capacity for biologics exporters. Spot pricing prevails for food-contact migration testing where Egyptian agricultural exporters seek pre-shipment certificates on demand. Price differentiation hinges on SANAS or GSO accreditation tier and after-sales calibration support intensity. Pricing pressure stems from buyer consolidation among Saudi food export conglomerates unbundling testing from logistics contracts. Small-scale Ethiopian and Kenyan agricultural exporters exhibit highest price sensitivity, while Gulf-state pharmaceutical manufacturers prioritize protocol reliability over unit cost.
Supply Chain Analysis
Extended payment terms from German and Japanese environmental simulation chamber manufacturers strain laboratory working capital, with 180-day cycles common for permeation analyzer procurement. Equipment supply concentrates in Germany, Japan, and Switzerland, while technical service personnel are sourced from South Africa and Egypt. Raw material dependencies include precision sensors, calibration gases, and thermal chamber insulation composites. Single-source vulnerability runs through German-made accelerated aging systems. Distribution runs through direct manufacturer-laboratory relationships with limited regional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Gulf and African standardization regimes creates niche opportunities for laboratories bridging harmonization gaps. Digital certificate authentication demands are splitting procurement requirements between blockchain-capable incumbents and paper-based competitors.
For Market Incumbents: Build accreditation moats spanning overlapping GCC and Southern African Customs Union territories to capture transshipment testing volume. Expand Jeddah and Cairo chamber capacity to anchor Red Sea corridor demand. Defend against European verification firms penetrating flexible packaging specialization by deepening technician training pipelines for film-laminate permeation analysis. For New Entrants and Emerging Players: Pursue East African trade route penetration through Nairobi or Addis Ababa laboratory partnerships, capturing pre-shipment inspection demand for Gulf-bound agricultural exports. Target Ethiopian coffee and Kenyan fresh produce exporters requiring accelerated aging protocols. Establish flexible packaging permeation testing capability in Sharjah industrial clusters where snack and pharmaceutical sachet demand outpaces generalist capacity. For Investors and Strategic Acquirers: Regional packaging engineers with logistics-integrated service models represent the most defensible acquisition profile for medium-term consolidation plays. Cairo-based networks extending into East Africa or Jeddah-co-located cold-chain specialists offer geographic optionality. Watch GSO-SANAS harmonization negotiations as the inflection signal for cross-border testing volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Scope Expansion | Dual GSO-SANAS certification captures transshipment testing across GCC-SACU corridors. |
| Blockchain Certificate Integration | Machine-readable documentation satisfies UAE and Saudi port entry requirements. |
| East African Network Extension | Cairo laboratory satellites capture Ethiopian and Kenyan pre-shipment demand. |
| Flexible Packaging Specialization | Dedicated permeation capacity addresses underserved film-laminate validation needs. |
| Technician Training Pipeline Investment | Certified thermal chamber operators mitigate Gulf and North African labor scarcity. |
Research Methodology
The analysis maps package testing service modalities, accreditation frameworks, and logistics corridor configurations, each validated through laboratory operations directors, pharmaceutical quality assurance managers, food export compliance officers, and Gulf logistics procurement leads. Primary fieldwork combined structured interviews with secondary triangulation against GSO protocol documentation, SANAS accreditation registers, SFDA biologics distribution guidelines, and Egyptian Organization for Standardization enforcement records. Bottom-up service volume estimates were cross-checked against top-down regional trade flow projections.
Assumptions held fixed include current GSO-SANAS harmonization gaps, existing equipment import lead times from German and Japanese manufacturers, and prevailing accreditation cost structures. The forecast framework modeled service type, end-user vertical, packaging format, material substrate, and logistics corridor proximity across the analysis window. CAGRs were derived from segmented demand elasticity coefficients applied to baseline capacity utilization rates. Thermal profiling service expansion and digital certificate adoption curves served as primary demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive accreditation scope expansion by multinational verification networks or rapid GSO-SANAS treaty negotiation would shift competitive outcomes. Currency fluctuation exposure for equipment imports and technician wage inflation in Gulf labor markets represent specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Packaging Testing Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Global Package Testing Market
Packaging Testing
Pack Testing Machines Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
North America Package Testing Market