
 Laminated Bulk Bins Market | 2026-2036
Laminated Bulk Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Bulk Bins Market Analytics
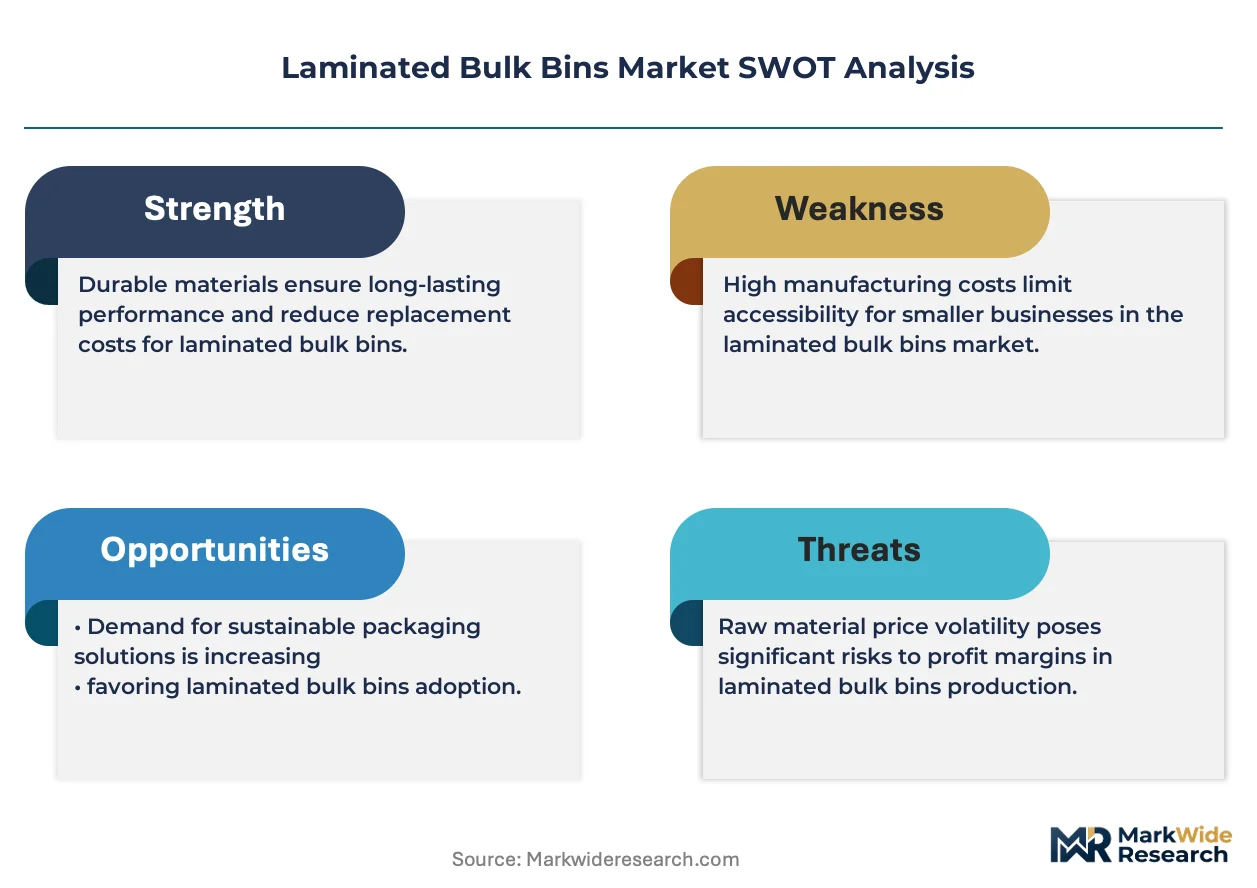
Asset-light leasing models for returnable packaging is tilting competitive dynamics toward firms with balance-sheet capacity to finance bin fleets at scale. WestRock Company leverages its integrated pulp-to-boxboard operations to control input costs across laminated bin production. Mondi Group anchors European supply through specialty kraftliner mills that feed moisture-resistant laminated grades. Smurfit Kappa Group competes via closed-loop pooling services that reduce customer capital expenditure.
Laminated bulk bins are multi-wall corrugated or composite containers bonded with moisture-barrier films, typically rated for 1,000–2,000 lb payloads and engineered for forklift handling and stacking stability in supply chain environments. Their primary purpose centers on protecting granular, powdered, or component goods from humidity and contamination during extended storage or intermodal transit. Heavy-duty bins command the strongest margin pools due to specialized reinforcement and custom dunnage requirements from industrial end users. Standard bins represent the mature volume base, while custom configurations capture growth from food industry clients seeking lot-traceable, washdown-compatible designs.
FDA food-contact regulations in the United States and EU Packaging and Packaging Waste Regulation constrain material selection and recyclability claims for laminated bulk bins sold into food and agriculture channels. REACH compliance across Europe further limits adhesive and coating chemistries, pushing converters toward water-based barrier systems. BIS certification requirements in India add testing layers for imported laminated containers, shaping market access for foreign suppliers. Stakeholders must monitor how evolving extended producer responsibility frameworks reshape total cost of ownership calculations against reusable alternatives.
Market Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing converters to redesign moisture-barrier films and adhesives, compressing margin structures for laminated bulk bin manufacturers serving food and pharmaceutical channels.
Growth Catalysts
- EU Green Deal packaging targets:Germany's automotive parts suppliers now require heavy-duty laminated bins for just-in-time assembly lines, creating sustained demand for reinforced, stackable containers rated for 1,000–2,000 lb payloads.
- Food cold chain expansion:Temperature-sensitive cargo transport is pulling laminated bulk bins into pharmaceutical and fresh produce distribution networks across France and the Netherlands.
- Returnable packaging pooling:Asset-light leasing models are tilting procurement toward closed-loop services that reduce customer capital expenditure while locking in long-term supply contracts.
Market Restraints
- REACH adhesive restrictions:ECHA limits on solvent-based coatings push converters toward water-based barrier systems with higher per-unit production costs and slower cure times.
- OCC price volatility:Old corrugated containerboard feedstock swings disrupt input cost forecasting for multi-wall laminated bin producers in Poland and Italy.
- Rigid IBC substitution:Intermediate bulk containers in HDPE and composite materials capture chemical and liquid food applications where washdown reuse is prioritized over fiber-based disposability.
Strategic Opportunities
- India BIS certification gap:Foreign laminated container suppliers face testing layers that domestic converters can exploit to capture food-contact and agriculture channel share before import compliance accelerates.
- Pharmaceutical serialization convergence:Integration of RFID-enabled lot tracking with laminated bin structures opens traceable, washdown-compatible designs for EU and US drug distribution networks.
- Extended producer responsibility frameworks:France's Citeo and Germany's ZSVR systems create financial incentives for fiber-based returnable packaging against single-use alternatives.
Industry Challenges
- Barrier film delamination:Moisture-resistant kraftliner-to-film bonding failures in high-humidity environments require reformulated adhesives and extended cure protocols that compress line throughput.
- Cross-border pooling reconciliation:Multi-country returnable bin fleets face tracking complexity and damage liability disputes that stall closed-loop adoption among mid-size logistics providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Bulk Bins Market |
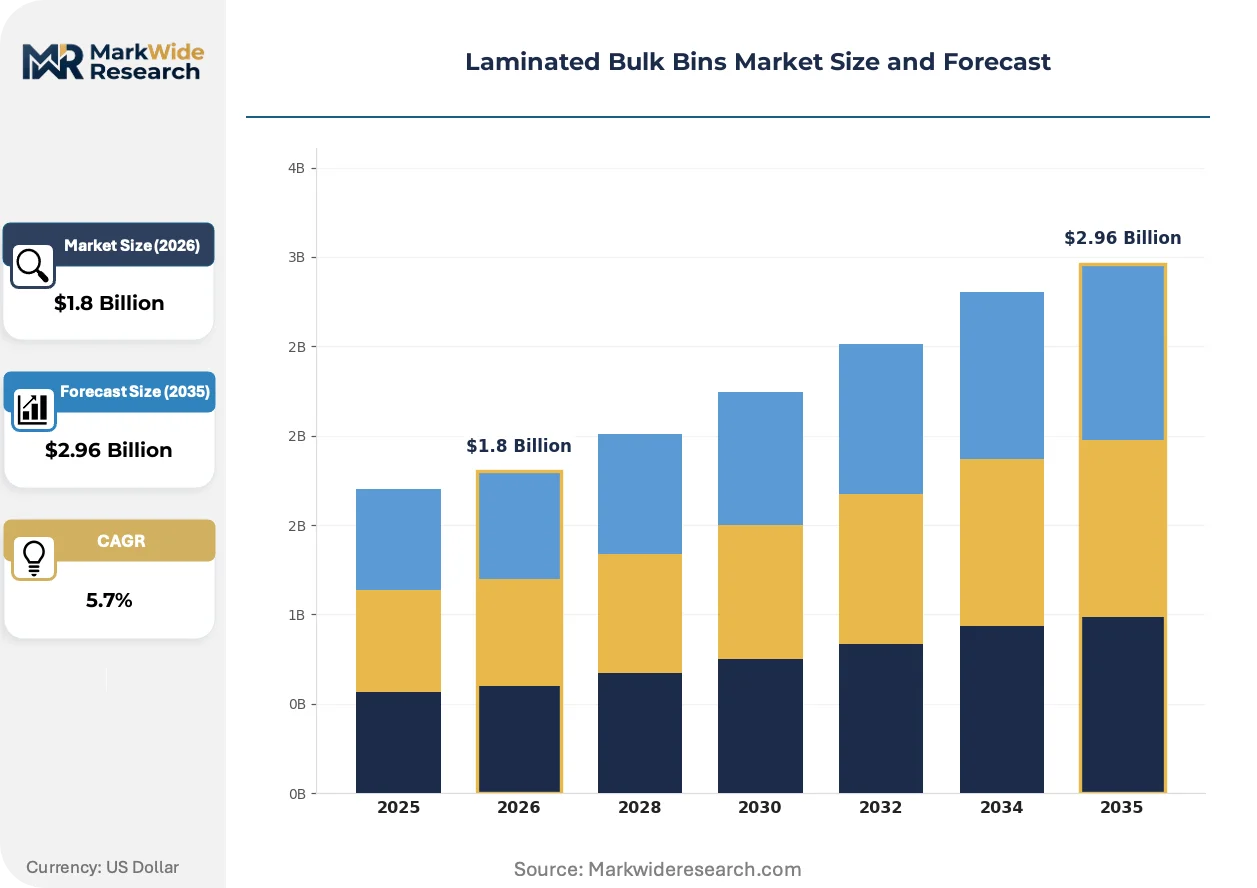
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bins, Custom Bins, Stackable Bins, Heavy-Duty Bins Material: Plywood, MDF, Hardboard, Plastic End User: Retail Stores, Warehouses, Food Industry, Agriculture Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | International Paper Company, WestRock Company, Mondi Group, Smurfit Kappa Group, DS Smith Plc, Georgia-Pacific LLC, Packaging Corporation of America, Pratt Industries, Saxon Packaging Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Bulk Bins Market Evolving Landscape
Moisture-barrier chemistry advances and digital tracking integration are compressing the performance gap between fiber-based containers and rigid alternatives, while regulatory pressure on recyclability claims accelerates material transparency requirements.
Water-based barrier coatings are collapsing the cost premium between conventional polyethylene-laminated bins and recyclable fiber alternatives. Food processors in the Netherlands and Belgium are adopting these systems at pilot scale ahead of 2030 recyclability targets. The technology is collapsing resistance from procurement teams previously wedded to legacy moisture protection specifications.
REACH Article 33 substance disclosure requirements are tightening supply chain documentation burdens for laminated bin converters selling into EU food and agriculture channels. Industrial consequence includes mandatory SCIP database entries for adhesive chemistries containing SVHC candidates. Pharmaceutical and chemical end-users in Germany and France are now demanding full material composition data as a contract precondition.
Leasing-based procurement is displacing capital purchase models among automotive and electronics manufacturers seeking to offload fleet management complexity. Pooling operators in Germany and the Czech Republic are capturing volume previously held by direct sales channels. This shift is most visible in Bavaria's automotive supplier corridor, where just-in-time delivery contracts now specify returnable packaging service fees rather than unit purchase pricing.
Laminated Bulk Bins Market Segmentation
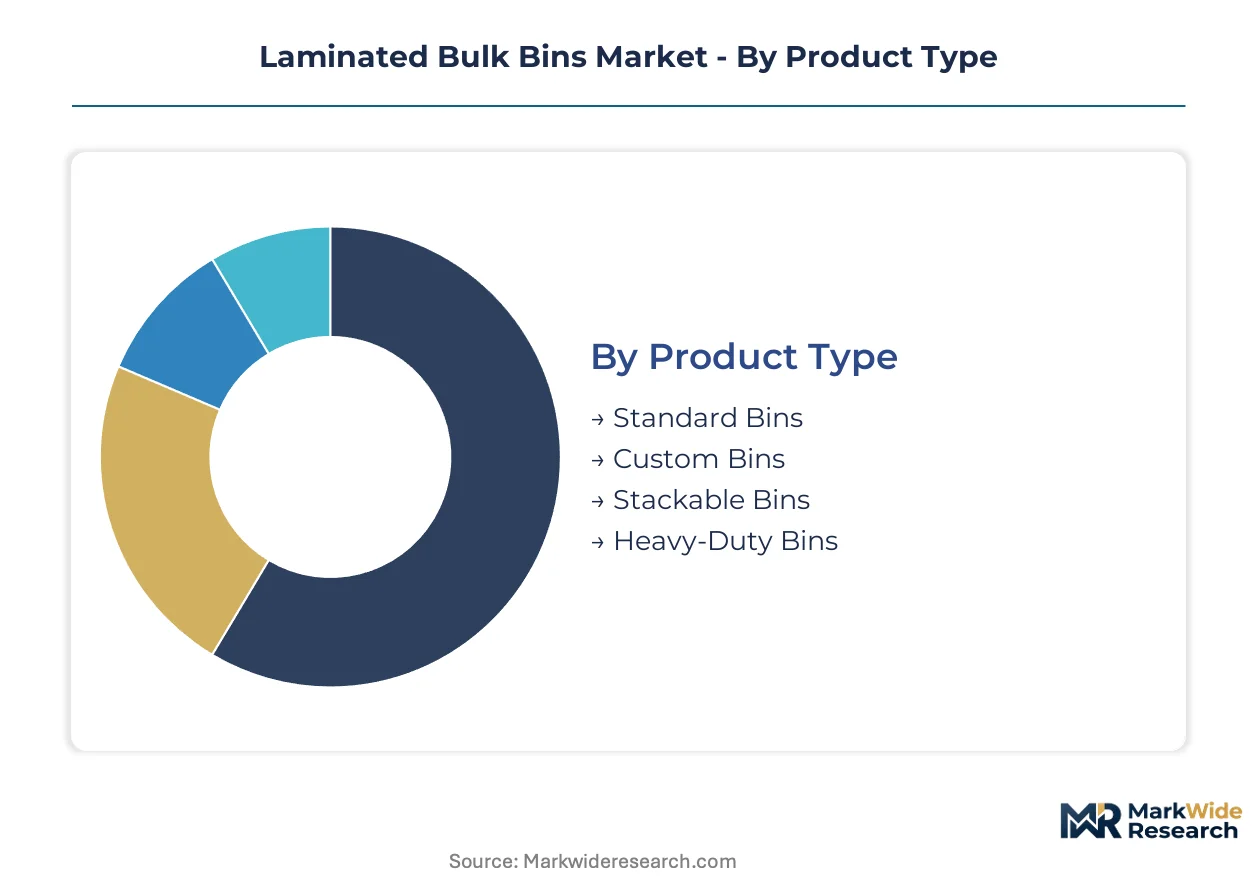
Laminated bulk bin segmentation reveals how payload requirements, moisture protection needs, and handling specifications split procurement decisions across industrial supply chains. Understanding these divides exposes where margin pools concentrate and which converter capabilities command pricing power.
Product Type:
Use-case spectrum spans commodity logistics to precision-engineered containment for sensitive cargo streams.
- Heavy-Duty Bins:Reinforced multi-wall corrugated or composite structures rated for 1,000–2,000 lb payloads with integrated forklift entry points and stacking stability features. German automotive parts suppliers anchor demand for just-in-time assembly line configurations requiring custom dunnage and damage-resistant sidewalls.
- Custom Bins:Lot-traceable, washdown-compatible designs engineered to food-contact FDA and EU Packaging and Packaging Waste Regulation standards. Temperature-sensitive cargo transport across French and Dutch pharmaceutical networks is pulling laminated bulk bins into serialization-ready formats with RFID integration.
- Standard Bins:Mature volume base serving general warehousing and non-specialized freight consolidation.
- Stackable Bins:Interlocking footprint designs optimizing cube utilization in returnable pooling fleets and multi-modal container stuffing.
The dominant share belongs to Heavy-Duty Bins, while Custom Bins is closing the gap fastest.
Material:
Cost tier stratification separates commodity fiber substrates from engineered moisture-barrier laminates.
- Plywood:Structural-grade hardwood or softwood veneers bonded with moisture-resistant adhesives, forming the substrate foundation for heavy-duty laminated bins in industrial pooling systems. REACH-compliant phenolic resins from European mills serve German automotive corridor demand.
- Plastic:HDPE and polypropylene composite panels laminated with barrier films for washdown reuse cycles in chemical and liquid food applications. Rigid IBC substitution pressure is strongest here as converters compete against reusable intermediate bulk containers.
- MDF:Medium-density fiberboard providing uniform surface quality for printed branding and retail-facing display configurations.
- Hardboard:High-density fiberboard offering cost-competitive rigidity for single-use export packaging and agricultural produce containment.
Plywood commands the installed base, though Plastic is expanding most quickly in closed-loop leasing contracts.
End User:
Customer type determines specification stringency from food-contact compliance to capital expenditure tolerance.
- Food Industry:Processors and cold chain operators requiring temperature-stable, contamination-resistant containment for granular and powdered ingredients. Netherlands and Belgium pilot programs are adopting water-based barrier coatings ahead of EU recyclability mandates.
- Agriculture:Grain handlers and produce distributors needing breathable yet moisture-protected storage for extended field-to-market intervals. India's BIS certification requirements shape domestic converter advantage against import competition.
- Warehouses:Third-party logistics providers prioritizing cube efficiency and forklift compatibility over specialized barrier performance.
- Retail Stores:Back-of-house receiving and stockroom operations favoring collapsible or nestable formats for space-constrained urban locations.
Food Industry holds the premium pricing tier, while Agriculture is gaining share fastest in emerging market expansion.
Distribution Channel:
Supply concentration patterns favor direct relationships for volume accounts versus intermediary layers for fragmented demand.
- Direct Sales:Converter-to-manufacturer relationships governing automotive and electronics sector procurement, particularly in Bavaria's supplier corridor where just-in-time contracts specify returnable packaging service fees. Asset-light leasing models lock in multi-year supply agreements with fleet management obligations.
- Distributors:Regional inventory stocking and technical support for mid-size food processors and agricultural cooperatives across Poland and Italy. Old corrugated containerboard price volatility complicates margin protection in this channel.
- Online Retail:Catalog and e-commerce platforms serving small-lot buyers and replacement bin procurement.
- Specialty Stores:Localized packaging supply outlets catering to immediate-need agricultural and light industrial customers.
Direct Sales captures the largest contract value, while Distributors is climbing the fastest in Central European market development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in corrugated fiberboard are redirecting laminated bulk bin sourcing toward regional manufacturing hubs. Germany and the United States maintain structural deficits in containerboard supply, while India and Poland emerge as net exporters of converted packaging. This trade geometry shapes where converters locate moisture-barrier lamination capacity.
Germany
Automotive parts suppliers in Bavaria and Baden-Württemberg anchor European demand for heavy-duty laminated bins rated for 1,000–2,000 lb payloads. The ZSVR extended producer responsibility system creates financial incentives for returnable fiber-based packaging against single-use alternatives. Stuttgart's supplier corridor now specifies closed-loop leasing contracts rather than unit purchase pricing for just-in-time assembly lines.
United States
Food cold chain operators across California's Central Valley and Florida's produce belt are expanding laminated bin adoption for temperature-sensitive cargo transport. FDA food-contact regulations constrain material selection for containers entering pharmaceutical and fresh produce distribution networks. Chicago's third-party logistics hub concentrates demand for stackable, forklift-compatible designs optimizing cube utilization.
India
Agricultural cooperatives in Maharashtra and Gujarat require breathable yet moisture-protected storage for extended field-to-market intervals. BIS certification requirements add testing layers for imported laminated containers, shaping domestic converter advantage against foreign suppliers. Pune's packaging manufacturing cluster is capturing food-contact and agriculture channel share before import compliance accelerates.
Netherlands
Pharmaceutical distributors in Rotterdam and Amsterdam are piloting RFID-enabled laminated bins for serialization-ready drug distribution. REACH Article 33 substance disclosure requirements tighten supply chain documentation burdens for adhesive chemistries entering EU food channels. Eindhoven's logistics technology corridor is integrating digital tracking with fiber-based container structures.
Poland
Mid-size food processors across Silesia and Greater Poland rely on distributor-stocked laminated bins for regional inventory flexibility. Old corrugated containerboard price volatility complicates margin protection for multi-wall laminated bin producers serving fragmented demand. Warsaw's packaging converter base is expanding capacity to supply German automotive suppliers seeking lower-cost sourcing alternatives.
Laminated Bulk Bins Market Competitive Landscape
On the supply side, the industry is consolidating around integrated paperboard producers with captive pulp supply and regional converters with specialized lamination expertise. Tiered competitive dynamics separate scale-driven multinational packaging groups from niche specialists in custom-engineered containment. Three archetypes dominate: vertically integrated forest products giants, regional corrugated specialists with pooling service capabilities, and independent custom fabricators serving lot-traceable pharmaceutical requirements. M&A activity concentrates on acquiring water-based barrier coating technologies, while capacity expansion targets Central European markets with automotive supplier density.
Within the integrated paperboard tier, WestRock Company and Mondi Group exemplify supply chain control strategies. WestRock leverages integrated pulp-to-boxboard operations to manage input costs across laminated bin production. Mondi anchors European supply through specialty kraftliner mills feeding moisture-resistant laminated grades. Among regional pooling specialists, Smurfit Kappa Group occupies a position defined by closed-loop services that reduce customer capital expenditure. These three represent distinct competitive vectors: upstream raw material control, regional mill network density, and asset-light fleet financing.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Mondi Group |
| Smurfit Kappa Group |
| DS Smith Plc |
| Georgia-Pacific LLC |
| Packaging Corporation of America |
| Pratt Industries |
| Saxon Packaging Limited |
| Others |
Value Network & Pricing Analysis
OCC price volatility in European containerboard markets determines both margin compression in mid-tier laminated bin production and the geographic relocation of moisture-barrier lamination capacity toward net-exporting converter hubs. This feedstock instability widens pricing spreads between heavy-duty custom configurations and commodity standard bins while accelerating backward integration among tier-one producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against raw material escalation clauses. Three-tier pricing structure across heavy-duty, custom, and standard levels reflects certification grade differentiation and customization depth. Cost compression in standard-grade segments is intensifying because water-based barrier coating transitions add per-unit production overhead. Mid-size food processors in Central Europe exhibit highest price sensitivity, while German automotive suppliers prioritize damage-resistant sidewall specifications over unit cost.
Supply Chain Analysis
Old corrugated containerboard feedstock draws from integrated pulp mills in the United States, Germany, and Poland, with specialty kraftliner production concentrated in Austrian and Swedish forest products operations. Laminated bulk bin manufacturing rests on moisture-barrier film supply from petrochemical processors, REACH-compliant adhesive formulations, and CNC-cut plywood structural components. Single-source vulnerability in solvent-based coating chemistries intensifies as ECHA restrictions phase out legacy adhesive systems. Distribution runs through converter-direct relationships for automotive volume accounts and regional distributor networks for fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laminated bulk bins market sits at a post-destocking recovery phase where automotive production normalization and food cold chain expansion are rebuilding order backlogs. Converter procurement teams are releasing pent-up demand for returnable pooling fleets after extended inventory drawdowns.
For Market Incumbents: Harden water-based barrier coating capabilities ahead of EU Packaging and Packaging Waste Regulation recyclability deadlines to defend margin position against rigid IBC substitution in chemical applications. Expand captive kraftliner supply through Austrian or Swedish mill network additions to insulate against OCC price volatility in Polish and Italian production.
For New Entrants and Emerging Players: India's agriculture sector, specifically Maharashtra and Gujarat cooperatives facing BIS certification gaps for imported containers, represents the most penetrable entry point before foreign compliance accelerates. Pharmaceutical serialization convergence in Dutch and Belgian distribution networks offers a second white-space target for RFID-integrated custom bin configurations. Pursue joint development agreements with regional logistics technology providers rather than direct fleet ownership.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty coating technology holders over commodity corrugated converters. Long-term viability centers on water-based barrier patent portfolios and closed-loop pooling software infrastructure. Watch for inflection in German ZSVR extended producer responsibility fee structures that could accelerate returnable packaging adoption against single-use alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraftliner Production | Captive supply from Swedish or Austrian mills insulates margin against OCC volatility in German automotive corridor. |
| Water-Based Barrier Coating Scale-Up | REACH-compliant adhesive transitions ahead of EU recyclability mandates capture pharmaceutical and food channel share. |
| Closed-Loop Pooling Service Expansion | Asset-light leasing models in Bavaria's supplier corridor lock in multi-year automotive contracts with fleet management obligations. |
| RFID-Enabled Serialization Integration | Rotterdam and Amsterdam pharmaceutical distributors pilot traceable, washdown-compatible designs for EU drug distribution networks. |
| India BIS Certification Pre-Compliance | Pune-based manufacturing clusters capture agriculture channel share before import testing layers accelerate for foreign suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from converter operations directors, automotive Tier 1 procurement managers, food cold chain logistics planners, and adhesive formulation chemists and refined through secondary validation against SEC filings of integrated paperboard producers, EU ECHA substance restriction updates, German ZSVR extended producer responsibility documentation, and Indian BIS certification schedules. Bottom-up volume builds across payload ratings and moisture-barrier specifications were triangulated against top-down macro demand indicators.
Demand-supply balance modeling across the projection horizon incorporated payload tier segmentation, material substrate categories, end-use industry specifications, and distribution channel structures. CAGRs were derived from weighted regression across historical shipment data and forward-looking capacity expansion announcements. Industry-specific forecast inputs included automotive production schedules in Baden-Württemberg and Bavaria, EU pharmaceutical serialization implementation timelines, and Indian agricultural export seasonality patterns.
Macroeconomic conditions sit as an overlay; deviation in European natural gas pricing, ocean freight rates for kraftliner imports, and Indian rupee exchange stability would shift the trajectory. Forecasts reflect documented assumptions regarding REACH adhesive phase-out schedules and EU Green Deal packaging target enforcement intensity. Cross-checking against German automotive supplier association order intake reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Container Stacking Machine Market
Containers
Canning Jars Market
Containers
Slip Lid Can Market
Containers
Sanitary Cans Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Sample Containers Market
Containers
Container Market
Containers
Slotted Containers Market
Containers
Multi Cavity Tray Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Stock Clamshell Packaging Market
Containers
PVC Container Market
Containers
Americas Container Technology Market
Containers
Popcorn Containers Market
Containers
Stackable Container Market
Containers
Global Multi Pack Carriers Market