
 Tubes and Cores Market | 2026-2036
Tubes and Cores Market Size, Share, and Industry Trends Forecast 2026-2036
Tubes and Cores Market Outlook
Single-source procurement for paper-based tubes is shifting toward multi-source agreements across European and North American converters. Smurfit Kappa Group PLC anchors its position through captive containerboard supply. Greif Inc. competes with metal and composite alternatives for industrial chemical applications. Sonoco Products Co. leverages its global mill network to sustain pricing leverage in fiberboard cores.
Tubes and cores are cylindrical support structures manufactured from wound paperboard, extruded plastic, or rolled metal, typically specified by crush strength, wall thickness, and moisture resistance to protect rolled goods during handling, storage, and transport. Fiberboard dominates volume across packaging applications where radial crush performance and recyclability determine specification. Plastic cores lead in textile and film winding where dimensional stability and moisture immunity command premium positioning. Composite constructions occupy niche high-performance segments requiring hybrid strength-to-weight ratios.
EPA guidelines on recycled fiber content shape North American sourcing standards, while REACH compliance governs adhesive and coating chemistries in European tube manufacturing. FDA food-contact regulations constrain plastic core formulations for dairy and produce film applications. Stakeholders must monitor evolving extended producer responsibility frameworks that will recalibrate material cost structures and regional sourcing decisions.
Market Dynamics
E-commerce fulfillment networks are compressing specification cycles for fiberboard shipping cores, forcing converters to synchronize production with just-in-time warehouse replenishment rhythms rather than quarterly contract manufacturing.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated recycled content thresholds are redirecting procurement toward certified fiberboard suppliers with verified post-consumer waste streams, tightening qualification windows for non-compliant converters.
- Film and textile winding automation:High-speed spooling lines in polyester and specialty film manufacturing require plastic cores with sub-millimeter runout tolerances, creating specification premiums that displace fiberboard in precision segments.
- Germany's industrial packaging corridor:Concentrated demand from automotive component suppliers and chemical distributors in Baden-Württemberg and North Rhine-Westphalia sustains dedicated tube production capacity with regional feedstock integration.
Market Restraints
- Old corrugated containerboard price volatility:Recovered fiber input costs swing with municipal collection program yields, compressing converter margins during supply disruptions from weather or logistics bottlenecks.
- REACH adhesive compliance:Restricted substance lists for formaldehyde and isocyanate-based bonding agents force European tube manufacturers into costly formulation substitutions with extended curing protocols.
- Composite core substitution:Hybrid fiber-glass and carbon-reinforced constructions capture wind blade and aerospace tape winding applications where specific strength requirements exceed wound paperboard capabilities.
Strategic Opportunities
- India's organized retail expansion:Modern trade and quick-commerce fulfillment centers in Mumbai, Delhi NCR, and Bangalore generate virgin demand for standardized shipping cores with barcode-compatible outer diameters.
- Biodegradable coating chemistry:Water-based barrier treatments that match polyethylene moisture resistance without compromising repulpability open food-contact film winding applications previously reserved for plastic cores.
- Digital print-on-demand integration:Direct-to-core branding capabilities allow converters to capture value-added decoration services from label converters seeking supply chain consolidation.
Industry Challenges
- Skilled slitter-operator scarcity:Precision spiral winding requires tacit knowledge of tension control and adhesive viscosity management that retiring workforces in Midwestern US and Northern Italian mills have not transferred systematically.
- Extended FDA food-contact certification timelines:New resin formulations for dairy film cores face 18-24 month migration testing protocols that delay commercialization against faster-moving Asian competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubes and Cores Market |
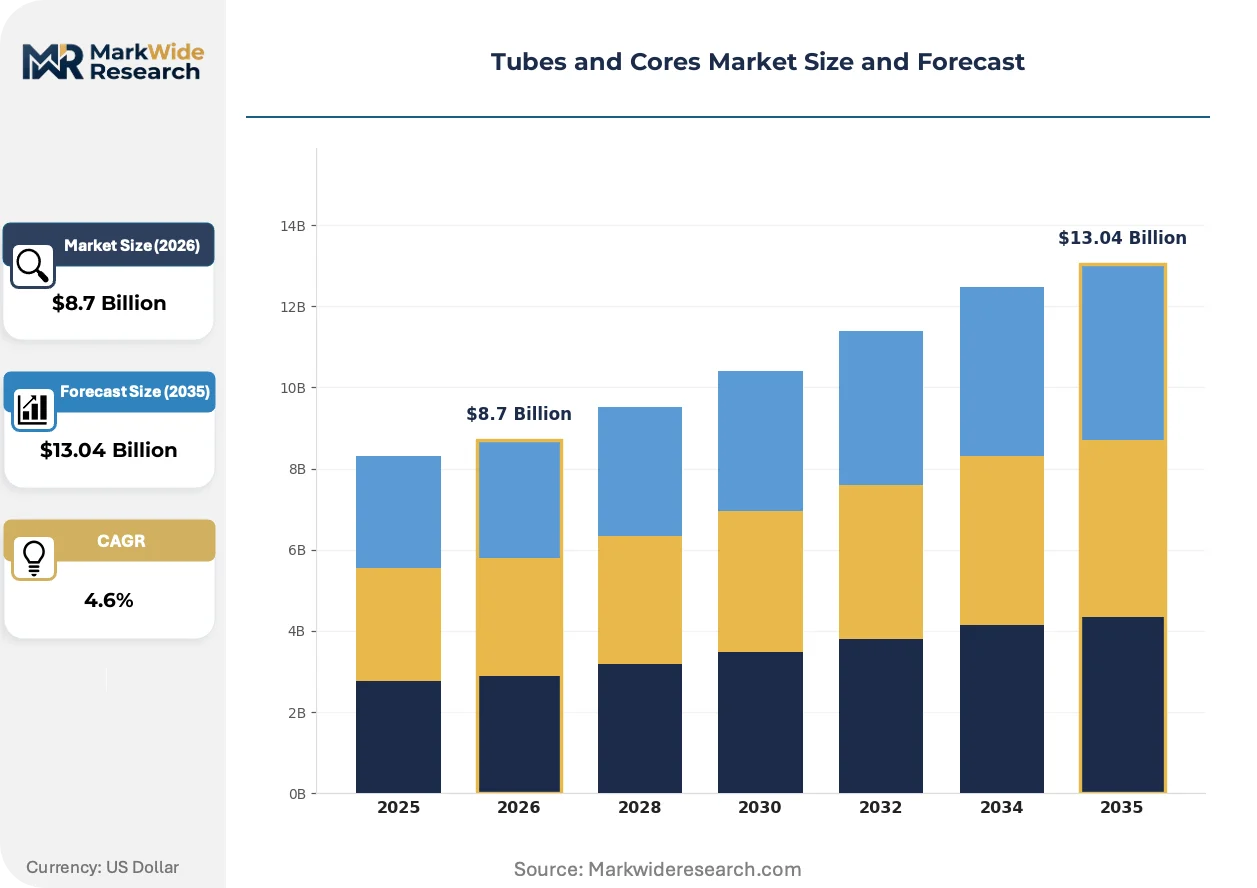
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberboard, Plastic, Metal, Composite Application: Packaging, Construction, Printing, Textiles End User: Manufacturers, Retailers, Distributors, Exporters Distribution Channel: Online, Direct Sales, Wholesalers, Agents |
| Companies Covered | Sonoco Products Co., Smurfit Kappa Group PLC, VPK Group, Greif Inc., Ace Paper Tube, Albert Eger GmbH and Co. KG, Corex Group, Chicago Mailing Tube Co., International Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubes and Cores Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine performance specifications across fiberboard, plastic, and composite core categories, with sustainability credentials now embedded in technical qualification rather than treated as secondary attributes.
High-precision laser-perforation systems for controlled moisture release are rewriting manufacturing protocols for hygroscopic goods protection. Pharmaceutical and specialty paper converters in Switzerland and the Netherlands are specifying perforated fiberboard cores that maintain dimensional stability through humidity cycling without secondary wrapping. This capability is compressing total packaging mass and eliminating desiccant inserts in temperature-sensitive shipments.
REACH Annex XVII restrictions on persistent organic pollutants are forcing adhesive reformulation across European tube manufacturing. Manufacturers serving industrial film and textile markets are shifting from solvent-based to hot-melt and waterborne bonding systems, accepting longer cure times and modified crush strength profiles. German chemical distributors and French luxury textile houses are driving this transition through supply chain audit requirements that exclude legacy formulations.
Consolidated buying desks at major e-commerce fulfillment operators are unbundling core supply from parent roll purchasing. Amazon and specialized third-party logistics providers in the US and UK now negotiate direct tube contracts with converters, bypassing traditional paper merchant intermediaries. This disintermediation concentrates volume with qualified suppliers capable of national distribution footprint and electronic data interchange integration.
Tubes and Cores Market Segmentation
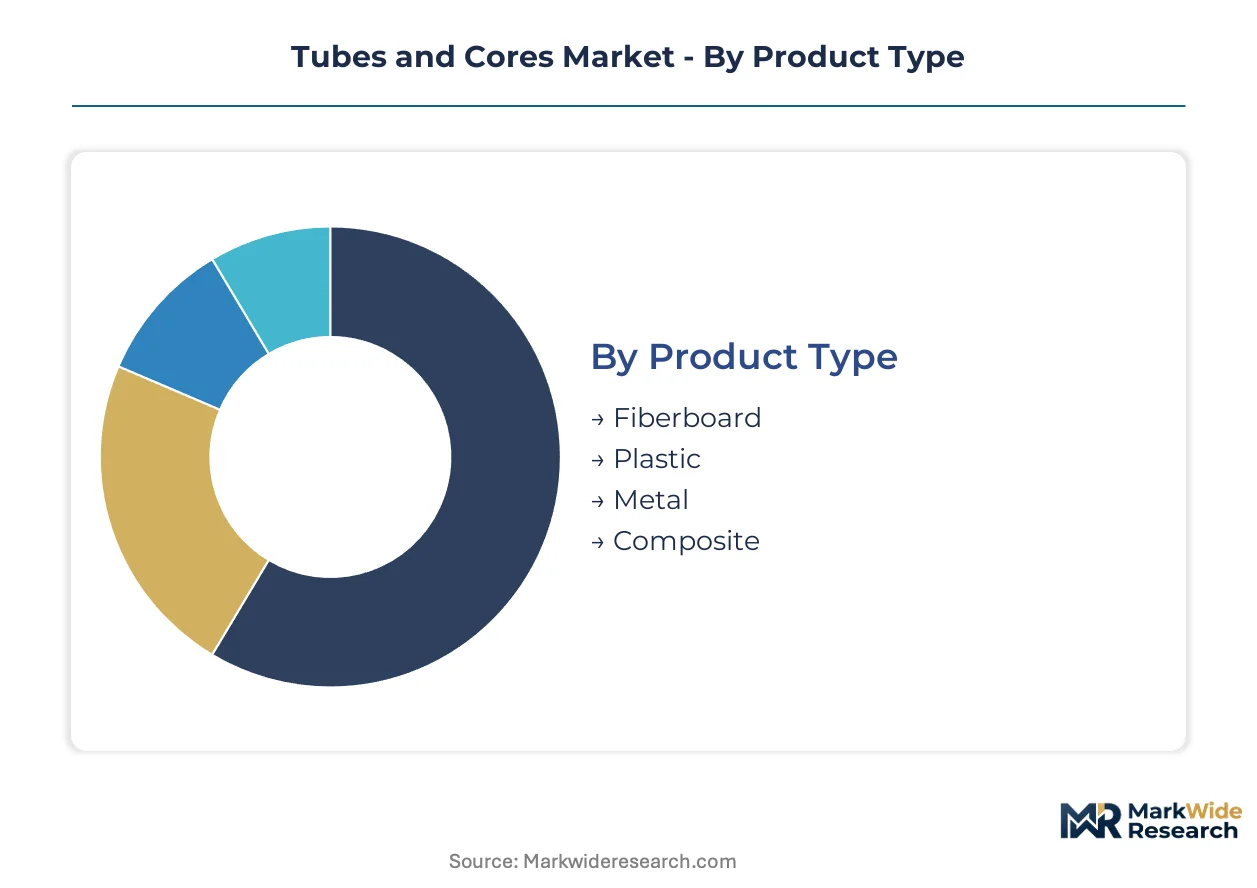
Specification divergence across fiberboard, plastic, and composite constructions creates distinct procurement ecosystems with non-overlapping supplier qualifications. End-use requirements for crush strength, moisture resistance, and dimensional tolerance determine material selection more than price elasticity.
Product Type:
Supply concentration in fiberboard manufacturing clusters around integrated paperboard mills with captive recovered fiber streams.
- Fiberboard:Wound paperboard construction specified by radial crush strength and caliper thickness dominates e-commerce shipping and industrial film winding. German automotive component suppliers in Baden-Württemberg specify high-recycled-content fiberboard cores under EU Packaging and Packaging Waste Regulation mandates.
- Plastic:Extruded polyethylene and polypropylene cores deliver sub-millimeter runout tolerances for high-speed polyester film spooling lines. REACH Annex XVII restrictions on adhesive chemistries are accelerating substitution toward plastic in precision textile winding applications where dimensional stability commands premium positioning.
- Metal:Rolled steel and aluminum cores serve heavy-gauge metal coil and wire rope applications requiring extreme crush resistance.
- Composite:Hybrid fiber-glass and carbon-reinforced constructions occupy wind blade and aerospace tape winding niches.
Fiberboard absorbs the bulk of installed capacity; plastic is expanding most quickly.
Application:
Cost tier stratification separates commodity shipping cores from precision-engineered constructions for automated manufacturing lines.
- Packaging:E-commerce fulfillment centers drive standardized fiberboard specifications with barcode-compatible outer diameters and just-in-time replenishment rhythms. Amazon's consolidated buying desk now negotiates direct tube contracts bypassing traditional paper merchant intermediaries.
- Construction:Concrete form tubes and structural column voids require moisture-resistant treatments and specified compressive loads.
- Printing:Narrow-web label and flexible packaging converters specify precision-wound cores for digital press feeding systems.
- Textiles:Luxury French textile houses enforce supply chain audits that exclude legacy solvent-based adhesive formulations.
Packaging commands the largest volume footprint; textiles is climbing the fastest on automation-driven specification premiums.
End User:
Customer type determines contract structure, with manufacturers seeking technical qualification partnerships and retailers prioritizing logistics integration.
- Manufacturers:Industrial film and paper converters maintain approved supplier lists with mill audits and migration testing protocols. FDA food-contact certification timelines of 18-24 months for new dairy film core formulations create switching costs.
- Retailers:Quick-commerce fulfillment operators in India generate virgin demand for standardized shipping cores with national distribution footprints.
- Distributors:Chemical distributors in Germany's North Rhine-Westphalia corridor sustain dedicated tube production capacity with regional feedstock integration.
- Exporters:Cross-border shippers face fragmented compliance with EPA recycled fiber guidelines, REACH adhesive restrictions, and destination-market packaging regulations.
Manufacturers lock in the longest contract tenures; retailers are gaining share fastest through disintermediation.
Distribution Channel:
Volume concentration favors direct relationships with qualified converters capable of electronic data interchange integration.
- Online:Digital procurement platforms aggregate spot demand from small converters and specialty manufacturers.
- Direct Sales:National distribution footprints with just-in-time synchronization capture e-commerce fulfillment volume from Amazon and UK third-party logistics providers.
- Wholesalers:Regional paper merchants face margin compression as consolidated buying desks unbundle core supply from parent roll purchasing.
- Agents:Independent representatives serve fragmented textile and specialty film manufacturers in Switzerland and the Netherlands with perforated fiberboard specifications.
Direct sales holds the dominant share; online is gaining traction fastest among small and mid-sized converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recovered fiber availability in the Midwestern United States and industrial packaging corridors in southwestern Germany anchor regional supply configurations. EU Packaging and Packaging Waste Regulation mandates and EPA recycled fiber guidelines reshape procurement patterns across major demand centers.
United States
E-commerce fulfillment operators in the Midwest and Southeast drive fiberboard shipping core consumption with just-in-time replenishment requirements. EPA guidelines on recycled fiber content shape North American sourcing standards for converters serving Amazon and third-party logistics networks. Chicago and Atlanta metropolitan areas concentrate tube manufacturing capacity with captive containerboard mill integration.
Germany
Automotive component suppliers and chemical distributors in Baden-Württemberg and North Rhine-Westphalia sustain dedicated production capacity with regional feedstock integration. REACH compliance governs adhesive and coating chemistries in European tube manufacturing, forcing costly formulation substitutions. Stuttgart and Düsseldorf industrial corridors enforce supply chain audits that exclude legacy solvent-based bonding systems.
China
Domestic e-commerce platforms and export-oriented textile manufacturers absorb substantial fiberboard and plastic core volumes. GB standards and MIIT industrial policies guide packaging material specifications for cross-border shipments. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate precision winding core production for polyester film exports.
India
Modern trade and quick-commerce fulfillment centers in Mumbai, Delhi NCR, and Bangalore generate virgin demand for standardized shipping cores. BIS certification requirements and DGFT import regulations shape material sourcing decisions for domestic converters. Maharashtra and Karnataka industrial zones attract regional tube production investments to serve organized retail expansion.
Switzerland
Pharmaceutical and specialty paper converters in Basel and Zurich specify laser-perforated fiberboard cores for humidity-sensitive shipments. Swissmedic quality frameworks and REACH Annex XVII restrictions elevate technical qualification thresholds for adhesive formulations. Swiss precision manufacturing culture drives specification premiums for dimensional stability in temperature-controlled logistics.
Tubes and Cores Market Competitive Environment
Capacity expansion dominates the current landscape as integrated paperboard mills and independent converters race to capture e-commerce fulfillment volume. The market structures around three tiers: multinational packaging conglomerates with captive fiber supply, regional specialists with niche technical qualifications, and commodity converters competing on spot pricing. Two strategic archetypes predominate: backward-integrated mills leveraging upstream control over recovered fiber streams, and precision specialists commanding specification premiums in textile and film winding. Competitive intensity concentrates in M&A activity targeting regional converters with established logistics footprints, and strategic partnerships between tube manufacturers and e-commerce operators seeking direct supply relationships.
Within the multinational tier, Sonoco Products Co., Smurfit Kappa Group PLC, and Greif Inc. exemplify divergent strategic positions. Sonoco represents the globally integrated archetype with mill network coverage sustaining pricing leverage. Smurfit Kappa anchors the European position through captive containerboard supply and regional feedstock integration. Greif occupies the industrial applications vector, competing with metal and composite alternatives for chemical handling and heavy-gauge winding requirements. These three entities collectively illustrate how scale, vertical integration depth, and end-use specialization fragment competitive positioning across fiberboard, plastic, and hybrid core categories.
| Leading Market Players |
|---|
| Sonoco Products Co. |
| Smurfit Kappa Group PLC |
| VPK Group |
| Greif Inc. |
| Ace Paper Tube |
| Albert Eger GmbH and Co. KG |
| Corex Group |
| Chicago Mailing Tube Co. |
| International Paper |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation recycled content thresholds gate qualified supply and premium-tier pricing access, forcing converters to absorb certification costs or retreat to commodity spot markets. Buyers seeking verified post-consumer fiberboard streams pay specification premiums that widen spreads between compliant and non-compliant supplier tiers.
Pricing Analysis
Warranty and technical qualification bundling separates premium fiberboard contracts from unbundled spot purchases. Three-tier pricing structure across certified sustainable, standard industrial, and economy spot levels reflects REACH adhesive compliance costs and FDA food-contact certification investments. Pricing pressure stems from old corrugated containerboard volatility compressing converter margins. Small textile manufacturers show highest price sensitivity; pharmaceutical converters accept premiums for Swissmedic-grade dimensional stability.
Supply Chain Analysis
Recovered fiber supply rests on Midwestern US municipal collection programs and German industrial packaging corridor mill networks. Wound paperboard, extruded polyethylene, and hot-melt adhesive formulations anchor raw material dependencies. Single-source vulnerability concentrates in spiral-winding equipment and skilled slitter-operator knowledge. Distribution runs through direct converter relationships with Amazon and UK third-party logistics providers, bypassing regional paper merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around converters with captive fiber supply and e-commerce fulfillment integration, as REACH compliance costs and just-in-time logistics requirements force sub-scale competitors toward exit.
For Market Incumbents: Deploy mill network coverage to synchronize production with Amazon's just-in-time replenishment rhythms. Capture stranded regional converter capacity through acquisition in Germany's Baden-Württemberg and North Rhine-Westphalia corridors. Offset composite core substitution threats in wind blade applications by deepening captive containerboard integration. For New Entrants and Emerging Players: Launch via digital procurement platforms serving small Swiss and Dutch pharmaceutical converters seeking laser-perforated fiberboard specifications. Target India's quick-commerce fulfillment centers in Mumbai and Bangalore with barcode-compatible outer diameter standardization. Penetrate through biodegradable coating chemistry partnerships that unlock food-contact film winding previously reserved for plastic cores. For Investors and Strategic Acquirers: Amazon's unbundling of core supply from parent roll purchasing is the leading indicator that direct converter relationships will concentrate volume with national distribution footprint holders. Five-to-ten year viability favors regional specialists with established logistics integration and REACH-compliant adhesive formulation capabilities. Watch for extended FDA food-contact certification timeline delays as signals of switching cost moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Streams | Captive old corrugated containerboard supply insulates margins from municipal collection volatility. |
| Direct E-Commerce Fulfillment Contracts | Amazon's consolidated buying desk concentrates volume with EDI-integrated national converters. |
| Biodegradable Coating Chemistry Development | Water-based barrier treatments open food-contact applications previously reserved for plastic cores. |
| Laser-Perforation System Investment | Swiss pharmaceutical converters specify humidity-controlled fiberboard for temperature-sensitive shipments. |
| Regional Tube Production Capacity Expansion | Maharashtra and Karnataka industrial zones attract investment to serve India's organized retail expansion. |
Study Parameters
Document review covered customs and trade data, SEC filings from integrated paperboard mills, and EU regulatory submissions, complemented by interviews with spiral-winding plant managers, procurement leads at polyester film manufacturers, and distribution channel partners. Bottom-up volume modeling triangulated against top-down spending analysis from e-commerce fulfillment operators and automotive component suppliers.
Historical capacity utilization patterns cross-referenced against panel input from tube converter executives anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material construction type, end-use application, customer contract structure, and regional regulatory cluster. CAGRs derived from shipment volume trajectories, input cost indices, and specification premium capture rates in precision textile winding.
Old corrugated containerboard price volatility, REACH adhesive reformulation delays, and FDA food-contact certification timeline extensions are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Urn Liners Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Laminated Tubes Market