
 Myanmar Packaging Market | 2026-2036
Myanmar Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Packaging Market Foresight
Polyethylene terephthalate is hardening its position against glass in Myanmar's beverage sector as weight-based logistics costs climb and breakage rates erode margins. Daibochi Packaging Myanmar leverages its blown film extrusion lines to supply snack and instant-noodle brands with metallized laminates. Oji Myanmar Packaging Co., Ltd. anchors the corrugated segment through containerboard integration with its regional pulp network. Double Packaging Myanmar Co. Limited competes in rigid plastics by controlling distribution into Yangon's Thanlyin zone.
Myanmar packaging encompasses the design, manufacture, and supply of enclosures, wraps, and containers that protect, preserve, and present goods for distribution, retail, and end-use consumption. The sector spans materials from 200-350 gsm kraft linerboard for corrugated cases to multilayer coextruded films with oxygen transmission rates below 10 cc/m²/day for oxygen-sensitive foods. Flexible packaging leads volume due to its dominance in instant-noodle sachets and edible-oil pouches, while rigid packaging commands stronger unit margins in pharmaceutical blister packs and personal-care bottles. Food and beverage applications absorb the majority of domestic board and film output, though e-commerce end users are accelerating demand for protective air-cell formats and tamper-evident closures.
Myanmar's national standards body, the Department of Research and Innovation under the Ministry of Education, administers packaging-related technical specifications alongside the Food and Drug Administration's contact-material safety rules. The Central Committee for Drug Abuse Control also influences pharmaceutical packaging through traceability mandates that shape barrier-film and serialization investments. Stakeholders must monitor whether Thanlyin's industrial zone expands utility capacity fast enough to support converter migration from imported resin toward domestic paperboard and biopolymer alternatives.
Market Dynamics
Myanmar's packaging sector pivots on a single structural force: the Ministry of Industry and Commerce's tightening of import licensing for pre-used plastic resin. This regulatory compression redirects converter investment toward domestic paperboard capacity and biopolymer pilot lines, reshaping material flows through Yangon's Thanlyin industrial zone and Mandalay's packaging cluster.
Growth Catalysts
- Import Licensing Restrictions:The Ministry of Industry and Commerce's stricter controls on pre-used plastic resin imports force converters to source kraft linerboard and containerboard domestically, accelerating local paperboard mill utilization.
- Instant-Noodle Sachet Demand:Food and beverage producers in Yangon's Thanlyin zone expand metallized laminate orders for seasoning and oil sachets, pulling flexible film capacity toward oxygen-barrier coextrusion.
- Pharmaceutical Traceability Mandates:The Central Committee for Drug Abuse Control's serialization requirements drive barrier-film investments and tamper-evident blister pack adoption across domestic drug manufacturers.
Market Restraints
- Resin Import Dependency:Pre-used plastic resin licensing delays create raw material volatility for rigid plastics converters serving personal-care and pharmaceutical bottle segments.
- Utility Capacity Bottlenecks:Thanlyin industrial zone's unreliable electricity supply constrains blown film extrusion uptime, forcing converters to maintain diesel generator backup at elevated operating cost.
- Glass Substitution Limits:Premium beverage brands retain glass for perceived quality differentiation, capping polyethylene terephthalate penetration in high-margin spirits and craft beer categories.
Strategic Opportunities
- E-Commerce Protective Formats:Air-cell cushioning and tamper-evident closures for last-mile delivery represent underdeveloped white space as Yangon's logistics networks expand parcel volumes.
- Biopolymer Pilots:The Ministry of Industry and Commerce's implicit preference for domestic alternatives creates regulatory tailwind for PLA and starch-based film trials in edible-oil pouches.
- Mandalay Cluster Expansion:Packaging converters can establish satellite extrusion and corrugating capacity in Myanmar's second city to capture northern state distribution routes before competitors consolidate land positions.
Industry Challenges
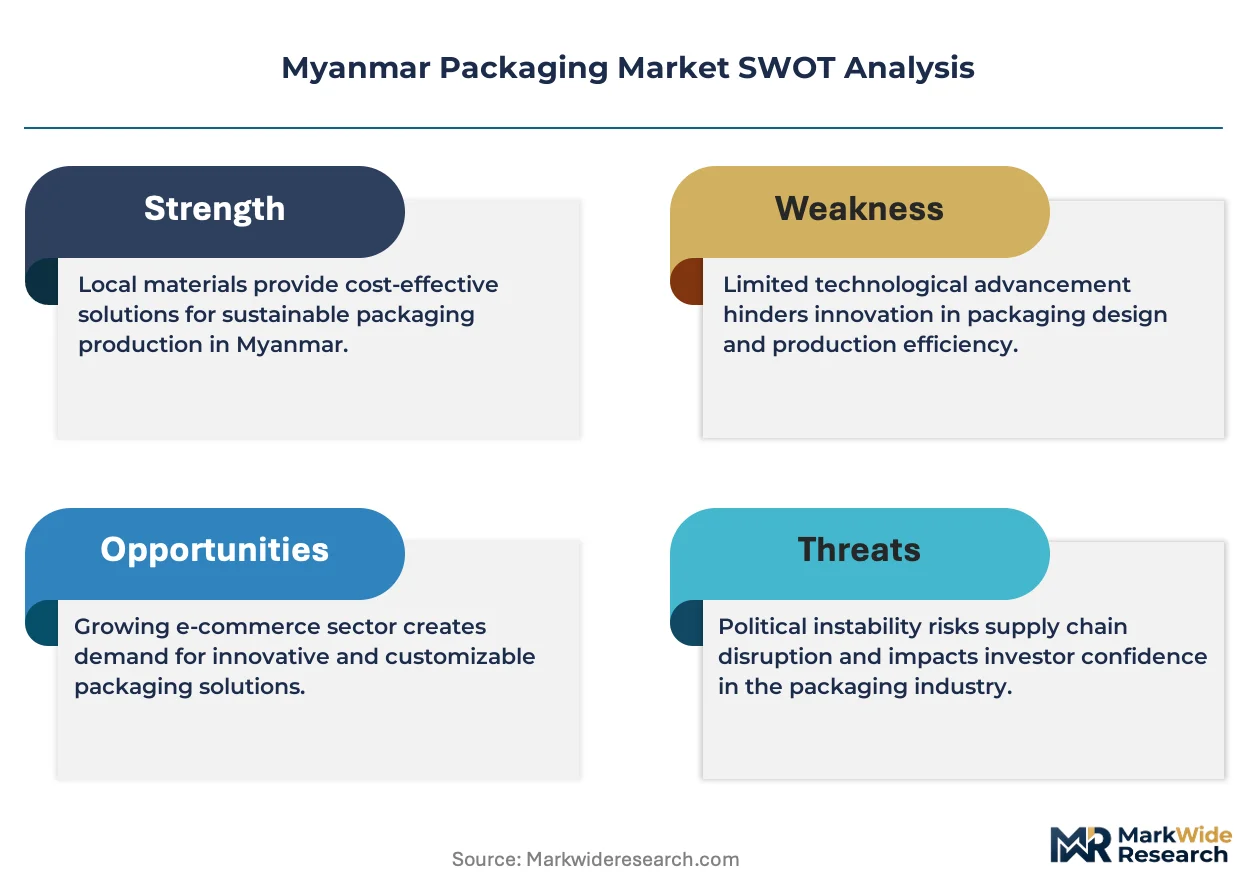
- Barrier Film Technician Scarcity:Coextrusion die setup and oxygen transmission rate testing require specialized skills absent from Myanmar's technical training institutes, forcing converters to import Thai or Vietnamese supervisors.
- Multi-Layer Lamination Capex:Metallized film capacity demands vacuum metallizers and solvent-free adhesive laminators requiring seven-figure dollar investments beyond mid-tier converter balance sheets.
- FDA Contact-Material Certification:Food and Drug Administration safety documentation timelines stretch six to nine months, delaying new packaging format launches for export-oriented food processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Packaging Market |
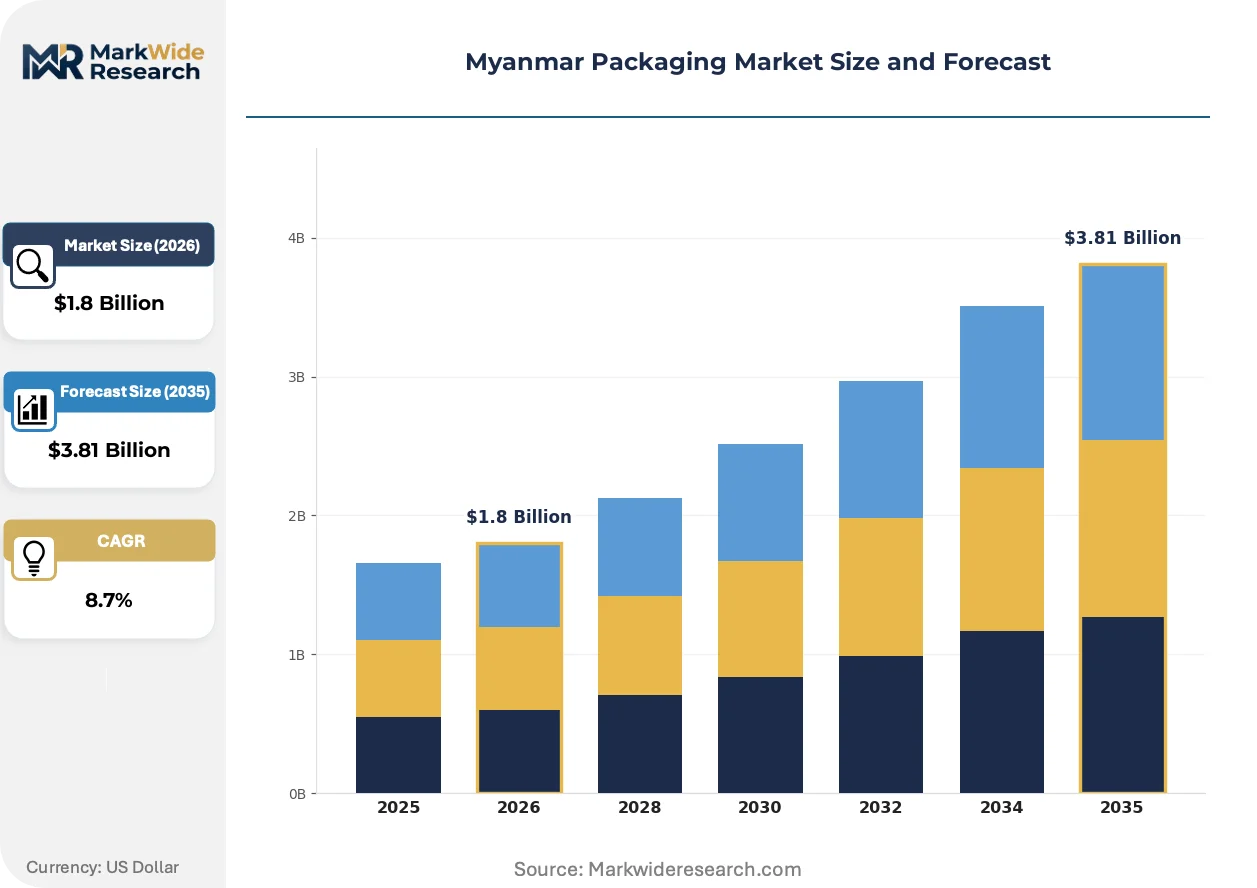
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Container, Protective Packaging Material: Plastic, Glass, Metal, Paperboard Application: Food & Beverage, Pharmaceuticals, Personal Care, Industrial Goods End User: Retail, Wholesale, E-commerce, Manufacturing |
| Companies Covered | Can-One Berhad, May Kha San Family Co Ltd, Daibochi Packaging Myanmar, Jackway Convertor Industries Pte Ltd, Tharaphusan Plastic, Oji Myanmar Packaging Co., Ltd., Double Packaging Myanmar Co. Limited, Diamond Printing Myanmar, Ball Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Packaging Market Shifts & Advancements
Material substitution and regulatory compression are actively reshaping Myanmar's packaging value chain. Converters reconfigure extrusion assets while buyers rewrite supplier qualification criteria around traceability and domestic content.
Metallized polyester film is consolidating its position in oxygen-sensitive snack and instant-noodle packaging. Domestic brands operating from Yangon's Thanlyin zone now specify 12-micron metallized structures as standard, displacing aluminum foil laminates at pace. This technology compression enables lighter pouch weights and reduced freight costs while maintaining sub-10 cc/m²/day oxygen transmission rates.
The Ministry of Industry and Commerce's import licensing framework for pre-used plastic resin functions as de facto industrial policy. Converters face extended procurement cycles for polyethylene and polypropylene feedstock, redirecting capital toward containerboard integration and biopolymer trials. Rigid plastics segments serving pharmaceutical blister packs absorb the most friction, as medical-grade resin purity requirements limit domestic substitution options.
Brand procurement teams now weight domestic content ratios heavily in supplier scorecards. Food and beverage manufacturers in Mandalay's packaging cluster favor converters with captive kraft linerboard supply or verified biopolymer pilot lines, displacing traditional price-only tendering. This preference shift concentrates contract awards toward vertically integrated paperboard producers with Ministry of Industry and Commerce certification documentation.
Myanmar Packaging Market Segmentation
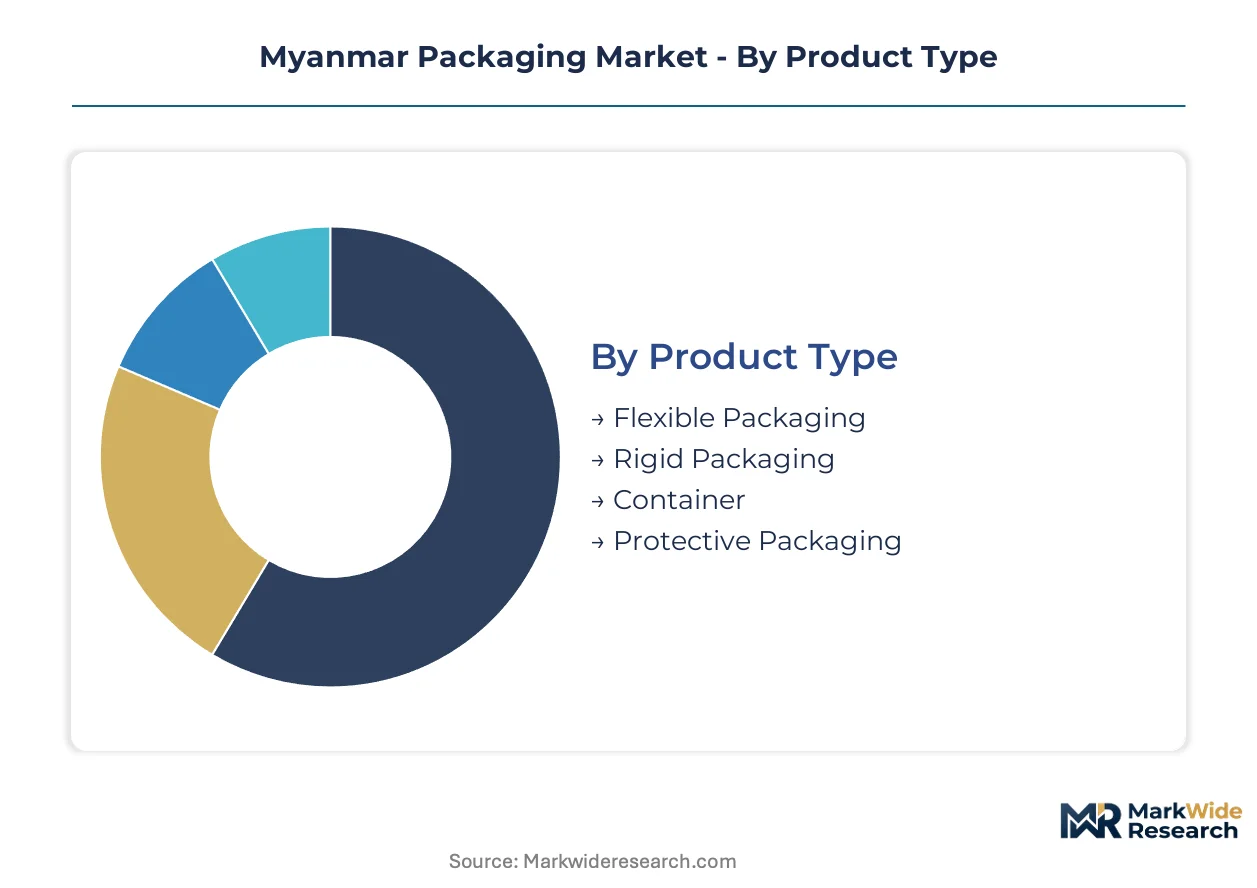
Myanmar's packaging market segments reflect divergent supply chain pressures and regulatory redirection. Material substitution dynamics and end-use concentration in Yangon's industrial corridor shape how converters allocate capacity across product categories.
Product Type:
Flexible formats operate as standalone solutions for high-volume food applications, while rigid and protective systems embed into broader logistics and retail infrastructure.
- Flexible Packaging:Multilayer coextruded films with metallized polyester barriers dominate instant-noodle sachets and edible-oil pouches. Demand concentrates in Yangon's Thanlyin zone where blown film extrusion lines serve seasoning and condiment brands. The Ministry of Industry and Commerce's resin licensing restrictions accelerate converter migration toward paperboard laminates and biopolymer trials.
- Rigid Packaging:Injection-molded polyethylene terephthalate bottles and polypropylene containers serve pharmaceutical blister packs and personal-care applications. Mandalay's packaging cluster absorbs rigid plastics capacity for northern state distribution, though medical-grade resin purity requirements limit domestic feedstock substitution.
- Container:Corrugated cases from 200-350 gsm kraft linerboard protect agricultural exports and processed foods. Oji Myanmar Packaging anchors this segment through containerboard integration with regional pulp networks.
- Protective Packaging:Air-cell cushioning and void-fill formats address e-commerce parcel growth. Last-mile logistics expansion in Yangon drives tamper-evident closure adoption alongside protective formats.
Flexible packaging leads volumes today; protective packaging is gaining share fastest.
Material:
Cost tiers separate commodity feedstocks from specialized barrier substrates, with regulatory pressure reshaping procurement patterns across converter tiers.
- Plastic:Polyethylene and polypropylene films, bottles, and thermoformed trays serve mass-market food and personal-care segments. Pre-used resin import licensing delays create volatility for rigid plastics converters.
- Paperboard:Kraft linerboard and containerboard gain share as the Ministry of Industry and Commerce tightens plastic resin access. Domestic mill utilization accelerates for corrugated cases and folding cartons.
- Glass:Premium beverage brands retain glass bottles for spirits and craft beer quality differentiation. Weight-based logistics costs and breakage rates constrain volume expansion.
- Metal:Aluminum cans and steel drums serve industrial lubricants and select beverage categories. Limited domestic canning capacity restricts segment scale.
Paperboard climbs the fastest; plastic retains dominant volume position.
Application:
Customer maturity varies sharply: food and beverage buyers drive standardization while pharmaceutical procurement demands certified barrier performance.
- Food & Beverage:Instant-noodle manufacturers and edible-oil processors absorb majority domestic board and film output. Metallized laminate specifications from Thanlyin zone brands standardize at 12-micron oxygen-barrier structures.
- Pharmaceuticals:The Central Committee for Drug Abuse Control's serialization mandates shape barrier-film and tamper-evident blister pack investments. FDA contact-material certification timelines stretch six to nine months for new format launches.
- Personal Care:Shampoo and cosmetic bottles face resin import dependency constraints. Premium positioning sustains rigid plastics demand despite feedstock volatility.
- Industrial Goods:Lubricants and agricultural chemicals require chemical-resistant drums and intermediate bulk containers. Northern state manufacturing pulls capacity toward Mandalay cluster.
Food and beverage leads volumes today; pharmaceuticals is expanding most quickly.
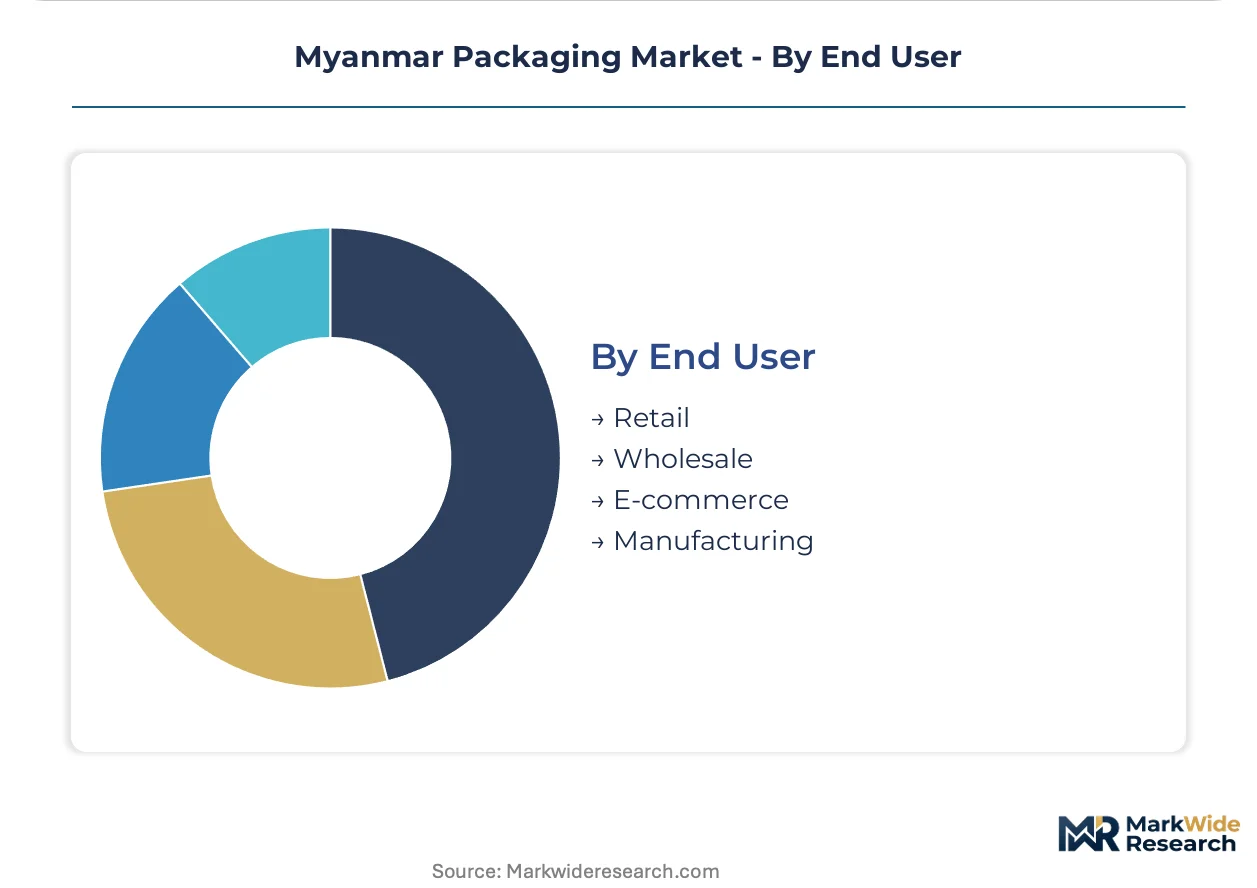
End User:
Channel concentration determines format complexity: retail and wholesale favor standardized SKUs while e-commerce demands protective customization.
- Retail:Supermarket and convenience store shelf-ready packaging drives folding carton and flexible pouch standardization. Point-of-sale display requirements influence secondary packaging specifications.
- Wholesale:Bulk distribution formats emphasize corrugated case stacking strength and palletization efficiency. Agricultural commodity exports dominate wholesale packaging procurement.
- E-commerce:Parcel volume growth in Yangon logistics networks accelerates demand for air-cell cushioning, void-fill, and tamper-evident closures. Last-mile delivery protection represents underdeveloped white space.
- Manufacturing:Industrial buyers specify intermediate packaging for in-process materials and component protection. Just-in-time delivery requirements influence reusable container adoption.
Retail leads volumes today; e-commerce shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangon's Thanlyin industrial zone concentrates Myanmar's packaging demand through its logistics access and utility infrastructure. The Ministry of Industry and Commerce's import licensing framework for pre-used plastic resin redirects converter investment toward domestic paperboard capacity and biopolymer alternatives. Industrial clusters in Mandalay and border states absorb spillover demand as regulatory pressure reshapes material flows.
Yangon Region
Instant-noodle manufacturers and edible-oil processors drive metallized laminate orders for seasoning sachets and barrier pouches. The Food and Drug Administration's contact-material safety rules stretch certification timelines to six or nine months for new format launches. Blown film extrusion lines in Thanlyin zone serve snack brands with oxygen-barrier coextrusion, though diesel generator backup elevates operating costs during electricity outages.
Mandalay Region
Northern state distribution routes pull rigid plastics capacity toward pharmaceutical blister packs and personal-care bottles. The Central Committee for Drug Abuse Control's serialization mandates shape barrier-film investments across domestic drug manufacturers. Mandalay's packaging cluster absorbs converter migration from resin-dependent formats toward containerboard integration with regional pulp networks.
Shan State
Agricultural commodity exports from the northeast drive corrugated case demand for tea and pulse shipments. Border trade regulations with China and Thailand influence secondary packaging specifications for cross-border logistics. The state's limited industrial base forces processors to source folding cartons and bulk containers from Mandalay or Yangon suppliers.
Rakhine State
Edible-oil processing near Sittwe generates flexible pouch demand for domestic distribution and export. Port infrastructure constraints limit containerboard import volumes, accelerating reliance on Oji Myanmar Packaging's regional pulp integration. Biopolymer pilot lines face extended commissioning timelines due to technical training gaps in coextrusion die setup.
Mon State
Seafood processing clusters near Mawlamyine require modified-atmosphere packaging for chilled export shipments. Utility reliability lags Thanlyin standards, constraining blown film extrusion uptime for high-barrier formats. The Ministry of Industry and Commerce's implicit preference for domestic alternatives creates procurement tailwind for local paperboard mills supplying kraft linerboard.
Myanmar Packaging Market Competitive Landscape
Global majors compete with regional champions across material integration and regulatory compliance capabilities. The vendor base stratifies between vertically integrated paperboard producers, flexible film specialists with metallized barrier capacity, and rigid plastics converters facing resin import dependency. Three archetypes dominate: containerboard-integrated pulp networks, blown film extrusion operators serving food brands, and pharmaceutical-focused barrier-film suppliers. Capacity expansion and backward integration into captive kraft linerboard supply represent the dominant competitive moves as import licensing tightens.
Within the containerboard-integrated tier, Oji Myanmar Packaging Co., Ltd. anchors regional pulp network coordination. Daibochi Packaging Myanmar occupies a position among flexible film specialists supplying metallized laminate structures. Double Packaging Myanmar Co. Limited exemplifies the rigid plastics archetype with distribution control into Yangon's Thanlyin zone. These three companies represent distinct strategic responses to the Ministry of Industry and Commerce's regulatory compression.
| Leading Market Players |
|---|
| Can-One Berhad |
| May Kha San Family Co Ltd |
| Daibochi Packaging Myanmar |
| Jackway Convertor Industries Pte Ltd |
| Tharaphusan Plastic |
| Oji Myanmar Packaging Co., Ltd. |
| Double Packaging Myanmar Co. Limited |
| Diamond Printing Myanmar |
| Ball Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FDA-contact-material-compliant formats and uncertified commodity grades splits Myanmar's packaging market into divergent cost structures. Premium-tier converters command spreads of thirty to fifty percent above commodity paperboard suppliers by embedding Ministry of Industry and Commerce documentation and six-month safety certification timelines into contract pricing.
Pricing Analysis
Input-cost pass-through from resin licensing delays and diesel generator backup expenses flows unevenly across converter tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification status, captive kraft linerboard supply, and metallized barrier capability. Cost compression in rigid plastics is intensifying because medical-grade polyethylene and polypropylene feedstock faces extended procurement cycles. Pharmaceutical blister pack buyers show least price sensitivity; instant-noodle sachet manufacturers absorb maximum pressure.
Supply Chain Analysis
Domestic-content preferences from Myanmar's Ministry of Industry and Commerce redirect sourcing from Thai and Vietnamese resin suppliers toward local paperboard mills and biopolymer pilot lines. Raw material flows draw from Indonesian pulp networks, Thai metallized film specialists, and domestic kraft linerboard producers. Single-source vulnerability concentrates in blown film extrusion equipment where Thai and Vietnamese technical supervisors dominate commissioning. Distribution runs through Yangon's Thanlyin industrial zone for southern state coverage and Mandalay's packaging cluster for northern routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in converters that substitute imported resin with captive paperboard capacity, capturing regulatory preference while input costs for competitors escalate.
For Market Incumbents: Deepen containerboard integration with regional pulp networks to offset resin import licensing friction. Secure Ministry of Industry and Commerce certification documentation ahead of competitor submissions. Add blown film extrusion capacity in Mandalay before land positions consolidate. For New Entrants and Emerging Players: Enter via e-commerce protective formats where air-cell cushioning and tamper-evident closure demand outpaces supply. Target Yangon logistics networks expanding parcel volumes. Lead with biopolymer pilot credentials to displace price-only tenders from established converters. For Investors and Strategic Acquirers: Consolidation pressure builds where resin-dependent rigid plastics converters face sustained feedstock volatility. Five-to-ten-year viability favors vertically integrated paperboard producers with Thanlyin zone utility access. Watch for Ministry of Industry and Commerce licensing framework expansion as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Linerboard | Captive supply of 200-350 gsm containerboard insulates against resin licensing restrictions. |
| Biopolymer Pilot Line Commissioning | PLA and starch-based film trials align with Ministry of Industry and Commerce domestic-content preference. |
| Metallized Barrier Capacity Addition | Vacuum metallizer installation serves Thanlyin zone instant-noodle manufacturers' oxygen-barrier specifications. |
| Mandalay Cluster Satellite Expansion | Northern state distribution route capture precedes competitor land consolidation. |
| FDA Contact-Material Certification Investment | Six-to-nine-month documentation timelines create switching costs for pharmaceutical buyers. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream food processors, secondary validation through Myanmar customs records and ASEAN packaging trade data, and technical specification review — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included blown film extrusion operators, corrugated case procurement managers at edible-oil processors, pharmaceutical packaging compliance officers, and logistics directors at e-commerce fulfillment networks.
Historical volume trajectories were cross-referenced against panel input from converter capacity planners to derive expansion rates across the analysis window. Segmentation dimensions modeled include product format, material grade tier, end-use application, and regional industrial zone concentration. Forecast inputs incorporated Ministry of Industry and Commerce licensing timeline assumptions and utility capacity expansion schedules for Thanlyin zone.
The model holds under stable regulatory enforcement and incremental utility infrastructure investment; deviation in import licensing severity or diesel cost spikes would shift converter migration timing. Forecasts reflect documented assumptions about resin substitution elasticity and paperboard mill utilization rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
GCC Disposables (Single-Use) Packaging Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Postal Packaging Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Printed Aluminium Foil Packaging Market