
 Conjunctivitis Drugs Market | 2026-2036
Conjunctivitis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Conjunctivitis Drugs Market Analysis
Market Context
Ophthalmic pharmacist training capacity is collapsing across community pharmacy chains, forcing manufacturers to deploy direct-to-clinic educational programs. Alcon leverages its vertically integrated eye-care platform to sustain formulary access across hospital networks. Pfizer competes through broad-spectrum antibiotic portfolios that anchor acute bacterial conjunctivitis protocols. Santen Pharmaceutical dominates in preservative-free delivery technologies that differentiate its portfolio in Japanese and European markets.
Technical Definition and Segment Structure
Conjunctivitis drugs comprise topical, oral, and injectable pharmaceutical agents formulated as solutions, suspensions, gels, or ointments to treat inflammation of the bulbar and palpebral conjunctiva, typically containing active pharmaceutical ingredients such as antihistamines, antibiotics, corticosteroids, or lubricating polymers at specified osmolarity and pH ranges compatible with ocular surface physiology. Antibiotics occupy the largest revenue pool due to high acute infection incidence, while artificial tears represent the fastest-expanding category as dry eye disease overlap broadens the addressable patient base. Topical delivery mode leads volume shipments, though ocular inserts are gaining share among glaucoma-cojunctivitis comorbidity patients seeking reduced dosing frequency.
Regulatory Framework and Outlook
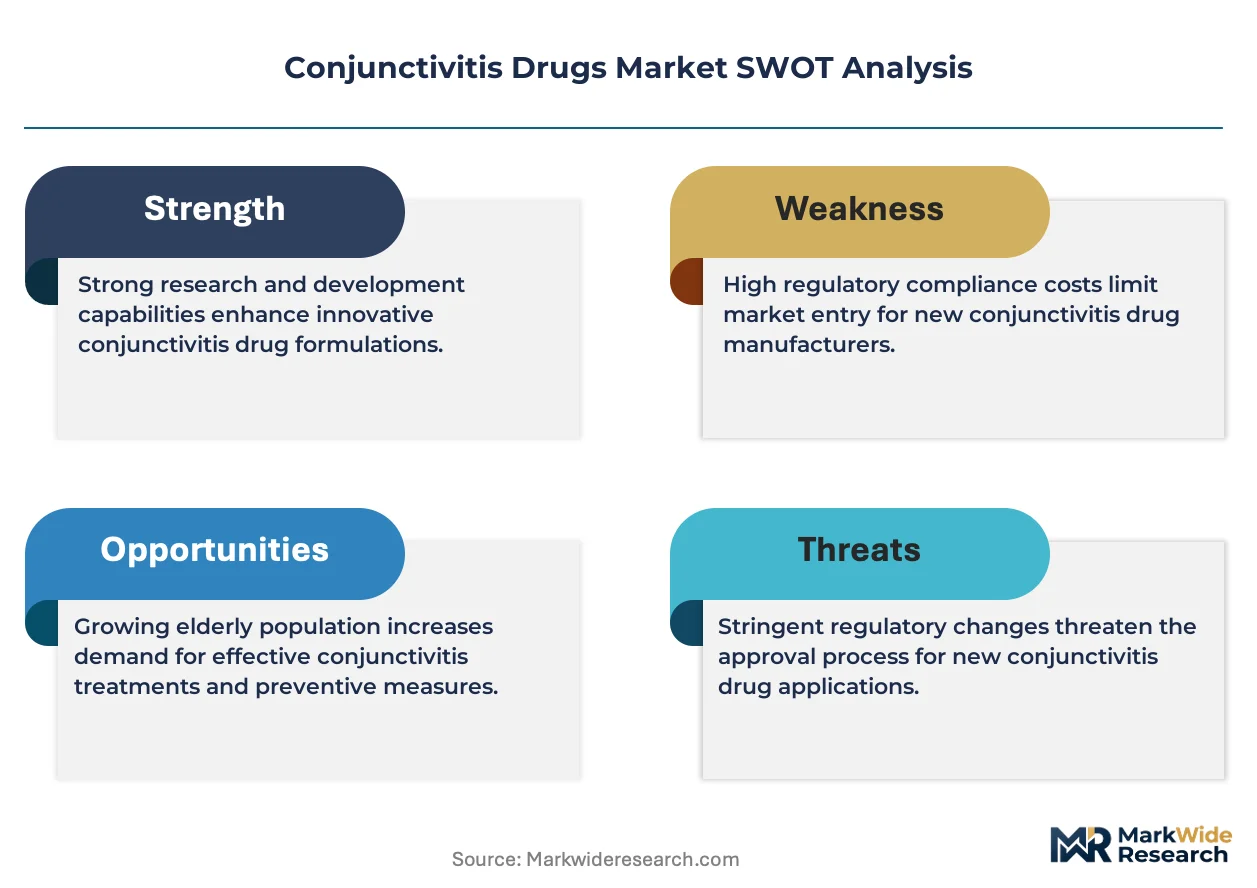
FDA ophthalmic drug manufacturing guidance, EMA's MDR requirements for ocular devices, and WHO prequalification standards for essential antibiotic eye medicines collectively elevate barrier-to-entry and shape regional product registration strategies. These frameworks compel sponsors to invest in extractables-leachables testing and sterility assurance validation that extend development timelines. Stakeholders must monitor how pharmacovigilance signal detection for preservative toxicity reshapes formulation preferences and reimbursement positioning.
Market Dynamics
Preservative-free formulation technology is compressing margins for legacy multi-dose manufacturers while simultaneously opening premium pricing tiers for compliant entrants across hospital and specialty clinic channels.
Growth Catalysts
- EMA MDR compliance deadlines:Device-drug combination products face reclassification pressure that accelerates investment in validated sterile manufacturing infrastructure across European contract development organizations.
- Pediatric ophthalmology formulary expansion:Academic medical centers in the United States are mandating benzalkonium chloride-free alternatives for all pediatric prescriptions, creating institutional procurement pull-through.
- Dry eye disease convergence:Artificial tears are capturing prescriptions from chronic allergic conjunctivitis patients as diagnostic overlap protocols expand in optometry practices.
Market Restraints
- API supply concentration:Fluoroquinolone active pharmaceutical ingredients concentrate in Chinese and Indian bulk chemical manufacturers, exposing formulators to tariff volatility and import inspection delays.
- Extractables-leachables testing costs:Novel polymer primary packaging requires 18-24 month validation timelines that extend development cycles for preservative-free multidose systems.
- Generic antibiotic substitution:Acute bacterial conjunctivitis protocols default to low-cost generic tobramycin and moxifloxacin, compressing branded portfolio economics.
Strategic Opportunities
- Home infusion channel expansion:Severe viral conjunctivitis patients with immunocompromise are receiving intravitreal antiviral administration through home health nursing networks in Germany and France.
- Japanese preservative-free innovation:PMDA's streamlined approval pathway for ocular surface devices enables faster market entry for hydrogel-based drug delivery platforms.
- Ocular insert co-development:Sustained-release corticosteroid inserts for glaucoma-conjunctivitis comorbidity patients reduce dosing frequency and improve adherence metrics in managed care contracts.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic processing technicians and ophthalmic quality assurance specialists command 40% wage premiums over standard pharmaceutical operations, constraining capacity expansion.
- Legacy ERP integration friction:Track-and-trace serialization requirements for FDA DSCSA compliance force mid-tier manufacturers to replace validated batch record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conjunctivitis Drugs Market |
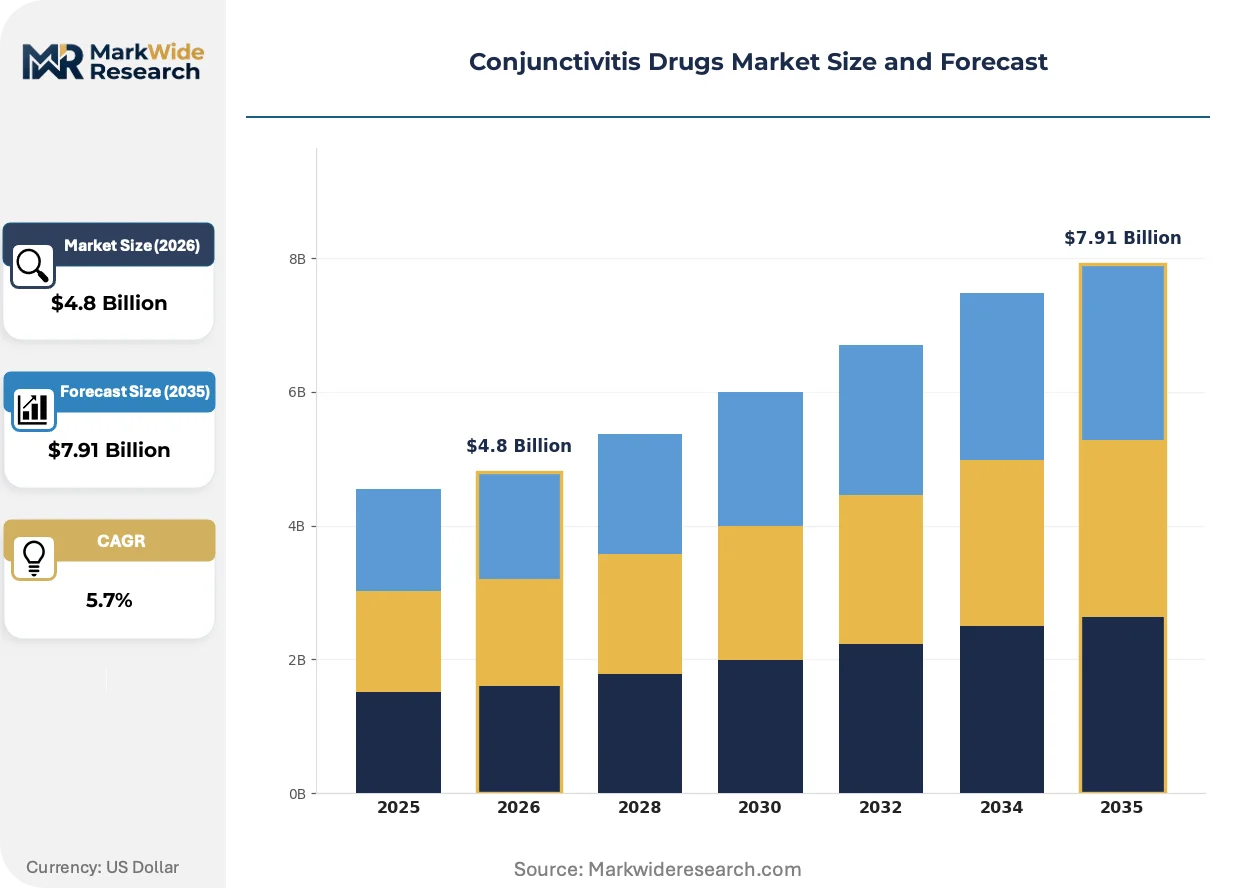
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Antibiotics, Corticosteroids, Artificial Tears Delivery Mode: Topical, Oral, Injectable, Ocular Inserts End User: Hospitals, Clinics, Home Healthcare, Pharmacies Formulation: Solutions, Suspensions, Gels, Ointments |
| Companies Covered | Allergan, Alcon, Novartis AG, Santen Pharmaceutical Co., Ltd, Bausch Health Companies Inc., Pfizer Inc., AbbVie Inc., Eyevance Pharmaceuticals LLC, Nicox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conjunctivitis Drugs Market Emerging Trajectories
Formulation chemistry and delivery mechanism evolution are fragmenting the traditional solution-suspension-ointment taxonomy as manufacturers engineer hybrid platforms that merge immediate relief with sustained therapeutic action.
Unit-dose preservative-free vials are displacing multi-dose bottles in managed care formularies as pharmacy benefit managers impose tiered copay structures favoring single-use presentations. Hospital outpatient departments are accelerating adoption despite higher per-unit acquisition costs. The shift is compressing economies of scale for legacy blow-fill-seal infrastructure while rewarding flexible aseptic filling investments.
REACH restrictions on boric acid and borates in consumer products are forcing European formulators to reformulate buffer systems for ophthalmic solutions. The industrial consequence is a 12-18 month reformulation cycle for established products. Polyvinyl alcohol and hyaluronic acid-based artificial tears are most affected, with manufacturers substituting tromethamine and citrate buffer systems.
Specialty pharmacy distribution is capturing conjunctivitis drug volume from traditional retail channels as biologic and corticosteroid-sparing therapies require cold chain handling and patient adherence monitoring. Hub service providers are replacing community pharmacy counseling for complex regimens. The United States exhibits the most pronounced channel migration, with Medicare Part D plans directing patients to limited distribution networks.
Conjunctivitis Drugs Market Segmentation
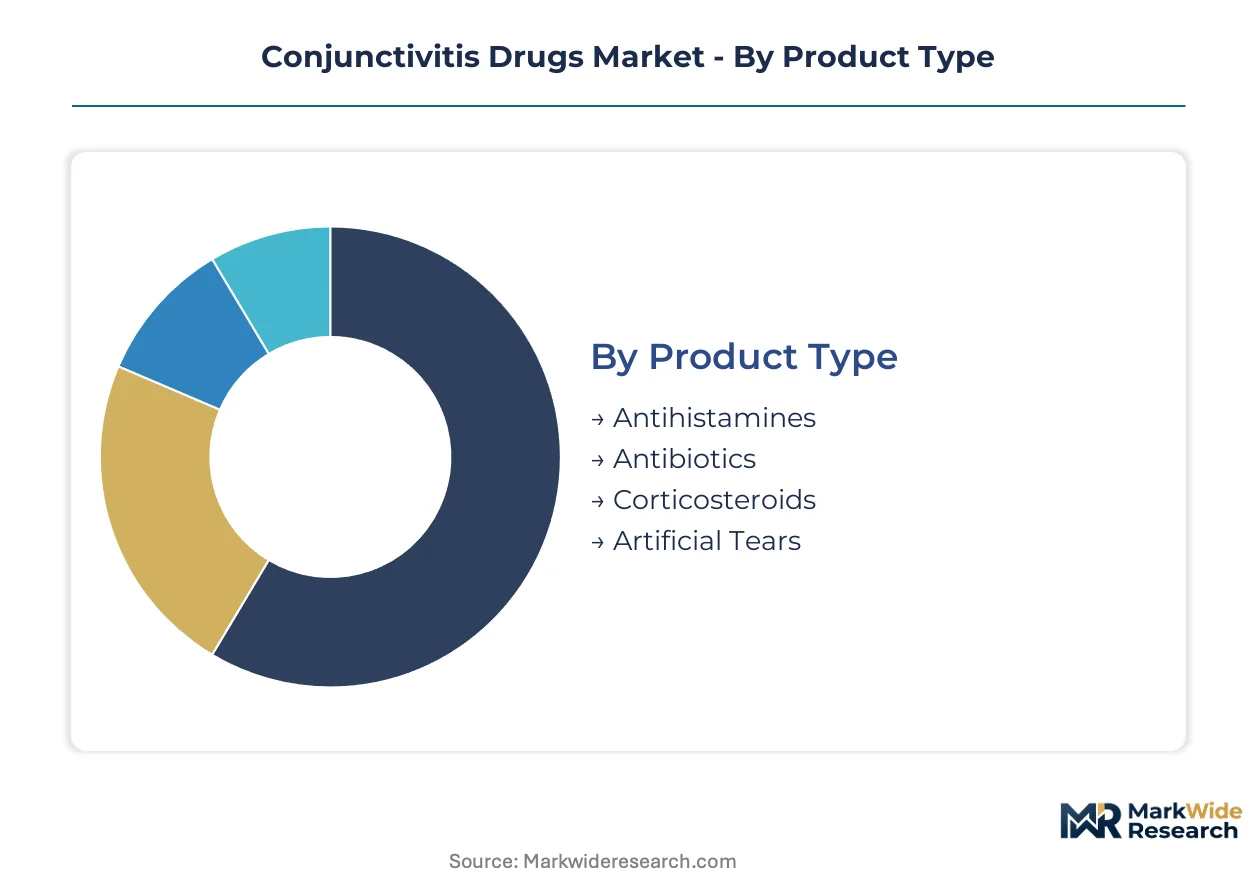
Segmentation in the conjunctivitis drugs market reveals divergent margin structures across therapeutic categories and delivery technologies. Formulation chemistry and sterility requirements create distinct competitive arenas that reward specialized manufacturing capabilities over commodity production.
Product Type:
Margin pools concentrate in preservative-free artificial tears and corticosteroid-sparing therapies where formulation complexity commands premium positioning.
- Antihistamines:Dual-action H1-receptor antagonists with mast-cell stabilizing properties dominate seasonal allergic conjunctivitis protocols. Demand clusters in United States managed care formularies where step-therapy requirements favor generic ketotifen before branded olopatadine escalation.
- Antibiotics:Fluoroquinolone and macrolide formulations anchor acute bacterial infection treatment, though generic tobramycin and moxifloxacin substitution compresses branded economics. Procurement concentrates in hospital emergency departments and urgent care networks facing antimicrobial stewardship pressures.
- Corticosteroids:Loteprednol etabonate and difluprednate formulations serve severe inflammatory presentations requiring rapid resolution. Japanese and European markets show strongest uptake for preservative-free presentations in academic medical centers.
- Artificial Tears:Hyaluronic acid and carboxymethylcellulose polymers with osmoprotectant additives address dry eye-conjunctivitis overlap. Pediatric ophthalmology clinics in Germany and France are mandating benzalkonium chloride-free alternatives, creating institutional procurement pull-through.
The dominant share belongs to antibiotics, while artificial tears is closing the gap fastest.
Delivery Mode:
Volume distribution reflects patient adherence economics and dosing frequency requirements across acute versus chronic treatment paradigms.
- Topical:Eye drops and gels deliver 90% of prescribed therapy through corneal and conjunctival absorption. United States retail pharmacy chains and specialty distributors handle the bulk of volume, with preservative-free unit-dose vials displacing multi-dose bottles in Medicare Part D formularies.
- Oral:Systemic antihistamines and antibiotics address refractory or bilateral infections where topical penetration is insufficient. Demand concentrates in primary care networks managing patients with concurrent sinus or respiratory infections.
- Injectable:Intravitreal antiviral administration serves immunocompromised patients with severe viral conjunctivitis. Home health nursing networks in Germany and France are expanding this channel for cytomegalovirus and herpetic presentations.
- Ocular Inserts:Sustained-release corticosteroid and cyclosporine devices reduce dosing frequency for glaucoma-conjunctivitis comorbidity patients. PMDA's streamlined approval pathway in Japan accelerates hydrogel-based platform entry.
Topical formulations retain volume leadership, though ocular inserts show the steepest expansion trajectory among device-drug combinations.
End User:
Channel economics fragment across institutional procurement, retail dispensing, and emerging home administration models with distinct cold chain and counseling requirements.
- Hospitals:Inpatient and emergency department formulary committees prioritize broad-spectrum antibiotic coverage and rapid therapeutic response. EMA MDR compliance deadlines for device-drug combinations are accelerating sterile manufacturing infrastructure investment across European contract development organizations.
- Clinics:Ophthalmology and optometry practices drive prescription volume for chronic and allergic presentations. Academic medical centers in the United States are mandating preservative-free alternatives for pediatric populations, reshaping procurement specifications.
- Home Healthcare:Infusion nursing networks administer complex antiviral regimens for immunocompromised patients. Germany and France lead channel development through reimbursement structures supporting domiciliary specialist care.
- Pharmacies:Community and specialty pharmacy channels face divergent futures as hub services capture biologic and corticosteroid-sparing therapy distribution. United States Medicare Part D plans increasingly direct patients to limited distribution networks requiring cold chain handling and adherence monitoring.
Hospitals command the largest prescription volume, while home healthcare is expanding most quickly as reimbursement models shift toward site-neutral payment.
Formulation:
Physical state determines manufacturing complexity, sterility validation requirements, and patient acceptance across different conjunctival pathologies.
- Solutions:Isotonic aqueous formulations with specified pH and osmolarity ranges provide immediate comfort and rapid drug release. REACH restrictions on boric acid and borates in Europe are forcing 12-18 month reformulation cycles for established polyvinyl alcohol and hyaluronic acid artificial tears.
- Suspensions:Micronized drug particles in viscous vehicles improve residence time for poorly soluble corticosteroids. Shake-before-use requirements reduce patient compliance in pediatric and geriatric populations.
- Gels:Thickened polymer matrices extend ocular surface contact duration for nighttime lubrication and severe dry eye. Preservative-free gel formulations command premium positioning in Japanese and European markets.
- Ointments:Petrolatum and mineral oil bases provide prolonged lubrication and drug release for nocturnal application. Vision-blurring properties limit daytime use to severe keratoconjunctivitis presentations.
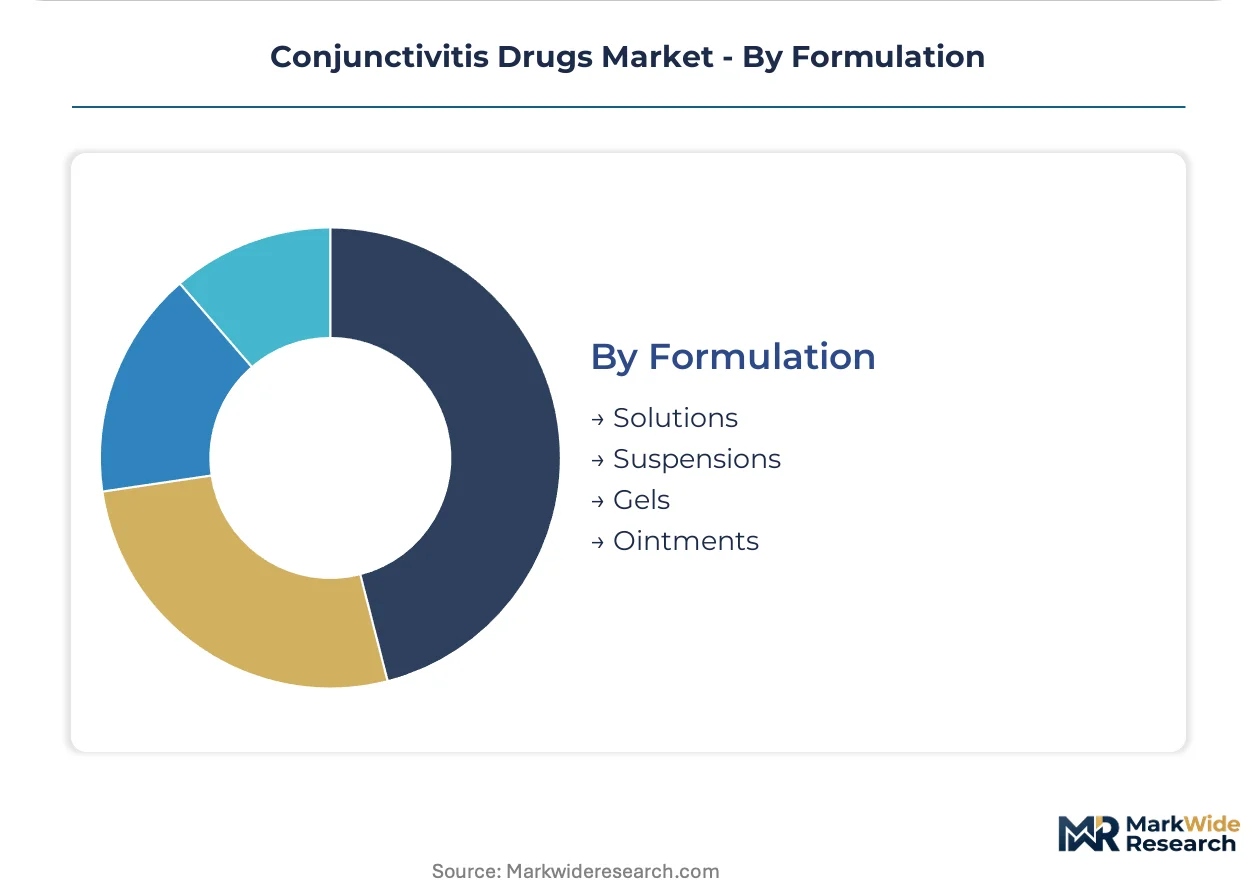
Solutions dominate current prescription volume, though gels are gaining share fastest as preservative-free positioning expands beyond unit-dose presentations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States prioritizing corticosteroid-sparing branded therapies in managed care formularies while Japan and Germany lead adoption of preservative-free delivery technologies.
United States
Managed care formularies increasingly favor branded corticosteroid-sparing therapies over generic antibiotics, driving premium positioning for differentiated products. FDA tightened guidance on topical ophthalmic drug manufacturing is reshaping quality standards and extending validation timelines. Pediatric ophthalmology clinics in academic medical centers are mandating benzalkonium chloride-free alternatives, creating institutional procurement pull-through.
Germany
Home health nursing networks are expanding intravitreal antiviral administration for immunocompromised patients with severe viral conjunctivitis. EMA MDR compliance deadlines for device-drug combination products are accelerating sterile manufacturing infrastructure investment across contract development organizations. Frankfurt and Munich clusters concentrate formulation chemistry expertise for preservative-free multidose systems.
Japan
PMDA's streamlined approval pathway for ocular surface devices enables faster market entry for hydrogel-based drug delivery platforms. Domestic demand concentrates in preservative-free artificial tears as dry eye disease diagnostic overlap expands in optometry practices. Osaka and Tokyo pharmaceutical corridors anchor sustained-release corticosteroid insert development for glaucoma-conjunctivitis comorbidity patients.
France
Specialty pharmacy distribution is capturing conjunctivitis drug volume from traditional retail channels as biologic therapies require cold chain handling. ANSM pharmacovigilance signal detection for preservative toxicity is reshaping formulation preferences and reimbursement positioning. Lyon and Paris hospital networks are piloting hub service providers to replace community pharmacy counseling for complex regimens.
India
Fluoroquinolone active pharmaceutical ingredient supply concentrates in bulk chemical manufacturers, exposing formulators to tariff volatility and import inspection delays. CDSCO quality standards for essential antibiotic eye medicines elevate barrier-to-entry for domestic manufacturers. Mumbai and Hyderabad API clusters face workforce scarcity as aseptic processing technicians command wage premiums over standard pharmaceutical operations.
Conjunctivitis Drugs Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical integration into sterile manufacturing infrastructure separating premium positioning from commodity substitution pressure. The market structure rewards formulation complexity and preservative-free delivery technology over broad-spectrum portfolio breadth. Three archetypes dominate: integrated eye-care platforms sustaining formulary access across hospital networks, broad-spectrum antibiotic anchors for acute bacterial protocols, and preservative-free delivery specialists differentiating in pediatric and European markets. Competitive moves concentrate on M&A for sterile manufacturing capacity and strategic partnerships for ocular insert co-development.
Within the integrated platform tier, Alcon exemplifies vertical control over eye-care distribution channels, while Pfizer occupies the broad-spectrum antibiotic anchor position. Santen Pharmaceutical represents the preservative-free delivery specialist archetype, with its geographic concentration in Japanese and European markets reflecting regional regulatory preferences for benzalkonium chloride-free alternatives.
| Leading Market Players |
|---|
| Allergan |
| Alcon |
| Novartis AG |
| Santen Pharmaceutical Co., Ltd |
| Bausch Health Companies Inc. |
| Pfizer Inc. |
| AbbVie Inc. |
| Eyevance Pharmaceuticals LLC |
| Nicox |
| Others |
Supply Flow & Price Mechanics
Aseptic filling capacity utilization rates above 85% in Indian and Chinese contract manufacturing organizations compress unit economics for preservative-free formulations while elevating price floors for compliant entrants. This scale concentration simultaneously shapes procurement leverage for hospital networks and formulary positioning for branded corticosteroid-sparing therapies.
Pricing Analysis
Long-term offtake contracts anchor procurement for fluoroquinolone APIs, while spot purchasing dominates excipient and packaging materials. Three-tier pricing structure across premium preservative-free, standard multi-dose, and economy generic antibiotics reflects FDA compliance tier and volume scale. Cost compression in the generic antibiotic tier intensifies because of Indian API import inspection delays. Hospital procurement committees exhibit lowest price sensitivity for pediatric benzalkonium chloride-free alternatives, while retail pharmacy chains remain most cost-conscious.
Supply Chain Analysis
Strategic stockpiling of polymer primary packaging materials offsets 18-24 month extractables-leachables validation timelines, contrasting with just-in-time API sourcing from Indian and Chinese bulk chemical manufacturers. Fluoroquinolone active ingredients concentrate in Hyderabad, Mumbai, and Zhejiang province facilities. Formulation chemistry expertise rests on German and Japanese specialty chemical suppliers for hyaluronic acid derivatives. Single-source vulnerability in boric acid buffer systems following REACH restrictions threatens European manufacturing continuity. Distribution runs through hospital outpatient departments, specialty pharmacy hubs, and home health nursing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified aseptic processing technicians and ophthalmic quality assurance specialists command 40% wage premiums, constraining capacity expansion and consolidating advantage among manufacturers with captive sterile infrastructure.
For Market Incumbents: Secure backward integration into preservative-free multidose system manufacturing to defend against generic antibiotic substitution and EMA MDR compliance cost escalation. Expand sterile filling capacity in Frankfurt or Munich clusters to capture European academic medical center procurement pull-through for pediatric formulations. For New Entrants and Emerging Players: Anchor in Japanese hydrogel-based ocular insert development through PMDA's streamlined approval pathway, targeting glaucoma-conjunctivitis comorbidity patients seeking reduced dosing frequency. Pursue co-development partnerships with established sterile manufacturers rather than greenfield capacity investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors preservative-free delivery platform specialists with validated sterile infrastructure over broad-spectrum antibiotic portfolio holders. Long-term viability hinges on formulation chemistry capabilities and regulatory submission track records. Monitor pharmacovigilance signal detection for preservative toxicity as inflection indicator for accelerated category shift.| Strategic Initiative | Industry Significance |
|---|---|
| Sterile Manufacturing Capacity Expansion | Captures hospital formulary access as EMA MDR deadlines accelerate compliance investment. |
| Preservative-Free Formulation Development | Commands premium positioning in United States pediatric ophthalmology procurement specifications. |
| Ocular Insert Co-Development Partnership | Reduces dosing frequency for glaucoma-conjunctivitis comorbidity patients in managed care contracts. |
| API Supply Agreement Restructuring | Mitigates tariff volatility exposure from concentrated Indian and Chinese bulk chemical sourcing. |
| Specialty Pharmacy Distribution Integration | Secures cold chain handling and adherence monitoring for biologic and corticosteroid-sparing therapies. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to converge on segment-level estimates.
Across the projection horizon, the analytical framework modeled treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves anchored to reported prescription trends and capacity expansion announcements. Forecast inputs incorporated sterile manufacturing workforce availability and pediatric formulary mandate adoption rates.
Underlying assumptions cover stable API import inspection protocols and REACH buffer system substitution timelines, with deviation risk concentrated in tariff regime shifts and pharmacovigilance signal escalations. Revision becomes warranted when preservative toxicity evidence crosses regulatory action thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Lipid-Lowering Drugs Market