
 Vascular Endothelial Growth Factor (VEGF) Antibodies Market | 2026-2036
Vascular Endothelial Growth Factor (VEGF) Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Endothelial Growth Factor (VEGF) Antibodies Market Analytics
Oncology clinics are redrawing procurement priorities for VEGF inhibitors as combination regimens displace monotherapy in first-line settings. Regeneron Pharmaceuticals leverages its Eylea franchise to anchor ophthalmology revenue streams alongside oncology pipeline assets. F. Hoffmann-La Roche Ltd sustains dominance through Avastin's entrenched position in colorectal and lung cancer protocols across major markets. Novartis competes through Beovu and broader retinal portfolio expansion, while Bayer AG differentiates via niche positioning in hepatocellular carcinoma combinations.
Vascular endothelial growth factor antibodies are recombinant protein therapeutics that bind VEGF-A ligands with picomolar affinity, blocking receptor activation on endothelial cells to inhibit pathological angiogenesis in tumors and neovascular retinal disease. These agents are manufactured through mammalian cell culture in Chinese hamster ovary lines, requiring glycosylation pattern control to preserve effector function and circulating half-life. Monoclonal antibodies occupy the largest value share due to entrenched originator brands, though biosimilars are capturing fastest volume growth as patent cliffs erode pricing power for reference products. Oncology applications lead absolute spending, yet ophthalmology generates higher per-patient margins with more frequent dosing intervals in age-related macular degeneration.
The FDA governs VEGF antibody approvals through its Center for Drug Evaluation and Research, with biosimilar interchangeability determinations now shaping payer substitution policies. EMA's biosimilar guidelines under the Committee for Medicinal Products for Human Use establish comparability standards that influence development investments across European markets. The EU AI Act and evolving FDA guidance on real-world evidence are accelerating post-market surveillance requirements for novel VEGF-targeted combinations. Stakeholders must monitor CMS reimbursement recalibrations and EMA biosimilar interchangeability rulings to anticipate volume shifts between originator and follow-on products.
Market Dynamics
Biosimilar interchangeability rulings by the FDA and EMA are compressing originator pricing power while expanding patient access to VEGF-targeted therapies across oncology and ophthalmology protocols.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's biosimilar interchangeability determinations under the Biologics Price Competition and Innovation Act enable automatic pharmacy-level substitution, expanding volume access for follow-on bevacizumab and ranibizumab products.
- Oncology Protocol Expansion:Academic medical centers in the United States are integrating VEGF antibodies into first-line combination regimens for metastatic colorectal and non-small cell lung cancer, displacing monotherapy standards.
- Intravitreal Administration:Retinal specialists are extending treatment intervals through high-dose aflibercept formulations, reducing injection burden while maintaining visual acuity gains in neovascular age-related macular degeneration.
Market Restraints
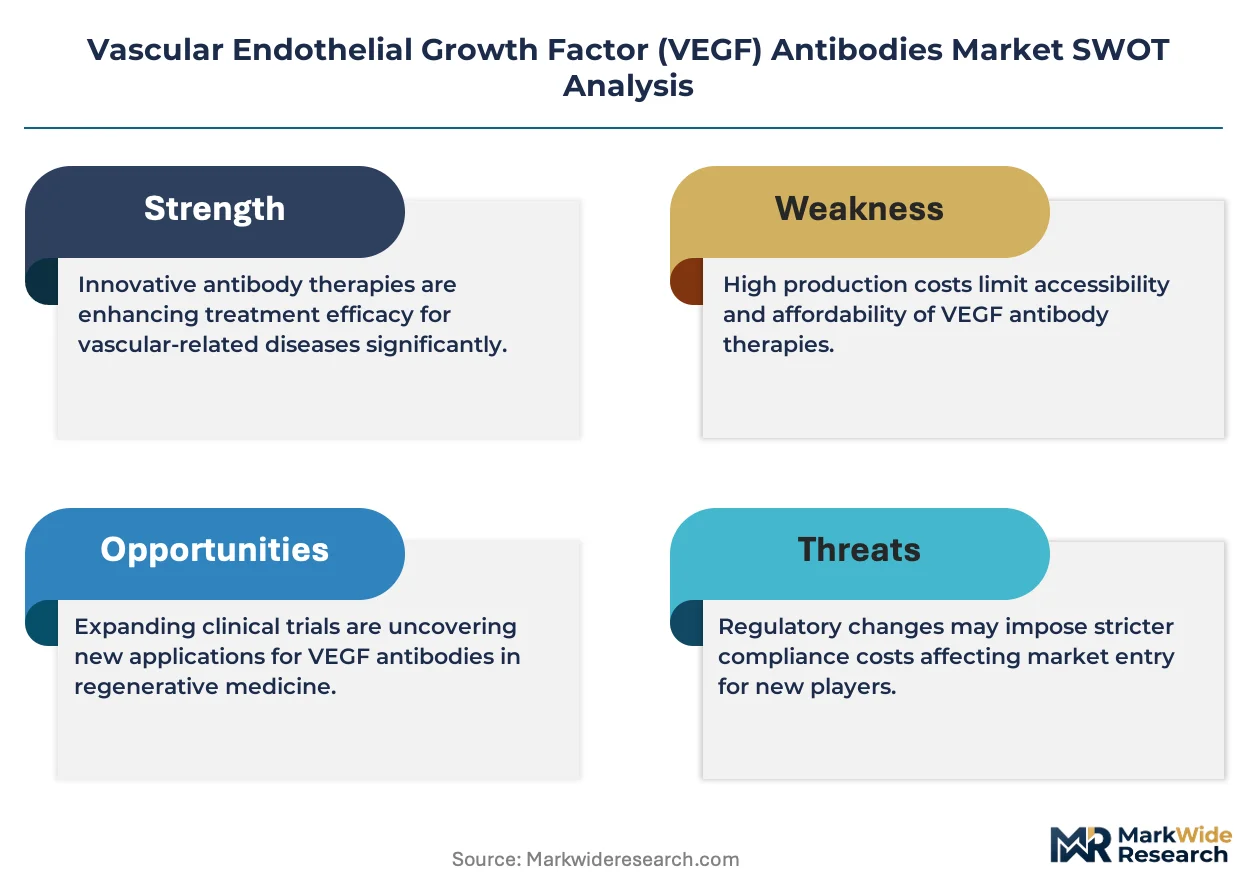
- Mammalian Cell Culture Constraints:Chinese hamster ovary line capacity limitations and glycosylation pattern control requirements create manufacturing bottlenecks that constrain rapid biosimilar scale-up.
- Reimbursement Compression:CMS Medicare Part B reimbursement recalibrations for intravenous oncology formulations and intravitreal ophthalmology injections are narrowing per-dose margins for hospital outpatient departments.
- Reference Product Loyalty:Entrenched Avastin and Eylea prescribing patterns among US-based oncologists and retinal specialists slow biosimilar uptake despite interchangeability designations.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered VEGF antibody delivery systems for oncology indications could shift administration from infusion centers to home settings, capturing patient convenience premiums.
- Real-World Evidence Integration:The FDA's expanding guidance on RWE for supplemental indications enables post-approval label expansion based on electronic health record data from integrated delivery networks.
- Combination Pipeline Positioning:VEGF-immune checkpoint inhibitor pairings in hepatocellular carcinoma and renal cell carcinoma represent unmet need segments where novel mechanisms can establish differentiated protocols.
Industry Challenges
- Immunogenicity Surveillance:Anti-drug antibody monitoring requirements for biosimilars demand extended pharmacovigilance infrastructure that stretches mid-cap developer resources.
- Cold Chain Integrity:Temperature-controlled distribution for protein therapeutics faces last-mile vulnerabilities in emerging markets where infrastructure gaps compromise product stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Endothelial Growth Factor (VEGF) Antibodies Market |
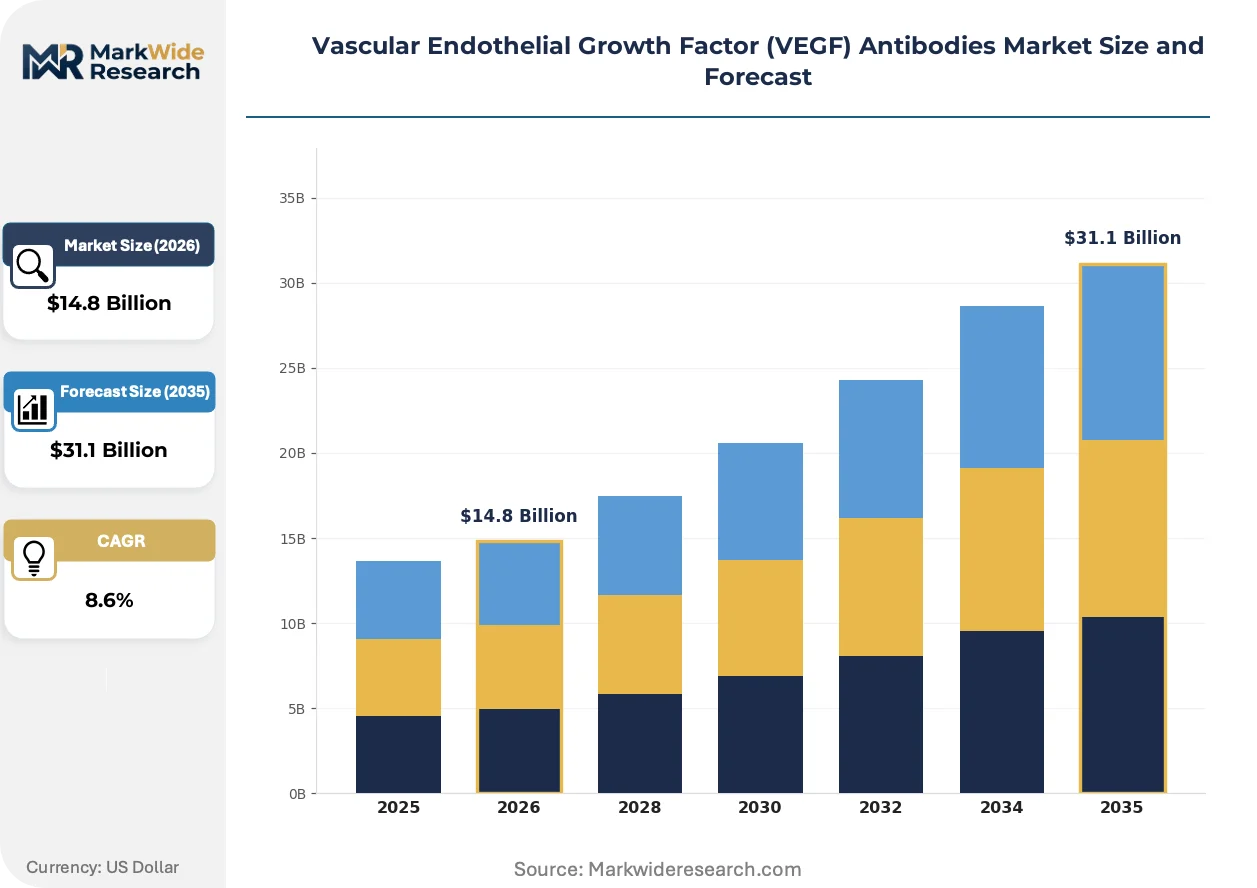
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Biosimilars, Conjugated Antibodies, Polyvalent Antibodies Application: Ophthalmology, Oncology, Dermatology, Cardiology End User: Hospitals, Research Institutions, Clinical Laboratories, Pharmaceutical Companies Distribution Channel: Online Pharmacies, Direct Sales, Retail Pharmacies, Wholesalers |
| Companies Covered | Regeneron Pharmaceuticals, F. Hoffmann-La Roche Ltd, Novartis AG, Bayer AG, Pfizer, Amgen, Biogen, Coherus BioSciences, Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Endothelial Growth Factor (VEGF) Antibodies Market Evolving Landscape
Biologic manufacturing and regulatory science are converging to reshape how VEGF-targeted therapies reach patients, with three distinct vectors altering competitive positioning.
High-concentration aflibercept formulations are displacing standard-dose regimens in retinal practice. These 8 mg presentations extend dosing intervals to 12-16 weeks in neovascular age-related macular degeneration. US-based retina specialists are adopting these protocols rapidly, compressing injection volume while maintaining visual outcomes and reducing clinic capacity constraints.
The EU AI Act's risk classification framework for medical device software is reshaping post-market surveillance obligations for VEGF antibody combination products. Algorithm-enabled dosing calculators and treatment response predictors now face conformity assessment requirements that extend development timelines. European ophthalmology clinics are restructuring data governance to accommodate automated decision-support tools under these new accountability standards.
Hospital purchasing coalitions are consolidating oncology drug procurement through single-source contracts with rebate guarantees. These arrangements displace traditional wholesaler relationships in the United States, concentrating volume with formulary-preferred biosimilars. Integrated delivery networks in Texas and Florida are pioneering these structures, extracting price concessions in exchange for committed volume thresholds across infusion center networks.
Vascular Endothelial Growth Factor (VEGF) Antibodies Market Segmentation
VEGF antibody procurement patterns diverge sharply across product categories and clinical settings. Substitution pressures from biosimilars, reimbursement tiering, and administration site economics reshape how manufacturers prioritize development investments and commercial infrastructure.
Product Type:
Biosimilar interchangeability rulings by FDA and EMA expose monoclonal antibodies to the most intense substitution pressure, while conjugated and polyvalent formats retain defensive moats through manufacturing complexity.
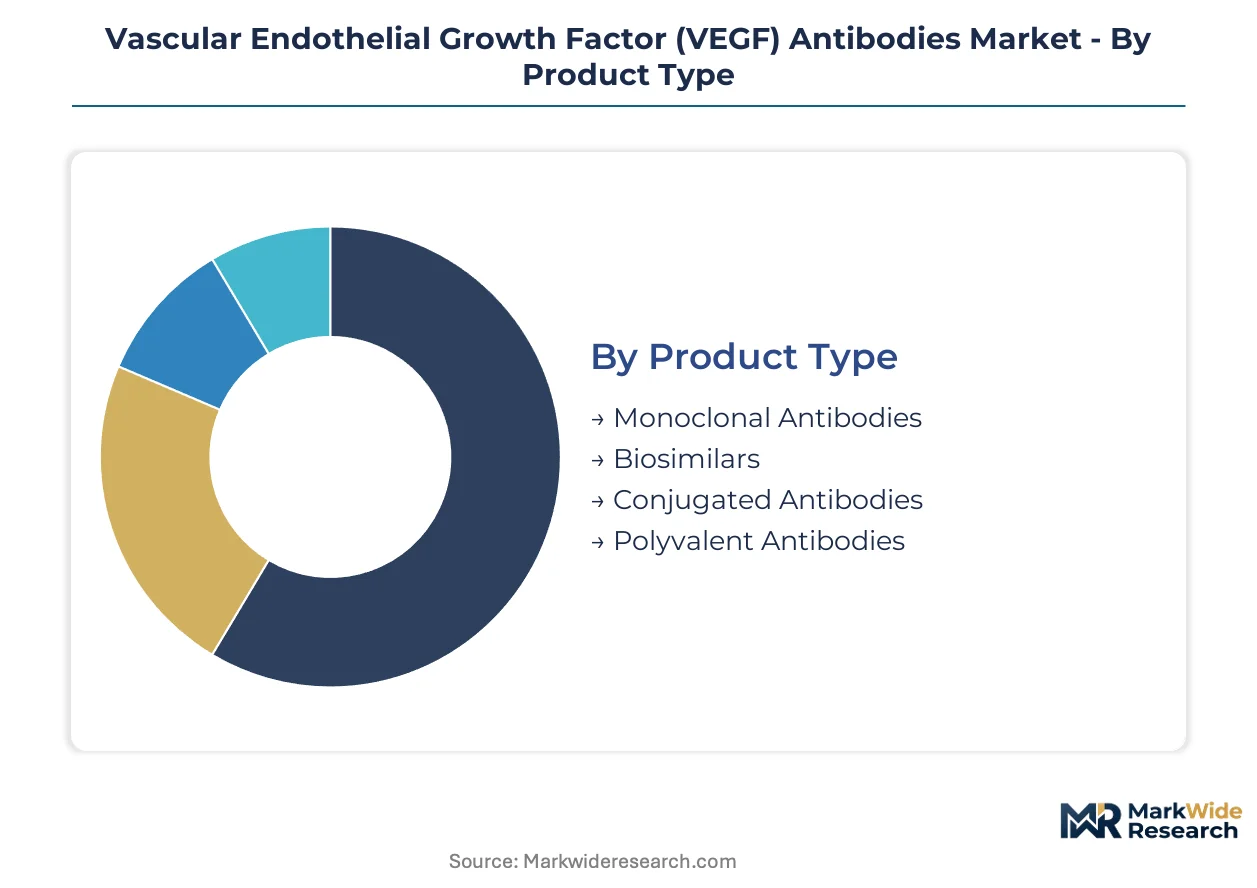
- Monoclonal Antibodies:Recombinant IgG1 constructs produced in Chinese hamster ovary lines with controlled glycosylation patterns. US oncology infusion centers concentrate demand as first-line colorectal and lung cancer protocols displace older standards. Medicare Part B reimbursement compression narrows per-dose margins for hospital outpatient departments.
- Biosimilars:Follow-on biologics demonstrating analytical and clinical comparability to reference products under FDA's Biologics Price Competition and Innovation Act pathway. German hospital purchasing coalitions and US integrated delivery networks drive volume concentration through single-source contracts with rebate guarantees. Automatic pharmacy-level substitution accelerates uptake despite physician loyalty to originator brands.
- Conjugated Antibodies:Antibody-drug conjugates linking VEGF-binding domains to cytotoxic payloads via cleavable linkers.
- Polyvalent Antibodies:Multi-specific constructs targeting VEGF-A alongside angiopoietin or PDGF ligands simultaneously.
Monoclonal antibodies retain volume leadership; biosimilars hold the steepest expansion curve.
Application:
Margin structures invert across clinical domains, with ophthalmology commanding premium per-injection pricing despite smaller patient populations versus oncology's volume-driven economics.
- Ophthalmology:Intravitreal administration for neovascular age-related macular degeneration and diabetic macular edema. Retinal specialists in US metropolitan markets extend treatment intervals through high-dose aflibercept formulations, reducing clinic capacity constraints while preserving visual acuity outcomes. Commercial payers and Medicare Advantage plans impose step-therapy requirements that favor formulary-preferred agents.
- Oncology:Intravenous infusion for metastatic colorectal, non-small cell lung, renal cell, and hepatocellular carcinomas. Academic medical centers in Texas and Florida integrate VEGF antibodies into first-line combination regimens with immune checkpoint inhibitors, displacing monotherapy standards. CMS reimbursement recalibrations compress per-dose margins for hospital outpatient departments.
- Dermatology:Off-label and emerging protocols for psoriasis and wound healing applications.
- Cardiology:Investigational applications in peripheral artery disease and coronary ischemia.
Oncology commands absolute spending; ophthalmology generates the highest per-patient margins.
End User:
Site-of-care economics determine procurement leverage, with hospital systems extracting volume-based concessions unavailable to fragmented research or laboratory customers.
- Hospitals:Integrated delivery networks and academic medical centers administering intravenous oncology infusions and intravitreal injections. US-based hospital purchasing coalitions consolidate procurement through single-source contracts, concentrating volume with formulary-preferred biosimilars. Infusion center capacity constraints and 340B drug pricing program participation reshape inventory management priorities.
- Research Institutions:Preclinical and clinical investigators evaluating novel VEGF-targeted combinations. Extended pharmacovigilance infrastructure demands strain mid-cap developer resources for immunogenicity surveillance.
- Clinical Laboratories:Companion diagnostic testing for VEGF expression and treatment response prediction.
- Pharmaceutical Companies:In-licensing and co-development partners seeking pipeline assets.
Hospitals retain volume leadership; research institutions hold the steepest expansion curve.
Distribution Channel:
Cold chain integrity requirements and temperature-controlled logistics favor direct manufacturer relationships over fragmented retail or wholesale intermediaries.
- Direct Sales:Manufacturer-controlled distribution to hospital systems and specialty pharmacies. Temperature-controlled logistics face last-mile vulnerabilities in emerging markets where infrastructure gaps compromise protein therapeutic stability. US integrated delivery networks in Texas and Florida pioneer committed volume thresholds across infusion center networks.
- Wholesalers:Traditional three-tier distribution for retail and independent pharmacy channels. Consolidating oncology drug procurement through single-source contracts with rebate guarantees displaces wholesaler relationships in US hospital purchasing coalitions.
- Online Pharmacies:Emerging specialty pharmacy platforms for patient home delivery.
- Retail Pharmacies:Limited role due to cold chain and administration complexity requirements.
Direct sales retain volume leadership; online pharmacies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply VEGF antibody formulations to hospital systems across Central and Eastern Europe. Swiss contract manufacturers ship active pharmaceutical ingredients to fill-finish facilities in the United States and Japan. Singapore serves as the regional distribution hub for temperature-controlled biologics moving into Southeast Asian markets.
United States
Medicare Part B reimbursement policies heavily influence prescribing patterns for intravitreal and intravenous VEGF antibody formulations. The FDA's accelerated approval pathways for biosimilars compress development timelines for follow-on bevacizumab products. Texas and Florida integrated delivery networks pioneer single-source procurement contracts with rebate guarantees across infusion center networks.
Germany
Hospital purchasing coalitions drive volume concentration through committed contracts with formulary-preferred biosimilars. EMA biosimilar interchangeability rulings under the Committee for Medicinal Products for Human Use establish comparability standards across European markets. The Rhine-Main biotech cluster hosts fill-finish operations supplying oncology and ophthalmology protocols to Benelux and Scandinavian markets.
Japan
PMDA review timelines for biosimilar applications shape developer entry sequencing for ranibizumab follow-ons. METI industrial policy supports domestic mammalian cell culture capacity expansion to reduce import dependency for protein therapeutics. The Kansai region concentrates contract manufacturing organizations serving ophthalmology-focused pharmaceutical partnerships.
India
CDSCO regulatory pathways for biosimilar approvals attract multinational licensing agreements for bevacizumab copy products. The PLI scheme incentivizes domestic production of biologic active pharmaceutical ingredients to capture export demand from African and Southeast Asian markets. Hyderabad and Bengaluru biotech parks host contract research organizations supporting immunogenicity surveillance for emerging market filings.
Switzerland
Swissmedic oversight of biologic manufacturing maintains quality standards for export-oriented production facilities. Basel-area pharmaceutical headquarters coordinate global clinical trial networks for VEGF-immune checkpoint inhibitor combinations. The country's central logistics position supports cold chain distribution into Southern European and Middle Eastern hospital systems.
Vascular Endothelial Growth Factor (VEGF) Antibodies Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and therapeutic focus. The market structure concentrates around originator biotechnology firms with entrenched ophthalmology franchises and emerging biosimilar developers capturing volume through purchasing coalition contracts. Three archetypes dominate: integrated biopharmaceutical conglomerates with oncology-ophthalmology dual portfolios, mid-cap biosimilar specialists leveraging interchangeability designations, and contract manufacturers supplying active pharmaceutical ingredients to branded and generic marketers. Competitive moves center on high-concentration formulation development for extended dosing intervals and vertical integration into fill-finish capacity to secure supply chain control.
Within the integrated biopharmaceutical tier, Regeneron Pharmaceuticals and F. Hoffmann-La Roche Ltd exemplify originator incumbents defending market position through ophthalmology revenue anchoring and oncology protocol entrenchment. Novartis AG occupies a position bridging originator and biosimilar strategies through portfolio diversification across retinal and oncology indications. These three entities represent the defensive moat structure that emerging competitors must navigate through interchangeability-enabled substitution or differentiated mechanism combinations.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Bayer AG |
| Pfizer |
| Amgen |
| Biogen |
| Coherus BioSciences |
| Viatris |
| Others |
Value Network & Pricing Analysis
Mammalian cell culture capacity utilization above 85% in South Korean and German facilities anchors supply concentration and sets minimum viable price floors for biosimilar entrants. Chinese hamster ovary line availability constraints concentrate bargaining power with contract manufacturers, forcing developers to accept longer lead times or premium slot pricing for glycosylation-controlled production runs.
Pricing Analysis
Originator-to-biosimilar pricing gaps span three technology generations: reference monoclonal antibodies at premium positioning, FDA-interchangeable biosimilars at standard tier, and emerging polyvalent constructs commanding economy-plus segmentation. Price differentiation rests on glycosylation pattern certification and EMA comparability study completion status. Cost compression in the standard tier intensifies as German hospital purchasing coalitions extract volume rebates exceeding 40% from interchangeable bevacizumab suppliers. Academic medical centers demonstrate highest price sensitivity due to CMS reimbursement recalibrations, while retinal specialists in US metropolitan markets show lowest sensitivity due to patient convenience premiums.
Supply Chain Analysis
Basel-to-Boston cold chain transit through Swissmedic-certified facilities underwrites temperature integrity for fill-finish operations serving ophthalmology markets. Active pharmaceutical ingredient production concentrates in Switzerland, Germany, and Singapore, with mammalian cell culture media and single-use bioreactor bags drawing from US and Japanese suppliers. Single-source vulnerability in Chinese hamster ovary cell line licensing creates concentration risk for mid-cap biosimilar developers. Distribution runs through manufacturer-direct relationships with integrated delivery networks, displacing traditional wholesale channels for intravenous oncology formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized glycosylation engineering expertise and extended pharmacovigilance infrastructure represent scarce capabilities that determine competitive survival as biosimilar interchangeability rulings compress development timelines.
For Market Incumbents: Compound defensive moats through backward integration into mammalian cell culture capacity and captive fill-finish operations in the Rhine-Main biotech cluster. Accelerate high-concentration aflibercept formulation development to extend dosing intervals and preempt biosimilar volume capture in retinal practice. Prioritize real-world evidence generation through integrated delivery network partnerships to defend formulary positioning against interchangeable substitutes. For New Entrants and Emerging Players: Lead with subcutaneous formulation development for oncology indications as the most penetrable white-space target, exploiting administration site economics that favor home settings over infusion center capacity constraints. Target hepatocellular carcinoma combination protocols with VEGF-immune checkpoint inhibitor pairings where reference product loyalty remains weakest. Pursue single-source procurement contracts with Texas and Florida hospital purchasing coalitions as the primary go-to-market channel. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with established Chinese hamster ovary line expertise and cold chain distribution infrastructure over asset-light biosimilar marketers. Long-term viability hinges on vertical integration depth through the analysis window. Acquisition target archetype: mid-cap developers with FDA interchangeability designations and committed volume thresholds under integrated delivery network contracts. Watch EMA biosimilar interchangeability rulings as the critical signal for European pricing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| High-Concentration Formulation Development | Extends dosing intervals to 12-16 weeks, reducing clinic capacity constraints for retinal specialists. |
| Biosimilar Interchangeability Pursuit | FDA determination under BPCIA enables automatic pharmacy substitution and accelerates volume access. |
| Real-World Evidence Integration | FDA guidance expansion allows label extension via electronic health record data from integrated networks. |
| Backward Integration into Cell Culture | Captive Chinese hamster ovary capacity secures glycosylation control and insulates against manufacturing bottlenecks. |
| Single-Source Procurement Contracts | Committed volume thresholds with rebate guarantees concentrate demand and displace traditional wholesaler relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA biosimilar approval filings, EMA Committee for Medicinal Products for Human Use opinions, ClinicalTrials.gov protocol registrations, and CMS Medicare Part B reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation across the analysis window.
Across the projection horizon, the analytical framework segmented demand by product type, application, end user, and distribution channel with treatment line and administration route as cross-cutting dimensions. CAGRs were derived from patent cliff erosion curves, biosimilar uptake velocity in German hospital purchasing coalitions, and ophthalmology injection frequency trends. Forecast inputs incorporated PMDA review timeline assumptions for Japanese ranibizumab biosimilars and METI industrial policy support for domestic mammalian cell culture expansion.
The analysis sits within stated boundaries; outcomes outside sustained FDA interchangeability determinations and stable CMS reimbursement policies would require recalibration. Forecasts reflect documented assumptions regarding biosimilar substitution elasticity and cold chain infrastructure development in Southeast Asian markets. Practitioners should keep alternative scenarios live as EMA biosimilar interchangeability rulings and EU AI Act conformity assessment timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Toxoid Vaccines Market