
 Conjunctivitis Market | 2026-2036
Conjunctivitis Market Size, Share, and Industry Trends Forecast 2026-2036
Conjunctivitis Market Analysis
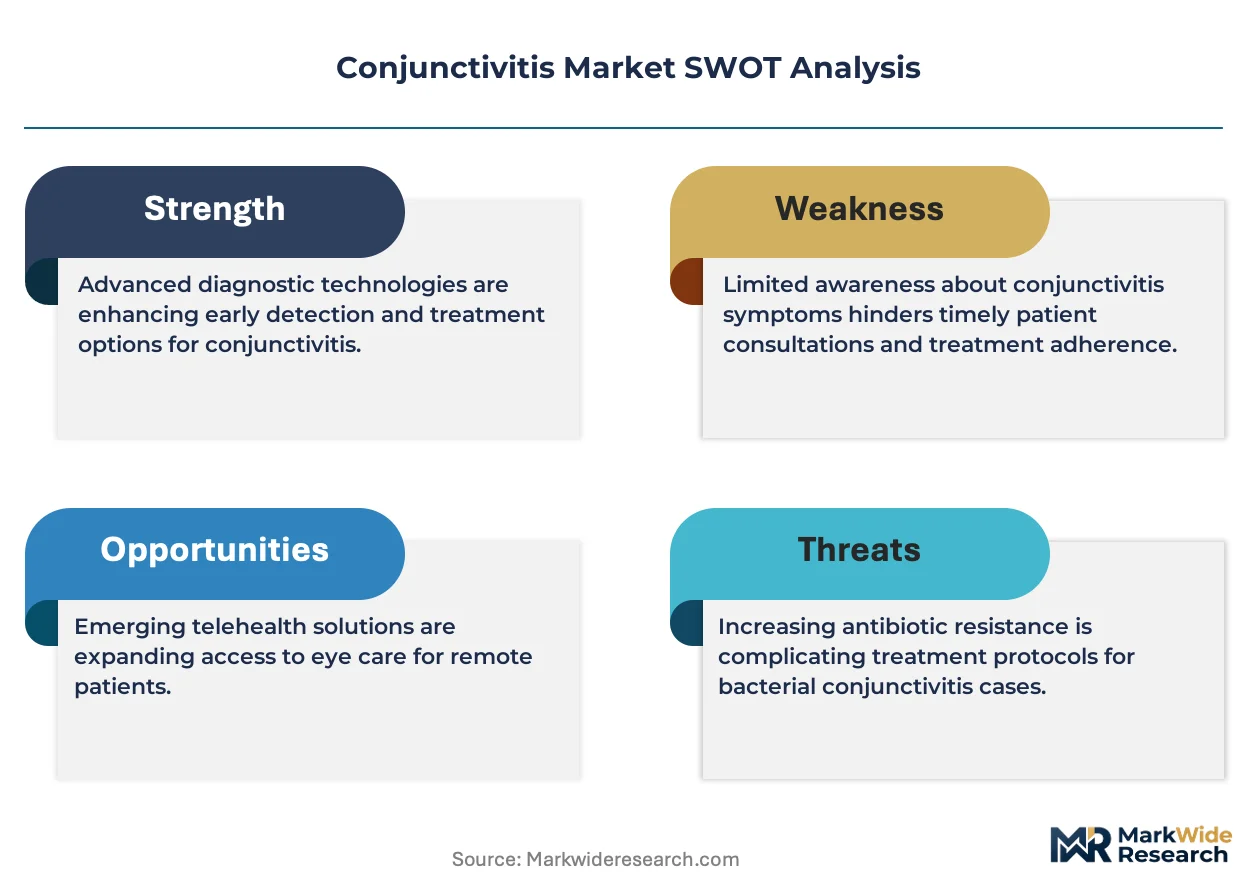
Specialty API manufacturers in India are recalibrating bulk production of fluoroquinolone and macrolide intermediates to serve branded and generic ophthalmic formulators. Novartis AG leverages its integrated sterile manufacturing network to sustain supply continuity for preservative-free formulations. Alcon competes through direct-to-practitioner channel control in North American optometry, while Santen Pharmaceutical Co., Ltd anchors its position in Asian hospital procurement systems with differentiated ocular delivery technologies.
Conjunctivitis denotes acute or chronic inflammation of the bulbar and palpebral conjunctiva, typically presenting with hyperemia, discharge, and pruritus caused by bacterial, viral, allergic, or irritant etiologies; diagnosis relies on slit-lamp biomicroscopy, culture, or point-of-care immunoassay, with treatment selection driven by pathogen identification and symptom severity. The condition's primary commercial purpose centers on rapid symptomatic relief and pathogen eradication to prevent corneal complication and transmission. Antibiotic formulations retain the largest revenue share due to high bacterial incidence and established reimbursement, while antihistamine demand accelerates fastest among seasonal allergic presentations in temperate climates. Ocular administration routes command premium positioning over topical and oral alternatives because of direct anterior segment bioavailability and reduced systemic exposure.
FDA cGMP regulations for sterile ophthalmic products and EMA's MDR requirements for preservative safety testing shape formulation development timelines and market access barriers for new entrants. The EPA's pharmaceutical effluent guidelines and REACH chemical restrictions additionally constrain excipient selection and manufacturing site qualification across multi-jurisdictional supply chains. Stakeholders must monitor evolving pharmacovigilance signal detection requirements for corticosteroid-sparing combination therapies as regulatory scrutiny intensifies on long-term ocular surface toxicity.
Market Dynamics
FDA's streamlined ANDA pathway for generic ophthalmic suspensions is compressing development timelines while managed care formularies in the United States increasingly favor cost-effective antihistamine therapies over branded antibiotics.
Growth Catalysts
- ANDA Streamlining:FDA's abbreviated new drug application pathway for generic ophthalmic suspensions accelerates therapeutic substitution and expands patient access to lower-cost alternatives.
- Hospital Outpatient Expansion:Rising prescription volumes in hospital outpatient departments reflect broader insurance coverage expansion and improved point-of-care diagnostic availability.
- Preservative-Free Demand:Patient and prescriber preference for preservative-free formulations drives investment in unit-dose packaging and sterile manufacturing upgrades.
Market Restraints
- API Concentration Risk:Bulk fluoroquinolone and macrolide intermediate production concentrates among specialty manufacturers in India, creating single-source vulnerability for generic formulators.
- EMA MDR Compliance Burden:Medical Device Regulation requirements for preservative safety testing extend formulation development timelines and raise qualification costs for new entrants.
- Systemic Alternative Substitution:Oral antihistamines and antibiotics compete on convenience and lower out-of-pocket costs, pressuring ocular-specific pricing power.
Strategic Opportunities
- Asian Hospital Procurement:Differentiated ocular delivery technologies unlock volume contracts in Japan, South Korea, and Singapore where hospital systems dominate pharmaceutical purchasing.
- Corticosteroid-Sparing Combinations:EMA pharmacovigilance signal detection requirements for long-term ocular surface toxicity create first-mover advantage for safer combination therapies.
- Direct-to-Practitioner Channels:North American optometry practices represent underpenetrated distribution nodes bypassing traditional pharmacy benefit manager controls.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:cGMP-qualified aseptic processing engineers and validation specialists command premium compensation, constraining capacity expansion timelines.
- Multi-Jurisdictional Excipient Qualification:EPA pharmaceutical effluent guidelines and REACH chemical restrictions force redundant testing and site qualification across supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conjunctivitis Market |
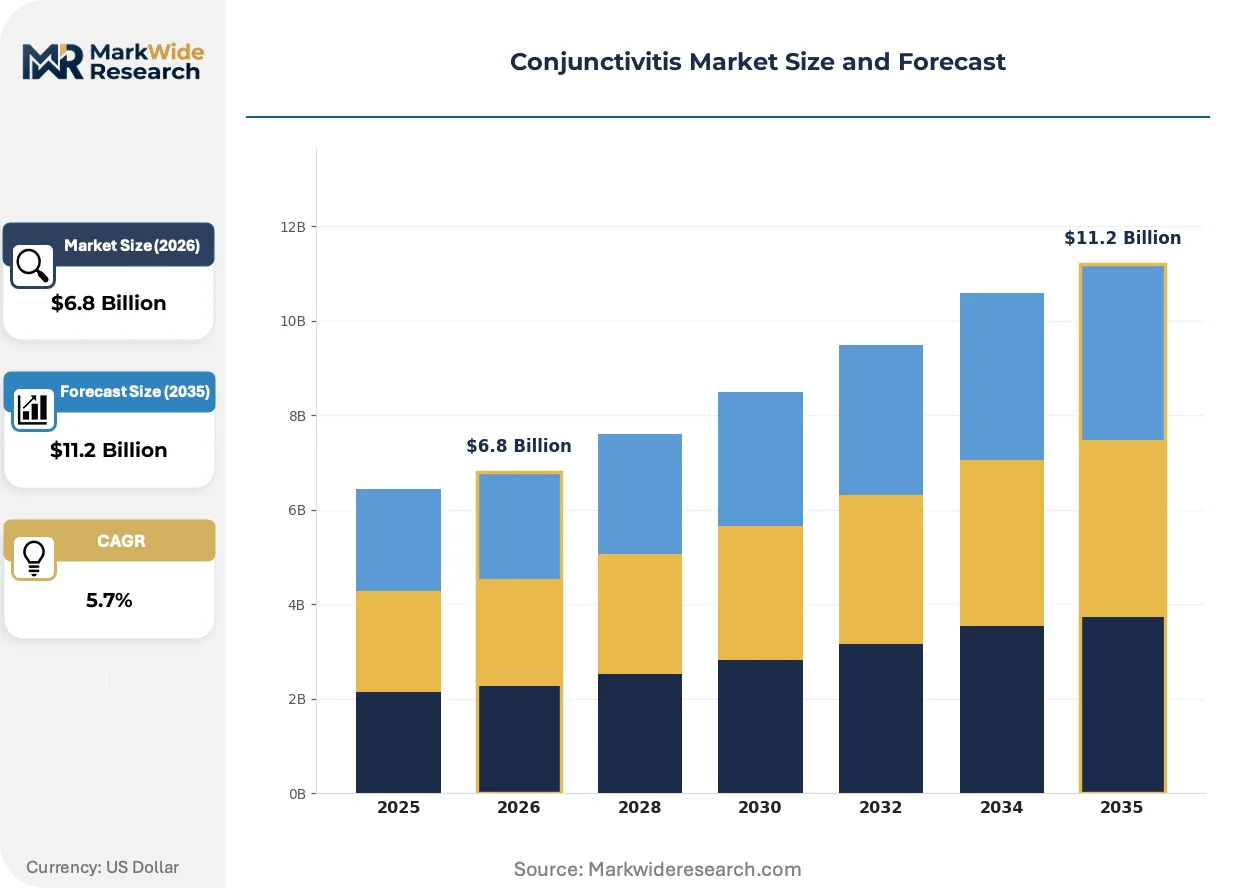
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Antibiotics, Antivirals, Corticosteroids Administration Route: Topical, Oral, Injectable, Ocular End User: Clinics, Hospitals, Home Care, Pharmacies Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Allergan, Novartis AG, Alcon, Bausch & Lomb Incorporated, Santen Pharmaceutical Co., Ltd, AbbVie Inc., Pfizer Inc., Sun Pharmaceutical Industries Ltd., Alembic Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conjunctivitis Market Emerging Trajectories
Point-of-care immunoassay platforms and preservative-free delivery systems are compressing diagnostic-to-treatment intervals while reshaping competitive differentiation around safety profiles rather than efficacy alone.
Nanoparticle-based drug delivery systems is rewriting anterior segment bioavailability standards by enabling sustained-release profiles with reduced dosing frequency. Hospital ophthalmology departments and specialty clinics in Germany and the United States are piloting these platforms for chronic allergic conjunctivitis management. The technology is compressing competitive advantage around formulation science rather than molecular innovation.
EMA's Medical Device Regulation Annex XVI expansion reclassifies certain combination ophthalmic products as borderline medical devices, triggering additional conformity assessment procedures. Manufacturers must now submit clinical evidence packages addressing both pharmaceutical and device performance characteristics. This regulatory friction most affects preservative-containing multi-dose containers targeting European hospital procurement tenders.
Optometry practice consolidation across the United States is concentrating purchasing power among multi-location groups negotiating directly with manufacturers. Traditional wholesale distributor relationships are fragmenting as these groups establish preferred vendor agreements with guaranteed volume commitments. This channel restructuring is most advanced in California, Texas, and Florida where regulatory scope-of-practice expansions have enlarged the treatable patient base.
Conjunctivitis Market Segmentation
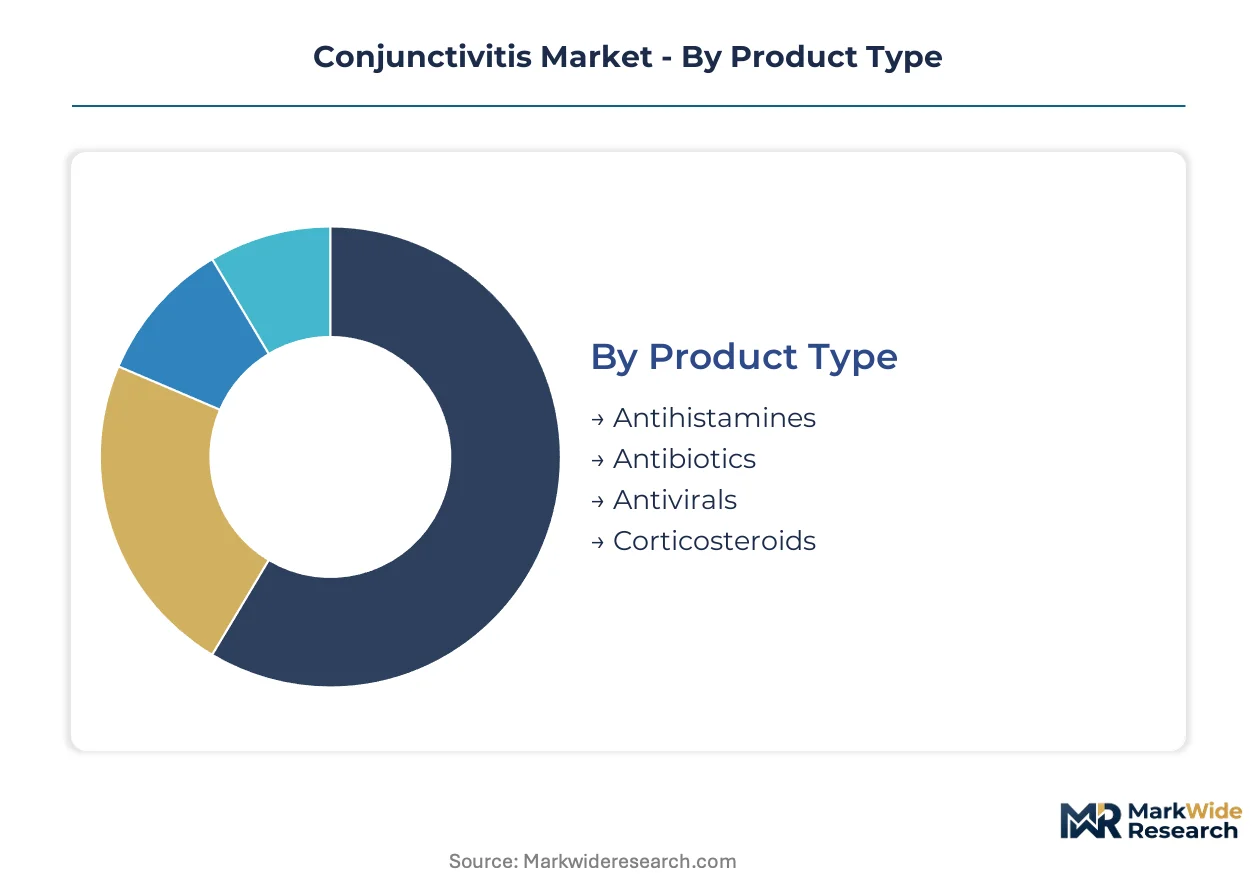
Segmentation in the conjunctivitis market reveals distinct procurement patterns across clinical settings and patient self-treatment behaviors. Product formulation choices diver sharply between acute infectious cases requiring pathogen-targeted therapy and chronic allergic presentations favoring symptomatic control. Understanding these divides enables targeted commercial strategy and regulatory pathway optimization.
Product Type:
Integration depth varies substantially across therapeutic classes, with standalone antibiotic formulations dominating acute care protocols while antihistamines increasingly embed within broader allergy management regimens.
- Antibiotics:Fluoroquinolone and macrolide formulations target bacterial pathogens with established culture-guided prescribing in hospital emergency departments. Demand concentrates in the United States where managed care formularies maintain broad reimbursement despite generic substitution pressure from FDA's streamlined ANDA pathway.
- Antihistamines:Dual-action H1-receptor antagonists with mast-cell stabilizing properties address seasonal allergic presentations without the infection risk of corticosteroid overuse. Prescription volumes are climbing fastest in temperate climate zones where pollen indices drive cyclical demand spikes.
- Antivirals:Limited to severe adenoviral keratoconjunctivitis cases requiring specialist referral.
- Corticosteroids:Reserved for refractory inflammatory presentations under ophthalmologist supervision due to IOP elevation and cataractogenesis risks.
Antibiotics lead volumes today; antihistamines are gaining share fastest.
Administration Route:
Cost tier stratification separates premium-positioned ocular delivery from commodity oral alternatives competing on convenience and out-of-pocket affordability.
- Ocular:Topical drops and ointments achieve direct anterior segment bioavailability with minimized systemic exposure, justifying premium pricing in formulary negotiations. Unit-dose preservative-free formats command additional price multiples in Japan and Germany where ocular surface toxicity concerns drive prescribing preferences.
- Topical:Periocular creams and gels serve adjacent dermatological presentations with overlapping inflammatory pathways. Demand clusters in European markets where EMA MDR requirements have elevated documentation standards for combination device-drug products.
- Oral:Systemic antihistamines and antibiotics compete on patient convenience for mild presentations, pressuring ocular-specific pricing power through pharmacy benefit manager substitution protocols.
- Injectable:Intravitreal and subconjunctival depot formulations address severe or sight-threatening complications requiring specialist intervention.
Ocular administration dominates revenue per patient; oral routes capture the highest prescription counts through primary care gatekeepers.
End User:
Customer type segmentation maps to acuity gradients, with hospitals managing severe infectious complications while home care and retail channels absorb the long tail of self-limiting cases.
- Hospitals:Inpatient and emergency ophthalmology services handle culture-positive bacterial infections, neonatal ophthalmia, and trauma-related complications requiring parenteral therapy. Asian hospital procurement systems in Japan and South Korea favor tenders specifying differentiated delivery technologies with guaranteed volume commitments.
- Clinics:Outpatient ophthalmology and optometry practices perform slit-lamp diagnostics and initiate targeted therapy based on point-of-care immunoassay results. North American optometry consolidation is concentrating purchasing power among multi-location groups negotiating direct manufacturer agreements.
- Home Care:Self-administered regimens for chronic allergic conjunctivitis leverage over-the-counter antihistamine availability.
- Pharmacies:Community and specialty pharmacy dispensing bridges prescription fulfillment with patient counseling on proper instillation technique and compliance.
Hospitals anchor infectious disease volumes; clinics are expanding fastest as scope-of-practice liberalizations enlarge the treatable patient base.
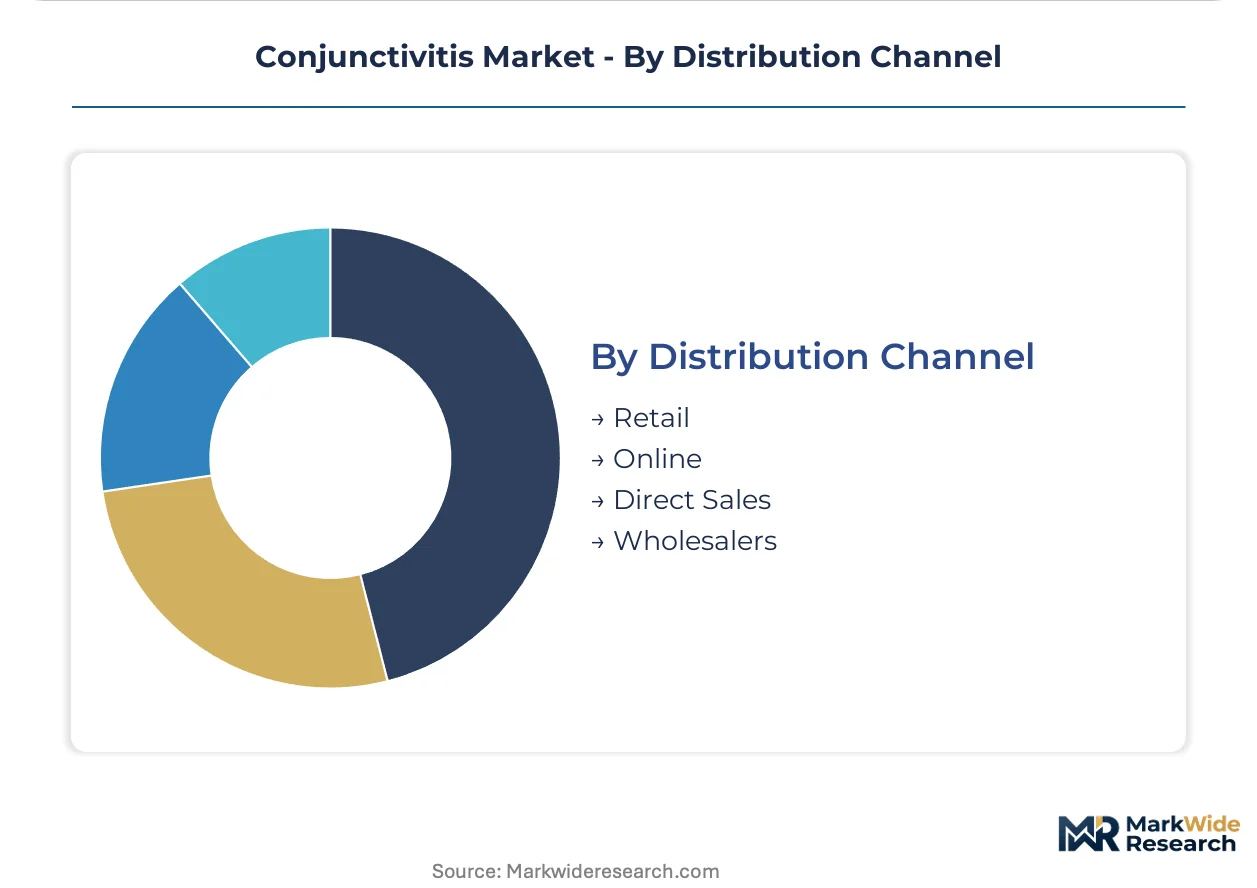
Distribution Channel:
Supply concentration patterns separate controlled wholesale networks serving institutional purchasers from fragmented retail and direct channels reaching individual practitioners.
- Retail:Chain and independent pharmacies maintain broad geographic coverage with immediate fulfillment for acute symptom relief. Shelf space allocation favors established brands with proven reimbursement codes in the United States.
- Wholesalers:Distributors like McKesson and Cardinal Health consolidate procurement for hospital systems and large clinic networks, capturing economies of scale in logistics and cold-chain handling for preservative-free formulations.
- Direct Sales:Manufacturer representatives cultivate relationships with optometry practices and ophthalmology departments, bypassing traditional distributor markups through guaranteed volume contracts.
- Online:Telehealth-integrated platforms and mail-order pharmacies serve chronic medication refills with automated compliance programs.
Wholesale channels move the highest absolute volumes; direct sales are expanding most quickly as practice consolidation enables vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting sterile ophthalmic manufacturing toward jurisdictions with streamlined approval pathways and lower compliance costs, while mature markets impose escalating safety documentation burdens that favor incumbents with established pharmacovigilance infrastructure.
United States
Hospital outpatient departments drive prescription volume expansion through improved insurance coverage and point-of-care diagnostic deployment. FDA's streamlined ANDA pathway for generic ophthalmic suspensions accelerates therapeutic substitution and compresses development timelines for domestic formulators. California and Texas host the most concentrated optometry practice consolidation, enabling direct manufacturer contracting that bypasses traditional wholesale channels.
Germany
Unit-dose preservative-free formats command premium price multiples driven by ocular surface toxicity concerns among prescribing ophthalmologists. EMA's Medical Device Regulation Annex XVI expansion reclassifies certain combination ophthalmic products as borderline medical devices, triggering additional conformity assessment procedures. The Rhine-Ruhr industrial corridor anchors sterile manufacturing capacity serving hospital procurement tenders across Central Europe.
Japan
Differentiated ocular delivery technologies unlock volume contracts within hospital-dominated pharmaceutical purchasing systems. PMDA maintains stringent preservative safety testing requirements that extend formulation development timelines but create defensive moats for qualified manufacturers. The Kanto region around Tokyo concentrates specialty API production and sterile packaging innovation for Asian export markets.
India
Bulk fluoroquinolone and macrolide intermediate production concentrates among specialty manufacturers serving branded and generic ophthalmic formulators worldwide. CDSCO's evolving bioequivalence standards for complex ophthalmic suspensions are narrowing the regulatory gap with ICH jurisdictions. Gujarat and Maharashtra host the dominant API manufacturing clusters where producers are recalibrating output to serve both domestic formulation and export demand.
South Korea
Hospital procurement systems favor tenders specifying differentiated delivery technologies with guaranteed volume commitments. MFDS alignment with international cGMP standards for sterile ophthalmic products is accelerating site qualification for multi-jurisdictional supply chains. The Seoul Capital Area concentrates formulation R&D and clinical trial infrastructure for regional market access.
Conjunctivitis Market Vendor Landscape
United States-based producers anchor the premium formulation tier; Indian specialists hold the generic API and intermediate supply base. Market structure consolidates around integrated sterile manufacturing networks capable of preservative-free unit-dose output, with fragmentation persisting among regional distributors and specialty formulators. Three archetypes dominate: multinational pharmaceutical conglomerates with ophthalmology divisions, mid-cap generic specialists leveraging ANDA streamlining, and API-forward integrated manufacturers. Competitive moves concentrate on direct-to-practitioner channel control and sterile manufacturing capacity expansion.
Within the multinational tier, Novartis AG and Alcon represent the integrated sterile manufacturing archetype, while Santen Pharmaceutical Co., Ltd occupies a position exemplifying Asian hospital procurement specialization. These entities anchor competitive positioning through differentiated ocular delivery technologies and direct practitioner relationships rather than molecular innovation alone.
| Leading Market Players |
|---|
| Allergan |
| Novartis AG |
| Alcon |
| Bausch & Lomb Incorporated |
| Santen Pharmaceutical Co., Ltd |
| AbbVie Inc. |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Alembic Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Captive sterile manufacturing networks anchor supply continuity for preservative-free formulations while simultaneously defending premium price multiples in formulary negotiations. FDA's streamlined ANDA pathway for generic ophthalmic suspensions is compressing development timelines and forcing branded incumbents to differentiate through unit-dose packaging investments rather than molecule exclusivity.
Pricing Analysis
Distributor margin compression runs through wholesale channels serving hospital systems, while direct-to-practitioner contracts bypass traditional markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates preservative-free unit-dose formats from multi-dose alternatives and commodity generics. Cost compression in the generic tier is intensifying because of therapeutic substitution pressure from FDA's accelerated ANDA reviews. Hospital procurement committees demonstrate lowest price sensitivity due to bundled reimbursement protocols, whereas retail pharmacy substitution protocols amplify consumer out-of-pocket sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with specialty API manufacturers in India producing fluoroquinolone and macrolide intermediates for global formulators. Bulk chemical production draws from India, China, and the United States, with sterile finishing capacity concentrating in Germany, Japan, and the United States. Active pharmaceutical ingredient feedstocks, borosilicate glass vials, and unit-dose blister films constitute critical input dependencies. Tariff exposure on Chinese-sourced excipients threatens margin stability for multi-jurisdictional supply chains. Distribution runs through consolidated wholesale networks for institutional purchasers and fragmented direct sales for optometry practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA's streamlined ANDA pathway and EMA's extended MDR compliance timelines creates geographic cost differentials for formulation development. Manufacturers can compress qualification expenses by sequencing market entry through jurisdictions with abbreviated review protocols.
For Market Incumbents: Acquire sterile manufacturing capacity in the United States and Germany to defend preservative-free formulation margins against generic substitution pressure from FDA's accelerated ANDA pathway. Expand direct-to-practitioner channel control in California and Texas where optometry consolidation enables volume-based contracting. Invest in nanoparticle-based delivery platforms to shift competitive differentiation toward formulation science rather than molecular innovation. For New Entrants and Emerging Players: FDA's streamlined ANDA pathway in the United States opens a window for mid-cap generic specialists to capture share in bacterial antibiotic suspensions before branded incumbents pivot to combination therapies. Target the North American antihistamine segment where managed care formularies increasingly favor cost-effective alternatives. Establish preferred vendor agreements with multi-location optometry groups bypassing traditional wholesale distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile manufacturing talent scarcity constrains capacity expansion timelines and qualified aseptic processing engineers command premium compensation. Five-to-ten year viability favors integrated manufacturers with backward control over API supply and forward relationships with hospital procurement systems. Monitor FDA pharmacovigilance signal detection requirements for corticosteroid-sparing combinations as an inflection indicator for safety-driven prescribing shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Manufacturing Scale-Up | Unit-dose sterile capacity captures premium pricing in Japanese and German hospital tenders. |
| Direct-to-Practitioner Channel Expansion | Bypassing wholesale distributors protects margins in consolidated Texas and California optometry markets. |
| Nanoparticle Delivery Platform Development | Sustained-release profiles reduce dosing frequency and anchor differentiation in chronic allergic presentations. |
| Asian Hospital Procurement System Integration | Volume contracts in Japan and South Korea favor differentiated ocular delivery technologies with guaranteed commitments. |
| ANDA Portfolio Acceleration | FDA's streamlined pathway compresses generic ophthalmic suspension approval timelines and expands patient access. |
Methodological Framework
Multiple input streams — regulatory filing databases, hospital procurement contract records, and sterile manufacturing capacity registries — were reconciled against primary interviews with ophthalmology department heads, formulary directors at managed care organizations, and regulatory affairs leads at ophthalmic formulators. Secondary validation drew from FDA ANDA approval records, EMA MDR submission timelines, and Japanese PMDA preservative safety testing guidelines. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure estimates were triangulated to anchor market size calculations.
Historical prescription trajectory cross-referenced against panel input from hospital pharmacy managers and optometry practice administrators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, administration route, end-user setting, and regional regulatory cluster. CAGRs were derived from prescription volume elasticity analysis and pricing power assessments by therapeutic class. Forecast inputs incorporated ANDA approval velocity, scope-of-practice expansion patterns, and preservative-free formulation adoption curves.
Revisions become necessary when FDA pharmacovigilance signal detection requirements intensify, EMA MDR compliance timelines extend unexpectedly, or API supply disruptions emerge from concentrated Indian manufacturing clusters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ocular Pain Market
Ophthalmology
Macular Edema Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Usher Syndrome Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
United Kingdom Ophthalmology Devices Market