
 Amoxicillin Drugs Market | 2026-2036
Amoxicillin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Amoxicillin Drugs Market Analytics
Subscription-based antimicrobial stewardship programs is repositioning how hospital systems procure amoxicillin, shifting volume commitments toward bundled compliance services. Pfizer Inc. leverages its hospital formulary relationships to sustain branded positioning despite generic erosion. Teva Pharmaceutical Industries Ltd. anchors North American retail pharmacy supply through vertically integrated API-to-tablet manufacturing. Aurobindo Pharma Limited dominates export tenders to low-income markets with cost-optimized powder-for-oral-suspension formats.
Amoxicillin drugs are beta-lactam antibiotics synthesized from 6-aminopenicillanic acid via fermentation and acylation, formulated as trihydrate or sodium salts with defined potency against gram-positive and select gram-negative pathogens. The compound serves as first-line therapy for community-acquired respiratory and urinary tract infections across outpatient and institutional settings. Tablet and capsule forms command stable margin pools in mature retail channels where patient compliance drives refill economics. Powder formulations for reconstitution represent the fastest-growing segment in pediatric and emerging-market therapy areas where cold-chain flexibility and dose titration matter. Hospital pharmacy distribution channels concentrate procurement volume through tender-based contracting, while retail pharmacies fragment demand across insured and cash-pay patient segments.
FDA bioequivalence standards shape generic amoxicillin market access through abbreviated new drug application pathways that require dissolution profile matching to reference listed drugs. EMA's pharmacovigilance obligations and REACH-derived impurity thresholds constrain API sourcing from non-audited manufacturers, elevating compliance costs for European market entry. India's CDSCO and PLI scheme for bulk drugs redirect domestic capacity toward import substitution of penicillin G fermentation intermediates. Stakeholders must monitor regulatory divergence between FDA dissolution specification updates and WHO prequalification criteria for tender eligibility in pooled procurement markets.
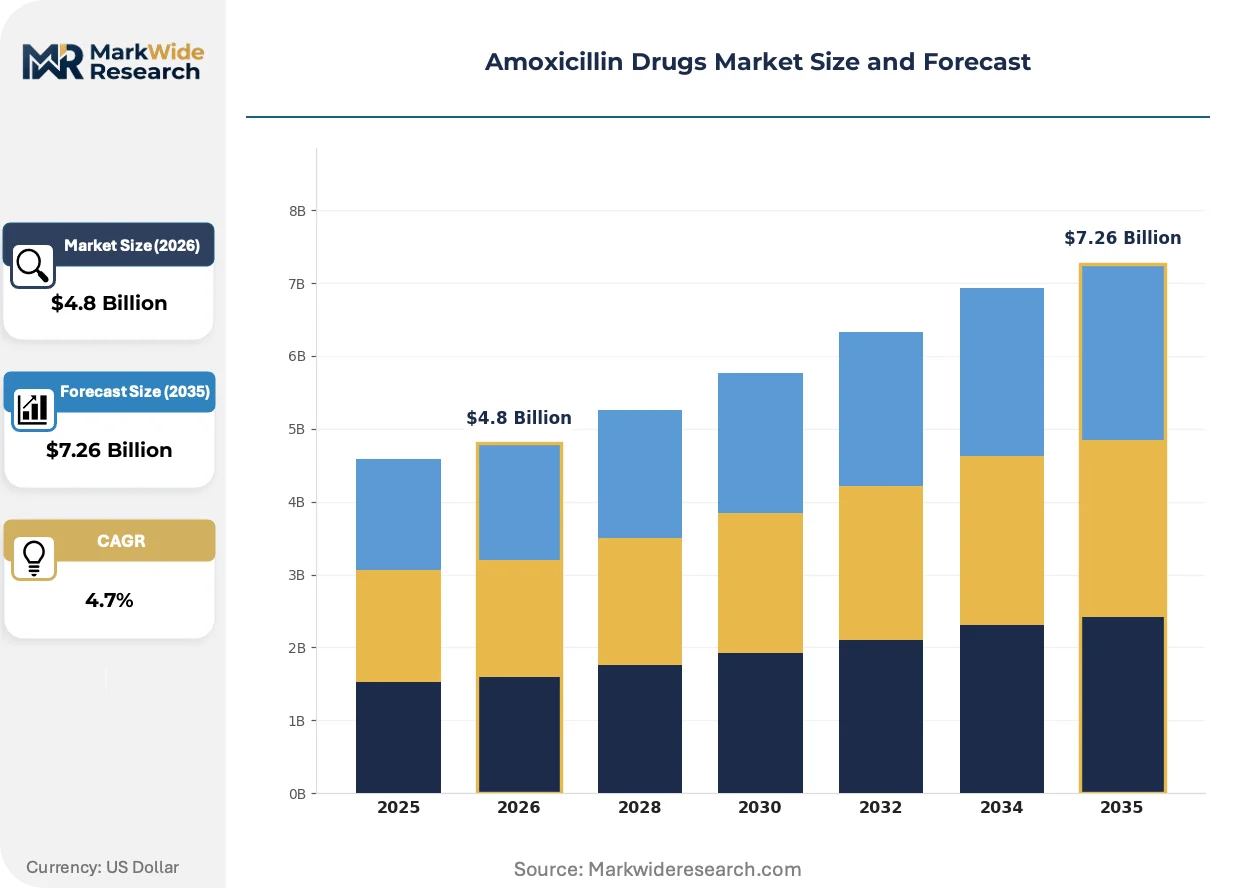
Market Dynamics
Antimicrobial resistance surveillance mandates are compressing procurement cycles for first-line antibiotics, forcing hospital systems to consolidate volume commitments under stewardship-linked contracts rather than spot purchasing.
Growth Catalysts
- India PLI scheme for bulk drugs:The production-linked incentive program redirects domestic fermentation capacity toward penicillin G intermediates, reducing import dependency for API precursors and stabilizing raw material flows.
- Pediatric formulation demand:Powder-for-oral-suspension formats gain traction in outpatient settings where dose flexibility and ambient storage requirements outweigh tablet convenience.
- WHO Essential Medicines List designation:The listing sustains pooled procurement eligibility across public health systems, locking in volume visibility for qualified manufacturers.
Market Restraints
- Penicillin G price volatility:Fermentation feedstock costs fluctuate with agricultural commodity cycles, squeezing margin predictability for API producers dependent on corn steep liquor and soybean meal inputs.
- EMA REACH impurity thresholds:The registration, evaluation, authorization and restriction of chemicals framework elevates compliance burdens for European market entry, screening out non-audited API suppliers.
- Macrolide substitution in respiratory:Azithromycin and clarithromycin alternatives capture share in community-acquired pneumonia where atypical pathogen coverage is prioritized over narrow-spectrum therapy.
Strategic Opportunities
- Sub-Saharan Africa tender markets:WHO prequalification pathways open access to pooled procurement mechanisms serving ministries of health with limited individual negotiating capacity.
- Fixed-dose combination expansion:Amoxicillin-clavulanate formulations address beta-lactamase resistance patterns, commanding premium positioning in hospital formularies.
- Direct-to-pharmacy distribution:Bypassing wholesale intermediaries reduces working capital cycles for generic manufacturers serving cash-pay retail channels.
Industry Challenges
- Fermentation process engineering talent:Deep expertise in industrial-scale penicillin strain optimization and downstream recovery is concentrated among retiring cohorts, constraining capacity expansion timelines.
- FDA dissolution specification alignment:Bioequivalence testing protocols require precise matching to reference listed drug profiles, extending ANDA approval timelines for formulation modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amoxicillin Drugs Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Tablet, Capsule, Suspension, Powder Therapy Area: Infections, Antibiotics, Dental, Pediatric Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesalers Pricing Model: Generic, Branded, Tiered Pricing, Discounted |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Novartis AG, Aurobindo Pharma Limited, Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Cipla Limited, Sandoz International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amoxicillin Drugs Market Evolving Landscape
Continuous manufacturing platforms are displacing batch fermentation for oral solid dosage production, compressing cycle times and reducing in-process inventory holding costs across generic antibiotic supply chains.
Process analytical technology is converging with real-time release testing protocols, enabling parametric control over crystallization and drying stages. Generic manufacturers adopting these systems reduce end-product testing burdens and accelerate lot release timelines. The structural consequence is a compression of quality assurance overhead toward upstream process control rather than downstream inspection.
EMA's pharmacovigilance periodic safety update report obligations now require granular exposure data by formulation type and pediatric indication. Manufacturers must invest in traceability infrastructure linking dispensing records to adverse event reporting systems. Hospital pharmacy buyers in Germany and France increasingly filter tenders through compliance scoring matrices that weight pharmacovigilance readiness alongside unit cost.
Hospital formulary committees are consolidating antibiotic stewardship oversight into centralized procurement functions, displacing individual prescriber autonomy with protocol-driven first-line selection. Retail pharmacy chains respond by developing private-label generic programs that mirror hospital tiering structures. This behavioral shift is most pronounced in US integrated delivery networks where pharmacy benefit managers align outpatient dispensing with inpatient resistance surveillance data.
Amoxicillin Drugs Market Segmentation
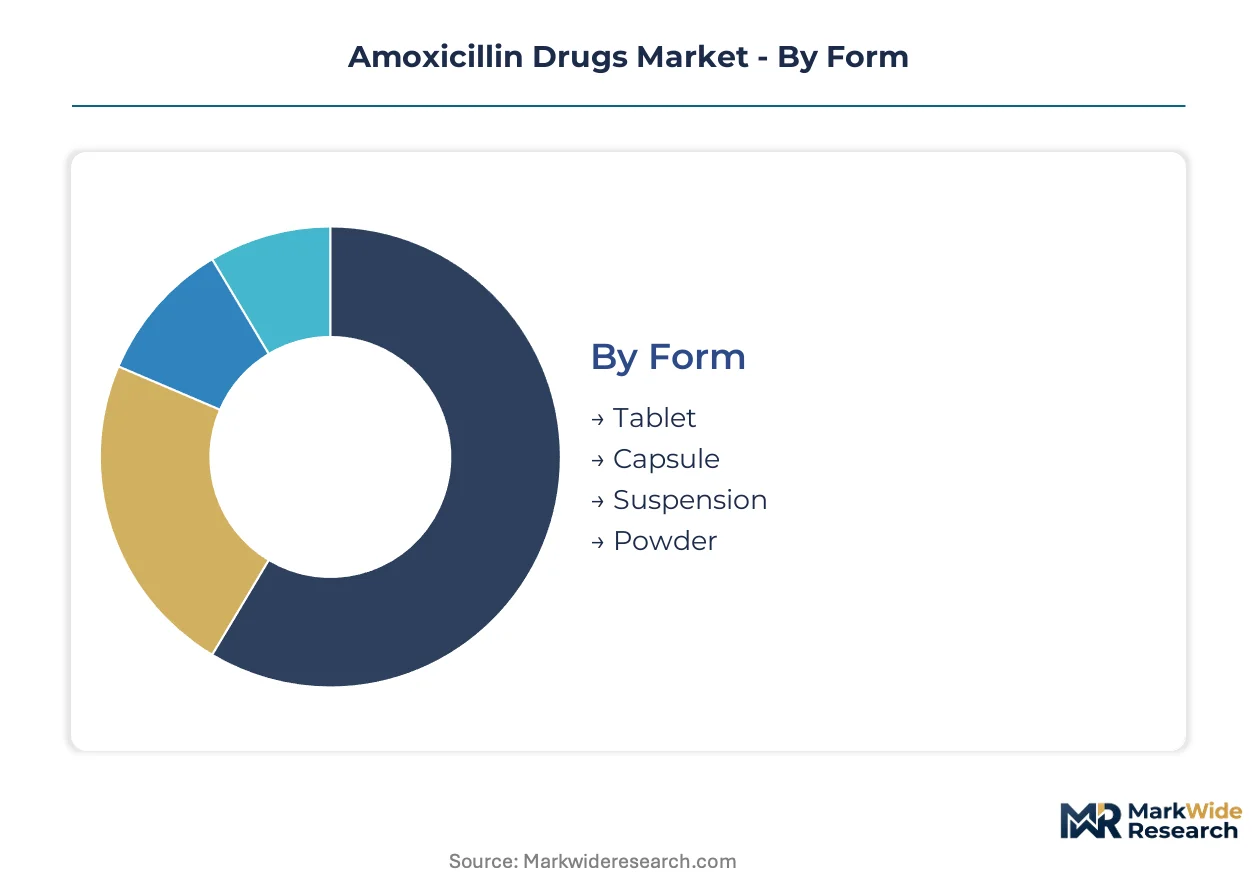
Amoxicillin formulation types carry divergent regulatory burdens that shape manufacturer entry costs and geographic market access. Certification requirements from FDA, EMA, and WHO prequalification programs segment competitive intensity across oral solid and liquid dosage categories.
Form:
FDA dissolution specifications and EMA bioequivalence standards create tiered approval timelines across solid and liquid presentations, with pediatric-focused formats commanding additional stability testing protocols.
- Tablet:Trihydrate-based compressed solids dominate outpatient dispensing volumes in mature retail channels. Demand concentrates in North American pharmacy chains where 30-day refill economics and insurance formulary tiering sustain margin pools. FDA ANDA pathways require precise dissolution profile matching to reference listed drugs.
- Capsule:Gelatin-encapsulated formulations offer faster dissolution kinetics and swallowing ease for adult populations. German and French hospital formularies favor capsule presentations in stewardship protocols where dose precision matters.
- Suspension:Reconstitutable liquid formats serve pediatric and geriatric populations with dosing flexibility. Ambient storage requirements and cold-chain independence drive procurement in Sub-Saharan African tender markets.
- Powder:Bulk API-for-reconstitution formats supply institutional compounding pharmacies and emerging-market manufacturers with formulation flexibility.
Leading the category by volume: Tablet. Growing fastest: Suspension.
Therapy Area:
Clinical indication shapes procurement channel selection and pricing power, with hospital-driven stewardship programs concentrating volume in infection management while retail fragmentation characterizes prophylactic segments.
- Infections:Community-acquired respiratory and urinary tract indications command first-line protocol placement across WHO Essential Medicines programs. India's public health systems anchor procurement volume through centralized tender mechanisms.
- Antibiotics:Systemic antibacterial therapy spans inpatient and outpatient settings with divergent resistance surveillance requirements. EMA pharmacovigilance periodic safety update reports mandate granular exposure tracking by indication.
- Dental:Prophylactic prescribing for endocarditis prevention and post-extraction coverage operates through cash-pay retail channels with limited insurance reimbursement. Brazilian and Mexican markets show concentrated dental antibiotic consumption patterns.
- Pediatric:Weight-based dosing requirements and palatability considerations favor powder-for-oral-suspension formats. CDSCO stability guidelines and WHO prequalification criteria impose additional formulation standards for this segment.
Infection management captures the largest procurement volumes. Pediatric applications are climbing the fastest as weight-optimized formulations penetrate lower-income markets.
Distribution Channel:
Channel selection determines working capital intensity and customer concentration risk, with hospital tenders offering volume visibility against retail fragmentation and wholesale intermediaries compressing margins.
- Retail Pharmacy:Chain and independent dispensaries fragment demand across insured and cash-pay patient segments. US pharmacy benefit manager formulary tiering and European generic substitution policies shape competitive dynamics.
- Online Pharmacy:Direct-to-consumer dispensing platforms expand geographic reach while raising cold-chain and counterfeit detection requirements. India's e-pharmacy regulations under CDSCO oversight are formalizing compliance standards.
- Hospital Pharmacy:Centralized procurement functions consolidate volume through tender-based contracting with antimicrobial stewardship-linked compliance scoring. German hospital buyers weight pharmacovigilance readiness alongside unit cost in vendor selection.
- Wholesalers:Distribution intermediaries aggregate fragmented retail demand but extend payment cycles and compress manufacturer margins. McKesson and Cardinal Health networks dominate North American wholesale flows.
Hospital pharmacy leads by procurement volume. Online pharmacy channels are gaining share fastest as regulatory frameworks mature.
Pricing Model:
Price architecture reflects intellectual property status, volume scale, and customer segmentation, with generic commoditization contrasting branded premium positioning in stewardship-contracted hospital systems.
- Generic:Bioequivalent formulations compete on manufacturing scale and API sourcing efficiency. India's PLI scheme for bulk drugs redirects domestic fermentation capacity toward cost-optimized penicillin G intermediates.
- Branded:Originators leverage hospital formulary relationships and clinical trial data packages to sustain premium positioning. Pfizer's hospital contracting teams defend share through bundled compliance services.
- Tiered Pricing:Three-tier structures across premium, standard, and economy levels align with certification grade and customer purchasing power. WHO prequalification unlocks pooled procurement access for qualified manufacturers.
- Discounted:Volume rebates and tender-specific pricing serve public health systems with constrained procurement budgets. Sub-Saharan African ministries of health negotiate through pooled procurement mechanisms.
Generic pricing dominates unit volume. Tiered structures are expanding fastest as manufacturers segment access across income-stratified markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors global amoxicillin API formulation capacity through its export-linked fermentation corridor and CDSCO-registered manufacturing parks serving WHO prequalified tender markets.
United States
Hospital formulary consolidation and pharmacy benefit manager tiering drive procurement concentration toward vertically integrated generic suppliers. FDA ANDA dissolution standards enforce bioequivalence testing rigor that extends approval timelines for new market entrants. New Jersey and North Carolina host the headquarters and distribution infrastructure of dominant hospital contracting organizations.
Germany
EMA pharmacovigilance periodic safety update report obligations shape vendor selection criteria for hospital pharmacy buyers prioritizing traceability infrastructure. REACH-derived impurity thresholds screen out non-audited API suppliers from European tender eligibility. Bavaria and North Rhine-Westphalia concentrate the country's pharmaceutical wholesale and hospital procurement decision-making functions.
India
CDSCO stability guidelines and the PLI scheme for bulk drugs redirect domestic fermentation capacity toward penicillin G intermediate production, reducing import dependency. WHO prequalification pathways unlock pooled procurement access to Sub-Saharan African ministries of health. Telangana and Gujarat dominate export-oriented formulation manufacturing with cost-optimized powder-for-oral-suspension capacity.
Brazil
ANVISA bioequivalence requirements and local content preferences in public health procurement sustain market access barriers for non-registered foreign suppliers. Dental prophylactic prescribing patterns concentrate retail antibiotic consumption in cash-pay pharmacy channels. São Paulo and Rio de Janeiro anchor the country's pharmaceutical distribution and hospital pharmacy procurement networks.
China
NMPA registration requirements and environmental compliance enforcement at fermentation facilities elevate production costs for penicillin G-derived APIs. Domestic demand for pediatric formulations supports powder-for-reconstitution manufacturing scale. Shandong and Jiangsu provinces host the concentrated industrial clusters for antibiotic API fermentation and downstream formulation.
Amoxicillin Drugs Market Competitive Landscape
Capital-heavy fermentation producers compete with asset-light formulation specialists across tiered procurement channels. Hospital formulary relationships and WHO prequalification status separate sustainable market access from commodity spot-selling. Three archetypes dominate: originator-backed branded players defending hospital stewardship contracts, Indian generic exporters capturing tender volumes, and vertically integrated API-to-tablet manufacturers serving retail pharmacy chains. Competitive moves center on antimicrobial stewardship program bundling and direct-to-pharmacy distribution bypassing wholesale intermediaries.
Among originator-backed pharmaceutical corporations, Pfizer Inc. and GlaxoSmithKline plc exemplify the branded-tier archetype leveraging clinical trial data packages and hospital formulary relationships. Within Indian generic manufacturing, Aurobindo Pharma Limited and Dr. Reddy's Laboratories Ltd. occupy positions defined by WHO prequalification status and cost-optimized export capacity. Teva Pharmaceutical Industries Ltd. represents the vertically integrated archetype with captive API supply and North American retail pharmacy channel dominance.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Aurobindo Pharma Limited |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Limited |
| Sandoz International GmbH |
| Others |
Value Network & Pricing Analysis
Continuous manufacturing platforms are displacing batch fermentation for oral solid dosage production, compressing cycle times and reducing in-process inventory holding costs across generic antibiotic supply chains. This technological shift simultaneously concentrates cost advantages among capital-intensive producers in India and China while fragmenting pricing power across formulation specialists lacking upstream API control.
Pricing Analysis
Stewardship-linked contracting anchors value-based pricing for hospital procurement, where formulary placement depends on bundled compliance services rather than unit cost alone. Three-tier pricing structure across premium, standard, and economy levels separates originator-backed branded players from Indian generic exporters and non-prequalified commodity suppliers. Price differentiation rests on WHO prequalification status and EMA pharmacovigilance readiness. Cost compression in economy-tier tender markets is intensifying because pooled procurement mechanisms aggregate volume and amplify buyer leverage. Cash-pay retail pharmacy segments show highest price sensitivity, while hospital systems with stewardship mandates prioritize traceability infrastructure over per-unit savings.
Supply Chain Analysis
Direct-to-pharmacy distribution channels handle hyperscale retail pharmacy demand in North America, bypassing wholesale intermediaries that extend payment cycles. API production concentrates in India, China, and the United States, with penicillin G fermentation intermediates drawing from agricultural feedstocks including corn steep liquor and soybean meal. Downstream formulation feeds from Hyderabad's export-linked manufacturing corridor and Shandong's industrial clusters. Single-source vulnerability in fermentation strain optimization expertise constrains capacity expansion timelines as retiring cohorts deplete technical talent pools. Distribution runs through hospital pharmacy tender networks in Europe, retail pharmacy chains in the Americas, and pooled procurement mechanisms in Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
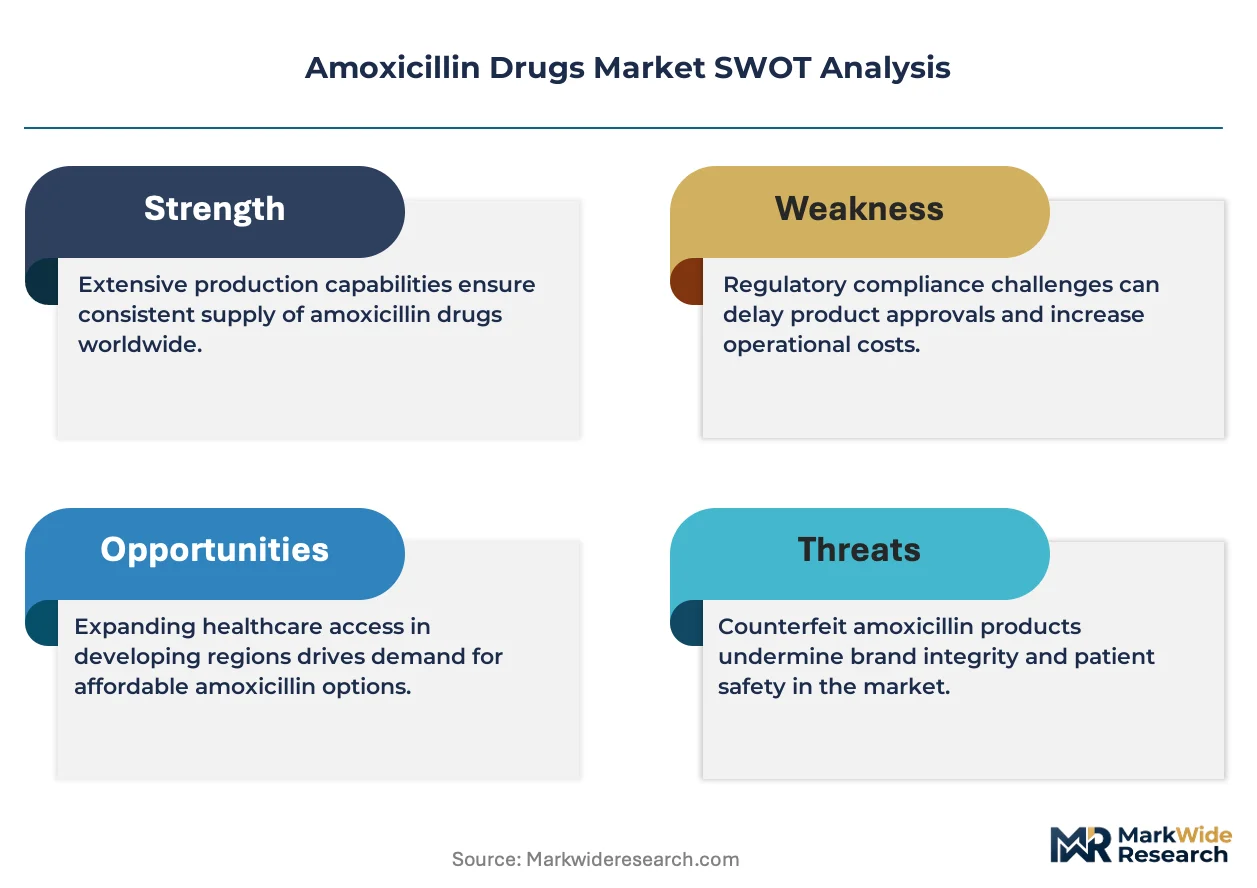
Antimicrobial resistance surveillance mandates are forcing consolidation among API producers lacking stewardship-program capabilities, eliminating marginal players dependent on spot-market sales. Surviving competitors must secure backward integration or captive hospital formulary relationships to sustain margin pools.
For Market Incumbents: Lock in hospital formulary relationships through bundled antimicrobial stewardship compliance services that generic exporters cannot replicate. Secure captive penicillin G fermentation capacity under India's PLI scheme to insulate margin predictability from agricultural commodity price swings. Defend against macrolide substitution in respiratory indications by emphasizing narrow-spectrum therapy protocols in stewardship guidelines.
For New Entrants and Emerging Players: CDSCO stability guidelines in India open a window for pediatric-focused powder-for-oral-suspension formats targeting WHO prequalification pathways. Sub-Saharan African tender markets present the most penetrable geography where pooled procurement mechanisms aggregate volume for qualified manufacturers lacking established hospital relationships. Direct-to-pharmacy distribution models in cash-pay retail channels offer lower competitive intensity than hospital contracting.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated API-to-tablet manufacturers with WHO prequalification status and North American retail pharmacy channel dominance. Long-term viability over the analysis window favors producers with captive fermentation capacity and traceability infrastructure meeting EMA pharmacovigilance obligations. Watch for FDA dissolution specification updates as inflection indicators that could extend ANDA approval timelines and screen out undercapitalized formulation specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Fermentation | Captive penicillin G supply insulates margin predictability from agricultural commodity cycles. |
| WHO Prequalification Pathway Completion | Unlocks pooled procurement access to Sub-Saharan African ministries of health. |
| Antimicrobial Stewardship Program Bundling | Pfizer's hospital formulary relationships defend branded positioning against generic erosion. |
| Direct-to-Pharmacy Distribution Expansion | Bypasses McKesson and Cardinal Health wholesale networks to compress working capital cycles. |
| Pediatric Formulation Stability Investment | CDSCO guidelines and WHO criteria impose standards that screen out non-specialized manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors were cross-referenced against FDA ANDA submissions, EMA pharmacovigilance periodic safety update reports, WHO prequalification databases, and CDSCO manufacturing facility registrations. Bottom-up volume estimates by formulation type and therapy area were reconciled with top-down market sizing derived from import-export flows and tender award disclosures.
Granularity-level modeling addressed dosage form, patient population, regional regulatory cluster, and distribution channel across the projection horizon. CAGRs were derived from segmented growth trajectory analysis incorporating pediatric formulation demand curves, stewardship-program penetration rates, and generic substitution policy impacts. Forecast inputs included India's PLI scheme capacity additions, EMA REACH compliance cost burdens, and macrolide substitution patterns in respiratory indications.
Caveats apply where FDA dissolution specification updates, penicillin G feedstock price volatility, or fermentation process engineering talent scarcity could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory pathway timelines and tender market access conditions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Conjunctivitis Drugs Market