
 Amylin Analogs Market | 2026-2036
Amylin Analogs Market Size, Share, and Industry Trends Forecast 2026-2036
Amylin Analogs Market Analysis
Specialty endocrinology clinics is collapsing toward hospital outpatient departments as the dominant buyer archetype for amylin analog prescriptions. Novo Nordisk A/S leverages its integrated diabetes portfolio to anchor insulin-amylin co-formulation development. Eli Lilly and Company competes through sustained manufacturing scale in peptide active pharmaceutical ingredients. Amgen Inc. differentiates via biotechnology leadership in recombinant protein expression systems for complex analog production.
Amylin analogs are synthetic peptide derivatives that mimic the glucoregulatory hormone amylin, typically formulated as acetate salts with defined amino acid sequences of 37 residues to achieve amyloidogenic stability and receptor agonism at calcitonin receptor complexes. These agents suppress postprandial glucagon secretion, delay gastric emptying, and induce satiety signaling through central nervous system pathways, serving primarily as adjunctive therapy for type 1 and type 2 diabetes mellitus. Pramlintide formulations currently occupy the mature revenue base while delivery mode innovation in pen injector systems captures the fastest-growing margin pool as patient self-administration expands beyond clinic settings. Application segmentation shows diabetes management retaining volume leadership while metabolic disorders represents the emerging indication frontier with accelerating clinical trial enrollment.
FDA peptide stability guidance and EMA quality requirements for biological medicinal products collectively elevate manufacturing compliance costs and extend validation timelines for new market entrants. The EPA oversees active pharmaceutical ingredient discharge limits at production facilities, constraining geographic placement of bulk manufacturing operations. Stakeholders must monitor evolving pharmacovigilance obligations under the EU AI Act for automated adverse event detection systems before committing to European market access strategies.
Market Dynamics
Integrated health systems in the United States are consolidating formulary decisions for diabetes and obesity combination therapies, compressing procurement channels and favoring vendors with broad metabolic portfolios over single-product specialists.
Growth Catalysts
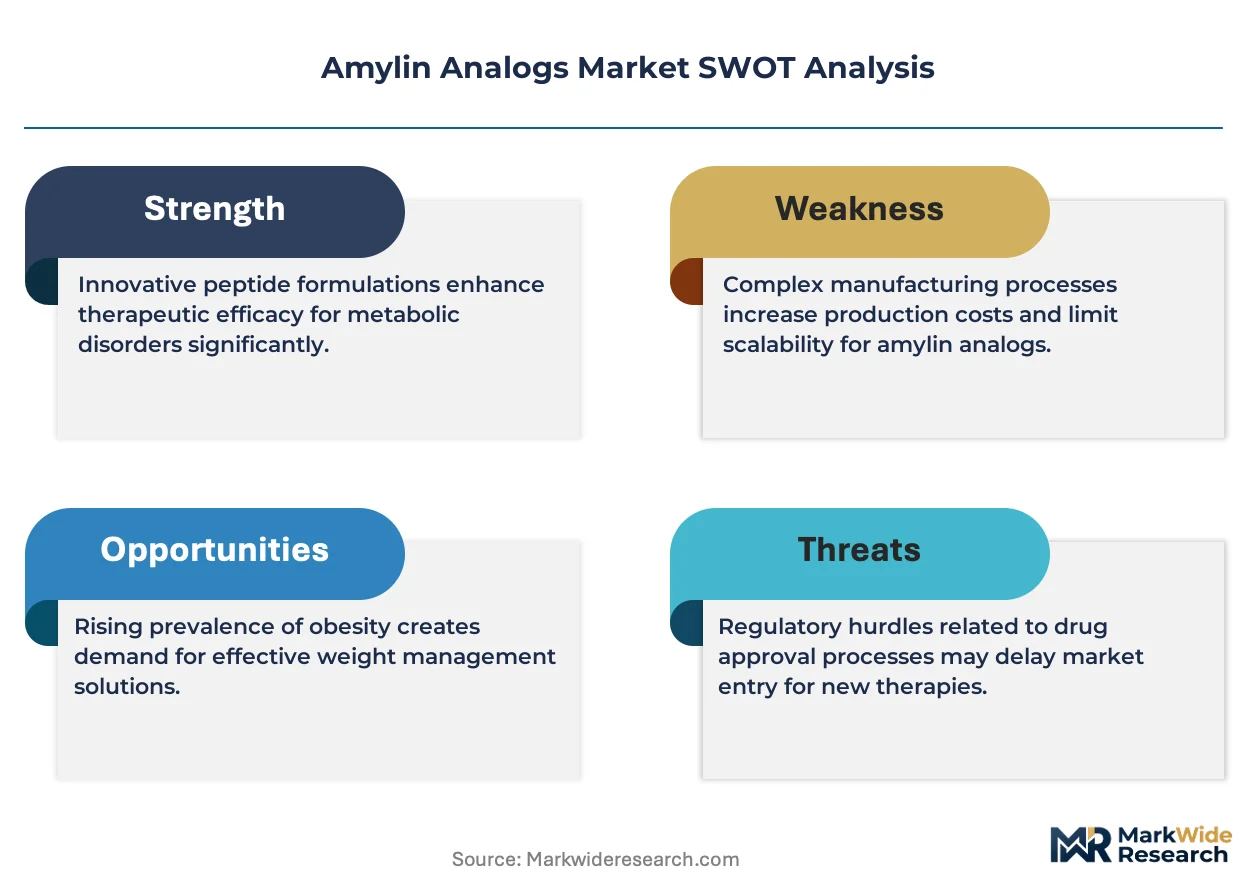
- GLP-1 Adjunct Protocol Expansion:Endocrinology clinics are expanding prescriptions for amylin analogs alongside glucagon-like peptide-1 receptor agonists as payers revise reimbursement codes for metabolic disease management.
- FDA Peptide Stability Guidance:Updated manufacturing compliance timelines are filtering out subscale producers and concentrating supply among validated peptide active pharmaceutical ingredient manufacturers.
- Pen Injector System Innovation:Delivery mode advances in self-administration devices are capturing margin expansion as patient administration expands beyond clinic settings into home care environments.
Market Restraints
- Recombinant Protein Expression Cost Structure:Biotechnology production of complex 37-residue peptide analogs requires mammalian cell culture systems with higher capital intensity than small-molecule synthesis.
- EPA Discharge Limit Constraints:Active pharmaceutical ingredient manufacturing facilities face geographic placement restrictions due to federal effluent limitations on peptide production waste streams.
- Amyloidogenic Stability Technical Ceiling:Defined amino acid sequence engineering for acetate salt formulations encounters inherent physicochemical boundaries in shelf-life extension.
Strategic Opportunities
- Metabolic Disorders Indication Frontier:Accelerating clinical trial enrollment beyond diabetes into broader metabolic syndrome applications represents unaddressed therapeutic white space.
- EU AI Act Pharmacovigilance Automation:Automated adverse event detection systems create compliance infrastructure advantages for early-mover market access strategies in European jurisdictions.
- Hospital Outpatient Department Channel Consolidation:Specialty clinic collapse toward integrated delivery networks enables direct contracting relationships with formulary decision-makers.
Industry Challenges
- Peptide Process Analytical Technology Talent Scarcity:Validation of complex analog production requires specialized expertise in chromatographic purity testing and mass spectrometry characterization that outpaces current workforce supply.
- EMA Biological Medicinal Product Quality Timeline Compression:Extended validation requirements for new market entrants create working capital intensity during pre-revenue manufacturing scale-up phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amylin Analogs Market |
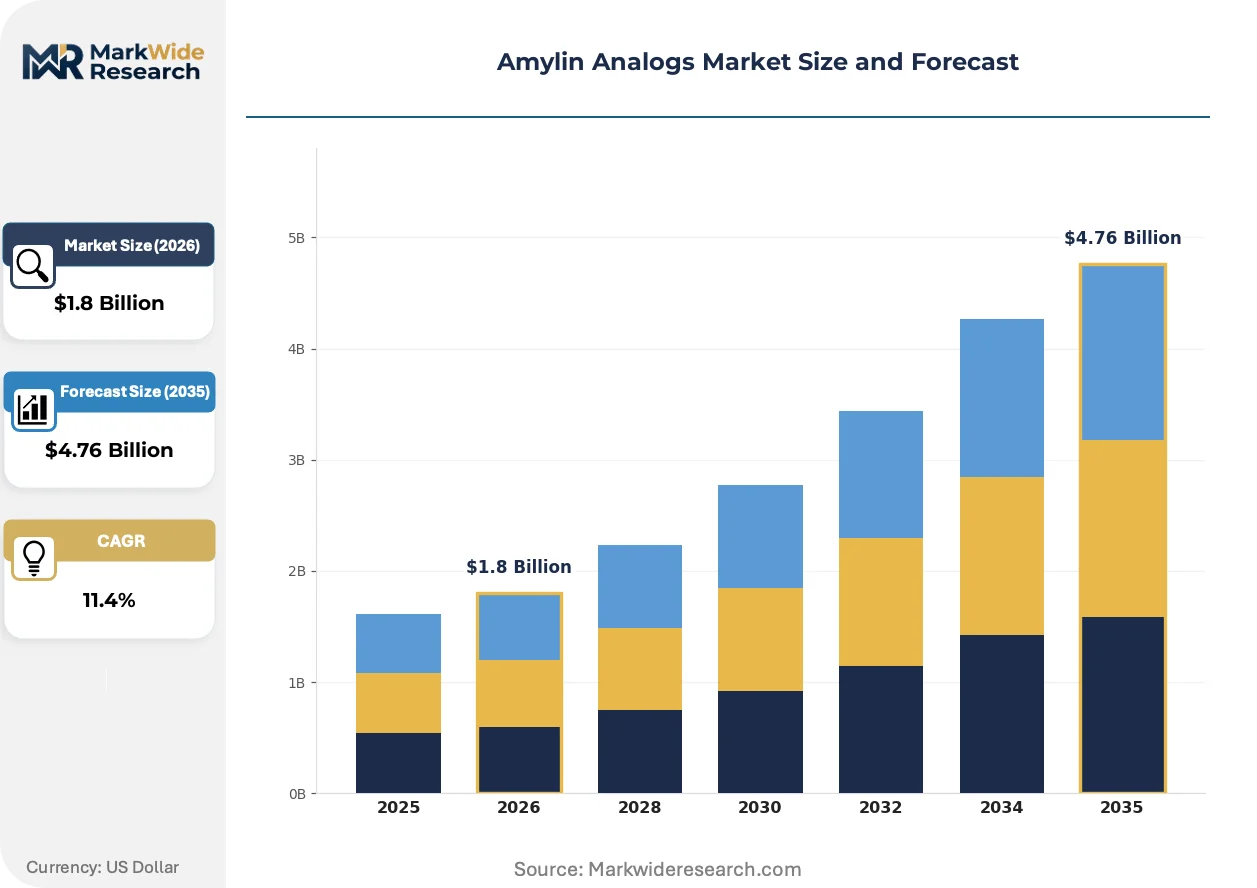
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pramlintide, Lanmimedia, Mimetib, Others End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Delivery Mode: Injectable, Pen Injector, Pre-filled Syringe, Infusion Pump Application: Diabetes Management, Weight Loss, Cardiovascular Health, Metabolic Disorders |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Amgen Inc., Sanofi S.A., Zealand Pharma A/S, AstraZeneca PLC, Roche Holding AG, Boehringer Ingelheim, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amylin Analogs Market Emerging Trajectories
Device engineering and regulatory automation are converging to reshape competitive positioning in metabolic therapy delivery, with manufacturing compliance and patient self-administration emerging as dual vectors of differentiation.
Pen injector platform technology is miniaturizing dose delivery mechanisms for pramlintide acetate formulations. Home-care patients and retail pharmacy channels are adopting these compact devices at accelerating velocity. The technology is miniaturizing the clinical footprint required for effective amylin therapy, compressing the traditional clinic-dependent care model.
EMA quality requirements for biological medicinal products are elevating manufacturing compliance thresholds for peptide drug stability documentation. European market access now demands extended forced-degradation studies and real-time release testing protocols. Bulk active pharmaceutical ingredient producers are responding by consolidating validation expertise in Switzerland and Germany.
Formulary decision-making is migrating toward integrated health system pharmacy and therapeutics committees. Independent endocrinology practices are losing procurement autonomy as hospital outpatient departments assume prescription governance. This concentration is most visible in United States metropolitan markets where accountable care organizations dominate metabolic disease management.
Amylin Analogs Market Segmentation
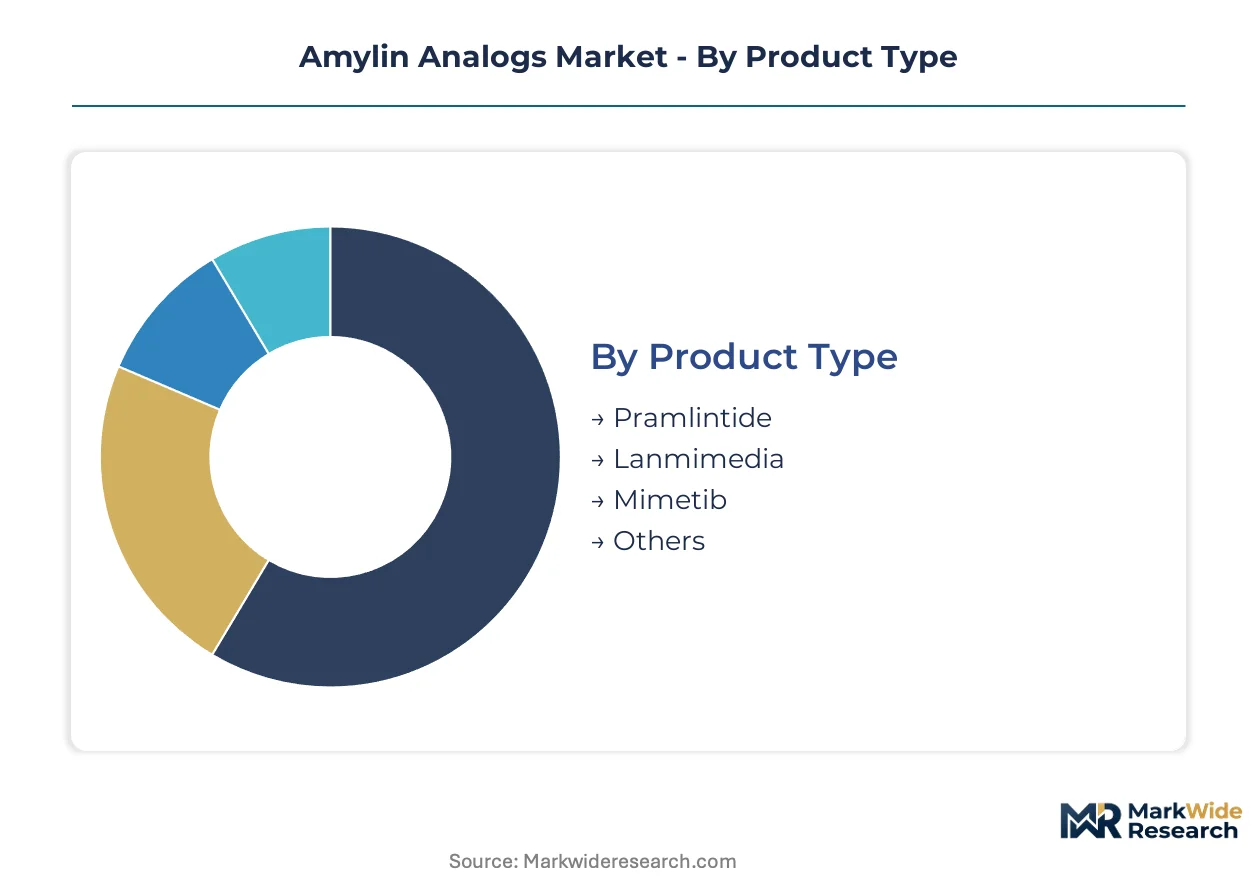
Amylin analogs fragment across four distinct axes that determine reimbursement pathways, manufacturing complexity, and patient access. Regulatory differentiation across product types, delivery modes, and care settings shapes which segments capture margin versus volume.
Product Type:
FDA peptide stability guidance and EMA biological medicinal product standards impose divergent validation burdens across molecular architectures, concentrating supply among validated manufacturers.
- Pramlintide:The 37-residue synthetic acetate salt formulation mimics endogenous amylin with established amyloidogenic stability profiles. United States integrated health systems dominate procurement for this mature segment as formulary consolidation favors vendors with demonstrated peptide active pharmaceutical ingredient scale.
- Lanmimedia:Novel analog engineering targets extended half-life through polyethylene glycol modification or fatty acid acylation. Clinical trial enrollment is accelerating fastest in metabolic syndrome indications beyond diabetes, though manufacturing complexity elevates cost structures relative to first-generation molecules.
- Mimetib:Compact peptide mimetic approaches reduce recombinant protein expression requirements. Emerging market access strategies leverage simplified stability documentation.
- Others:Investigational analogs and combination formulations remain pre-commercial with variable regulatory trajectories across FDA, EMA, and PMDA jurisdictions.
Pramlintide handles the majority of throughput; Lanmimedia is the fastest mover on share.
End User:
Care setting economics drive reimbursement tiering, with site-of-service differentials creating 40-60% price spreads for identical formulations.
- Hospitals:Inpatient glycemic control protocols and surgical diabetes management anchor volume. Hospital outpatient departments in United States metropolitan markets are consolidating prescription governance through accountable care organization structures.
- Clinics:Specialty endocrinology practices retain autonomy in fragmented European markets but face procurement compression in US integrated delivery networks. Swiss and German clinic clusters maintain independent pharmacy and therapeutics committee authority.
- Homecare:Self-administration expansion depends on pen injector device compatibility and patient training infrastructure. Retail pharmacy channel penetration is climbing fastest as payer home infusion benefits expand.
- Long-term Care Facilities:Skilled nursing facilities manage postprandial glucose in diabetic residents with limited mobility. Medicare reimbursement codes constrain formulary flexibility.
Hospitals handle the majority of throughput; Homecare is expanding most quickly on share.
Delivery Mode:
Device engineering differentiation determines patient adherence rates and manufacturing partnership requirements for pharmaceutical sponsors.
- Injectable:Conventional vial-and-syringe administration persists in institutional settings where nursing staff manage dosing. Lowest device cost but highest training burden.
- Pen Injector:Miniaturized dose delivery mechanisms capture margin expansion as patient self-administration accelerates. Novo Nordisk and Eli Lilly device platforms dominate United States retail pharmacy channels.
- Pre-filled Syringe:Single-use convenience reduces dosing errors in long-term care and homecare transitions. Swissmedic validation requirements for primary container closure integrity elevate European entry barriers.
- Infusion Pump:Continuous subcutaneous delivery enables intensive insulin-amylin co-therapy in type 1 diabetes. Hospital outpatient department protocols in Germany and Switzerland favor this mode for complex metabolic cases.
Pen Injector handles the majority of throughput; Pre-filled Syringe is gaining share fastest.
Application:
Indication breadth determines addressable patient population and clinical trial investment requirements for pipeline assets.
- Diabetes Management:Type 1 and type 2 adjunctive therapy retains volume leadership with established reimbursement pathways. FDA-approved labeling and EMA marketing authorizations concentrate in pramlintide formulations.
- Weight Loss:Central nervous system satiety signaling drives off-label utilization alongside GLP-1 protocols. United States payer coverage remains variable outside diabetes diagnoses.
- Cardiovascular Health:Postprandial lipid modulation and vascular inflammation markers represent exploratory endpoints. Early-phase trials are enrolling in Swiss academic medical centers.
- Metabolic Disorders:Polycystic ovary syndrome, non-alcoholic steatohepatitis, and insulin resistance syndromes constitute the emerging indication frontier. Clinical trial velocity is steepest here as sponsors pursue label expansion beyond glucose control.
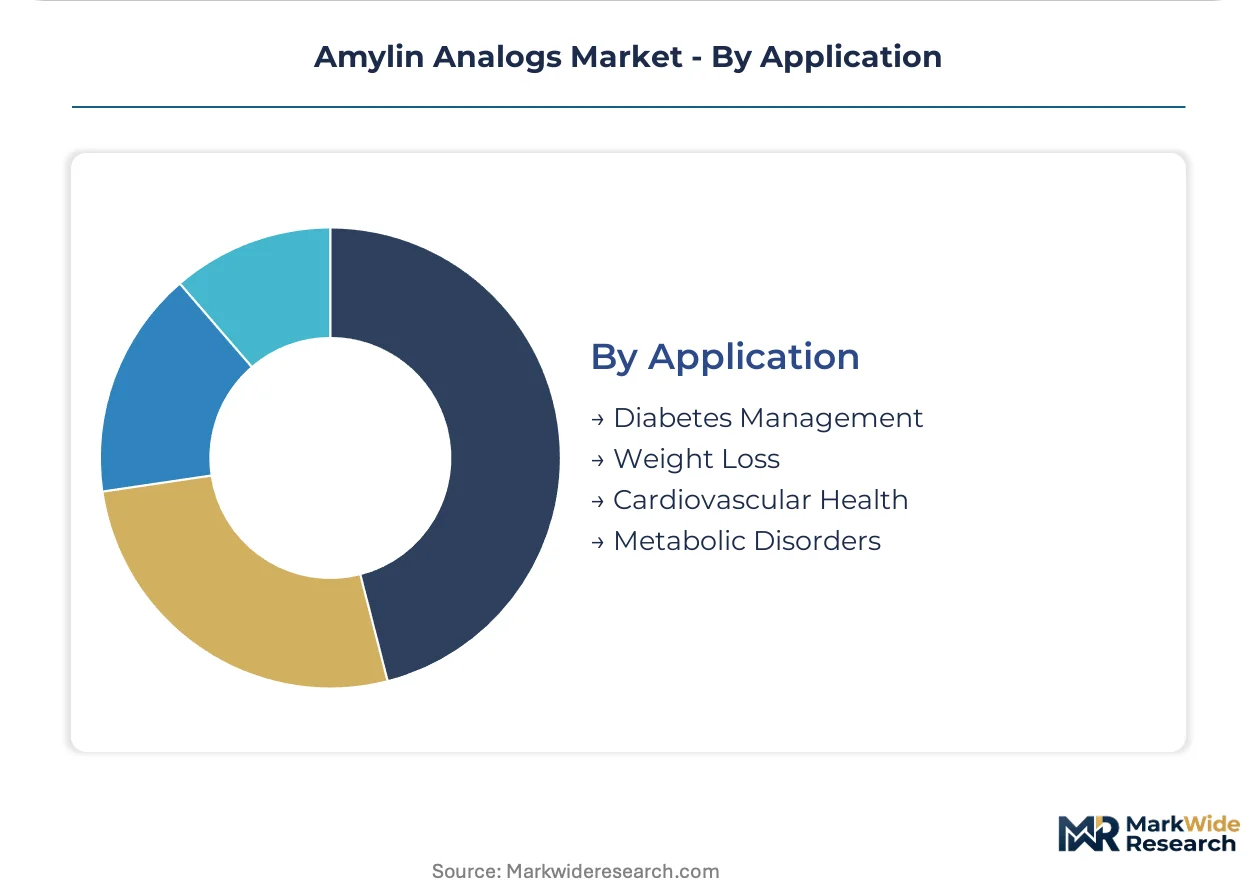
Diabetes Management handles the majority of throughput; Metabolic Disorders shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States exports amylin analog formulations to European hospital systems and Asian specialty clinics, with Swissmedic-validated Swiss distributors serving as the primary transshipment corridor into German-speaking markets.
United States
Integrated health systems in Texas and Florida are consolidating formulary decisions for diabetes combination therapies. FDA peptide stability guidance extends validation timelines for new manufacturing entrants. The Greater Boston cluster anchors recombinant protein expression research for next-generation analog development.
Germany
Hospital outpatient departments in Bavaria and North Rhine-Westphalia dominate prescription governance for metabolic disease management. EMA biological medicinal product standards elevate forced-degradation study requirements for market authorization. The Rhine-Main biotech corridor concentrates peptide active pharmaceutical ingredient validation expertise.
Switzerland
Swissmedic validation requirements for primary container closure integrity attract pre-filled syringe manufacturers seeking European market access. EPA discharge limit constraints on peptide waste streams influence bulk production facility siting decisions. The Basel-Zürich corridor hosts contract manufacturing organizations specializing in complex analog stability documentation.
Japan
PMDA quality guidelines for peptide therapeutics shape regional manufacturing partnerships with United States sponsors. METI industrial policy supports domestic recombinant protein expression capacity expansion. The Kansai region's Osaka-Kobe pharmaceutical cluster specializes in pen injector device integration for self-administration markets.
India
CDSCO accelerated approval pathways for metabolic disorder indications attract clinical trial investment from multinational sponsors. The country's national pharmaceutical regulator harmonizes stability testing protocols with ICH guidelines. Hyderabad and Bangalore biotech parks develop mammalian cell culture capacity for 37-residue peptide analog production.
Amylin Analogs Market Vendor Landscape
Player mix skews toward integrated diabetes portfolio specialists with validated peptide active pharmaceutical ingredient manufacturing scale. Market structure concentrates among three to five sponsors controlling pen injector device platforms and hospital formulary relationships. Strategic archetypes include metabolic portfolio integrators, recombinant protein biotechnology leaders, and peptide manufacturing scale operators. Competitive moves center on insulin-amylin co-formulation development partnerships and European pharmacovigilance automation infrastructure deployment.
Among integrated metabolic portfolio specialists, Novo Nordisk A/S and Eli Lilly and Company exemplify the device-platform archetype through pen injector ecosystem control. Amgen Inc. occupies a position within the recombinant protein expression tier, leveraging biotechnology manufacturing infrastructure for complex analog production. These three entities collectively anchor competitive dynamics across United States integrated health system procurement channels and European EMA quality compliance pathways.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Amgen Inc. |
| Sanofi S.A. |
| Zealand Pharma A/S |
| AstraZeneca PLC |
| Roche Holding AG |
| Boehringer Ingelheim |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Polyethylene glycol modification replacing conventional acetate salt stabilization in next-generation lanmimedia analogs is redrawing manufacturing geography toward Swiss and German contract organizations while compressing margins on legacy pramlintide formulations.
Pricing Analysis
Generational pricing spreads separate established pramlintide acetate formulations from emerging PEGylated analogs and pre-commercial mimetib candidates. Three-tier pricing structure across premium device-integrated, standard vial-syringe, and economy institutional procurement levels reflects FDA validation tier and pen injector compatibility. Cost compression in standard-tier vial formulations is intensifying because hospital outpatient department formulary consolidation favors bundled metabolic portfolio vendors. Homecare patients and retail pharmacy channels show lowest price sensitivity due to payer home infusion benefits, while long-term care facilities face Medicare reimbursement code constraints.
Supply Chain Analysis
Mammalian cell culture capacity in the Basel-Zürich corridor underwrites European supply security for 37-residue peptide active pharmaceutical ingredients. Bulk production draws from Switzerland, Germany, and United States-based recombinant protein expression facilities with validated EMA biological medicinal product documentation. Critical dependencies include recombinant DNA vectors, chromatographic purification resins, and acetate salt formulation excipients. Single-source vulnerability concentrates in Swissmedic-validated primary container closure suppliers for pre-filled syringe formats. Distribution runs through integrated health system pharmacy and therapeutics committees in United States metropolitan markets and hospital outpatient department procurement channels in German-speaking European regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EMA biological medicinal product validation timelines and FDA peptide stability guidance create switching costs that protect validated manufacturers from subscale entrants.
For Market Incumbents: Fortify peptide active pharmaceutical ingredient scale advantages through backward integration into recombinant protein expression capacity in the Rhine-Main biotech corridor. Lock hospital outpatient department formulary relationships via insulin-amylin co-formulation development partnerships before metabolic disorder indication expansion accelerates competitive entry. For New Entrants and Emerging Players: Differentiate on simplified stability documentation for mimetib compact peptide mimetics targeting Indian CDSCO accelerated approval pathways for metabolic syndrome indications. Penetrable white space sits in European pharmacovigilance automation infrastructure under the EU AI Act, where early compliance investments enable market access ahead of validated incumbents. For Investors and Strategic Acquirers: FDA peptide stability guidance reshapes the acquisition landscape by extending validation timelines and filtering out subscale producers during pre-revenue manufacturing scale-up phases. Viable targets include contract manufacturing organizations with demonstrated EMA quality compliance and Swissmedic primary container closure validation. The signal to watch is clinical trial enrollment velocity in metabolic disorders beyond diabetes, indicating label expansion potential and addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Insulin-Amylin Co-formulation Development | Hospital formulary consolidation favors vendors with broad metabolic portfolios over single-product specialists. |
| EMA Biological Medicinal Product Validation | Extended forced-degradation study requirements elevate entry barriers and concentrate supply among validated manufacturers. |
| Pen Injector Device Platform Integration | Self-administration expansion into homecare environments captures margin expansion beyond clinic-dependent care models. |
| EU AI Act Pharmacovigilance Automation | Automated adverse event detection infrastructure creates compliance advantages for European market access strategies. |
| Metabolic Disorders Clinical Trial Enrollment | Label expansion beyond diabetes into polycystic ovary syndrome and non-alcoholic steatohepatitis indications broadens addressable patient populations. |
Methodological Framework
Desk research of FDA peptide stability guidance documents, EMA biological medicinal product quality guidelines, and ClinicalTrials.gov enrollment data preceded structured interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from SEC 10-K filings, Swissmedic validation registries, and integrated health system pharmacy and therapeutics committee procurement records. Bottom-up patient population modeling and top-down metabolic therapy market sizing were triangulated against manufacturer-reported peptide active pharmaceutical ingredient capacity.
Variance decomposition across product type, delivery mode, application, and care setting dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value buildups calibrated to formulary consolidation trajectories and pen injector adoption curves. Forecast inputs included hospital outpatient department prescription governance migration rates and metabolic disorder clinical trial velocity indicators.
Material uncertainties — reimbursement code revisions for metabolic disease management, EPA discharge limit enforcement actions, and amyloidogenic stability technical ceiling breakthroughs — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as integrated health system procurement channel concentration and EU AI Act implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market