
 Netupitant-Palonosetron FDC Market | 2026-2036
Netupitant-Palonosetron FDC Market Size, Share, and Industry Trends Forecast 2026-2036
Netupitant-Palonosetron FDC Market Foresight
Subscription-based patient-support programs is repositioning how antiemetic manufacturers engage oncology practices beyond the pill itself. Helsinn Group leverages its originator expertise to sustain premium positioning across European and Asian markets. Heron Therapeutics anchors its portfolio through extended-release technology leadership in the broader CINV supportive-care space. Eisai Co., Ltd. competes via its established oncology franchise and hospital formulary relationships across Japan.
Netupitant-Palonosetron FDC combines a neurokinin-1 receptor antagonist with a 5-HT3 receptor antagonist in a single oral or injectable formulation, delivering dual-mechanism prophylaxis against acute and delayed chemotherapy-induced nausea and vomiting through synchronized receptor blockade. Oral tablets dominate current prescription volumes due to outpatient chemotherapy expansion, while intravenous administration routes capture the fastest growth as same-day infusion centers prioritize seamless emetic control without oral intake dependencies. The therapy area segmentation shows chemotherapy-induced nausea claims the deepest margin pool, though postoperative nausea applications are widening as surgical protocols adopt multimodal antiemetic strategies.
The FDA's 505(b)(2) pathway shapes U.S. market access timelines for generic entrants, while EMA's centralized oncology product assessments standardize approval benchmarks across EU member states. Japan's PMDA maintains distinct pharmacokinetic bridging requirements that extend development cycles for foreign sponsors seeking market entry. Stakeholders must monitor evolving FDA guidance on bioequivalence standards for fixed-dose neurokinin-1 and 5-HT3 combinations, as this will determine the pace of generic substitution and originator defense strategies.
Market Dynamics
Dual-mechanism antiemetic protocols are restructuring prescribing patterns across oncology practices, with outpatient chemotherapy expansion creating sustained pull for oral fixed-dose combinations that eliminate sequential administration complexity.
Growth Catalysts
- 505(b)(2) Pathway Acceleration:FDA's streamlined approval framework for reformulated combinations compresses development timelines and reduces clinical burden for sponsors targeting the neurokinin-1 and 5-HT3 receptor antagonist class.
- Same-Day Infusion Center Expansion:Oncology clinics in the United States are consolidating chemotherapy administration into ambulatory settings where single-dose prophylaxis reduces nursing time and patient chair occupancy.
- Reimbursement Bundling:CMS oncology care model incentives reward practices that standardize on evidence-based antiemetic protocols, embedding fixed-dose combinations into value-based payment structures.
Market Restraints
- API Supply Concentration:Palonosetron active pharmaceutical ingredient production clusters among three contract manufacturers in India and Italy, exposing formulation sponsors to single-source risk during geopolitical disruptions.
- Generic Substitution Pressure:Off-patent 5-HT3 antagonists and imminent neurokinin-1 receptor antagonist exclusivity expirations enable payer-mandated therapeutic substitution that fragments premium positioning.
- Bridging Study Requirements:Japan's PMDA maintains distinct pharmacokinetic equivalence standards that extend development cycles and inflate registration costs for foreign sponsors seeking market entry.
Strategic Opportunities
- Postoperative Nausea Protocol Adoption:Enhanced recovery after surgery programs in Germany and the United Kingdom are expanding multimodal antiemetic strategies beyond oncology into abdominal and gynecologic surgical settings.
- Injectable-to-Oral Switch Incentives:Payer contracts that reward oral bioequivalent alternatives create white space for sponsors demonstrating non-inferior pharmacokinetics against intravenous comparators.
- Patient Support Program Integration:Subscription-based adherence monitoring and remote nursing support are embedding fixed-dose combinations into longitudinal cancer care relationships that extend beyond the prescription transaction.
Industry Challenges
- Biostatistical Talent Scarcity:Complex bioequivalence study design for fixed-dose neurokinin-1 and 5-HT3 combinations requires specialized pharmacometric expertise that concentrates among a limited pool of contract research organizations.
- Legacy Formulary Entrenchment:Hospital pharmacy and therapeutics committees maintain sequential ondansetron plus aprepitant protocols that resist switching costs despite equivalent clinical outcomes data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netupitant-Palonosetron FDC Market |
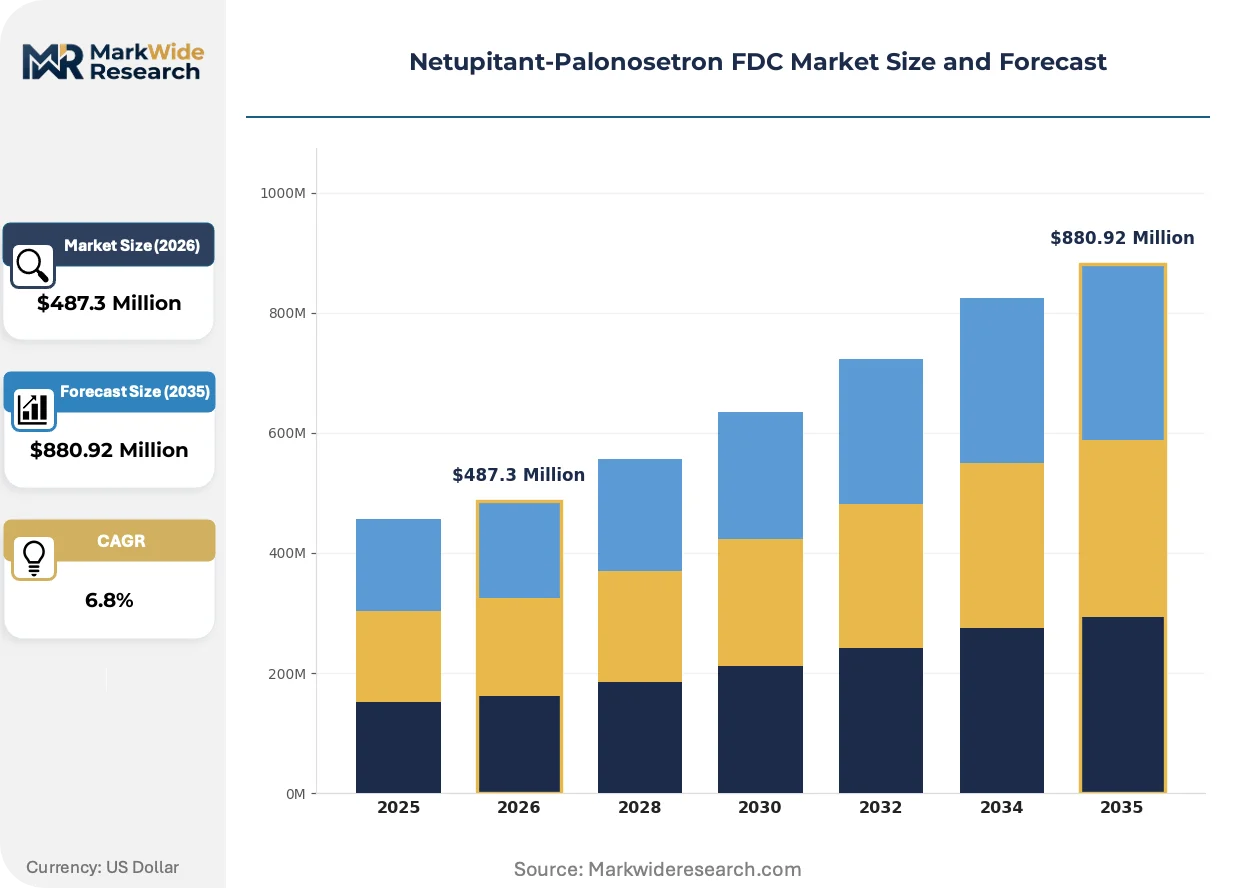
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablets, Injectable Solutions, Combination Therapy, Dose Optimization Therapy Area: Chemotherapy-Induced Nausea, Postoperative Nausea, Radiotherapy-Induced Nausea, Motion Sickness Patient Type: Adult Patients, Pediatric Patients, Geriatric Patients, Pregnant Women Administration Route: Oral Administration, Intravenous Administration, Subcutaneous Injection, Intramuscular Injection |
| Companies Covered | Chugai Pharmaceutical Co., Ltd., Dr. Reddy's Laboratories Ltd., Helsinn Group, Hikma Pharmaceuticals PLC, Aurobindo Pharma Limited, Eisai Co., Ltd., Heron Therapeutics, Inc., Glenmark Pharmaceuticals Limited, Taiho Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netupitant-Palonosetron FDC Market Shifts & Advancements
Antiemetic delivery technology is converging with digital adherence monitoring, while regulatory frameworks recalibrate bioequivalence standards and procurement patterns fragment across institutional versus community oncology settings.
Extended-release injectable depot formulations are overtaking conventional oral tablets in high-volume infusion centers seeking to eliminate patient-dependent intake compliance. Memorial Sloan Kettering Cancer Center and similar tertiary institutions are piloting single-injection prophylaxis that covers the full emetic risk window. This technology is compressing the addressable market for daily oral regimens in metastatic chemotherapy protocols.
EMA's centralized oncology product assessments are harmonizing bioequivalence benchmarks across EU member states, reducing regulatory fragmentation that previously forced redundant national submissions. The industrial consequence is accelerated parallel entry for generic sponsors targeting the European supportive care market. Oncology clinics in France, Spain, and Poland are responding by consolidating procurement through European hospital purchasing alliances that leverage volume across borders.
Hospital formulary committees are unbundling antiemetic selection from chemotherapy protocol templates, creating direct contracting opportunities between manufacturers and individual cancer centers. This disrupts traditional distributor-mediated purchasing that aggregated oncology supportive care into broad therapeutic class contracts. The shift is most visible in the United States, where IDN consolidation has concentrated purchasing power within fifty dominant health systems that negotiate directly with originator and generic sponsors.
Netupitant-Palonosetron FDC Market Segmentation
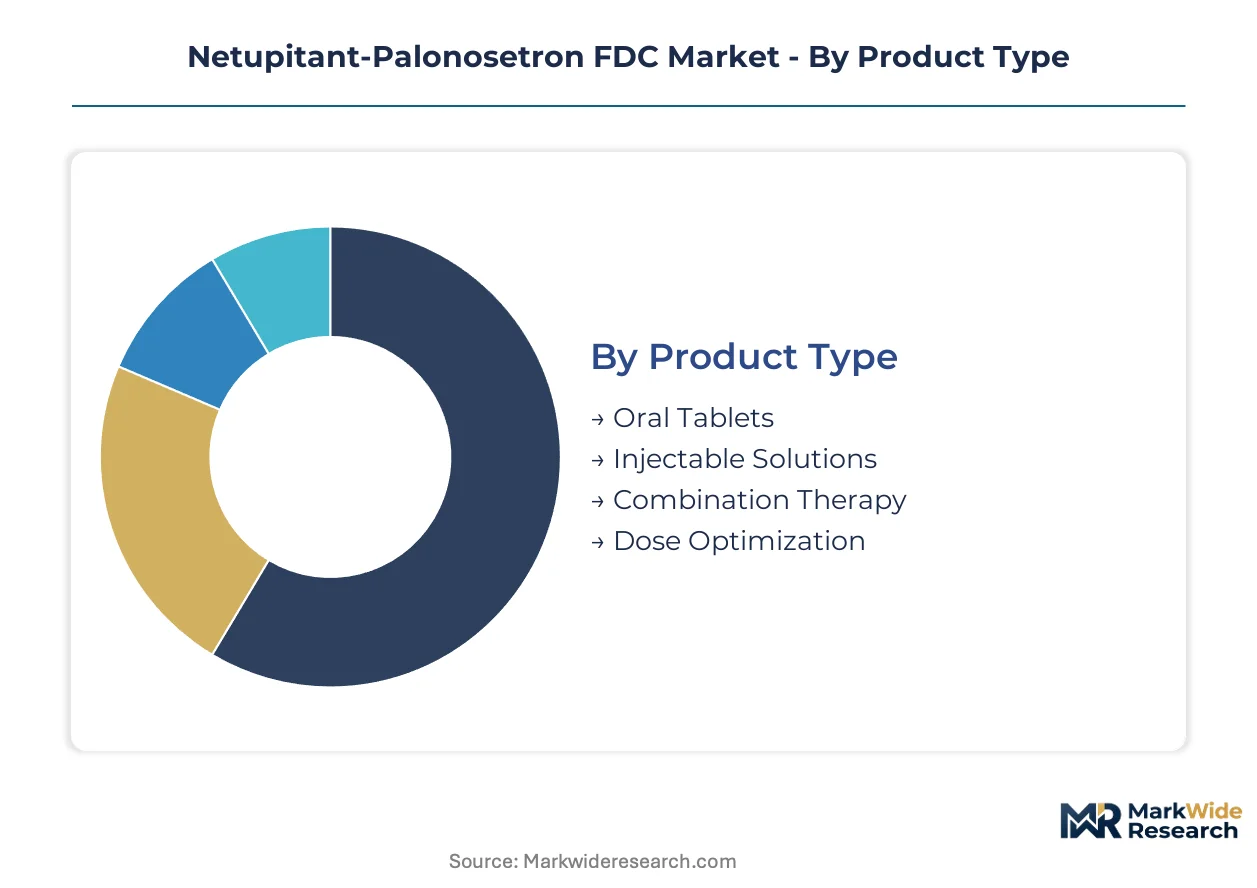
Fixed-dose antiemetic combinations fragment across formulation technologies, patient risk profiles, and care settings that each impose distinct manufacturing and regulatory requirements. Understanding these divides clarifies where sponsors must concentrate formulation expertise versus where commercial partnerships suffice.
Product Type:
Supply concentration clusters among sterile injectable specialists and high-volume oral solid dose contractors, with distinct capacity bottlenecks governing each pathway.
- Oral Tablets:Film-coated bilayer tablets synchronize netupitant and palonosetron release profiles for outpatient chemotherapy protocols. Demand concentrates in United States community oncology practices where same-day dispensing eliminates cold-chain dependencies.
- Injectable Solutions:Ready-to-use vials and prefilled syringes require aseptic manufacturing capabilities that concentrate among European and North American contract development and manufacturing organizations. Germany's infusion center networks are expanding pull for single-dose IV prophylaxis that bypasses oral intake uncertainty.
- Combination Therapy:Co-packaged regimens pairing FDC with corticosteroids address high-emetic-risk protocols.
- Dose Optimization:Titrated formulations for renally or hepatically impaired populations.
Oral tablets absorb the bulk of installed capacity; injectable solutions are expanding most quickly.
Therapy Area:
Margin structure varies sharply across settings, with oncology commanding premium pricing and surgical applications demanding volume-driven cost positions.
- Chemotherapy-Induced Nausea:Acute and delayed emesis prophylaxis in highly and moderately emetogenic regimens. United States academic medical centers anchor demand through standardized supportive care pathways embedded in NCCN guidelines.
- Postoperative Nausea:Multimodal antiemetic protocols in enhanced recovery after surgery programs. United Kingdom NHS trusts and German university hospitals are piloting FDC substitution for sequential ondansetron plus dexamethasone regimens in laparoscopic procedures.
- Radiotherapy-Induced Nausea:Fractionated treatment protocols requiring repeated prophylaxis.
- Motion Sickness:Off-label utilization in specialized occupational settings.
Chemotherapy-induced nausea claims the deepest margin pool; postoperative nausea is climbing the fastest as surgical protocols broaden.
Patient Type:
Regulatory filing strategies diverge across age and physiological status, with pediatric and pregnancy indications requiring dedicated toxicity and teratogenicity programs.
- Adult Patients:The reference population for original FDA and EMA approvals, encompassing broad oncology and surgical indications. Formulary placement in United States Medicare-funded cancer centers sustains baseline prescribing volumes.
- Pediatric Patients:Weight-based dosing requirements and taste-masking considerations for oral formulations. Japan's pediatric drug development incentives are accelerating sponsor investment in age-appropriate pharmacokinetic bridging studies.
- Geriatric Patients:Polypharmacy interaction profiles and renal clearance adjustments.
- Pregnant Women:Hyperemesis gravidarum applications with stringent reproductive toxicity data requirements.
Adult patients retain dominant prescription share; pediatric patients are gaining share fastest as regulatory incentives reshape development priorities.
Administration Route:
Route selection determines distribution infrastructure, with intravenous formulations requiring cold-chain integrity and oral routes enabling retail pharmacy dispensing.
- Oral Administration:Patient-controlled intake enabling home-based chemotherapy regimens. United States specialty pharmacies and mail-order distributors are consolidating procurement for oral oncology supportive care.
- Intravenous Administration:Direct infusion center delivery eliminating bioavailability variability. France's hospital purchasing alliances are standardizing on IV FDC for all moderately emetogenic same-day chemotherapy.
- Subcutaneous Injection:Self-administration potential for select patient populations.
- Intramuscular Injection:Alternative parenteral delivery for patients with venous access limitations.
Oral administration commands the largest addressable patient base; intravenous administration shows the steepest expansion trajectory as infusion center consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing concentrates in India and Italy, while consumption tilts toward the United States, Germany, and Japan where high chemotherapy volumes and favorable reimbursement sustain prescribing. This production-consumption divide shapes cross-border supply dependencies and regulatory bridging requirements.
United States
Community oncology practices and same-day infusion centers anchor demand for oral and injectable formulations. FDA's 505(b)(2) pathway compresses approval timelines for reformulated antiemetic combinations. Memorial Sloan Kettering and other tertiary centers in New York and Boston pilot single-injection depot protocols that reduce nursing burden.
Germany
University hospitals and NHS trusts drive adoption of multimodal antiemetic strategies in enhanced recovery after surgery programs. EMA centralized oncology assessments standardize bioequivalence benchmarks across EU member states. The Rhine-Ruhr and Bavarian hospital purchasing alliances consolidate procurement for IV FDC across moderately emetogenic chemotherapy protocols.
Japan
Eisai's established oncology franchise and hospital formulary relationships sustain domestic prescribing volumes. PMDA maintains distinct pharmacokinetic bridging requirements that extend development cycles for foreign sponsors. Tokyo and Osaka metropolitan cancer centers anchor demand through standardized supportive care pathways.
India
Dr. Reddy's, Aurobindo, and Glenmark anchor API and formulation supply for global markets. CDSCO oversight of fixed-dose combination manufacturing aligns with WHO prequalification standards for export-oriented production. Hyderabad and Mumbai pharmaceutical clusters concentrate sterile injectable and oral solid dose capacity for neurokinin-1 and 5-HT3 antagonist classes.
United Kingdom
NHS trusts pilot FDC substitution for sequential ondansetron plus dexamethasone regimens in laparoscopic surgical settings. MHRA post-Brexit regulatory autonomy enables accelerated assessment of reformulated supportive care products. London and Manchester academic medical centers embed dual-mechanism prophylaxis into standardized chemotherapy pathways.
Netupitant-Palonosetron FDC Market Competitive Landscape
Top-tier vendors anchor originator and first-generic positions, while mid-tier Indian and Japanese manufacturers compete on API supply and regional formulation rights. The vendor base stratifies across originator defense, generic acceleration, and contract manufacturing archetypes. Competitive moves concentrate on portfolio diversification into extended-release injectable formats and strategic partnerships with infusion center networks.
Among originator-tier specialists, Helsinn Group and Heron Therapeutics occupy positions defined by regulatory expertise and technology leadership in extended-release formats. Indian pharmaceutical conglomerates Dr. Reddy's Laboratories and Aurobindo Pharma exemplify the API-to-formulation vertical integration archetype, leveraging domestic manufacturing scale for global supply. Japanese incumbents Chugai Pharmaceutical and Eisai sit within the regional franchise defense tier, anchoring hospital formulary relationships through established oncology portfolios.
| Leading Market Players |
|---|
| Chugai Pharmaceutical Co., Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Helsinn Group |
| Hikma Pharmaceuticals PLC |
| Aurobindo Pharma Limited |
| Eisai Co., Ltd. |
| Heron Therapeutics, Inc. |
| Glenmark Pharmaceuticals Limited |
| Taiho Pharmaceutical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Palonosetron active pharmaceutical ingredient production clusters among contract manufacturers in India and Italy, creating tiered pricing power that flows from API scarcity through finished-dose premiums to hospital procurement negotiations in Germany and the United States.
Pricing Analysis
Price erosion across oral tablet tiers traces to neurokinin-1 receptor antagonist exclusivity expirations enabling payer-mandated therapeutic substitution. Three-tier pricing structure across originator premium, first-generic standard, and multi-source economy levels separates Helsinn's brand defense from Indian API-integrated challengers. Cost compression in the economy tier accelerates because CMS oncology care model incentives reward evidence-based protocol standardization. Community oncology practices in the United States exhibit highest price sensitivity; tertiary academic medical centers anchor demand for premium positioning.
Supply Chain Analysis
API supply for netupitant rests on Italian specialty chemical producers and Indian bulk manufacturing clusters in Hyderabad and Mumbai. Palonosetron synthesis draws from asymmetric catalysis expertise concentrated among three contract manufacturers. Single-source vulnerability during geopolitical disruptions threatens sterile injectable capacity. Distribution runs through European hospital purchasing alliances and United States specialty pharmacy networks consolidating oral oncology supportive care procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic acceleration and infusion center consolidation are compressing viable positioning to sponsors with captive API supply or extended-release technology leadership, forcing originator-dependent challengers toward exit or acquisition.
For Market Incumbents: Anchor formulary defense through backward integration into palonosetron API production and extended-release injectable depot capacity additions in Germany. Payer-mandated therapeutic substitution threatens premium positioning; certification investment in FDA 505(b)(2) bioequivalence standards creates regulatory moats against abbreviated new drug application challengers.
For New Entrants and Emerging Players: Capture white space in postoperative nausea protocols across United Kingdom NHS trusts and German university hospitals piloting multimodal antiemetic substitution. Pediatric bridging studies for Japan's PMDA represent the most penetrable regulatory pathway; partner with established oncology franchise holders for hospital formulary access.
For Investors and Strategic Acquirers: FDA draft guidance on fixed-dose neurokinin-1 and 5-HT3 bioequivalence standards is the leading indicator that generic substitution velocity will accelerate or stall. Five-to-ten year viability favors API-integrated manufacturers with sterile injectable capabilities; watch EMA centralized oncology assessment timelines for European parallel entry signals.
| Strategic Initiative | Industry Significance |
|---|---|
| API Backward Integration | Captive palonosetron supply insulates against Italian and Indian contract manufacturer concentration risk. |
| Extended-Release Depot Development | Single-injection coverage of full emetic risk window displaces daily oral regimens in infusion centers. |
| Pediatric Bridging Study Investment | Japan's PMDA incentives accelerate age-appropriate pharmacokinetic programs for regulatory exclusivity. |
| Hospital Purchasing Alliance Partnership | Direct contracting with Rhine-Ruhr and Bavarian alliances bypasses distributor-mediated aggregation. |
| Postoperative Nausea Protocol Expansion | Enhanced recovery after surgery programs in Germany and United Kingdom widen addressable surgical market. |
Research Methodology
Multi-period observation of FDA 505(b)(2) approval timelines, EMA centralized oncology assessments, and PMDA pharmacokinetic bridging requirements anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA Orange Book filings, EMA EPAR assessments, ClinicalTrials.gov protocol registries, and formulary database snapshots. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue disclosures.
Segment-weighted projections applied formulation-specific growth rates across oral tablets, injectable solutions, and extended-release depot technologies, further disaggregated by chemotherapy-induced nausea, postoperative nausea, and radiotherapy-induced nausea therapy areas. Patient type stratification incorporated adult, pediatric, and geriatric population pharmacokinetic considerations. CAGRs derived from regression-adjusted historic prescription trajectories, with infusion center expansion rates and CMS reimbursement policy shifts as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA bioequivalence guidance finalization and neurokinin-1 receptor antagonist patent cliff sequencing. Forecasts reflect documented assumptions regarding same-day infusion center buildout velocity and European hospital purchasing alliance procurement consolidation. API supply disruption, generic substitution acceleration, and pediatric regulatory incentive expiration constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market