
 Disease-Modifying Agents Market | 2026-2036
Disease-Modifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Disease-Modifying Agents Market Analysis
Specialty clinics is bifurcating from hospital infusion centers as the preferred administration setting for parenteral disease-modifying agents. Biogen Inc. anchors its position through deep manufacturing scale in recombinant protein production. Pfizer Inc. competes across both small molecule and biologic modalities with broad regulatory dossiers. F. Hoffmann-La Roche Ltd. dominates the monoclonal antibody segment with established intravenous infrastructure.
Disease-modifying agents comprise pharmacologically active compounds designed to alter underlying disease pathophysiology rather than merely suppressing symptoms, typically requiring molecular weights ranging from small molecules under 900 Daltons to biologics exceeding 150 kilodaltons and manufactured through either chemical synthesis or mammalian cell culture systems. Their primary commercial purpose centers on slowing or halting structural damage in progressive autoimmune and neurodegenerative conditions. Monoclonal antibodies command the largest revenue pool due to premium pricing and chronic administration schedules, while small molecules attract development investment for oral bioavailability and patient convenience. The rheumatoid arthritis therapy area remains the most mature indication with established biosimilar competition, whereas multiple sclerosis shows concentrated demand for novel mechanisms with improved safety profiles.
FDA's Breakthrough Therapy designation and EMA's PRIME scheme compress regulatory review timelines and reshape portfolio prioritization for developers. The FDA, EMA, and WHO prequalification standards collectively determine manufacturing compliance burdens and market access sequencing across jurisdictions. Stakeholders must monitor evolving biosimilar interchangeability policies and their cascading effects on formulary positioning and rebate negotiations.
Market Dynamics
The FDA's accelerated approval pathway compresses development timelines for breakthrough disease-modifying therapies, forcing incumbents to recalibrate portfolio prioritization against faster-moving entrants while site-of-care migration toward specialty clinics reshapes distribution economics.
Growth Catalysts
- Medicare reimbursement frameworks:The United States Medicare prior authorization structure for biologic agents creates predictable demand pools that anchor manufacturer investment in chronic autoimmune indications.
- Specialty clinic infrastructure:Outpatient infusion centers in Florida, Texas, and California are capturing parenteral administration volumes previously concentrated in hospital-based settings.
- Monoclonal antibody manufacturing scale:Mammalian cell culture capacity expansion in Singapore and Ireland is reducing production bottlenecks for high-molecular-weight biologics.
Market Restraints
- Biosimilar interchangeability uncertainty:The FDA's evolving standards for automatic substitution create formulary positioning friction that delays payer adoption of follow-on biologics.
- Recombinant protein input concentration:Single-source dependence on Chinese hamster ovary cell lines and fetal bovine serum suppliers concentrates supply risk in mammalian production systems.
- Small molecule patent cliffs:Expiring composition-of-matter protections for oral disease-modifying agents in rheumatoid arthritis expose originators to rapid price erosion.
Strategic Opportunities
- Neurodegenerative underpenetration:Multiple sclerosis and Alzheimer's disease segments in Germany and Japan show substantial unmet need for novel mechanisms with improved safety profiles.
- EMA PRIME scheme leverage:Priority medicines designation offers accelerated assessment timelines that compress competitive entry windows for European market access.
- Subcutaneous formulation convergence:Combination of auto-injector devices with monoclonal antibody engineering enables self-administration that displaces infusion center dependency.
Industry Challenges
- Bioprocess engineering talent scarcity:Cell culture optimization and continuous manufacturing expertise remains concentrated among a limited pool of specialists in Boston and Basel.
- Good Manufacturing Practice certification timelines:EMA and FDA pre-approval inspections for new biologic facilities routinely extend 18-24 months beyond construction completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disease-Modifying Agents Market |
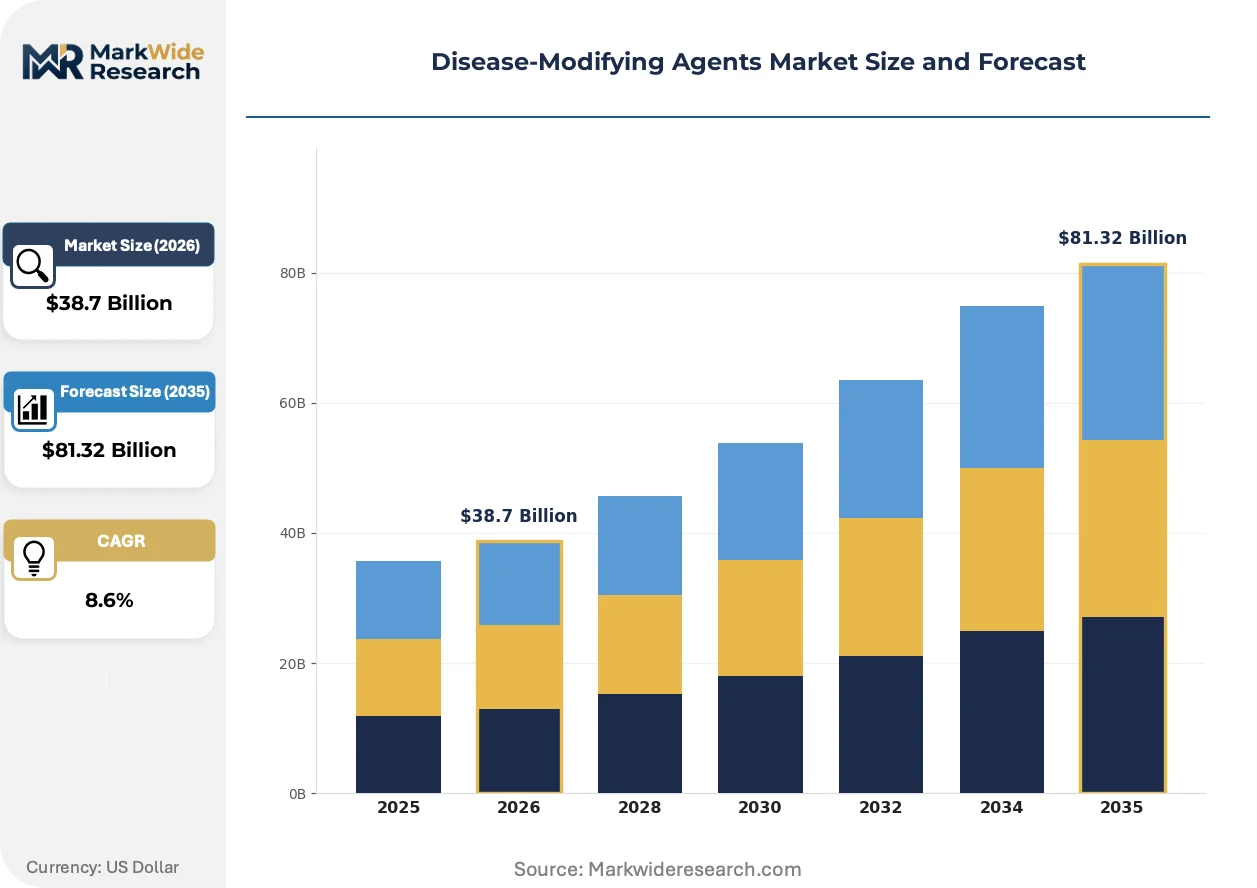
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Recombinant Proteins, Biologics Therapy Area: Rheumatoid Arthritis, Multiple Sclerosis, Crohn's Disease, Psoriasis Delivery Method: Intravenous, Subcutaneous, Oral, Intra-articular End User: Hospitals, Specialty Clinics, Home Healthcare, Research Institutions |
| Companies Covered | Biogen Inc., Pfizer Inc., F. Hoffmann-La Roche Ltd., Novartis AG, Sanofi, Teva Pharmaceutical Industries Ltd., AbbVie Inc., Merck KGaA, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disease-Modifying Agents Market Emerging Trajectories
Biologic delivery systems are undergoing fundamental redesign as patient convenience demands and site-of-care economics converge, compressing the viable window for intravenous-only formulations.
Subcutaneous monoclonal antibody formulations are miniaturizing administration burden for chronic autoimmune patients. Rheumatology practices in the United States are adopting these alternatives at accelerating pace to reduce chair time and staffing costs. The technology is miniaturizing the infrastructure required for biologic delivery, enabling smaller clinic footprints and home-based administration models that displace traditional infusion center economics.
EMA's PRIME scheme and FDA's Breakthrough Therapy designation are compressing regulatory review timelines for novel mechanisms. Developers are prioritizing portfolios around these accelerated pathways to capture first-mover positioning in competitive indications. Multiple sclerosis therapies with improved safety profiles are most affected, with sponsors front-loading investment in European Medicines Agency rapporteur engagement to secure priority status.
Specialty pharmacy distribution is consolidating purchasing influence as prior authorization complexity drives consolidation among dispensing channels. Large specialty pharmacies are capturing biologic dispensing volumes previously fragmented across hospital outpatient pharmacies and independent infusion centers. This concentration is most visible in United States Medicare Part B reimbursement zones where vertical integration between payers and pharmacies accelerates channel control.
Disease-Modifying Agents Market Segmentation
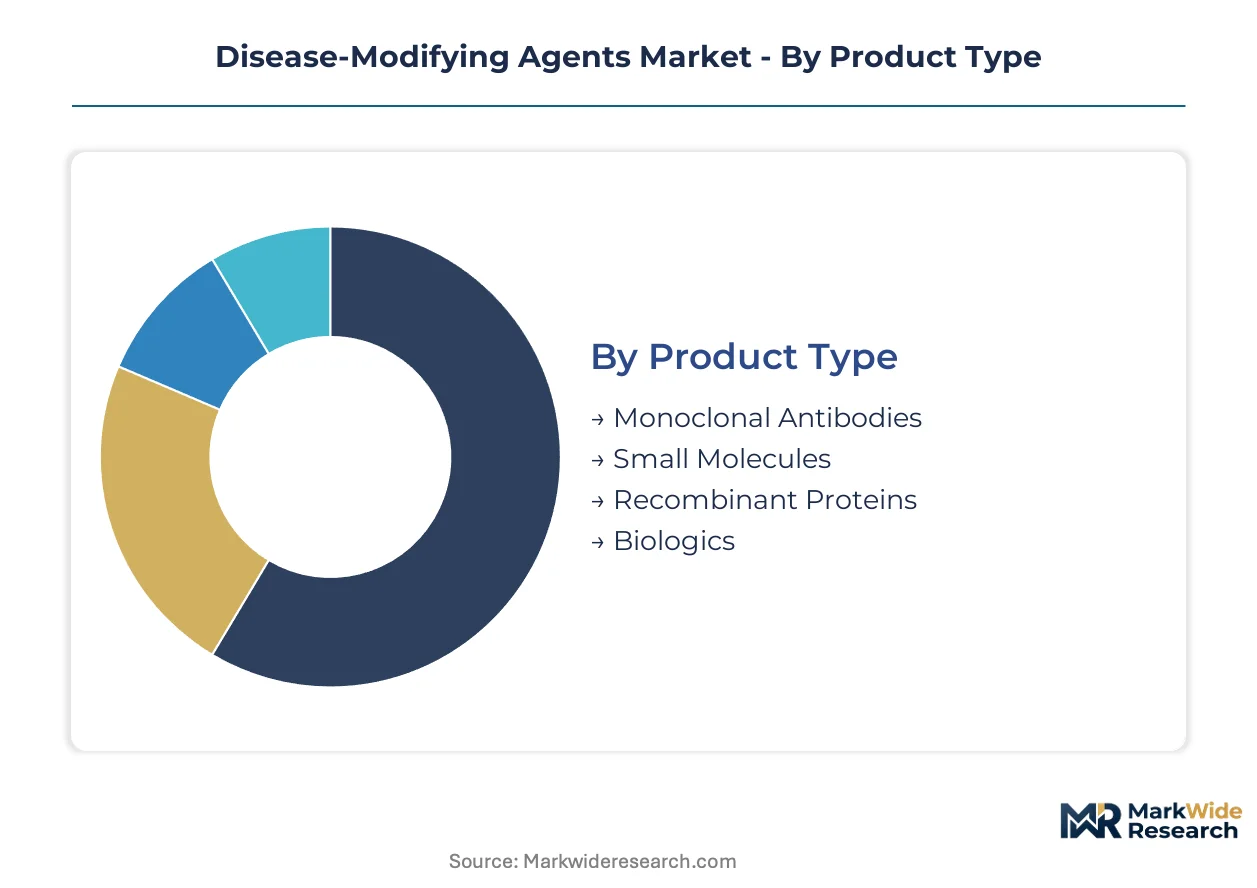
Disease-modifying agents fragment across molecular class, clinical indication, and administration setting. Each dimension carries distinct reimbursement logic and competitive substitution dynamics that reshape portfolio prioritization for developers.
Product Type:
Monoclonal antibodies face the most acute substitution pressure from biosimilars and next-generation small molecules, forcing incumbents to defend through formulation innovation and manufacturing scale.
- Monoclonal Antibodies:High-molecular-weight immunoglobulins engineered for target specificity in autoimmune and oncologic indications. Demand concentrates in United States Medicare Part B reimbursement zones where infusion center economics favor chronic administration schedules. Pricing power erodes as FDA biosimilar interchangeability standards mature.
- Small Molecules:Synthetic compounds under 900 Daltons with oral bioavailability and established generic substitution pathways. Rheumatoid arthritis prescriptions in Germany and Japan show accelerating preference for convenience over parenteral alternatives. Patent cliffs in key molecules expose revenue streams to rapid erosion.
- Recombinant Proteins:Therapeutic proteins manufactured through microbial or mammalian expression systems.
- Biologics:Broad category encompassing cellular and tissue-derived products with complex manufacturing requirements.
Monoclonal antibodies anchor the volume base while small molecules gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates mature indications with biosimilar saturation from premium-priced novel mechanisms in underpenetrated neurodegenerative segments.
- Rheumatoid Arthritis:The most commercially mature autoimmune indication with established TNF-alpha inhibitor biosimilar competition. United States commercial payers and Medicare Advantage plans drive aggressive formulary positioning battles. Originators defend through Janus kinase inhibitor switching and combination protocols.
- Multiple Sclerosis:Progressive neurodegenerative indication with concentrated demand for sphingosine-1-phosphate modulators and anti-CD20 monoclonal antibodies. EMA PRIME scheme engagement accelerates European market access for novel mechanisms with improved safety profiles. Pricing remains elevated due to limited therapeutic alternatives.
- Crohn's Disease:Inflammatory bowel indication with biologic penetration still expanding beyond anti-TNF first-line therapy.
- Psoriasis:Dermatologic autoimmune indication with strong IL-17 and IL-23 inhibitor uptake in United States specialty clinic settings.
Rheumatoid arthritis anchors the volume base while multiple sclerosis climbs the fastest on novel mechanism adoption.
Delivery Method:
Patient convenience preferences and site-of-care economics are displacing intravenous-only formulations across chronic indications.
- Intravenous:Hospital and infusion center administration requiring clinical infrastructure and staffing. United States hospital outpatient departments retain volume in oncology and acute autoimmune flares where monitoring protocols mandate supervised delivery. Chair time costs and staffing shortages accelerate migration to alternatives.
- Subcutaneous:Auto-injector and prefilled syringe formats enabling self-administration or rapid clinic throughput. Rheumatology practices in Florida and Texas adopt these alternatives to reduce facility overhead and expand patient capacity. Engineering advances in monoclonal antibody concentration enable high-dose subcutaneous delivery previously requiring intravenous infusion.
- Oral:Small molecule and peptide formulations maximizing patient adherence and pharmacy dispensing efficiency.
- Intra-articular:Direct joint injection for localized inflammatory control in monoarticular presentations.
Intravenous administration anchors the volume base while subcutaneous delivery expands most quickly on convenience and cost advantages.
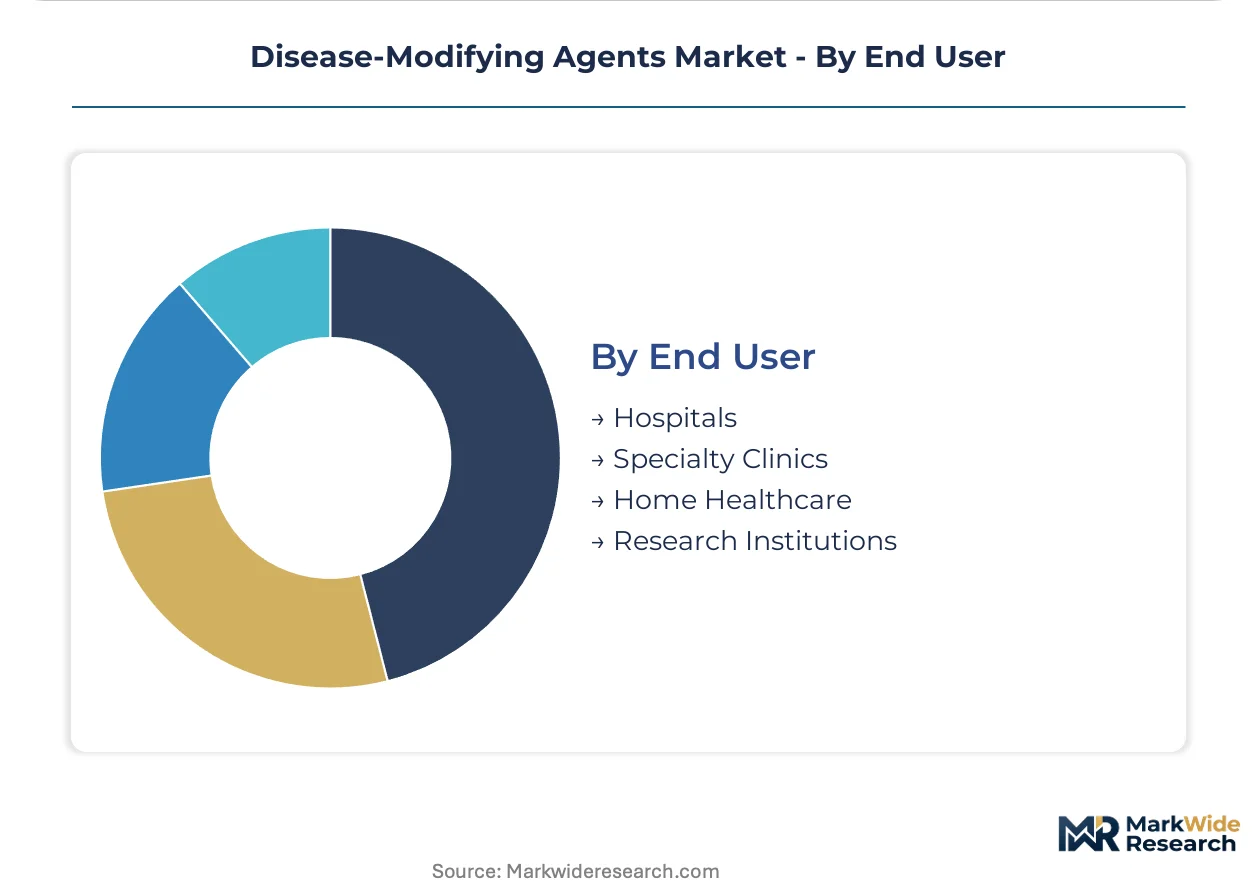
End User:
Customer type concentration reflects prior authorization complexity and reimbursement channel control across United States healthcare financing structures.
- Specialty Clinics:Outpatient infusion and injection centers capturing parenteral biologic administration from hospital-based settings. United States Medicare reimbursement differentials and vertical payer-pharmacy integration accelerate channel consolidation in Florida, Texas, and California markets. Smaller clinic footprints and focused staffing models reduce per-dose delivery costs.
- Hospitals:Acute care and outpatient departments retaining complex induction protocols and comorbid patient populations. United States 340B drug pricing program participation influences biologic purchasing patterns for eligible institutions. Emergency department and inpatient consultation volumes sustain hospital-based infusion for acute presentations.
- Home Healthcare:Self-administration and visiting nurse models for stable chronic patients with established therapy tolerance.
- Research Institutions:Academic medical centers conducting investigator-initiated trials and early-phase clinical development.
Hospitals anchor the volume base while specialty clinics gain share at the steepest rate on site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biogen Inc. ships monoclonal antibody formulations from Massachusetts to German rheumatology clinics. Singapore's CHO cell culture facilities export recombinant protein intermediates to Japanese multiple sclerosis centers. Ireland's biologics manufacturing plants supply subcutaneous auto-injector formulations to United Kingdom specialty pharmacies.
United States
Medicare Part B reimbursement differentials and prior authorization complexity concentrate biologic prescribing in Florida, Texas, and California specialty clinics. FDA's Breakthrough Therapy designation compresses review timelines for novel mechanisms in multiple sclerosis. Boston's biotech corridor anchors mammalian cell culture optimization expertise for monoclonal antibody production.
Germany
Rheumatoid arthritis patients in Bavaria and North Rhine-Westphalia show accelerating preference for oral small molecules over parenteral alternatives. EMA's PRIME scheme accelerates assessment timelines for developers targeting neurodegenerative indications. Frankfurt's pharmaceutical distribution hubs consolidate biologic dispensing volumes for Central European markets.
Japan
Multiple sclerosis and Alzheimer's disease segments demonstrate substantial unmet need for novel mechanisms with improved safety profiles. PMDA's Sakigake designation system mirrors FDA accelerated pathways for priority review. Tokyo-Osaka corridor hosts concentrated specialist neurology practices driving demand for next-generation monoclonal antibodies.
United Kingdom
NHS England's specialized commissioning frameworks create predictable demand pools for high-cost biologic agents in autoimmune indications. MHRA's post-Brexit regulatory autonomy enables divergence from EMA timelines for national priority therapies. London's academic medical centers retain investigator-initiated trial volumes for early-phase disease-modifying development.
Switzerland
Basel's pharmaceutical manufacturing cluster concentrates recombinant protein production expertise for global biologic supply. Swissmedic maintains alignment with EMA standards while offering streamlined national access pathways. The country's private reimbursement frameworks sustain premium pricing for novel monoclonal antibody formulations.
Disease-Modifying Agents Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and regulatory dossier breadth. The vendor base concentrates among integrated pharmaceutical conglomerates with mammalian cell culture infrastructure and established intravenous infusion center relationships. Three archetypes dominate: biologic manufacturing specialists with deep CHO platform expertise, diversified conglomerates spanning small molecule and large molecule modalities, and neurology-focused developers with concentrated multiple sclerosis portfolios. Competitive moves center on subcutaneous formulation engineering to displace infusion dependency and EMA rapporteur engagement to secure PRIME designation.
Among the biologic manufacturing specialists, Biogen Inc. exemplifies deep platform concentration in recombinant protein production. Pfizer Inc. occupies a diversified position across both chemical synthesis and mammalian cell culture systems. F. Hoffmann-La Roche Ltd. anchors the monoclonal antibody segment with established intravenous infrastructure and auto-injector device integration.
| Leading Market Players |
|---|
| Biogen Inc. |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Merck KGaA |
| Amgen Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between monoclonal antibody manufacturers and United States specialty pharmacy networks lock in both supply access and price visibility across multi-year horizons. These contracts insulate biologic producers from spot-market volatility while embedding volume commitments that stabilize manufacturing capacity utilization.
Pricing Analysis
Next-generation subcutaneous auto-injector formulations command 15-25% premiums over intravenous alternatives in United States Medicare Part B zones. Three-tier pricing structure across premium novel mechanisms, standard-of-care biologics, and economy-tier biosimilars stratifies the rheumatoid arthritis segment. Cost compression in the TNF-alpha inhibitor class intensifies as FDA interchangeability standards mature and payer rebate negotiations escalate. Rheumatology practices in Florida and Texas show highest price sensitivity, while academic medical centers retain lowest sensitivity due to 340B drug pricing program participation.
Supply Chain Analysis
Singapore and Ireland anchor mammalian cell culture production for high-molecular-weight biologics, while Massachusetts and Basel concentrate recombinant protein optimization expertise. Chinese hamster ovary cell lines and fetal bovine serum feed upstream bioprocessing, with single-source dependence creating vulnerability to agricultural disease outbreaks. Tariff exposure on cold-chain logistics equipment concentrates risk in trans-Atlantic distribution lanes. Distribution runs through vertically integrated specialty pharmacy networks that consolidate prior authorization processing and patient hub services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Disease-Modifying Agents Market functions as a defensive-moat industry where regulatory entrenchment creates durable competitive advantages. FDA Breakthrough Therapy and EMA PRIME designations embed multi-year lead times that protect first-mover returns.
For Market Incumbents: Fortify manufacturing scale in Singapore and Ireland to capture subcutaneous formulation demand migrating from infusion centers. Deepen backward integration into CHO cell line development to reduce single-source serum dependence. Prioritize EMA rapporteur engagement for PRIME designation in multiple sclerosis novel mechanisms. For New Entrants and Emerging Players: Anchor in Japanese and German neurodegenerative segments where unmet need for improved safety profiles exceeds biosimilar saturation. Target oral small molecule development in rheumatoid arthritis as patient convenience preferences displace parenteral volumes. Pursue licensing agreements with established auto-injector device manufacturers to compress formulation engineering timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-specialist acquisitions over diversified conglomerates. Five-to-ten year viability hinges on subcutaneous delivery convergence and biosimilar interchangeability resolution. Signal to monitor: FDA publication of final interchangeability guidance for monoclonal antibody follow-ons.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Engineering | Auto-injector integration with high-concentration monoclonal antibodies displaces infusion center dependency in United States rheumatology practices. |
| EMA PRIME Scheme Engagement | Priority medicines designation compresses European market access timelines for novel mechanisms in multiple sclerosis. |
| CHO Cell Line Optimization | Proprietary mammalian expression systems reduce fetal bovine serum dependence and stabilize recombinant protein yields. |
| Specialty Pharmacy Vertical Integration | Payer-owned dispensing channels capture Medicare Part B reimbursement flows and consolidate prior authorization processing. |
| Biosimilar Interchangeability Investment | FDA substitution standards determine formulary positioning and rebate negotiation leverage for follow-on biologics. |
Methodological Framework
The analysis maps monoclonal antibody, small molecule, and recombinant protein sub-sectors, each validated through drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Primary interview insights triangulate against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare formulary databases. Bottom-up patient-flow modeling and top-down manufacturer revenue reconciliation ensure cross-validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include molecular class, therapy area, administration route, and regional regulatory cluster. CAGRs derive from patient population epidemiology, treatment penetration curves, and pricing elasticity assumptions. Forecast inputs incorporate biosimilar launch sequencing and site-of-care migration velocity.
Decision-makers should treat outputs as directional under stable Medicare reimbursement and EMA regulatory alignment assumptions; material deviation would warrant model refresh. Specific risk factors include FDA interchangeability policy shifts, CHO cell line supply disruptions, and specialty pharmacy channel consolidation. Recalibration cycles align with material shifts in payer prior authorization frameworks and biosimilar approval milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Kidney Cancer Drugs Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Demerol (Meperidine) Market