
 Trisenox Market | 2026-2036
Trisenox Market Size, Share, and Industry Trends Forecast 2026-2036
Trisenox Market Analytics
Modular vial-to-infusion configurations is shifting procurement patterns across hospital systems, letting buyers unbundle sterile preparation from administration. Teva Pharmaceutical Industries Ltd. leverages its generic injectables infrastructure to sustain cost-competitive supply chains. Fresenius Kabi anchors hospital channel access through integrated compounding and distribution networks. Cell Therapeutics competes on specialized oncology positioning with concentrated hematology sales forces.
Trisenox is an arsenic trioxide injectable formulation, typically supplied as a concentrated solution requiring dilution prior to intravenous administration, with established use in inducing remission in acute promyelocytic leukemia. The drug functions by promoting differentiation and apoptosis in malignant promyelocytes, making it a targeted therapy within hematologic oncology protocols. Oncology applications dominate current utilization, while clinical research segments represent the fastest-growing demand pool as investigators explore expanded indications. Hospital pharmacies command the primary distribution channel, though specialty pharmacies are capturing margin from outpatient administration shifts.
FDA orphan drug designations and GMP manufacturing standards govern product approval, batch release, and facility inspection requirements for Trisenox manufacturers. The EPA regulates arsenic compound handling, waste disposal, and occupational exposure limits throughout the production chain. Stakeholders must monitor regulatory alignment between environmental compliance and pharmaceutical manufacturing standards as supply networks expand.
Market Dynamics
Modular vial-to-infusion configurations are compressing procurement cycles across hospital pharmacy networks, unbundling sterile compounding from bedside administration and forcing suppliers to compete on discrete service tiers rather than bundled packages.
Growth Catalysts
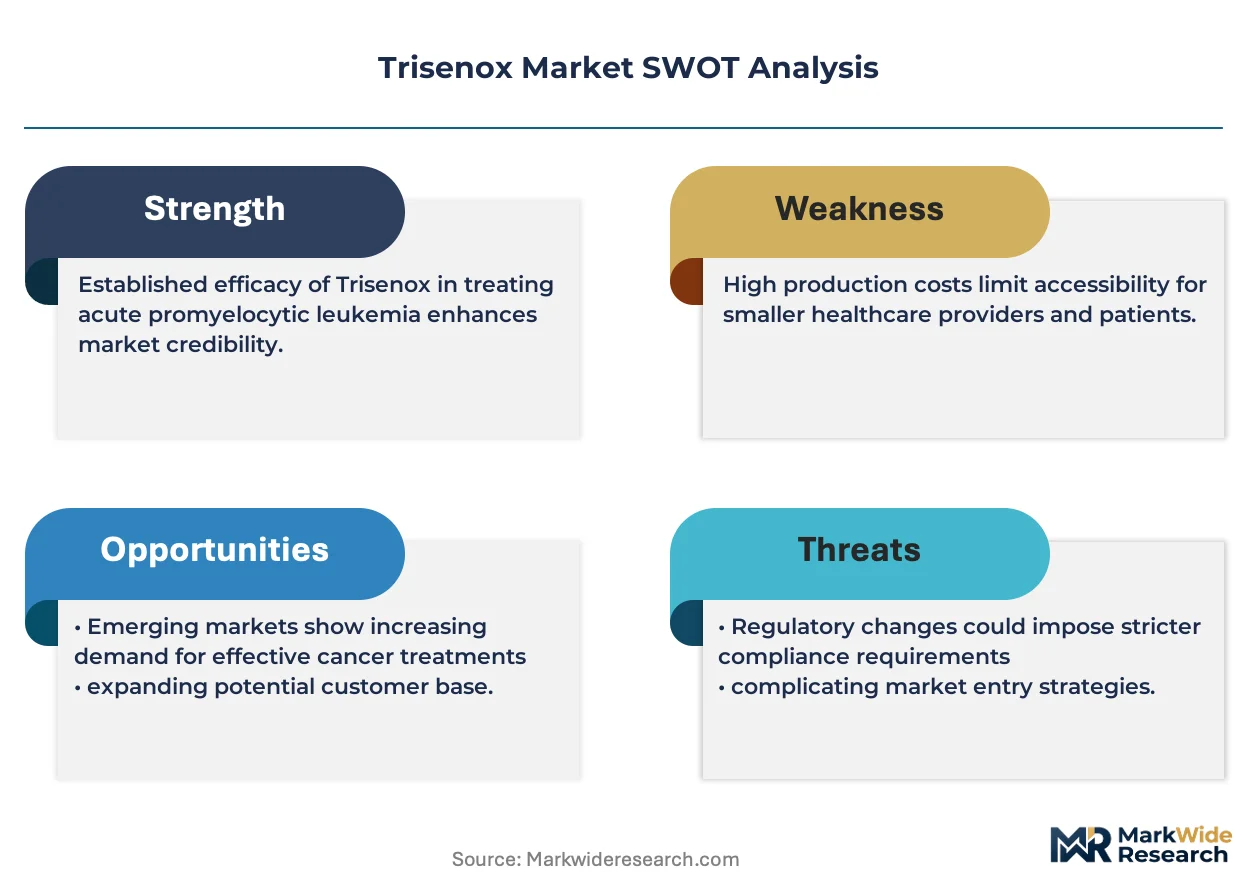
- FDA Orphan Drug Incentives:Tax credits and extended exclusivity provisions for acute promyelocytic leukemia indications sustain manufacturer commitment to arsenic trioxide production despite limited patient populations.
- Outpatient Administration Migration:Oncology clinics in the United States are expanding infusion suite capacity, pulling prepared doses from hospital inpatient settings into ambulatory revenue streams.
- Integrated Compounding Networks:Hospital systems with captive sterile preparation facilities capture margin previously allocated to external compounding pharmacies, tightening vertical control over the administration chain.
Market Restraints
- Arsenic Compound Handling Costs:EPA waste disposal mandates and occupational exposure monitoring requirements inflate per-dose logistics expenditure throughout the distribution chain.
- Single-Source API Concentration:Active pharmaceutical ingredient production for arsenic trioxide concentrates among specialty chemical manufacturers with toxic substance handling permits, creating supply vulnerability.
- Infusion Capability Thresholds:Community oncology practices without 24-hour pharmacy coverage face exclusion from administration protocols requiring immediate dose preparation and cardiac monitoring.
Strategic Opportunities
- Clinical Research Expansion:Investigators are probing Trisenox efficacy in myelodysplastic syndromes and multiple myeloma, opening protocol enrollment beyond established acute promyelocytic leukemia indications.
- Specialty Pharmacy Channel Development:Hub-and-spoke distribution models permit centralized compounding with regional cold-chain delivery, extending reach into markets lacking hospital infusion infrastructure.
- EU Orphan Designation Pathways:EMA incentives for rare disease therapeutics create parallel regulatory runway for manufacturers seeking European market entry alongside United States commercialization.
Industry Challenges
- Sterile Compounding Workforce Scarcity:Hospital pharmacies face recruitment pressure for pharmacists with hazardous drug handling certification and USP 797 compliance training.
- Batch Release Timeline Compression:Arsenic content verification and endotoxin testing protocols extend quality control cycles, constraining just-in-time inventory strategies for time-sensitive oncology protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trisenox Market |
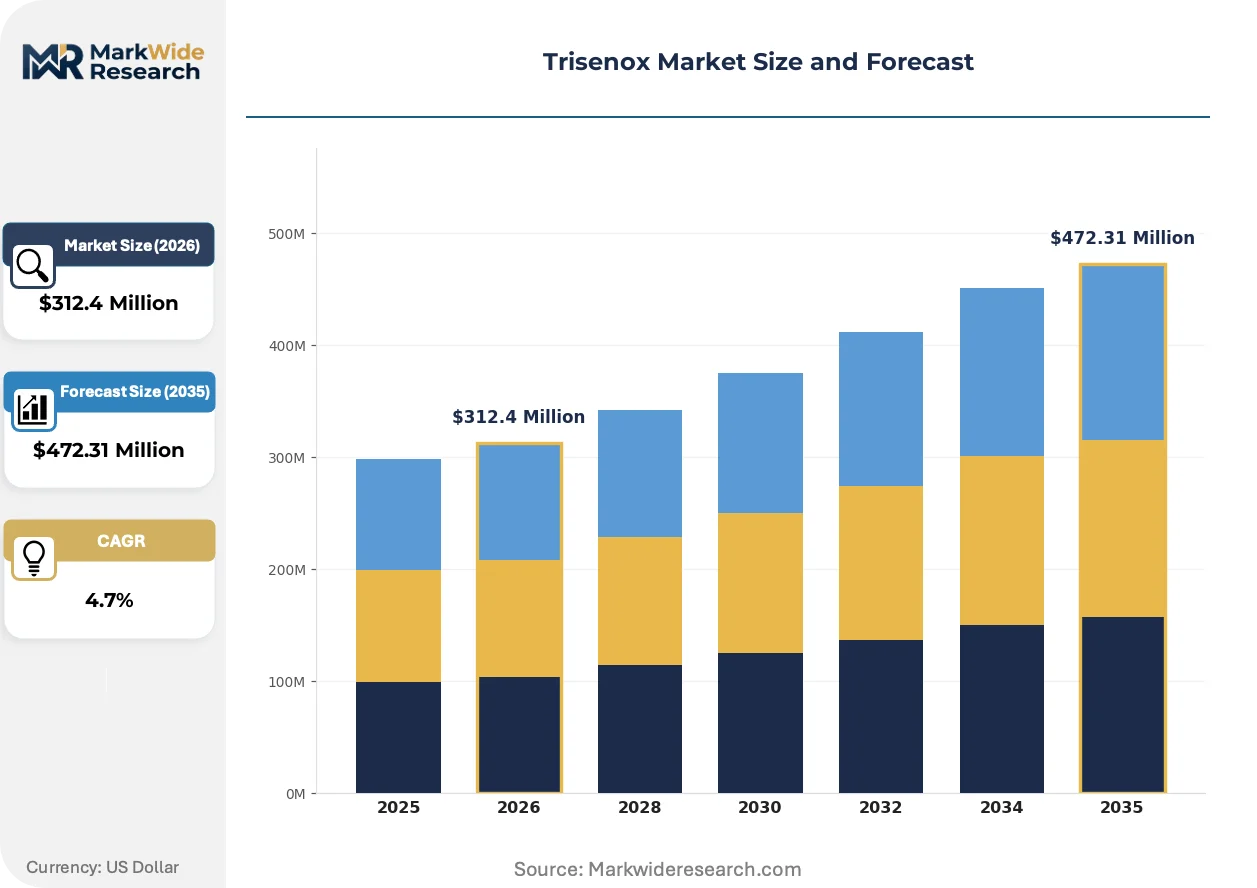
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Oncology, Hematology, Transplantation, Clinical Research End User: Hospitals, Research Institutes, Physicians, Outpatient Clinics Form: Injection, Solution, Injectable Suspension, Vial Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Specialty Pharmacies |
| Companies Covered | Cell Therapeutics, All-Chemie, Ltd., Teva Pharmaceutical Industries Ltd., Goyal Chem Associates, Amring Pharmaceuticals, Fresenius Kabi, Reagents LLC, Seidler Chemical Company, Nexus Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trisenox Market Evolving Landscape
Point-of-care preparation technologies and regulatory harmonization efforts are compressing the distance between manufacturing and patient administration, redistributing value capture across the supply chain.
Ready-to-administer infusion bags are decentralizing dose preparation from centralized hospital pharmacies to satellite infusion centers and ambulatory oncology suites. Community-based cancer clinics in the United States are adopting these pre-formulated configurations to bypass 24-hour pharmacy staffing requirements. The shift is compressing the role of traditional compounding intermediaries and reallocating margin toward manufacturers with fill-finish flexibility.
EMA's updated guidelines on arsenic-containing medicinal products are tightening impurity profiling and stability testing requirements for European market authorization holders. Manufacturers must now demonstrate extended shelf-life data under accelerated degradation conditions to maintain batch release privileges. Hematology-focused suppliers with established pharmacovigilance systems in Germany and France are absorbing compliance costs more readily than new market entrants.
Consolidated purchasing coalitions among integrated delivery networks are displacing individual hospital pharmacy negotiations across the United States. These coalitions extract volume-based pricing concessions and demand standardized preparation protocols across member facilities. The concentration of buying power is most visible in markets where three or fewer health systems control regional oncology service capacity.
Trisenox Market Segmentation
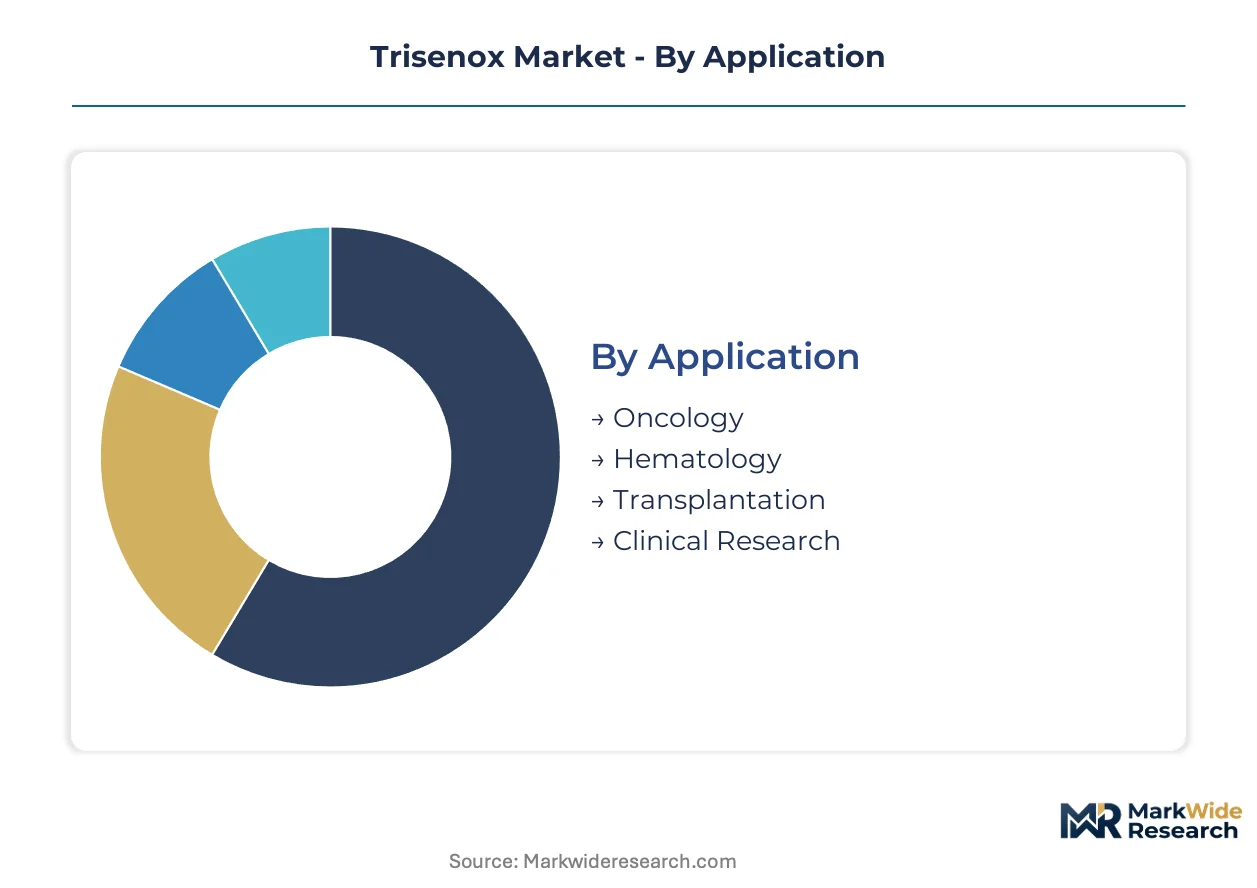
Trisenox procurement patterns diverge sharply across patient acuity levels, institutional capabilities, and regulatory exposure. Manufacturers must calibrate formulation configurations and channel strategies to match distinct operational constraints in hospital infusion suites versus ambulatory settings.
Application:
Oncology clinics prioritize cardiac monitoring infrastructure and immediate pharmacy access when selecting arsenic trioxide protocols.
- Oncology:Acute promyelocytic leukemia induction protocols dominate utilization, with United States cancer centers requiring continuous telemetry during infusion. Demand concentrates in academic medical centers with 24-hour pharmacy coverage and established hematologic malignancy programs.
- Hematology:Myelodysplastic syndrome protocols and combination therapies with retinoids drive protocol expansion beyond first-line indications. Investigators at major United States research hospitals are probing efficacy in relapsed disease settings.
- Transplantation:Conditioning regimens incorporate arsenic trioxide for select high-risk populations prior to stem cell infusion.
- Clinical Research:Expanded indication trials and pharmacokinetic studies generate protocol-specific demand for documented batch pedigree and stability data.
Volume sits with Oncology; growth tilts toward Clinical Research.
End User:
Institutional pharmacy capabilities and reimbursement structures determine access tier for each buyer type.
- Hospitals:Inpatient oncology units with captive sterile compounding facilities capture margin through vertical control over preparation and administration. These institutions command preferential pricing through consolidated purchasing coalitions.
- Research Institutes:National Cancer Institute-designated centers and contract research organizations drive protocol enrollment for expanded indication studies. Investigators require documented chain-of-custody and specialized pharmacovigilance reporting.
- Physicians:Community hematologists in private practice rely on external compounding pharmacies for dose preparation.
- Outpatient Clinics:Ambulatory infusion centers in the United States are expanding suite capacity to capture revenue from hospital migration.
Procurement scale favors Hospitals; ambulatory expansion is climbing fastest among Outpatient Clinics.
Form:
Preparation complexity and stability requirements differentiate formulations across care settings.
- Injection:Concentrated ampoules requiring dilution in controlled environments remain standard for hospital pharmacy networks with USP 797-compliant cleanrooms.
- Solution:Ready-to-administer bags are gaining traction among United States community oncology practices lacking 24-hour staffing.
- Injectable Suspension:Modified release formulations for research protocols requiring sustained exposure profiles.
- Vial:Multi-dose configurations support high-volume academic centers with immediate turnover.
Utilization clusters on Injection; convenience positioning is expanding most quickly for Solution.
Distribution Channel:
Channel selection reflects institutional scale, compounding capabilities, and geographic proximity to patients.
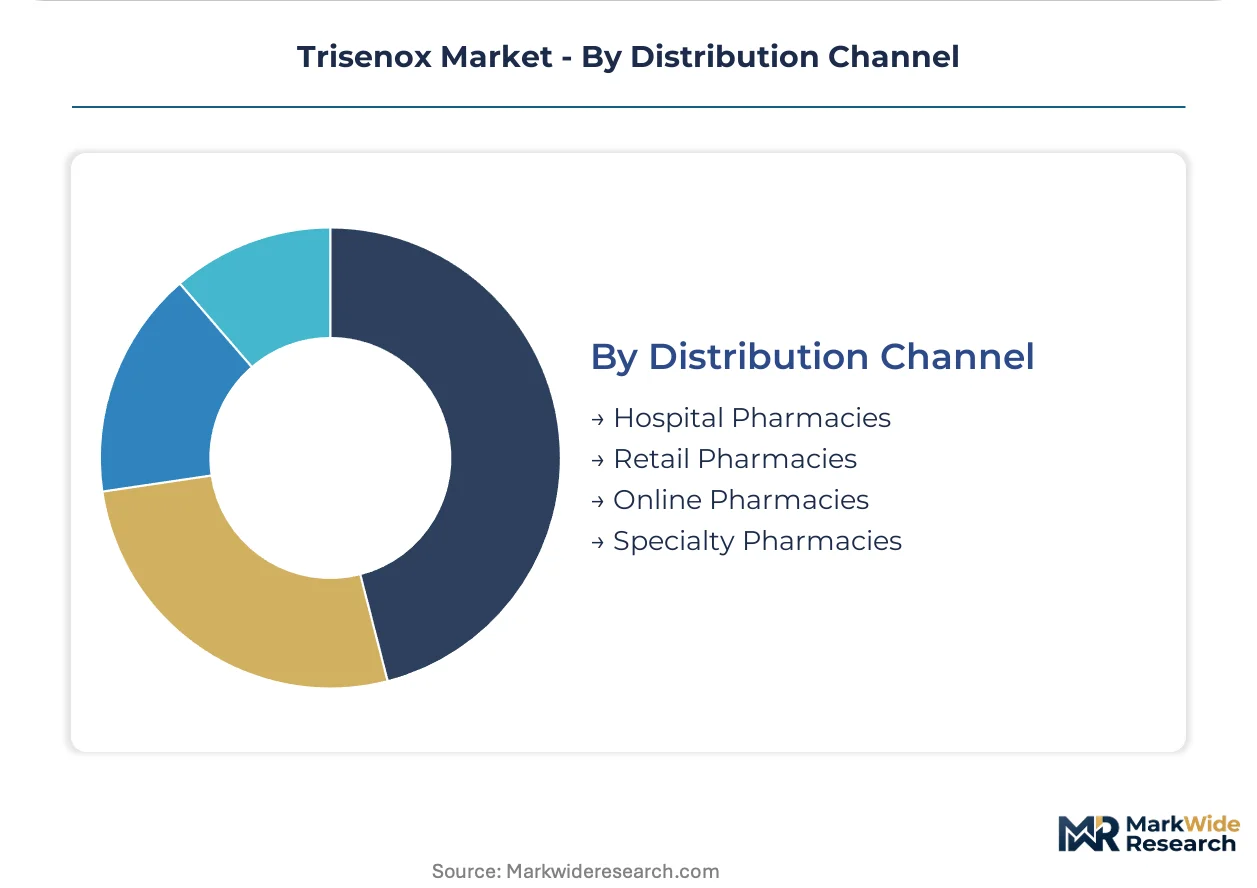
- Hospital Pharmacies:Integrated delivery networks with captive sterile preparation facilities capture margin previously allocated to external intermediaries. These buyers demand just-in-time inventory with documented batch release timelines.
- Specialty Pharmacies:Hub-and-spoke models permit centralized hazardous drug compounding with regional cold-chain delivery to satellite infusion sites. United States specialty pharmacy networks are extending reach into markets lacking hospital infrastructure.
- Retail Pharmacies:Limited role given handling restrictions and administration requirements.
- Online Pharmacies:Emerging channel for research supply and documented reagent procurement.
Transaction volume concentrates in Hospital Pharmacies; network expansion is steepest for Specialty Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API production for arsenic trioxide concentrates among specialty chemical manufacturers in China and India, while clinical consumption clusters in United States and European oncology centers with established infusion infrastructure.
United States
FDA orphan drug incentives sustain manufacturer commitment to acute promyelocytic leukemia indications despite limited patient populations. The EPA regulates arsenic compound handling, waste disposal, and occupational exposure limits throughout the production chain. Academic medical centers in Boston and Houston command preferential pricing through consolidated purchasing coalitions.
Germany
EMA's updated guidelines on arsenic-containing medicinal products tighten impurity profiling requirements for European market authorization holders. REACH compliance mandates extensive documentation for toxic substance import and handling. Hematology-focused suppliers in Munich and Frankfurt absorb pharmacovigilance costs more readily than new market entrants.
India
CDSCO accelerated approval pathways for orphan oncology indications attract contract manufacturing investment to the subcontinent. The country's national pharmaceutical regulator aligns batch release protocols with WHO prequalification standards. API manufacturers in Gujarat and Maharashtra leverage existing toxic chemical handling infrastructure for arsenic trioxide production.
China
NMPA priority review channels for rare disease therapeutics compress regulatory timelines for domestic manufacturers. GB standards for pharmaceutical-grade arsenic compounds exceed baseline international specifications. Specialty chemical clusters in Jiangsu and Zhejiang provinces dominate active pharmaceutical ingredient output for global supply.
Switzerland
Swissmedic harmonized inspection protocols with FDA and EMA reduce redundant facility audits for multi-territory manufacturers. The country's national pharmaceutical regulator emphasizes documented chain-of-custody for investigational arsenic trioxide shipments. Basel-based hematology research institutes drive protocol enrollment for expanded indication studies.
Trisenox Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Trisenox supply chain, creating a tiered structure where scale-driven generic injectables manufacturers anchor hospital channel access while concentrated hematology sales forces capture specialty positioning. Three archetypes dominate: integrated pharmaceutical conglomerates with hazardous drug infrastructure, captive API-to-finished-dose vertically integrated operators, and research-centered biotech specialists. Competitive moves concentrate on fill-finish flexibility investments and hub-and-spoke distribution partnerships.
Among the integrated pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd. and Fresenius Kabi occupy positions exemplifying cost-competitive supply chain scale and hospital channel integration respectively. Cell Therapeutics represents the specialized oncology positioning archetype with concentrated hematology focus. These three anchors illustrate how manufacturer archetype selection determines channel access tier and margin capture potential across inpatient versus ambulatory settings.
| Leading Market Players |
|---|
| Cell Therapeutics |
| All-Chemie, Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Goyal Chem Associates |
| Amring Pharmaceuticals |
| Fresenius Kabi |
| Reagents LLC |
| Seidler Chemical Company |
| Nexus Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Arsenic trioxide commodity benchmarks cascade through specialty chemical manufacturing into finished-dose pricing tiers, with EPA waste handling premiums and single-source API concentration compressing margins at each supply chain node. Hospital pharmacy networks with consolidated purchasing coalitions extract volume concessions that propagate upstream to API manufacturers in Gujarat and Jiangsu.
Pricing Analysis
Cost-down pressure on hospital procurement tiers accelerates because integrated delivery networks weaponize scale against compounding intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with captive sterile preparation from community oncology practices relying on external compounding, with volume scale and USP 797 certification status driving differentiation. Pricing pressure stems from specialty pharmacy hub-and-spoke models disintermediating traditional hospital channels. Community hematologists exhibit highest price sensitivity due to reimbursement compression, while NCI-designated centers prioritize batch pedigree over unit cost.
Supply Chain Analysis
Cold-chain logistics costs for hazardous drug handling inflate per-dose expenditure across the distribution network, particularly for satellite infusion centers lacking immediate pharmacy access. API production concentrates in China, India, and Switzerland, with specialty chemical clusters in Jiangsu and Gujarat feeding finished-dose manufacturers. Arsenic compound sourcing draws from mining operations with toxic substance handling permits, creating single-source vulnerability around environmental compliance certification. Distribution runs through hospital pharmacy networks with captive compounding, though specialty pharmacy cold-chain delivery is displacing traditional channels in ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trisenox supply is structurally constrained by sterile compounding workforce scarcity and EPA-permitted API manufacturing capacity, propping pricing power for incumbent manufacturers with established hazardous drug infrastructure.
For Market Incumbents: Hedge against specialty pharmacy channel erosion by deepening backward integration into API supply and securing exclusive hub-and-spoke partnerships with regional oncology networks. Invest in USP 797-compliant fill-finish flexibility to capture ambulatory migration revenue streams. Defensive priority rests on locking in consolidated purchasing coalition contracts before generic injectables competitors replicate Teva's cost structure. For New Entrants and Emerging Players: Launch via specialty pharmacy hub-and-spoke distribution to bypass hospital pharmacy consolidation barriers. Target clinical research segments requiring documented batch pedigree and stability data, where pricing tolerance exceeds standard oncology procurement. White-space opportunity concentrates in EU orphan designation pathways for myelodysplastic syndrome protocols, with EMA regulatory alignment as the critical go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor captive API-to-finished-dose vertically integrated operators in India and China with existing toxic chemical handling permits. Long-term viability hinges on regulatory moats around environmental compliance rather than patent exclusivity. Watch for EPA enforcement actions against specialty chemical manufacturers as the inflection signal for supply disruption and pricing spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expanded indication studies in myelodysplastic syndromes unlock protocol enrollment beyond acute promyelocytic leukemia at NCI-designated centers. |
| Regulatory Approval Pathway | EMA orphan designation applications in Germany and France create parallel commercialization runway alongside FDA exclusivity provisions. |
| Manufacturing Scale-Up | USP 797-compliant sterile compounding capacity additions in United States hospital networks capture margin from ambulatory administration shifts. |
| Backward Integration | Captive API production with EPA toxic substance permits insulates against single-source concentration in Jiangsu and Gujarat chemical clusters. |
| Distribution Channel Expansion | Specialty pharmacy hub-and-spoke partnerships extend reach into United States community oncology markets lacking 24-hour pharmacy coverage. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital pharmacy directors, hematology formulary managers, sterile compounding supervisors, and EPA compliance officers at specialty chemical manufacturers. FDA orphan drug designations, EMA marketing authorization submissions, ClinicalTrials.gov protocol registries, and consolidated purchasing coalition contract databases provided segmentation benchmarks. Bottom-up demand modeling across patient population cohorts triangulated against top-down manufacturer revenue estimates.
Granularity-level framing applied treatment line, dosage form, and regional regulatory cluster dimensions at the country level, with administration setting and distribution channel modeled at the facility tier. CAGRs derived from patient incidence projections, protocol penetration assumptions, and pricing trajectory analysis across the projection horizon. Forecast inputs incorporated EPA enforcement probability weightings and specialty pharmacy network expansion rates.
Regulatory enforcement intensity, API manufacturing capacity additions, and clinical trial enrollment velocity are the dominant revision risks for projection accuracy. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Aminophylline Market