
 Bacterial Conjunctivitis Market | 2026-2036
Bacterial Conjunctivitis Market Size, Share, and Industry Trends Forecast 2026-2036
Bacterial Conjunctivitis Market Analysis
Ophthalmic pharmacy networks is reshaping how bacterial conjunctivitis treatments reach patients, with specialty retail and mail-order channels gaining shelf authority over generalist distributors. Novartis AG leverages its integrated eye-care portfolio to sustain formulary access across European hospital systems. Pfizer Inc. anchors its position through manufacturing scale in sterile drop production. Alcon Laboratories, Inc. differentiates via direct-to-practitioner sampling programs that bypass wholesale intermediaries.
Bacterial conjunctivitis denotes acute purulent inflammation of the bulbar and palpebral conjunctiva caused by pathogens including Staphylococcus aureus and Streptococcus pneumoniae, typically treated with topical fluoroquinolone or macrolide formulations dosed at one to two drops per affected eye every four to six hours. The condition drives commercial demand through high recurrence rates in daycare and school settings, necessitating repeat prescription cycles and preservative-free packaging for sensitive populations. Antibiotic drops dominate volume due to immediate bioavailability and patient self-administration convenience, while ointments retain share in pediatric applications where drop instillation proves difficult. Home care delivery is expanding fastest as telehealth prescribing normalizes post-consultation fulfillment through retail pharmacy partnerships.
FDA Current Good Manufacturing Practice for ophthalmic products enforces sterility and particulate limits that raise barrier costs for new entrants, while EMA MDR requirements in Europe mandate enhanced clinical evidence for reusable multi-dose containers. The EU F-Gas Regulation indirectly shapes packaging decisions by pressuring propellant-based delivery systems toward mechanical pump alternatives. Stakeholders must monitor evolving pharmacovigilance obligations across FDA and EMA jurisdictions to anticipate labeling revisions that could reposition existing portfolio assets.
Market Dynamics
FDA sterility enforcement and EMA MDR compliance are compressing manufacturing capacity for ophthalmic antibiotics while pediatric prescribing volumes expand through telehealth channels.
Growth Catalysts
- Telehealth prescribing normalization:Post-consultation fulfillment through retail pharmacy partnerships accelerates antibiotic drop dispensing in United States pediatric networks.
- EMA MDR clinical evidence mandates:Enhanced safety documentation for multi-dose containers drives preservative-free formulation investment across European hospital systems.
- Daycare density concentration:High recurrence environments in clustered childcare facilities generate repeat prescription cycles for topical fluoroquinolone therapies.
Market Restraints
- Sterile manufacturing input volatility:Pharmaceutical-grade propellant supply constraints under EU F-Gas Regulation elevate packaging conversion costs for mechanical pump alternatives.
- Single-source API concentration:Active pharmaceutical ingredient production for macrolide ophthalmic formulations clusters in limited Asian manufacturing zones.
- Antibiotic resistance surveillance:CDC and ECDC pathogen tracking programs impose label restriction risks that compress formulary placement flexibility.
Strategic Opportunities
- Home care delivery channel expansion:Mail-order pharmacy networks bypass wholesale intermediaries to capture chronic recurrence patient segments.
- Preservative-free pediatric positioning:Sensitive population formulations open formulary access in United States Medicaid pediatric clinic networks.
- ISO 13485 convergence with ophthalmic GMP:Unified quality management certification streamlines dual FDA-EMA market entry for sterile drop manufacturers.
Industry Challenges
- Aseptic processing technician scarcity:FDA Current Good Manufacturing Practice compliance requires specialized cleanroom operations expertise that outpaces training pipeline output.
- Legacy multi-dose container validation:Reusable bottle systems face extended FDA stability testing timelines that delay portfolio line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacterial Conjunctivitis Market |
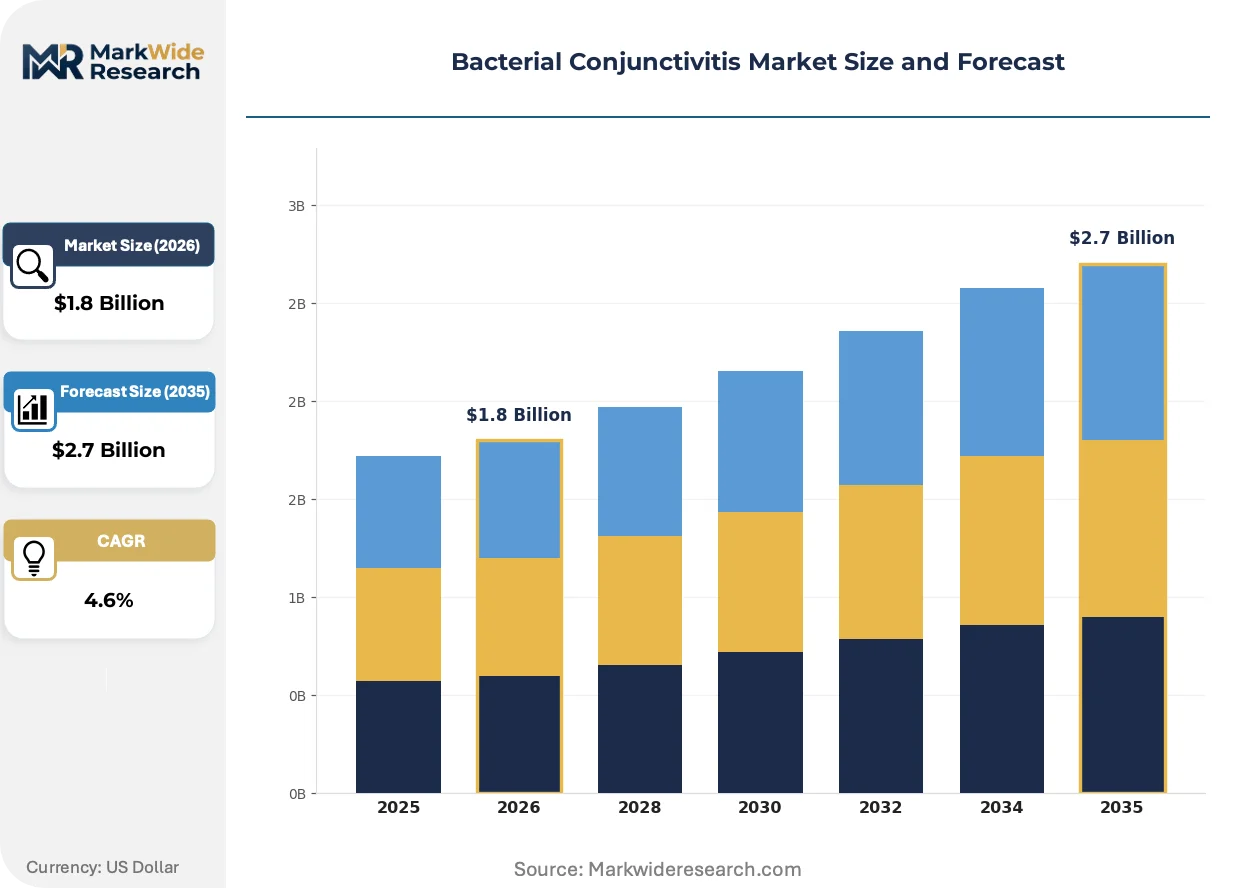
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotic Drops, Ointments, Oral Medications, Steroid Drops Delivery Mode: Topical, Systemic, Injectable, Ophthalmic End User: Hospitals, Clinics, Home Care, Pharmacies Age Group: Pediatrics, Adults, Geriatrics, Others |
| Companies Covered | Novartis AG, Allergan, Bausch Health Companies Inc., Merck & Co., Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Santen Pharmaceutical Co., Ltd., Alcon Laboratories, Inc., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacterial Conjunctivitis Market Emerging Trajectories
Packaging technology and distribution channel architecture are undergoing parallel transformation as sterility requirements tighten and patient fulfillment preferences fragment across physical and digital touchpoints.
Preservative-free unit-dose vial technology is collapsing the cost premium between single-use and multi-dose antibiotic delivery systems. Pediatric ophthalmology practices in the United States are adopting these vials at accelerating rates for school-age patient populations. The shift is collapsing reimbursement differentiation that previously favored bulk packaging economics.
EMA Medical Device Regulation Annex XVI reclassification is capturing certain ophthalmic drug-device combination products under enhanced clinical investigation requirements. Manufacturers must now generate pre-market clinical evidence for reusable dropper systems previously exempt from device scrutiny. European hospital procurement committees are responding by consolidating supplier lists to favor established MDR-compliant portfolios.
Direct-to-practitioner sampling programs are displacing traditional wholesale repackaging for new antibiotic launches. Specialty retail pharmacy chains capture fulfillment volume while generalist distributors lose shelf authority in bacterial conjunctivitis categories. This channel reconfiguration is most visible in United States metropolitan markets where integrated eye-care networks concentrate prescribing influence.
Bacterial Conjunctivitis Market Segmentation
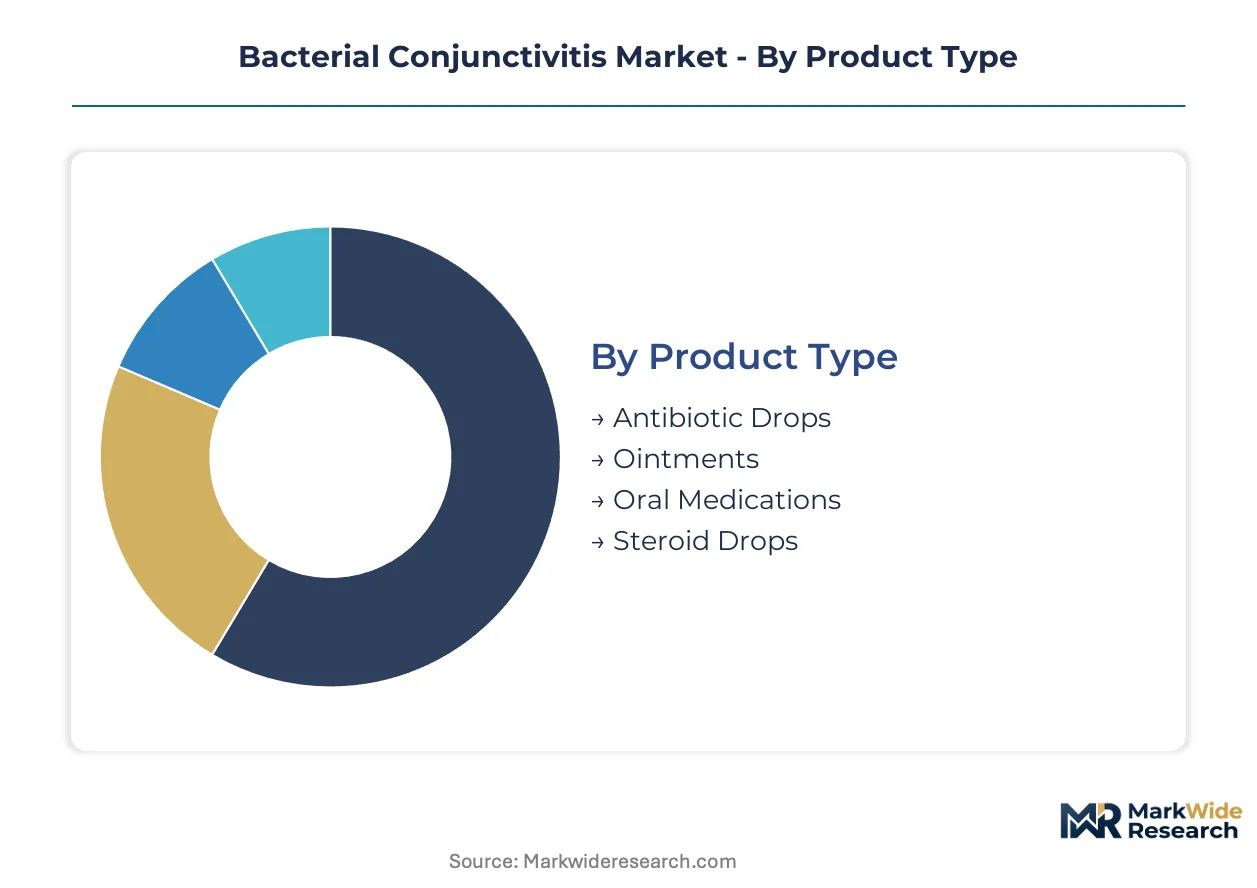
Antibiotic formulation choices and delivery preferences fragment the bacterial conjunctivitis market across distinct patient populations and care settings. Segmentation reveals how sterility requirements, recurrence patterns, and reimbursement structures concentrate commercial opportunity in specific product configurations.
Product Type:
Cost tier positioning separates acute episodic treatment from chronic management protocols across the bacterial conjunctivitis market.
- Antibiotic Drops:Topical fluoroquinolone and macrolide solutions deliver immediate bioavailability through one-to-two drop dosing every four to six hours. Pediatric clinic networks in the United States concentrate procurement volumes here due to self-administration convenience and telehealth prescribing normalization.
- Ointments:Semisolid petrolatum-based vehicles containing erythromycin or bacitracin provide prolonged ocular surface contact. Demand clusters in daycare-aged populations where drop instillation proves difficult, with Medicaid pediatric networks driving formulary placement.
- Oral Medications:Systemic antibiotics address refractory or complicated infections extending beyond conjunctival surfaces.
- Steroid Drops:Anti-inflammatory adjuncts manage severe inflammatory response in selected clinical scenarios.
Antibiotic drops hold installed capacity. Ointments are rotating up the share rankings in pediatric-specific procurement channels.
Delivery Mode:
Application site specificity determines regulatory pathway complexity and manufacturing barrier height for each delivery configuration.
- Topical:Direct ocular surface application via drops or ointments dominates bacterial conjunctivitis treatment protocols. FDA sterility enforcement for ophthalmic products elevates manufacturing standards, compressing capacity for new entrants while established sterile drop producers capture volume.
- Ophthalmic:Dedicated eye-specific formulations with pH-balanced vehicles and tonicity-adjusted solutions. European hospital systems under EMA MDR requirements are consolidating supplier lists toward MDR-compliant portfolios with enhanced clinical evidence for reusable multi-dose containers.
- Systemic:Oral or intravenous routes for complicated infections with periorbital involvement.
- Injectable:Parenteral antibiotics reserved for severe orbital cellulitis or vision-threatening complications.
Topical delivery holds installed capacity. Ophthalmic-specific formulations are rotating up the share rankings through regulatory compliance advantages.
End User:
Customer type segmentation maps how prescribing authority and fulfillment infrastructure reshape distribution economics across care settings.
- Home Care:Patient-directed administration with telehealth-prescribed fulfillment through retail pharmacy partnerships. Mail-order pharmacy networks are bypassing wholesale intermediaries to capture chronic recurrence segments, expanding fastest as post-consultation fulfillment normalizes.
- Clinics:Pediatric and ophthalmology practices with direct sampling program access. Alcon's direct-to-practitioner sampling bypasses wholesale intermediaries in United States metropolitan markets with concentrated eye-care network influence.
- Hospitals:Inpatient and emergency department settings for severe presentations.
- Pharmacies:Community and specialty retail channels handling prescription fulfillment.
Clinic settings hold installed capacity. Home care delivery is rotating up the share rankings through telehealth channel expansion.
Age Group:
Volume concentration in high-recurrence populations drives packaging innovation and preservative-free formulation investment cycles.
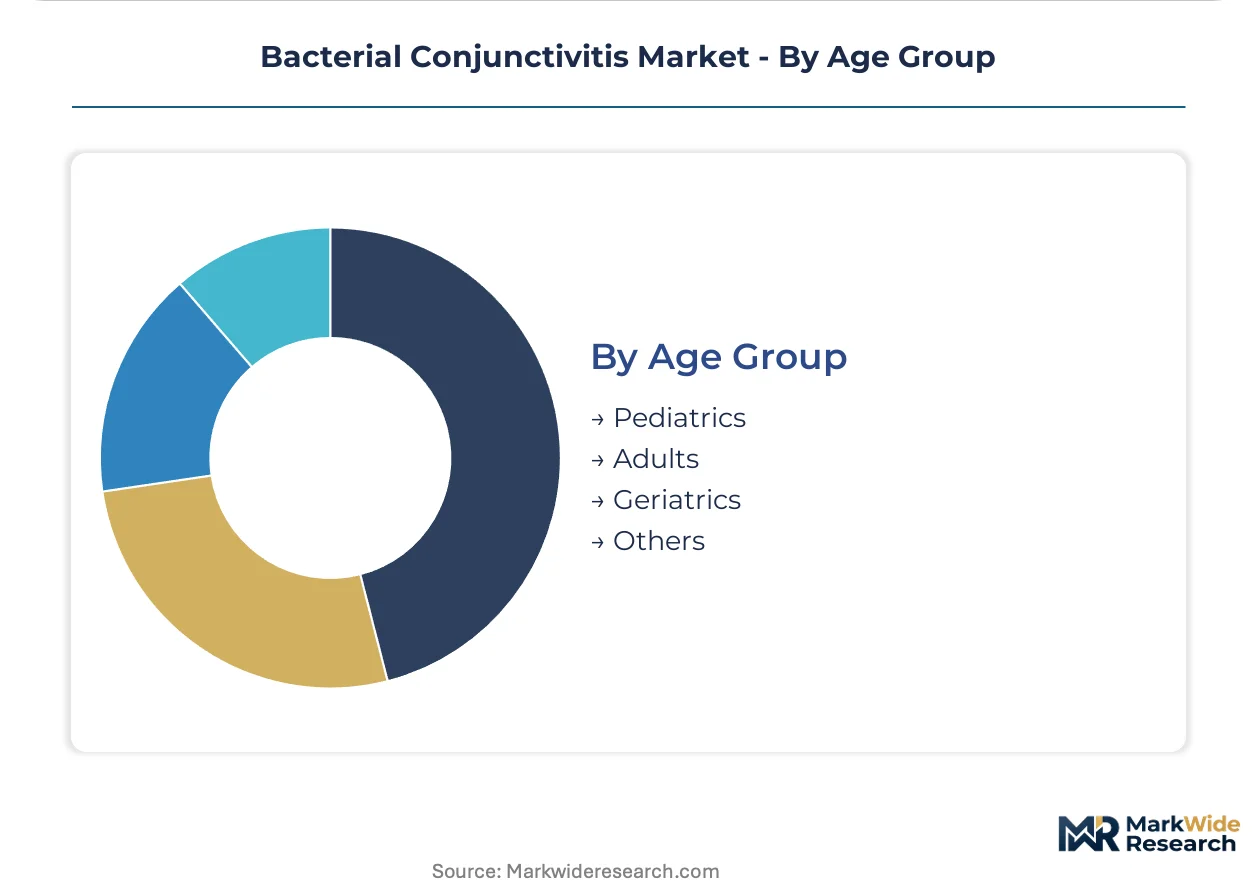
- Pediatrics:School-age and daycare populations experiencing high recurrence rates in clustered childcare environments. Preservative-free unit-dose vial adoption is accelerating here as reimbursement differentiation between single-use and multi-dose systems collapses.
- Adults:Working-age patients with occupational exposure and contact lens-related infection risk.
- Geriatrics:Elderly populations with compromised ocular surface defense mechanisms.
- Others:Immunocompromised and special risk category patients requiring modified protocols.
Adult populations hold installed capacity. Pediatric segments are rotating up the share rankings through daycare density concentration and packaging innovation pull-through.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive ophthalmic formulations. FedEx's Memphis superhub anchors North American next-day fulfillment networks for antibiotic drops. Singapore's Changi cargo terminals connect Asia-Pacific manufacturing clusters to Middle Eastern hospital procurement systems.
United States
Telehealth prescribing normalization through retail pharmacy partnerships accelerates pediatric antibiotic drop dispensing. FDA sterility enforcement for ophthalmic products compresses manufacturing capacity while raising compliance barriers for new entrants. The Dallas-Fort Worth metroplex concentrates specialty pharmacy distribution centers serving southern Medicaid pediatric networks.
Germany
EMA MDR clinical evidence mandates for reusable multi-dose containers drive preservative-free formulation investment across hospital systems. The EU F-Gas Regulation pressures propellant-based delivery systems toward mechanical pump alternatives. The Rhine-Main region around Frankfurt hosts centralized procurement consortia consolidating supplier lists toward MDR-compliant portfolios.
Japan
PMDA's stringent ophthalmic sterility guidelines elevate manufacturing standards for topical fluoroquinolone therapies. METI's pharmaceutical quality initiatives reinforce cleanroom operations expertise requirements. The Kansai corridor between Osaka and Kobe concentrates sterile drop production facilities serving domestic and export markets.
India
CDSCO's evolving ophthalmic product regulations align with international GMP standards for export-oriented manufacturers. The country's national pharmaceutical regulator tightens documentation for active pharmaceutical ingredient sourcing. Hyderabad's bulk drug manufacturing clusters supply macrolide ophthalmic formulations to European and North American formulators.
Brazil
ANVISA's convergence with FDA sterility protocols opens market access for multinational ophthalmic antibiotic portfolios. The country's national health surveillance agency accelerates approval timelines for preservative-free pediatric formulations. São Paulo's metropolitan health districts concentrate pediatric clinic networks driving repeat prescription cycles for topical therapies.
Bacterial Conjunctivitis Market Vendor Landscape
On the supply side, the industry is consolidating around integrated eye-care portfolios and sterile manufacturing scale. Three archetypes dominate: diversified pharmaceutical conglomerates with ophthalmic divisions, specialized eye-care pure-plays, and generic manufacturers leveraging API cost advantages. Competitive moves center on direct-to-practitioner sampling programs bypassing wholesale intermediaries, and preservative-free formulation line extensions capturing pediatric formulary access.
Among diversified pharmaceutical conglomerates, Novartis AG and Pfizer Inc. exemplify the integrated portfolio archetype, anchoring formulary access through manufacturing scale and cross-therapeutic presence. Alcon Laboratories, Inc. occupies a position within the specialized eye-care tier, representing direct-to-practitioner distribution models that displace traditional wholesale channels in United States metropolitan markets.
| Leading Market Players |
|---|
| Novartis AG |
| Allergan |
| Bausch Health Companies Inc. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Santen Pharmaceutical Co., Ltd. |
| Alcon Laboratories, Inc. |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
The Memphis superhub's next-day fulfillment premiums compress margins for sterile drop manufacturers while concentrating pricing power among integrated eye-care portfolios with captive distribution networks. This logistics cost dynamic reinforces three-tier pricing stratification across premium preservative-free, standard multi-dose, and economy generic tiers, with supply concentration in Asian API clusters and European packaging equipment further shaping downstream price differentiation.
Pricing Analysis
Volume-discount tiering separates annual procurement contracts for pediatric clinic networks from spot purchases in retail pharmacy channels. Pricing stratifies across premium preservative-free unit-dose vials, standard multi-dose bottles, and economy generic macrolide formulations, with FDA sterility compliance costs driving premium tier expansion. Cost compression in the economy tier intensifies because single-source API concentration in Asian manufacturing zones limits supplier switching. Medicaid pediatric networks exhibit highest price sensitivity, while integrated hospital systems demonstrate lowest sensitivity due to formulary lock-in effects.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement relationships between European hospital consortia and sterile drop manufacturers, with supply-chain finance facilities bridging working capital gaps for mid-tier formulators. Active pharmaceutical ingredient production clusters in India and China, while packaging equipment and cleanroom infrastructure draw from Germany and Japan. Single-source vulnerability pervades macrolide ophthalmic API sourcing, with distribution running through specialty pharmacy networks bypassing traditional wholesale intermediaries in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bacterial conjunctivitis therapeutics increasingly function as service-attach platforms where direct-to-practitioner sampling programs and telehealth fulfillment partnerships generate recurring revenue streams expanding faster than standalone product margins.
For Market Incumbents: Build regulatory compliance moats through simultaneous FDA sterility certification and EMA MDR clinical evidence generation for reusable multi-dose containers. Novartis and Pfizer should deepen backward integration into sterile API production to offset single-source concentration risks in Asian supply zones. Alcon's direct-to-practitioner sampling model warrants replication across European hospital procurement committees consolidating toward MDR-compliant portfolios.
For New Entrants and Emerging Players: Build out preservative-free pediatric formulations targeting United States Medicaid clinic networks where reimbursement differentiation between single-use and multi-dose systems has collapsed. White-space concentration appears in mail-order pharmacy fulfillment partnerships for chronic recurrence patient segments, with telehealth-prescribed fulfillment representing the most penetrable go-to-market angle against established wholesale-dependent incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core ophthalmic divisions lacking integrated eye-care portfolio scale. Long-term viability centers on manufacturers with captive sterile processing capacity and dual FDA-EMA regulatory pathways. Watch FDA sterility enforcement intensity and EMA MDR compliance timeline adherence as inflection indicators for portfolio repositioning opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Line Extension | Pediatric clinic networks in United States Medicaid systems drive formulary access expansion. |
| Direct-to-Practitioner Sampling Program | Alcon's model bypasses wholesale intermediaries in metropolitan eye-care concentration zones. |
| EMA MDR Clinical Evidence Generation | Reusable multi-dose container validation opens European hospital procurement committee consolidation. |
| Telehealth Fulfillment Partnership | Mail-order pharmacy networks capture chronic recurrence segments through post-consultation normalization. |
| Sterile Manufacturing Scale-Up | FDA Current Good Manufacturing Practice compliance compresses capacity for new market entrants. |
Methodological Framework
Operator-level perspectives from ophthalmology practice administrators, sterile manufacturing plant managers, hospital procurement committee members, and specialty pharmacy distribution executives anchored the qualitative base for this analysis. These primary insights combined with secondary validation from FDA 483 inspection observations, EMA MDR submission databases, ClinicalTrials.gov ophthalmic protocol registrations, and GPO contract award disclosures. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation ensured cross-verification of market sizing assumptions.
Scenario-bracketing framed projections across base, accelerated telehealth adoption, and regulatory enforcement intensification cases over the projection horizon. Segmentation dimensions encompassed antibiotic formulation type, delivery mode specificity, end-user care setting, and pediatric versus adult patient population. CAGRs derived from historical prescription volume trajectories, sterilization capacity expansion pipelines, and recurrence rate epidemiology. Forecast inputs included daycare density demographic projections and EU F-Gas Regulation packaging conversion timelines.
Stress conditions across API supply disruption severity, FDA sterility enforcement intensity, and telehealth prescribing normalization velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement structure continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Toxoplasmosis Infection Treatment Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market