
 Depression Drugs Market | 2026-2036
Depression Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Depression Drugs Market Intelligence
North American manufacturing capacity for active pharmaceutical ingredients is tilting toward complex psychotropic compounds. Eli Lilly and Company leverages its neuroscience R&D heritage to sustain a pipeline focused on treatment-resistant depression. Pfizer anchors its position through backward integration into key intermediate synthesis. AbbVie differentiates via immunology-psychiatry crossover research platforms.
Depression drugs comprise pharmaceutical agents modulating monoamine neurotransmission or novel receptor targets to alleviate depressive symptomatology, with formulations ranging from immediate-release tablets to extended-release injectable depots requiring precise dissolution profiles and bioequivalence validation. Their primary purpose is restoring functional capacity in patients with diagnosed mood disorders across outpatient and institutional settings. SSRIs occupy the largest volume position due to established tolerability profiles and generic availability, while intranasal delivery modes represent the fastest-expanding category driven by rapid-onset formulations for acute suicidal ideation. Atypical antipsychotics command premium positioning within bipolar depression therapy areas where reimbursement supports newer mechanisms.
The FDA's psychiatric drug review divisions shape clinical trial design requirements and labeling standards for novel antidepressant entities, while the DEA imposes scheduling controls on emerging ketamine-derived therapies that restrict distribution channels. The EMA's centralized procedures govern market access across European member states with divergent national pricing negotiations. Stakeholders must monitor evolving FDA guidance on digital therapeutics as adjuncts to pharmacotherapy and prepare for potential reimbursement integration of biomarker-directed prescribing protocols.
Market Dynamics
FDA's accelerated approval pathways for novel antidepressant mechanisms are compressing development timelines and reshaping how sponsors design pivotal trials for treatment-resistant populations.
Growth Catalysts
- Intranasal Delivery Innovation:Rapid-onset formulations targeting acute suicidal ideation are expanding addressable episodes beyond chronic maintenance therapy. Hospital emergency departments and crisis intervention units represent the primary adoption sites.
- DEA Scheduling Flexibility:Controlled substance protocols for ketamine-derived therapies are enabling supervised clinical access while maintaining distribution safeguards. Specialty clinics and academic medical centers are building administration infrastructure.
- Treatment-Resistant Depression Protocols:Biomarker-directed patient stratification is virtualizing trial enrollment and expanding reimbursement for non-SSRI mechanisms. Payers are developing coverage frameworks for refractory subpopulations.
Market Restraints
- API Supply Concentration:Complex psychotropic intermediate synthesis depends on concentrated Asian manufacturing bases. Geopolitical friction and shipping disruptions create formulation bottlenecks.
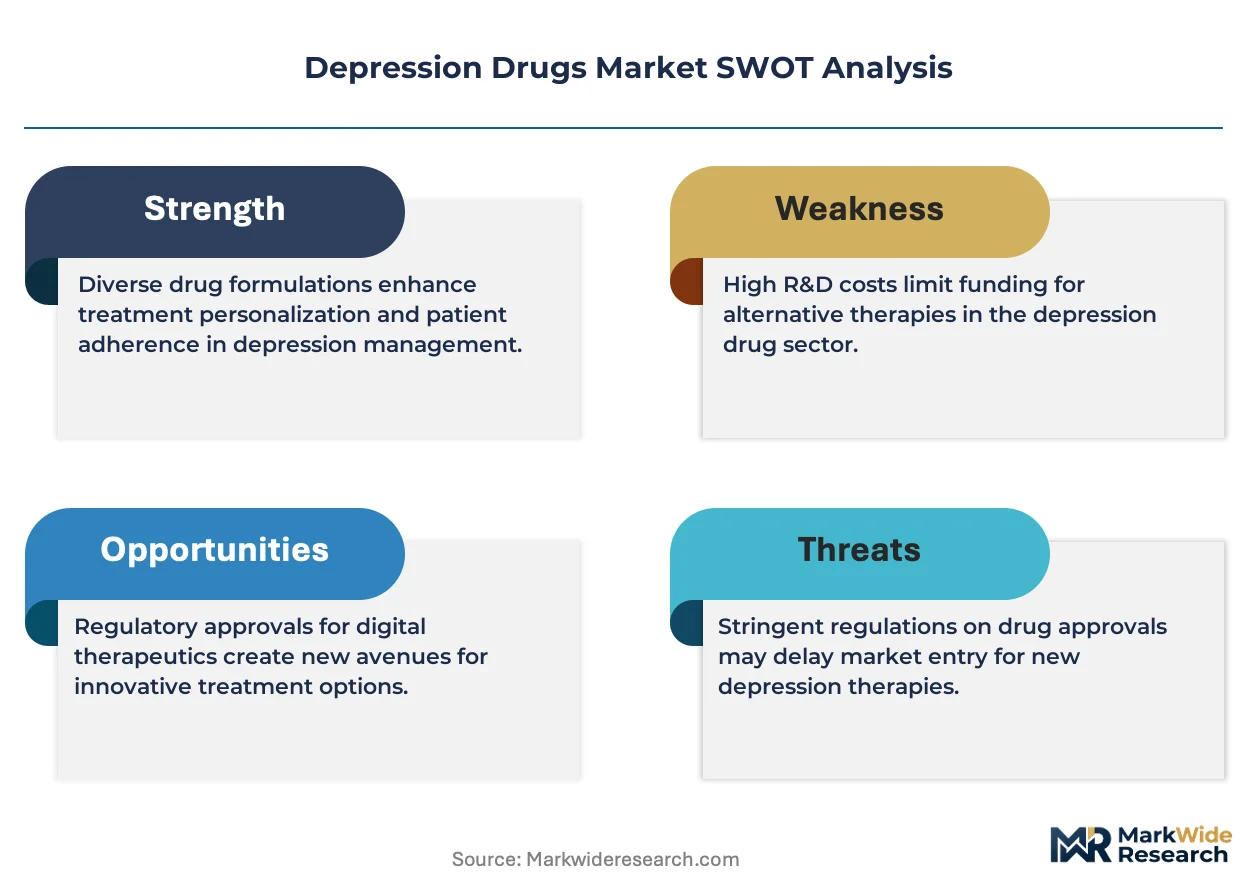
- Reimbursement Compression:Generic SSRI saturation limits pricing power for established mechanisms. Payers mandate step-therapy protocols that delay novel therapy access.
- Clinical Trial Complexity:Placebo response variability in depression endpoints inflates sample size requirements. Recruitment costs for adequate powered studies strain development budgets.
Strategic Opportunities
- Digital Therapeutic Adjunction:FDA guidance on software-as-medical-device integration creates parallel reimbursement pathways. Prescription digital therapeutics for cognitive behavioral augmentation are entering formularies.
- Immunology-Psychiatry Convergence:Anti-inflammatory mechanisms targeting cytokine-mediated depression phenotypes represent mechanistic white space. Research platforms combining psychiatric and immunologic expertise are attracting venture funding.
- Extended-Release Depot Formulations:Long-acting injectable antipsychotics for bipolar depression reduce adherence failure and hospitalization recurrence. Community mental health centers are expanding injection capacity.
Industry Challenges
- Specialized Psychiatry Talent Scarcity:Clinical trial investigators with psychopharmacology expertise are concentrated at academic sites. Site activation timelines extend due to principal investigator availability constraints.
- Biomarker Validation Gaps:Predictive markers for treatment response lack regulatory qualification. Sponsors face uncertainty in patient selection strategy for registrational programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depression Drugs Market |
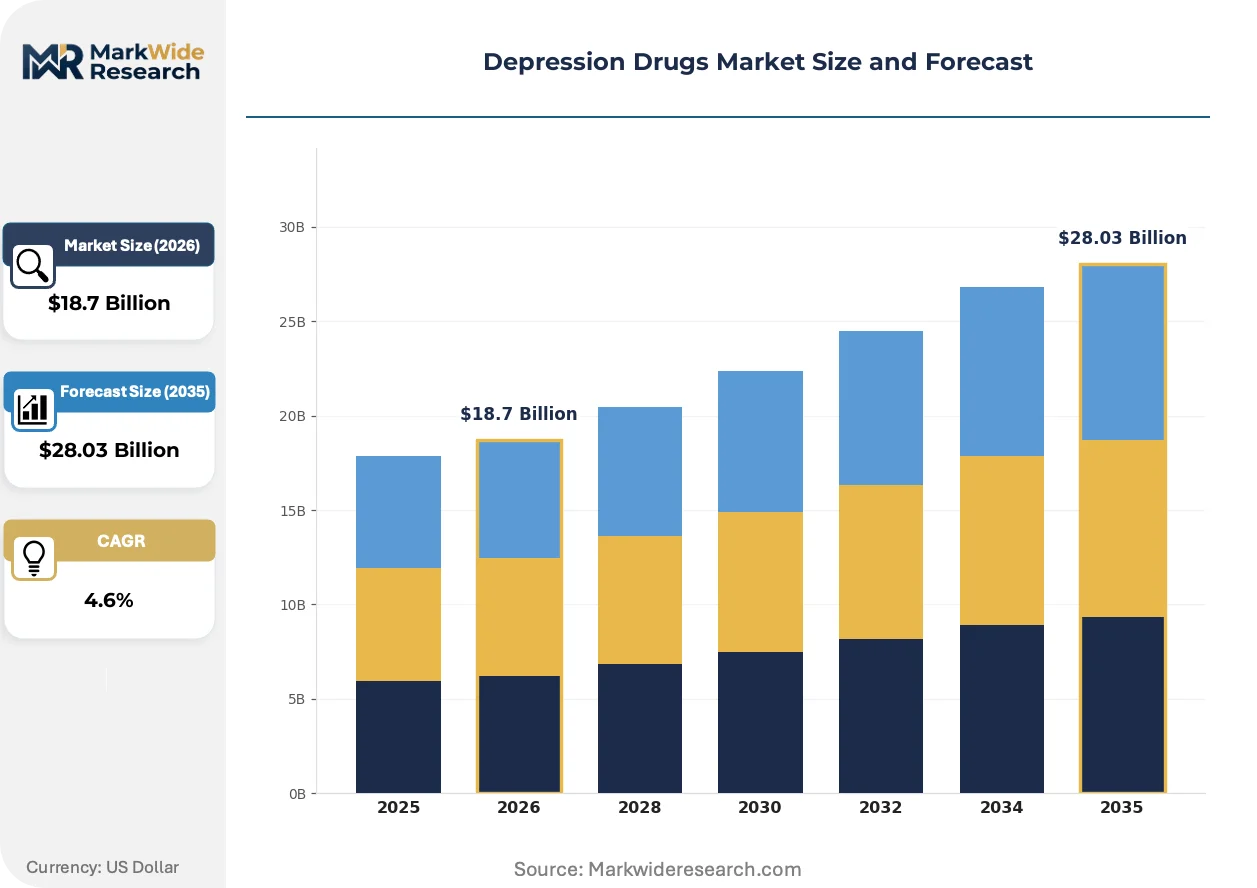
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Atypical Antipsychotics, Tricyclics Therapy Area: Major Depressive Disorder, Seasonal Affective Disorder, Dysthymia, Bipolar Disorder Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Pfizer, Eli Lilly and Company, AstraZeneca, GlaxoSmithKline, Johnson & Johnson, Novartis, Otsuka Pharmaceutical, Takeda Pharmaceutical Company, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depression Drugs Market Strategic Shifts & Innovations
Antidepressant development is virtualizing around rapid-onset mechanisms and digital integration, with regulatory frameworks adapting to accommodate novel administration routes and adjunctive technologies.
Intranasal esketamine and related rapid-acting glutamatergic modulators are virtualizing the acute care pathway for suicidal ideation. Psychiatric emergency services and crisis stabilization units are adopting these formulations as standard-of-care alternatives to inpatient admission. The technology is virtualizing traditional 4-6 week onset expectations into hours-to-days response windows.
EMA centralized procedures with divergent national pricing negotiations are fragmenting commercial strategy across European member states. Manufacturers must submit parallel health technology assessments while navigating Germany's AMNOG early benefit review and France's HAS transparency committee. Smaller markets with limited psychiatric infrastructure are experiencing delayed access as sponsors prioritize higher-reimbursement jurisdictions.
Hospital formularies are consolidating purchasing around integrated mental health service lines rather than discrete drug categories. Accountable care organizations and behavioral health carve-outs are negotiating bundled payment arrangements that include pharmacotherapy, psychotherapy, and care coordination. The United States exhibits the most pronounced concentration of specialty mental health prescribing authority within consolidated delivery systems.
Depression Drugs Market Segmentation
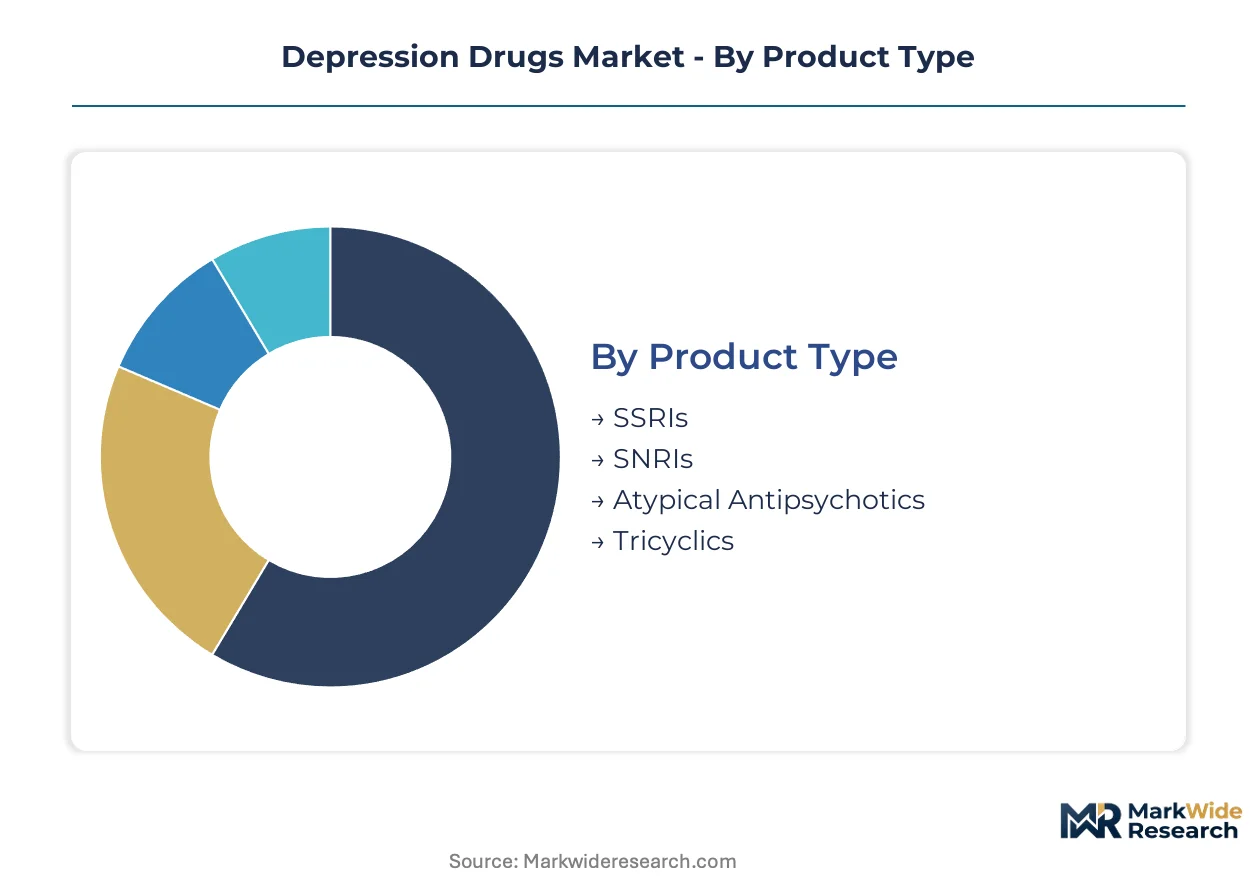
Depression drug segmentation reveals how formulation science, clinical setting requirements, and reimbursement structures fragment commercial opportunity. Each dimension carries distinct regulatory, manufacturing, and competitive implications that shape portfolio strategy.
Product Type:
Mature mechanisms dominate volume while novel targets capture premium positioning and fastest label expansion.
- SSRIs:First-line selective serotonin reuptake inhibitors with extensive generic substitution. Demand concentrates in primary care settings across the United States where step-therapy protocols mandate initial trial before novel mechanisms.
- Atypical Antipsychotics:Second-generation dopamine-serotonin modulators with established bipolar depression indications. Academic medical centers and specialty psychiatric hospitals drive adoption where reimbursement supports augmentation therapy.
- SNRIs:Dual reuptake inhibitors with chronic pain comorbidity advantages.
- Tricyclics:Legacy monoamine modulators with narrow therapeutic indices limiting new prescribing.
SSRIs retain volume leadership; atypical antipsychotics hold the steepest expansion curve.
Therapy Area:
Diagnostic specificity determines trial design complexity and regulatory pathway selection.
- Major Depressive Disorder:The largest addressable population with heterogeneous symptom profiles. FDA breakthrough therapy designations for treatment-resistant subpopulations are accelerating novel mechanism reviews.
- Bipolar Disorder:Mania-depression cycling requires mood stabilizer co-therapy. Lithium augmentation protocols at Veterans Affairs facilities and state hospital systems sustain demand for antipsychotic adjuncts.
- Seasonal Affective Disorder:Phototherapy adjunctive prescribing with limited dedicated drug development.
- Dysthymia:Persistent depressive disorder with chronic maintenance therapy patterns.
Major depressive disorder commands the largest patient pool; bipolar disorder shows the most rapid mechanism diversification.
Delivery Mode:
Route of administration directly shapes site-of-care economics and patient adherence profiles.
- Oral:Immediate and extended-release tablets with established bioequivalence frameworks. Retail pharmacy dispensing dominates outpatient maintenance therapy across commercial and Medicare Part D formularies.
- Intranasal:Rapid-onset glutamatergic modulators for acute suicidal ideation. Psychiatric emergency departments at crisis stabilization facilities are building supervised administration protocols.
- Injectable:Long-acting depot formulations for adherence-challenged populations.
- Transdermal:Steady-state delivery with reduced gastrointestinal side effects.
Oral formulations sustain volume dominance; intranasal delivery is climbing the fastest with emergency psychiatry adoption.
End User:
Care setting fragmentation creates divergent procurement and reimbursement pathways.
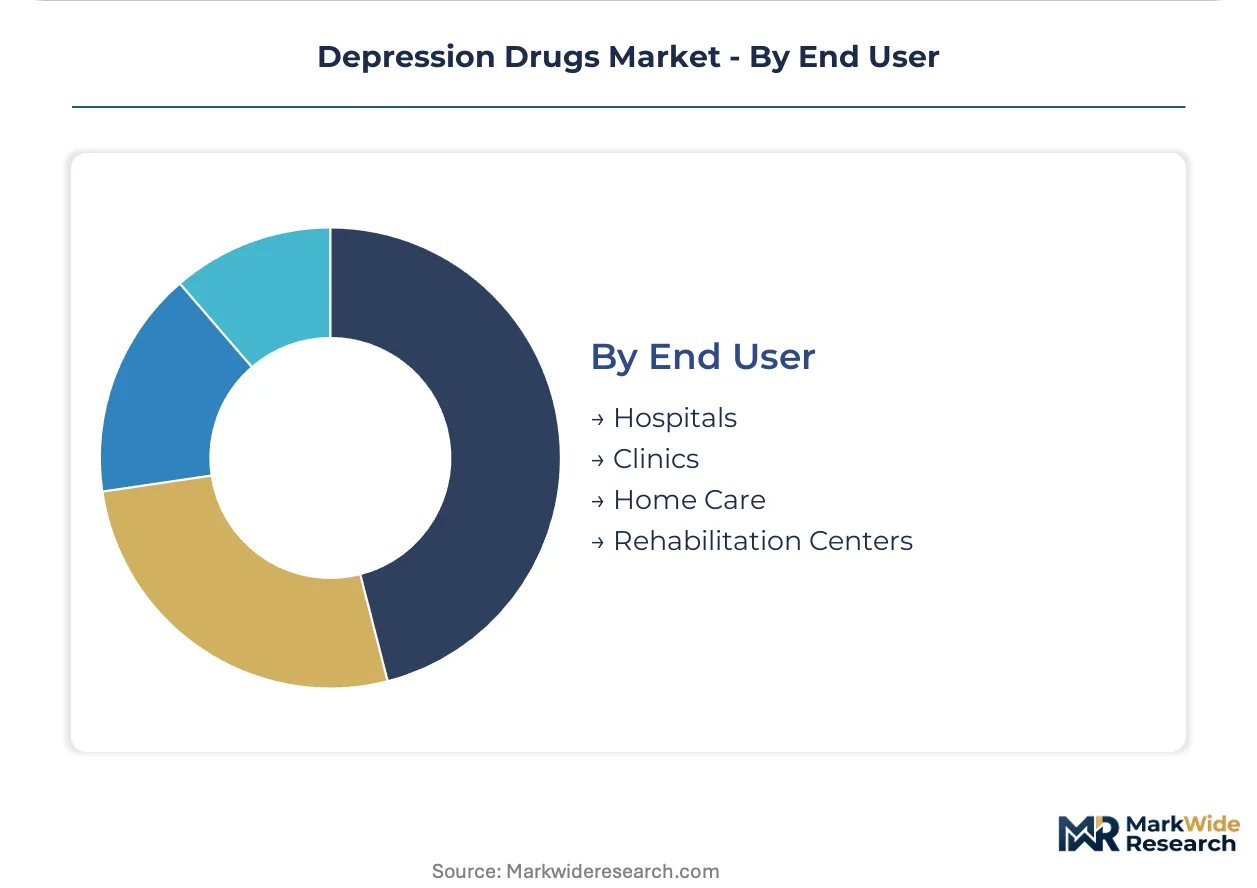
- Hospitals:Inpatient psychiatric units and emergency departments with 340B pricing exposure. Academic medical centers with NIH-funded research programs pilot novel rapid-acting therapies.
- Clinics:Outpatient mental health centers with bundled behavioral health payments. Federally qualified health centers in underserved counties are expanding prescriber capacity through telepsychiatry integration.
- Home Care:Long-acting injectable administration and medication management services.
- Rehabilitation Centers:Substance use disorder co-occurring treatment programs.
Hospitals anchor institutional purchasing volume; clinics are gaining share fastest with community-based care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's distribution reach for temperature-sensitive psychotropic compounds. This logistics backbone connects API synthesis clusters to formulation facilities across the continent.
United States
Specialty mental health prescribing concentrates within consolidated delivery systems and academic medical centers. FDA's accelerated approval pathways for novel antidepressant mechanisms compress development timelines for treatment-resistant populations. The Research Triangle Park corridor in North Carolina anchors psychopharmacology clinical trial infrastructure with NIH-funded investigator networks.
Germany
AMNOG early benefit review procedures shape reimbursement negotiations for new depression therapies entering statutory health insurance formularies. EMA centralized procedures govern market access while divergent national pricing creates commercial complexity. The Rhine-Main biotech cluster around Frankfurt sustains neuroscience research platforms with venture capital backing.
Japan
PMDA's Sakigake designation system accelerates regulatory review for innovative antidepressant mechanisms addressing unmet need. Aging demographics expand the addressable patient pool for mood disorder pharmacotherapy. The Kansai pharmaceutical manufacturing belt surrounding Osaka maintains active ingredient synthesis capacity for complex psychotropic intermediates.
Switzerland
Swissmedic's streamlined review procedures attract neuroscience-focused sponsors seeking efficient European market entry. Basel's cross-border biopharma ecosystem leverages proximity to German and French regulatory expertise. The country's precision manufacturing base supports high-potency API production for specialized depression indications.
India
CDSCO's New Drugs and Clinical Trials Rules streamline investigational new drug approvals for multinational sponsors. Contract research organizations in Hyderabad and Bangalore virtualize patient recruitment for global depression trials through telepsychiatry networks. Domestic API manufacturers supply generic SSRI intermediates to formulation facilities worldwide.
Depression Drugs Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with targeted mechanism expertise. The vendor base organizes around three archetypes: diversified pharmaceutical conglomerates with neuroscience heritage, mid-cap firms with single-therapeutic-focus pipelines, and emerging biotechs with novel receptor-targeting platforms. Consolidation pressures favor entities with backward integration into key intermediate synthesis and established psychiatric prescriber relationships. Competitive moves concentrate on strategic partnerships for digital therapeutic adjunction and capacity expansion for rapid-onset formulation manufacturing.
Within the diversified pharmaceutical tier, Eli Lilly and Company and Pfizer occupy positions reflecting distinct strategic emphases. AbbVie sits within the immunology-psychiatry convergence space with research platforms spanning inflammatory mechanisms. These entities exemplify how neuroscience R&D heritage and manufacturing integration anchor competitive positioning in a market where reimbursement complexity and regulatory pathway selection determine commercial viability.
| Leading Market Players |
|---|
| Pfizer |
| Eli Lilly and Company |
| AstraZeneca |
| GlaxoSmithKline |
| Johnson & Johnson |
| Novartis |
| Otsuka Pharmaceutical |
| Takeda Pharmaceutical Company |
| AbbVie |
| Others |
Cost & Logistics Intelligence
Indian and Chinese API manufacturing clusters for complex psychotropic intermediates anchor cost structures for downstream formulation facilities. Margin pools concentrate with sponsors who have secured captive supply of ketamine-derived precursors and extended-release depot polymers.
Pricing Analysis
FDA's breakthrough therapy designation dictates the pricing tier structure for novel antidepressant mechanisms, separating premium rapid-onset formulations from generic SSRI maintenance therapy. Price differentiation rests on administration route complexity and reimbursement coding novelty, with intranasal delivery commanding specialty pharmacy margins while oral generics face Medicare Part D compression. Pricing pressure intensifies in established mechanisms as step-therapy protocols mandate generic trial periods. Hospital systems exhibit lowest price sensitivity for acute crisis formulations; primary care settings show highest sensitivity to monthly therapy costs.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk planning for SSRI intermediate sourcing. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland, drawing from specialized fermentation feedstocks and high-potency chemical precursors. Single-source vulnerability persists for esketamine-derived compounds and long-acting injectable polymers. Distribution runs through temperature-controlled logistics networks connecting Rotterdam's pharmaceutical cold-chain hub to European formulation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation and integrated mental health service line purchasing. Three health system archetypes now control formulary access for novel mechanisms.
For Market Incumbents: Build regulatory data exclusivity moats through biomarker qualification partnerships with FDA. Secure backward integration into ketamine precursor synthesis to defend against API supply disruption. Expand manufacturing capacity in Research Triangle Park to anchor clinical trial investigator relationships against emerging biotech competition. For New Entrants and Emerging Players: Rural and underserved county markets present the most penetrable geography for telepsychiatry-enabled prescribing platforms. Target federally qualified health centers with bundled payment arrangements for depression care. Pursue FDA's accelerated approval pathway for treatment-resistant subpopulations to bypass step-therapy barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty pharmaceutical platforms holding intranasal delivery infrastructure. Five-to-ten year viability hinges on digital therapeutic adjunction capabilities and immunology-psychiatry research platforms. Watch for inflection signals in biomarker-directed prescribing protocol adoption by major payers.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Partnership | FDA qualification of predictive response markers accelerates patient stratification for registrational trials. |
| Intranasal Manufacturing Scale-Up | Capacity expansion for rapid-onset formulations captures emergency psychiatry adoption curves. |
| Digital Therapeutic Licensing | Software-as-medical-device adjunction creates parallel reimbursement codes for cognitive behavioral augmentation. |
| Immunology Platform Acquisition | Anti-inflammatory mechanism expertise addresses cytokine-mediated depression phenotypes in white-space indications. |
| Extended-Release Depot Investment | Long-acting injectable capacity reduces adherence failure costs for community mental health centers. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions included treatment line, dosage form, administration route, patient population, and regional regulatory cluster. CAGRs derived from patent expiry schedules, generic entry modeling, and novel mechanism adoption curves. Forecast inputs incorporated DEA scheduling flexibility scenarios and biomarker-directed reimbursement policy evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich immunology platforms or digital therapeutic specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market