
 Allergic Conjunctivitis Market | 2026-2036
Allergic Conjunctivitis Market Size, Share, and Industry Trends Forecast 2026-2036
Allergic Conjunctivitis Market Intelligence
The proliferation of co-development and out-licensing agreements is rewriting the competitive landscape for novel therapies. This model allows smaller innovators like Ocular Therapeutix, Inc. to advance specialized drug delivery systems. Meanwhile, established giants such as Novartis AG leverage their extensive global distribution networks. Johnson & Johnson differentiates through its broad consumer health and prescription portfolio, covering multiple treatment modalities and distribution channels.
Allergic conjunctivitis is an ocular surface disease characterized by an IgE-mediated hypersensitivity reaction to specific allergens. This immune response triggers mast cell degranulation and the release of histamine, causing symptoms like itching and redness. Combination drugs are gaining share over single-action treatments such as antihistamines alone. Within therapy areas, treatments for seasonal allergies constitute the largest segment due to high prevalence, while perennial allergy treatments offer consistent, year-round revenue streams.
Market access hinges on clearance from bodies like the US FDA, Europe's EMA, and Japan's PMDA. These agencies enforce stringent requirements for clinical trial data on efficacy and safety, particularly for novel combination drugs and corticosteroids. The key decision for developers is balancing the high-cost, high-reward path of novel drug development against the lower-margin but stable generic and OTC product space.
Market Dynamics
The clinical pivot towards dual-action therapies that combine antihistamine and mast cell stabilizing properties represents the central market force. This shift away from single-mechanism treatments is redefining R&D priorities and influencing regulatory expectations for new product approvals.
Growth Catalysts
- Novel Drug Delivery:Preservative-free formulations are improving ocular tolerance and patient compliance, especially for chronic users who need frequent application.
- OTC Switch Approvals:The reclassification of prescription agents to over-the-counter status by regulators like the US FDA expands direct patient access.
- High Pollen Prevalence:Intense pollen seasons in geographies such as Japan sustain a large, predictable demand base for effective seasonal allergy treatments.
Market Restraints
- Generic Erosion:Patent expiries for major drugs allow low-cost generic alternatives, compressing pricing and margins for branded product manufacturers.
- Stringent Clinical Hurdles:High evidence standards from the EMA and PMDA for demonstrating superiority over existing therapies increase R&D costs and timelines.
- Corticosteroid Side Effects:Risks like increased intraocular pressure limit long-term corticosteroid use, restricting them to severe, short-term cases.
Strategic Opportunities
- Emerging Economies:Rising incomes and healthcare access in Latin America and Southeast Asia create new growth frontiers for branded allergy treatments.
- Digital Health Integration:Coupling therapies with mobile apps for pollen tracking and symptom logging improves patient adherence and creates digital service opportunities.
- Perennial Allergy Focus:Developing specific treatments for year-round perennial allergies offers a stable revenue stream compared to seasonal product sales cycles.
Industry Challenges
- Patient Education and Compliance:Ensuring patients correctly differentiate allergic conjunctivitis from other conditions like dry eye or infection and adhere to treatment regimens remains a persistent public health challenge.
- Complex Reimbursement Pathways:Navigating disparate reimbursement systems and formularies across different countries and insurance providers complicates market access strategies and can limit patient uptake of novel therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergic Conjunctivitis Market |
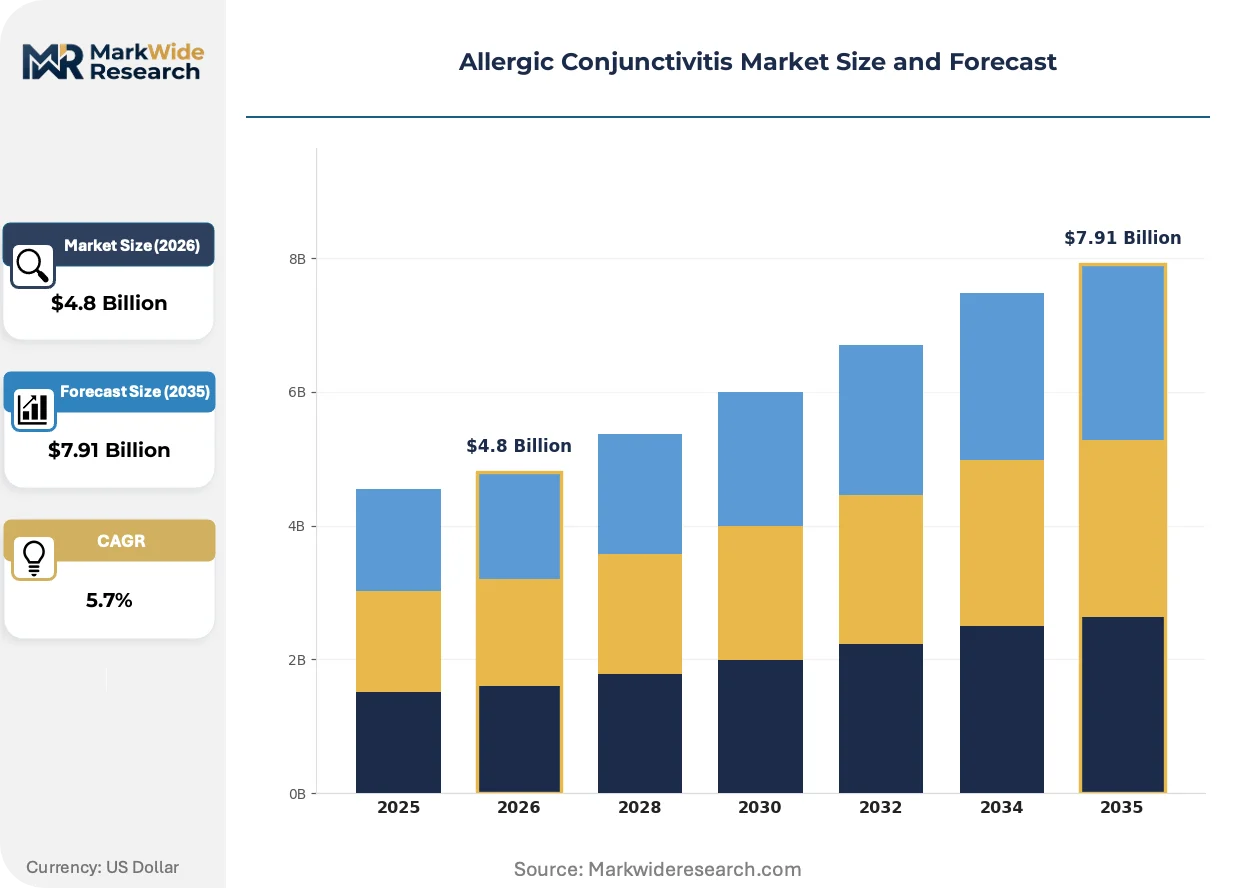
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Mast Cell Stabilizers, Corticosteroids, Decongestants, Combination Drugs Therapy Area: Seasonal Allergies, Perennial Allergies, Atopic Keratoconjunctivitis, Vernal Keratoconjunctivitis End User: Ophthalmic Clinics, Eye Hospitals, Ambulatory Surgery Centers, Specialty Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Alembic Pharmaceuticals Ltd, Ocular Therapeutix, Inc., Novartis AG, Alcon Inc., Bausch Health Companies Inc., Johnson & Johnson, Teva Pharmaceutical Industries Ltd, AbbVie Inc., Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergic Conjunctivitis Market Strategic Shifts & Innovations
A drive for greater therapeutic precision is fundamentally altering the allergic conjunctivitis treatment paradigm. Innovations in drug delivery, evolving regulatory frameworks, and shifting patient behaviors are collectively pushing the market beyond one-size-fits-all solutions toward more personalized care.
Sustained-release drug delivery platforms, like bioresorbable implants or punctal plugs, provide a consistent therapeutic dose over extended periods. Ophthalmic specialists adopt these for patients with poor compliance to daily eye drop regimens. This technology is rendering obsolete the need for frequent self-dosing, improving long-term disease management for specific patient cohorts.
The European Medicines Agency's (EMA) growing emphasis on real-world evidence (RWE) in regulatory decision-making represents a significant policy shift. This change requires pharmaceutical developers to collect and analyze data from routine clinical practice, supplementing traditional randomized controlled trials. Combination therapies are most affected, as RWE can better demonstrate their value and safety profile in complex, real-world patient populations.
Patients are increasingly self-diagnosing and seeking treatment advice from pharmacists or through online telehealth services, bypassing primary care physicians. This behavior elevates the role of over-the-counter products and direct-to-consumer marketing, disrupting traditional prescription pathways for mild-to-moderate cases. The trend is most pronounced in markets like the United States and the UK, where pharmacy access and digital health adoption are high.
Allergic Conjunctivitis Market Segmentation
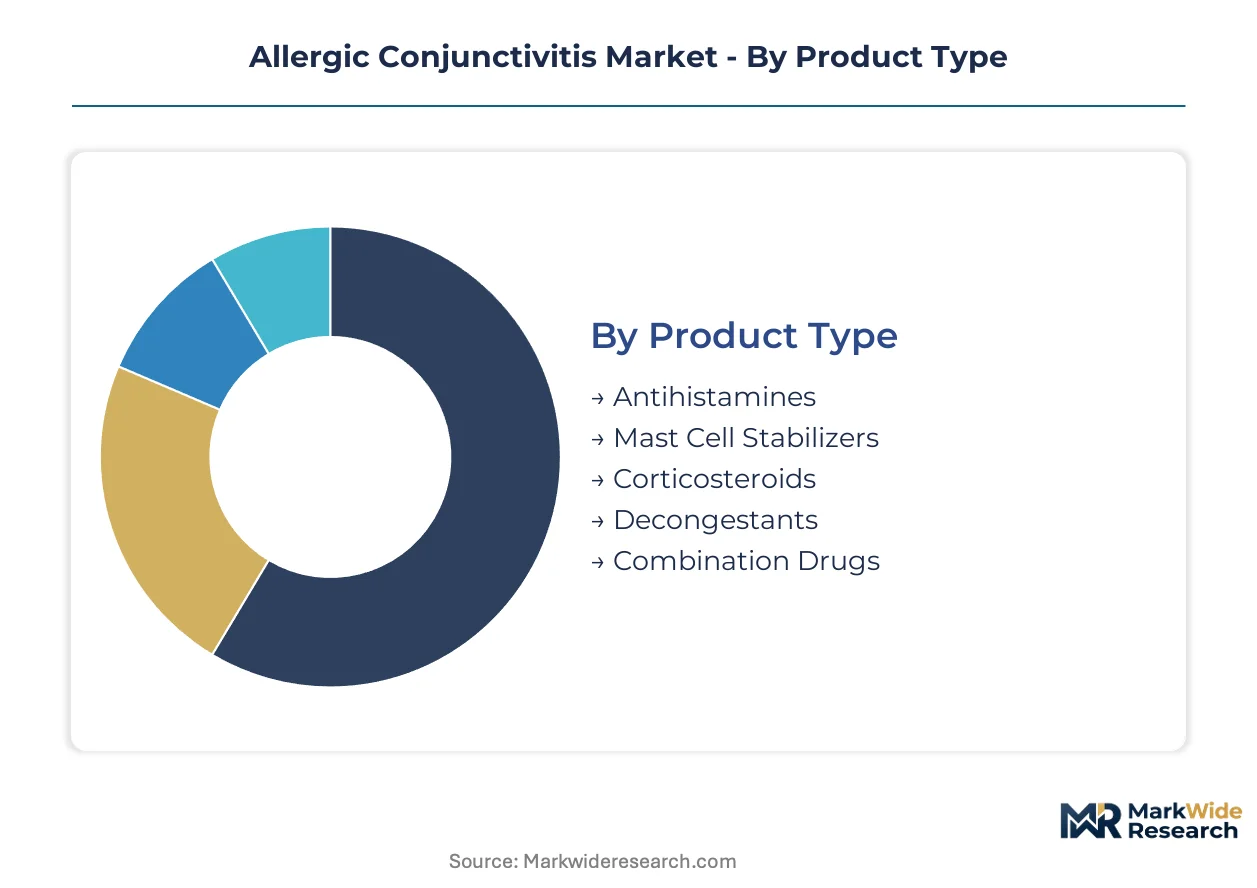
Understanding the Allergic Conjunctivitis Market requires a detailed breakdown of its constituent parts. This segmentation reveals the varying product preferences, patient needs, and access points influencing therapeutic adoption. Analyzing these distinct segments helps stakeholders tailor strategies for drug development and market penetration.
Product Type:
The spectrum of product types available dictates the level of ongoing patient support and monitoring required, influencing clinical practice intensity.
- Combination Drugs:These formulations integrate multiple active ingredients, often an antihistamine and a mast cell stabilizer, to provide dual-action relief. Demand concentrates in ophthalmic clinics seeking comprehensive, single-product solutions for patients with persistent or severe symptoms.
- Corticosteroids:These potent anti-inflammatory agents are reserved for severe, acute allergic conjunctivitis due to their potential for side effects like increased intraocular pressure. Eye hospitals often prescribe them for short-term management of intense inflammation.
- Antihistamines:These block histamine receptors to alleviate immediate symptoms like itching and redness.
- Mast Cell Stabilizers:These prevent mast cell degranulation, reducing the release of inflammatory mediators over time.
- Decongestants:These vasoconstrictors reduce eye redness but offer no anti-allergic effect.
By volume, Antihistamines lead due to their widespread availability. By growth pace, Combination Drugs are ahead, driven by their enhanced efficacy.
Therapy Area:
The primary therapy area determines the duration and intensity of treatment, directly influencing patient adherence and product formulation needs.
- Seasonal Allergies:This segment addresses allergic reactions triggered by airborne allergens present during specific times of the year, such as pollen. Demand is particularly high in regions like Japan, where distinct pollen seasons drive predictable spikes in patient visits.
- Perennial Allergies:These year-round allergies are caused by allergens like dust mites or pet dander, requiring consistent, long-term therapeutic management. This segment offers stable revenue streams for pharmaceutical companies due to continuous patient needs.
- Atopic Keratoconjunctivitis:This severe, chronic form of allergic conjunctivitis often accompanies atopic dermatitis, requiring aggressive management.
- Vernal Keratoconjunctivitis:A rare, severe, and recurrent inflammation primarily affecting children and young adults, often requiring specialized care.
Perennial Allergies provide a consistent revenue stream, while Seasonal Allergies account for the largest patient volume.
End User:
The diverse end-user landscape reflects varying levels of clinical specialization and patient access points for allergic conjunctivitis treatments.
- Ophthalmic Clinics:These specialized outpatient facilities serve as a primary point of contact for routine allergic conjunctivitis diagnosis and ongoing management. Demand from these clinics is a significant driver for effective, patient-friendly treatment options.
- Eye Hospitals:These larger institutions handle more complex or severe cases requiring advanced diagnostics, surgical interventions, or intensive medical management. They often stock a broader range of prescription-strength medications.
- Ambulatory Surgery Centers:These facilities focus on outpatient surgical procedures, occasionally managing severe allergic conjunctivitis cases requiring minor interventions.
- Specialty Clinics:These clinics may include allergy specialists or pediatric ophthalmologists, catering to specific patient demographics or complex conditions.
Ophthalmic Clinics command the largest share of patient visits, while Eye Hospitals address the most critical cases.
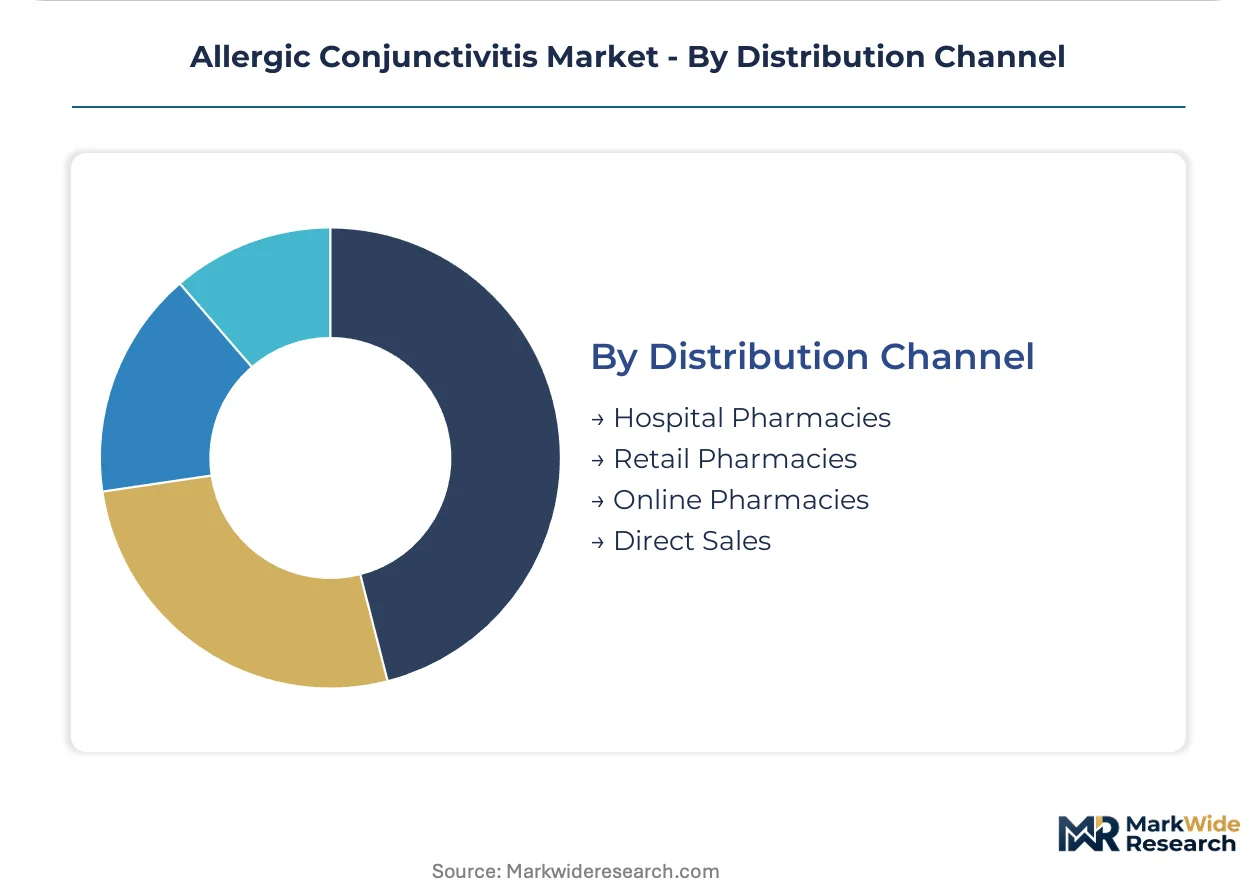
Distribution Channel:
The evolution of distribution channels mirrors regulatory shifts and consumer preferences, especially concerning accessibility and convenience.
- Retail Pharmacies:These outlets provide widespread access to both prescription and over-the-counter allergic conjunctivitis treatments, benefiting from OTC switch approvals. Patient self-diagnosis and pharmacist advice drive significant sales through this channel.
- Online Pharmacies:This channel capitalizes on increasing digital health integration and patient preference for convenience, offering direct-to-consumer delivery of medications. Telehealth consultations often precede purchases through online platforms in markets like the United States.
- Hospital Pharmacies:These pharmacies primarily dispense medications for inpatients or those receiving care within the hospital system.
- Direct Sales:This channel involves manufacturers selling directly to healthcare providers or institutions, often for specialized or high-volume products.
Retail Pharmacies ensure broad market penetration, while Online Pharmacies offer expanding reach and efficiency for consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory bodies globally prioritize patient access to advanced therapies for allergic conjunctivitis. This focus drives pharmaceutical innovation and market expansion across key regions. Governments are implementing policies to accelerate approvals for novel drug formulations, enhancing therapeutic availability.
United States
The United States experiences significant demand driven by a high prevalence of seasonal allergies and a robust consumer health market. US FDA approvals for over-the-counter switches have expanded patient access, particularly for mild-to-moderate cases. The Boston-Cambridge biotech hub remains a critical center for ophthalmic R&D, fostering novel drug delivery systems.
Japan
Japan faces persistent demand due to its intense pollen seasons, creating predictable spikes in seasonal allergic conjunctivitis cases. The PMDA enforces strict efficacy and safety standards for new ophthalmic drugs, influencing localized R&D. Tokyo's pharmaceutical research centers actively develop advanced allergy treatments tailored to the Japanese population.
Germany
German demand for allergic conjunctivitis treatments stems from an aging population and increasing exposure to environmental allergens. EMA guidelines significantly shape clinical trials and market authorization processes for novel combination therapies. Frankfurt's pharmaceutical industry focuses on specialized drug formulations, including preservative-free options for chronic users.
India
India's market expansion is driven by rising incomes and improving healthcare access, alongside diverse allergen exposure across its regions. The CDSCO regulates drug approvals, balancing affordability with the adoption of therapeutic innovations. Hyderabad's pharmaceutical manufacturing cluster produces both branded and generic ophthalmic solutions for domestic and export markets.
China
China's market growth is influenced by rapid urbanization, increasing pollution levels, and growing patient awareness of allergic conditions. The NMPA prioritizes local drug development and ensures stringent product quality standards for ophthalmic treatments. Shanghai's biotech parks attract significant investment in ocular drug discovery and development programs.
Allergic Conjunctivitis Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic competitive landscape in the allergic conjunctivitis market. The market structure exhibits a tiered consolidation, with established pharmaceutical giants leveraging extensive distribution networks for widespread product reach. Smaller innovators focus on specialized drug delivery systems and novel formulations, often through co-development and out-licensing agreements to accelerate market entry. Strategic partnerships, portfolio diversification, and geographic expansion are dominant competitive moves, extending market reach and therapeutic offerings across different patient segments.
Established pharmaceutical giants, such as Swiss-based Novartis AG, leverage extensive global distribution networks to maintain market presence across various therapeutic areas within allergic conjunctivitis. US-based Ocular Therapeutix, Inc. represents a specialized innovator, focusing on advancing novel drug delivery systems like sustained-release platforms for ophthalmic conditions. Johnson & Johnson, a diversified US corporation, occupies a position bridging broad consumer health and prescription portfolios, covering multiple treatment modalities and distribution channels for a wide patient base. These players exemplify the strategic differentiation observed across the industry.
| Leading Market Players |
|---|
| Alembic Pharmaceuticals Ltd |
| Ocular Therapeutix, Inc. |
| Novartis AG |
| Alcon Inc. |
| Bausch Health Companies Inc. |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd |
| AbbVie Inc. |
| Sun Pharmaceutical Industries Ltd |
| Others |
Cost & Logistics Intelligence
Specialized cold chain logistics networks, crucial for ophthalmic pharmaceuticals, significantly influence supply concentration and downstream price differentiation. The cost dynamics of these complex distribution pathways impact the final pricing of novel preservative-free formulations, especially across diverse international markets.
Pricing Analysis
FDA-grade certification creates the primary spread in allergic conjunctivitis treatment pricing. The dominant pricing structure for novel therapies is value-based, often incorporating contract agreements for institutional buyers. Clinical efficacy and specialized preservative-free formulations drive significant price differentiation. Pricing pressure stems from the increasing availability of low-cost generic alternatives. Individual consumers purchasing over-the-counter products are most price-sensitive, while eye hospitals acquiring advanced combination drugs are less sensitive.
Supply Chain Analysis
Upstream pharmaceutical raw material sourcing for active pharmaceutical ingredients (APIs) primarily draws from India, China, and the United States. Key component dependencies include specialized sterile packaging and specific excipients for ophthalmic solutions. A structural risk involves regulatory bottlenecks for novel drug components, delaying market entry. Distribution runs through a multi-channel model, leveraging retail pharmacies, hospital networks, and expanding online platforms to reach diverse patient cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market faces a strategic gap in integrated patient management solutions. This deficiency highlights the need for advanced digital health and adherence platforms that can bridge the patient-provider communication divide.
For Market Incumbents: Build a robust intellectual property moat around novel combination therapies. Expand global distribution networks to counter emerging regional players and generic erosion. Invest in R&D for sustained-release platforms, offering long-term patient compliance benefits. Leverage co-development agreements to access specialized drug delivery technologies and accelerate market reach.
For New Entrants and Emerging Players: Pursue niche segments with unmet needs in perennial allergies, offering consistent revenue streams. Target underserved emerging economies in Latin America and Southeast Asia with accessible formulations. Focus on digital health integration for patient support and symptom tracking as a key go-to-market angle. Develop specialized drug delivery for chronic users who struggle with daily eye drop regimens.
For Investors and Strategic Acquirers: Specialized drug delivery innovators offer significant long-term growth potential over the next decade. Prioritize companies with advanced ophthalmic drug delivery platforms or strong regional distribution capabilities. The signal to watch is successful clinical trial readouts for sustained-release devices, indicating future market disruption and acquisition value.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates novel combination drug efficacy and safety for regulatory approval. |
| Licensing Agreement | Accelerates market entry for specialized drug delivery systems and expands portfolio. |
| Manufacturing Scale-Up | Ensures consistent supply for high-demand preservative-free formulations. |
| Platform Integration | Couples therapies with digital health tools for improved patient adherence. |
| Geographic Expansion | Accesses new patient populations in emerging economies with rising healthcare access. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform the market analysis. Primary interviews with ophthalmic specialists, regulatory affairs leads, pharmaceutical R&D directors, and hospital procurement managers provided qualitative insights. Secondary validation utilized FDA filings, EMA submissions, clinical trial registries, and published industry reports, triangulating bottom-up and top-down data points.
Calibration involved cross-referencing historical market data with projected clinical pipeline developments across the analysis window. Segmentation dimensions included product type, therapy area, end user, distribution channel, and regional regulatory frameworks. Compound annual growth rates (CAGRs) were derived through regression analysis of demand drivers. Forecast inputs integrated prevalence of seasonal allergies and new drug approval rates.
Sensitivities concentrate around unforeseen regulatory changes or major generic drug launches. Forecasts reflect assumptions on clinical pipeline success rates and patient adherence trends. Cross-checking against national health statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market