
 Lipid-Lowering Drugs Market | 2026-2036
Lipid-Lowering Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Lipid-Lowering Drugs Market Outlook
High-efficacy LDL-C reduction thresholds above 50% is bifurcating the competitive landscape into premium biologic and conventional oral tiers. Amgen Inc. leverages its Repatha manufacturing scale to anchor the PCSK9 inhibitor segment in North American and European hospital channels. Sanofi competes through differentiated cardiovascular outcome data that sustains payer preference across European markets.
Lipid-lowering drugs comprise pharmacological agents that modulate cholesterol biosynthesis, intestinal absorption, or hepatic clearance to reduce atherosclerotic cardiovascular risk, with specifications typically measured by percent LDL-C reduction from baseline and safety margins against hepatotoxicity thresholds. Their primary commercial purpose centers on preventing myocardial infarction, stroke, and revascularization procedures in patients with familial hypercholesterolemia or established cardiovascular disease. Statins occupy the mature volume base with compressed margins, while PCSK9 inhibitors capture the fastest-growing revenue pool as injectable therapies penetrate high-risk patient cohorts. The oral administration route dominates total prescription volume, though injectable formats command disproportionate value per patient in hospital and specialty clinic settings.
FDA cardiovascular outcome trial requirements and EMA benefit-risk reassessment protocols shape clinical development costs and label expansion timelines for novel mechanisms. The EPA evaluates manufacturing effluent standards that constrain active pharmaceutical ingredient production geography. Stakeholders must monitor how CMS and national health technology assessment bodies recalibrate cost-effectiveness thresholds for combination therapy against intensified statin regimens.
Market Dynamics
FDA cardiovascular outcome trial mandates are compressing development timelines for novel mechanisms while hospital systems accelerate formulary adoption of injectable PCSK9 therapies, creating a bifurcated market structure between premium biologics and commoditized oral statins.
Growth Catalysts
- EMA Benefit-Risk Reassessment Protocols:These frameworks accelerate label expansions for therapies demonstrating superior cardiovascular outcomes, incentivizing manufacturers to pursue broader indications in European markets.
- Injectable Therapy Manufacturing Scale:Hospital systems in the United States are expanding centralized pharmacy capabilities to administer biologic lipid-lowering agents, reducing per-dose operational costs and improving patient adherence monitoring.
- Metabolic Disease Management Infrastructure:Germany and Japan are deepening specialty clinic networks that integrate lipid management with diabetes and obesity care, creating bundled reimbursement pathways for high-risk patient cohorts.
Market Restraints
- Active Pharmaceutical Ingredient Supply Concentration:EPA effluent standards constrain statin API production to specific manufacturing geographies, limiting supplier diversification and creating vulnerability to environmental compliance disruptions.
- Cost-Effectiveness Threshold Compression:CMS and national health technology assessment bodies are tightening incremental cost-effectiveness ratios for combination therapies against intensified statin regimens, squeezing pricing power for novel agents.
- Oral Formulation Substitution Threat:High-efficacy statin generics and ezetimibe combinations retain formulary preference in primary care settings, delaying biologic penetration into moderate-risk populations.
Strategic Opportunities
- Underpenetrated Familial Hypercholesterolemia Screening:Japan's healthcare system exhibits diagnostic gaps in genetic lipid disorders, presenting expansion potential for specialty diagnostic-pharmaceutical integration models.
- RNA Interference Technology Convergence:Combination of siRNA mechanisms with established PCSK9 pathways offers annual or biannual dosing regimens that could reshape adherence economics in United States specialty pharmacy channels.
- European Green Deal Manufacturing Incentives:EMA regulatory pathways prioritizing sustainable API production create first-mover advantages for manufacturers investing in continuous flow chemistry and solvent reduction technologies.
Industry Challenges
- Cardiovascular Outcome Trial Talent Scarcity:Recruitment of biostatisticians and clinical pharmacologists experienced in large-scale event-driven studies is constraining pipeline advancement timelines across multiple development programs.
- Legacy Formulary Integration Complexity:Hospital pharmacy information systems require substantial reconfiguration to accommodate cold-chain biologic inventory management alongside traditional oral dispensing workflows.
- Patent Thicket Navigation:Dense intellectual property surrounding PCSK9 epitope binding and formulation stability is forcing licensing negotiations that extend pre-commercialization phases by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipid-Lowering Drugs Market |
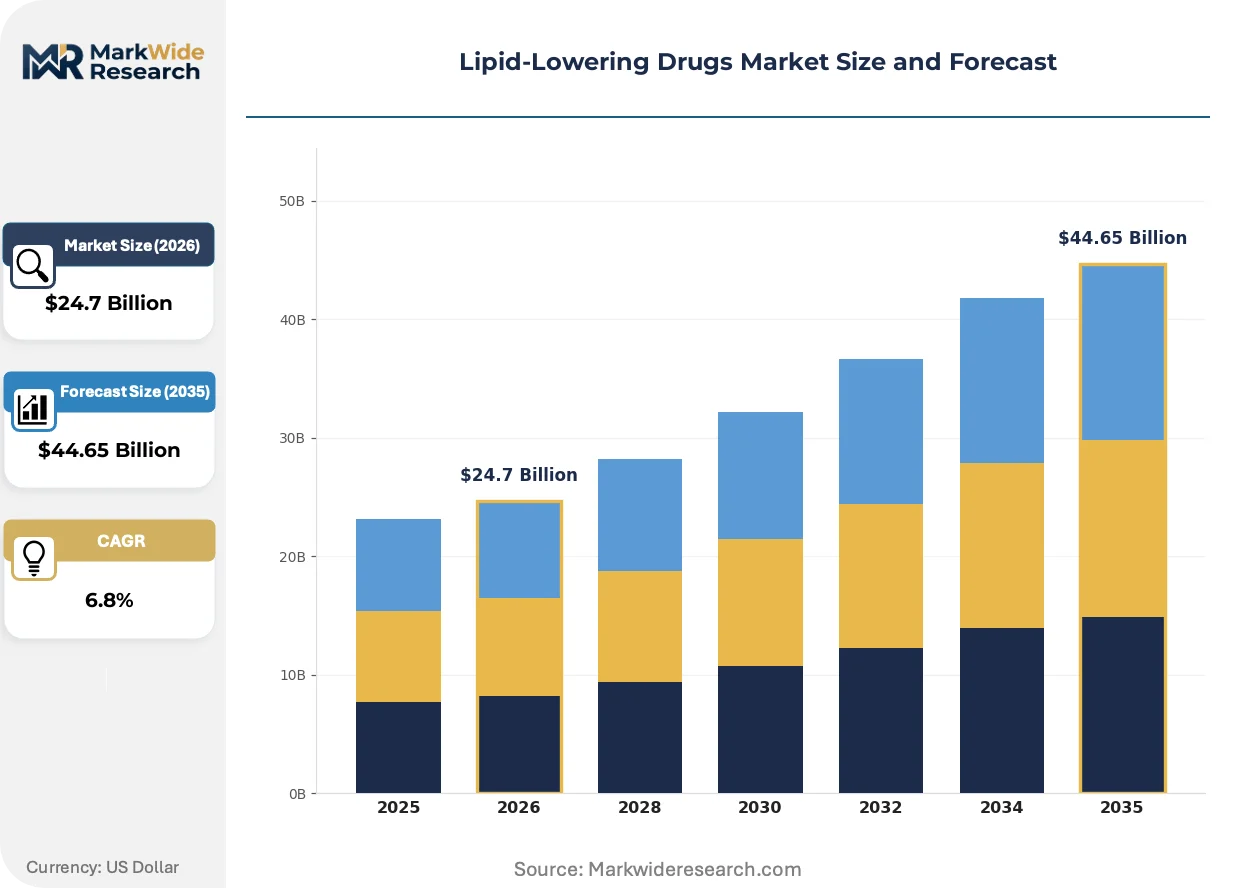
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, Ezetimibe, PCSK9 Inhibitors, Fibrates End User: Clinics, Hospitals, Homecare, Pharmacies Administration Route: Oral, Injectable, Transdermal, Inhalation Therapy Area: Cardiology, Diabetes Management, Prevention, Metabolic Disorders |
| Companies Covered | Amgen Inc., Novartis AG, AstraZeneca, AbbVie Inc., Daiichi Sankyo Company, Merck & Co., Sanofi, Regeneron Pharmaceuticals, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipid-Lowering Drugs Market Strategic Shifts
RNA-based therapeutic modalities are disrupting the established small-molecule and monoclonal antibody paradigm, with annual-dosing regimens threatening to collapse the chronic medication adherence model that has sustained statin economics for three decades.
Inclisiran, a small interfering RNA agent targeting PCSK9 hepatic synthesis, is supplanting biweekly or monthly monoclonal antibody injections in early-adopter United States health systems that prioritize pharmacy benefit management simplification and patient convenience metrics. Cardiology specialty clinics are consolidating their injectable lipid management protocols around this mechanism, compressing reimbursement bandwidth for competing antibody therapies and reshaping contracting dynamics with pharmacy benefit managers.
EMA's updated benefit-risk assessment guidelines for cardiovascular therapies now mandate real-world evidence collection through national registries, forcing manufacturers to embed electronic health record integration into post-marketing commitments. This regulatory evolution is accelerating partnerships between pharmaceutical developers and European hospital networks capable of generating longitudinal outcome data, with Germany's statutory health insurance funds demanding such evidence prior to premium reimbursement tiers.
Hospital procurement committees are unbundling drug acquisition from adherence monitoring services, creating separate vendor relationships for medication therapy management and clinical outcome tracking. This purchasing pattern shift is most visible in United States integrated delivery networks, where specialty pharmacies now compete on patient engagement platform capabilities rather than unit pricing alone, and where outcomes-based contracts require granular patient-level data sharing that legacy distribution channels cannot support.
Lipid-Lowering Drugs Market Segmentation
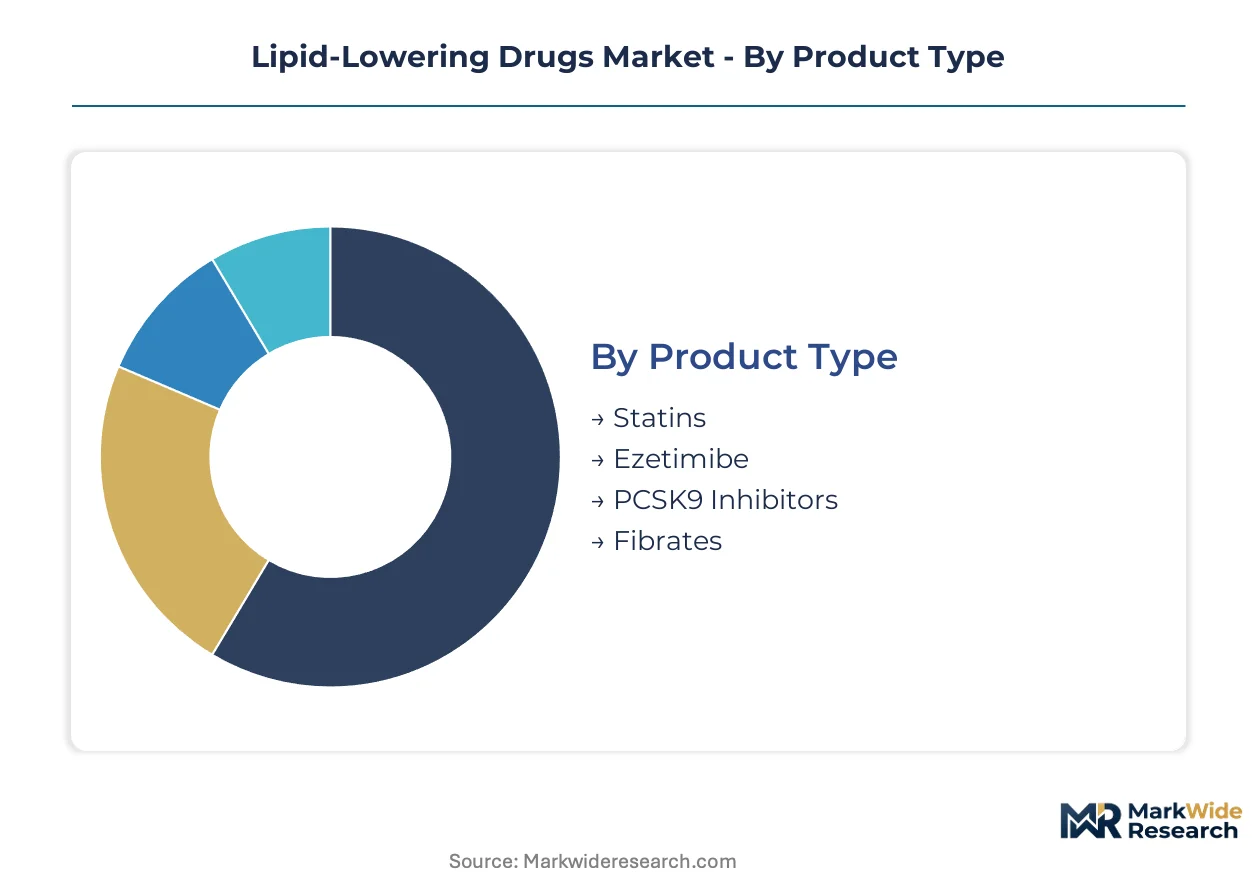
Segmentation reveals how substitution pressures fragment commercial opportunity across the lipid-lowering landscape. Manufacturers must align portfolio depth with channel-specific reimbursement mechanics and patient risk stratification protocols.
Product Type:
Generic statin saturation exerts the strongest substitution pressure, compressing margins and forcing differentiation through mechanism novelty or dosing convenience.
- Statins:HMG-CoA reductase inhibitors remain the volume foundation, with atorvastatin and rosuvastatin generics dominating primary care prescribing in the United States and Germany. Intensified regimens face reimbursement scrutiny as payers demand cardiovascular outcome documentation for dose escalation above standard thresholds.
- PCSK9 Inhibitors:Monoclonal antibodies and siRNA agents targeting hepatic PCSK9 clearance command premium positioning in hospital specialty clinics. United States integrated delivery networks prioritize these therapies for familial hypercholesterolemia and atherosclerotic cardiovascular disease patients failing statin-ezetimibe combinations.
- Ezetimibe:Intestinal cholesterol absorption inhibitor used predominantly in combination protocols.
- Fibrates:PPAR-alpha agonists addressing severe hypertriglyceridemia with narrower cardiovascular outcome evidence.
Statins anchor the volume base while PCSK9 inhibitors gain share at the steepest rate.
End User:
Channel cost structures determine which administration formats achieve formulary access, with centralized pharmacy capabilities favoring biologic handling.
- Hospitals:Academic medical centers and community hospital systems in the United States are consolidating injectable lipid management within specialty pharmacy operations. Cold-chain infrastructure investments and adherence monitoring platforms justify premium biologic acquisition despite higher per-dose costs.
- Clinics:Cardiology and endocrinology specialty practices in Japan and Germany integrate lipid panels with metabolic disease protocols. Bundled reimbursement for diabetes-obesity-lipid management creates prescribing incentives for high-efficacy agents.
- Homecare:Self-administered oral regimens dominate patient-managed therapy.
- Pharmacies:Retail dispensing concentrates on generic statin fulfillment with limited clinical intervention.
Hospitals capture the steepest biologic revenue expansion while pharmacies retain the prescription volume foundation.
Administration Route:
Patient adherence economics and pharmacy benefit design determine route selection, with convenience premiums reshaping competitive dynamics.
- Oral:Once-daily tablet and capsule formulations sustain the prescription volume majority across all risk strata. Germany's statutory health insurance funds maintain preference for oral first-line therapy, requiring documented failure before injectable authorization.
- Injectable:Subcutaneous monoclonal antibody and siRNA delivery enables biannual or quarterly dosing that collapses adherence gaps. United States specialty pharmacy channels compete on patient engagement platform sophistication to support these regimens.
- Transdermal:Patch-based delivery remains experimental with limited commercial penetration.
- Inhalation:No approved lipid-lowering agents currently utilize this route.
Oral administration commands prescription volume dominance while injectable formats climb the fastest in revenue contribution per patient.
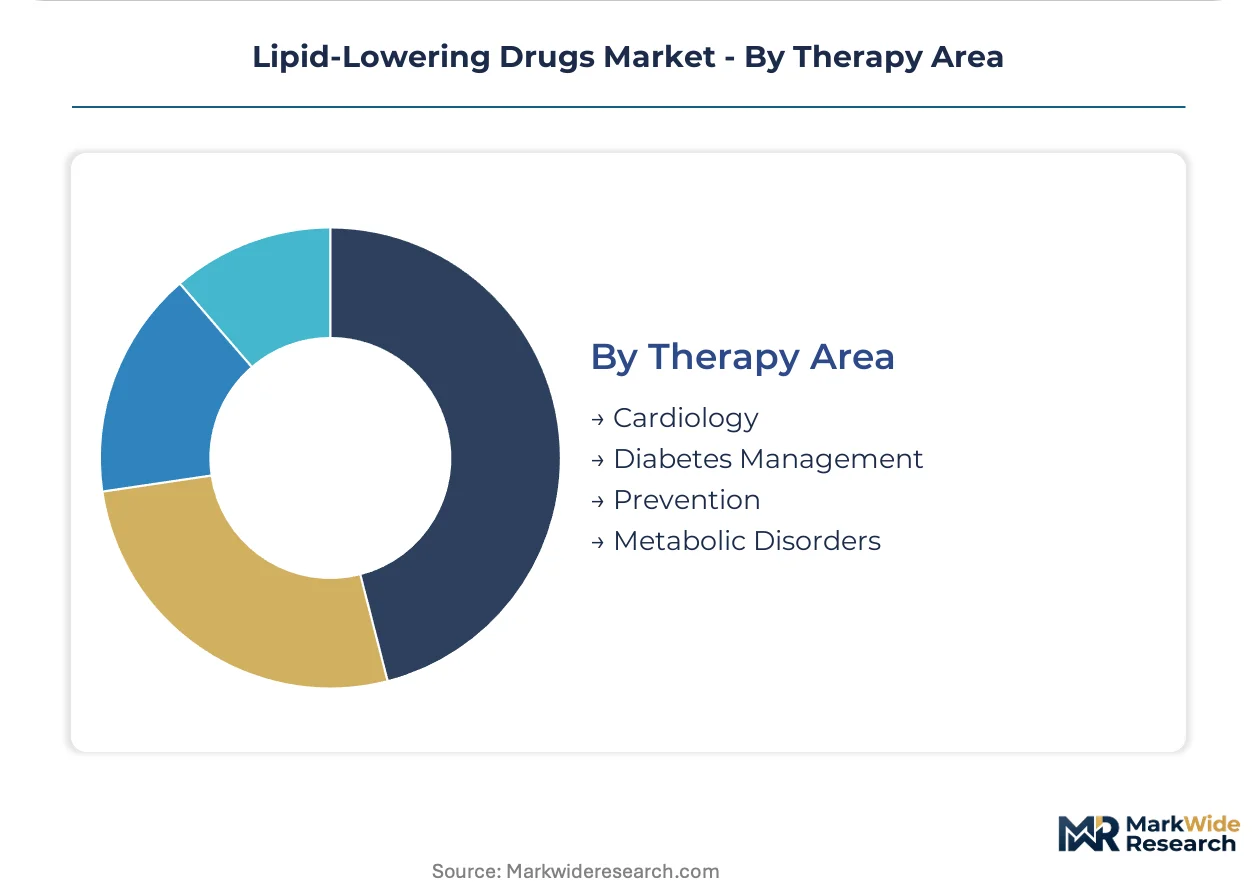
Therapy Area:
Comorbidity bundling in reimbursement policy determines which indications receive prioritized access and promotional investment.
- Cardiology:Secondary prevention of myocardial infarction and stroke represents the largest addressable population with established outcome trial requirements. FDA cardiovascular outcome mandates shape label claims and payer negotiation positioning for novel agents.
- Diabetes Management:Integrated metabolic protocols in Japan and Germany create reimbursement pathways for lipid-lowering agents prescribed alongside GLP-1 receptor agonists and SGLT2 inhibitors. Shared risk factors drive bundled care model adoption.
- Prevention:Primary prevention populations face stricter cost-effectiveness scrutiny from CMS and health technology assessment bodies.
- Metabolic Disorders:Familial hypercholesterolemia and rare lipid disorders command orphan pricing premiums with narrower patient pools.
Cardiology anchors commercial scale while diabetes management integration expands the fastest across European and Asia-Pacific reimbursement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for statin intermediates concentrates in coastal industrial zones where EPA effluent compliance infrastructure already exists. Hospital formulary expansion for injectable PCSK9 therapies is accelerating fastest in systems with established specialty pharmacy operations.
United States
Integrated delivery networks in Texas and Florida are consolidating lipid management within centralized pharmacy operations. FDA cardiovascular outcome trial mandates shape label expansion timelines for novel siRNA mechanisms. The Research Triangle and Greater Boston clusters host contract research organizations specializing in event-driven cardiovascular studies.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia require documented statin failure before authorizing biologic therapy. EMA benefit-risk reassessment protocols accelerate label expansions for therapies with superior outcome data. The Frankfurt-Rhine-Main corridor anchors pharmacovigilance operations for European cardiovascular registries.
Japan
Specialty clinic networks in Tokyo and Osaka integrate lipid panels with diabetes and obesity protocols under bundled reimbursement. PMDA reviews emphasize real-world evidence from national health insurance claims databases. The Kansai region exhibits diagnostic gaps in familial hypercholesterolemia screening that pharmaceutical-diagnostic partnerships target.
United Kingdom
NICE cost-effectiveness thresholds constrain PCSK9 inhibitor access to high-risk secondary prevention populations. The MHRA operates post-Brexit recognition pathways for EMA-approved cardiovascular therapies. London and Cambridge host biostatistics consultancies specializing in adaptive trial design for lipid-lowering agents.
Switzerland
Swissmedic's streamlined review pathways attract cardiovascular outcome trial submissions for orphan lipid disorders. Basel and Zurich anchor pharmaceutical manufacturing for high-potency biologic fill-finish operations. The country's statutory health insurance system maintains preference for oral first-line therapy with strict prior authorization for injectable alternatives.
Lipid-Lowering Drugs Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Large-cap biopharmaceutical conglomerates anchor the premium biologic segment through manufacturing scale and cardiovascular outcome data generation. Mid-sized specialty pharmaceutical firms occupy the oral generic and combination therapy tier with compressed margins but volume dominance. Competitive moves concentrate on strategic partnerships for real-world evidence generation and capacity expansion for cold-chain biologic distribution.
Within the large-cap biopharmaceutical tier, Amgen Inc. and Novartis AG exemplify divergent strategic positioning. Amgen anchors North American hospital channel penetration through established PCSK9 monoclonal antibody manufacturing scale. Novartis occupies a position at the technology frontier with siRNA mechanisms that collapse dosing frequency to annual or biannual intervals. Sanofi represents European market prioritization through differentiated cardiovascular outcome data that sustains payer preference across health technology assessment frameworks. These three entities collectively illustrate how geographic focus and mechanism modality determine competitive positioning within the bifurcated market structure.
| Leading Market Players |
|---|
| Amgen Inc. |
| Novartis AG |
| AstraZeneca |
| AbbVie Inc. |
| Daiichi Sankyo Company |
| Merck & Co. |
| Sanofi |
| Regeneron Pharmaceuticals |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Outcomes-based contracts with integrated delivery networks lock in multi-year supply commitments for PCSK9 inhibitors while establishing fixed per-patient reimbursement rates that compress margin volatility for manufacturers. This contracting pattern concentrates procurement leverage among United States hospital systems with centralized pharmacy capabilities, tethering price visibility to cold-chain distribution performance metrics and adherence monitoring technology integration.
Pricing Analysis
FDA cardiovascular outcome trial mandates dictate the pricing tier structure across mechanism classes, with siRNA agents commanding annual-dosing premiums over biweekly monoclonal antibodies. Pricing stratifies across premium injectable biologics, standard oral combination therapies, and economy generic statin tiers based on LDL-C reduction magnitude and cardiovascular outcome documentation. Cost compression in the oral tier is intensifying because Germany's statutory health insurance funds require documented statin failure before authorizing biologic alternatives. Primary care prescribing segments exhibit highest price sensitivity, while hospital specialty clinics demonstrate lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for statin active pharmaceutical ingredients manufactured in India and China. API production concentrates in India, China, and selected United States coastal zones where EPA effluent compliance infrastructure already exists. Manufacturing rests on fermentation-derived statin intermediates, synthetic PCSK9 inhibitor biologics, and siRNA oligonucleotide precursors. Single-source vulnerability characterizes the biologic fill-finish segment, where Swiss and German contract manufacturers dominate high-potency sterile operations. Distribution runs through United States specialty pharmacy channels, European hospital procurement consortiums, and Japanese clinic-based dispensing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA interference convergence with cardiovascular risk platforms marks an ecosystem inflection, where dosing frequency collapse and electronic health record interoperability reshape competitive moats around patient adherence data rather than molecule exclusivity alone.
For Market Incumbents: Shield manufacturing scale advantages in North American hospital channels by embedding real-world evidence generation capabilities directly into specialty pharmacy partnerships, neutralizing the threat of annual-dosing siRNA substitution through adherence platform stickiness. Deepen backward integration into cold-chain logistics to capture margin leakage from third-party distribution and secure channel control against emerging biologic entrants. For New Entrants and Emerging Players: Anchor in Japan's underpenetrated familial hypercholesterolemia screening infrastructure, where diagnostic gaps create white-space for pharmaceutical-diagnostic integration models that bypass saturated United States and European markets. Target German bundled reimbursement pathways for metabolic disease management, leveraging the intersection of lipid, diabetes, and obesity protocols to secure formulary access without head-to-head statin displacement battles. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap siRNA platform specialists with validated hepatic delivery mechanisms and existing cardiovascular pipeline assets, positioning for acquisition by large-cap biopharmaceuticals seeking mechanism diversification. Long-term viability hinges on regulatory data exclusivity extension through real-world evidence collection infrastructure, with the signal to watch being EMA-mandated national registry integration requirements that favor scaled players with hospital network partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| RNA Interference Platform Expansion | Annual-dosing regimens collapse adherence economics and threaten statin chronic medication models. |
| Real-World Evidence Infrastructure Investment | EMA registry mandates favor manufacturers with embedded European hospital data partnerships. |
| Cold-Chain Distribution Capacity Buildout | Centralized United States pharmacy operations require biologic handling capabilities for formulary access. |
| Diagnostic-Pharmaceutical Integration | Japan's familial hypercholesterolemia screening gaps create partnership opportunities for targeted therapy expansion. |
| Green Manufacturing Certification | EU Green Deal incentives reward continuous flow chemistry investments with regulatory pathway prioritization. |
Study Parameters
A standing panel of drug development executives, formulary directors, hospital procurement managers, and payer access specialists provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Primary interviews with cardiology specialty clinic administrators and specialty pharmacy operations heads combined with bottom-up prescription volume modeling and top-down revenue triangulation across mechanism classes and administration routes.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks segmenting by product type, end user channel, administration route, and therapy area. CAGRs were derived from patient population epidemiology, penetration rate assumptions for novel mechanisms, and pricing trajectory modeling for generic substitution pressures. Forecast inputs incorporated cardiovascular outcome trial completion timelines, regulatory label expansion pathways, and reimbursement authorization criteria by national health technology assessment bodies.
Material uncertainties — regulatory benefit-risk reassessment outcomes, API manufacturing environmental compliance disruptions, and cardiovascular outcome trial recruitment delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding patient adherence to injectable regimens, payer cost-effectiveness threshold stability, and biosimilar entry timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Mitotane Market