
 Chloramphenicol Eye Drops Market | 2026-2036
Chloramphenicol Eye Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Chloramphenicol Eye Drops Market Analysis
Pharmaceutical-grade sterility certification is bifurcating the Chloramphenicol Eye Drops competitive landscape. Novartis AG leverages its integrated sterile manufacturing network to supply regulated markets. Pfizer Inc. anchors its position through hospital formulary contracts across North America and Europe. Sun Pharmaceutical Industries Ltd. competes aggressively on cost in emerging markets while maintaining WHO prequalification status.
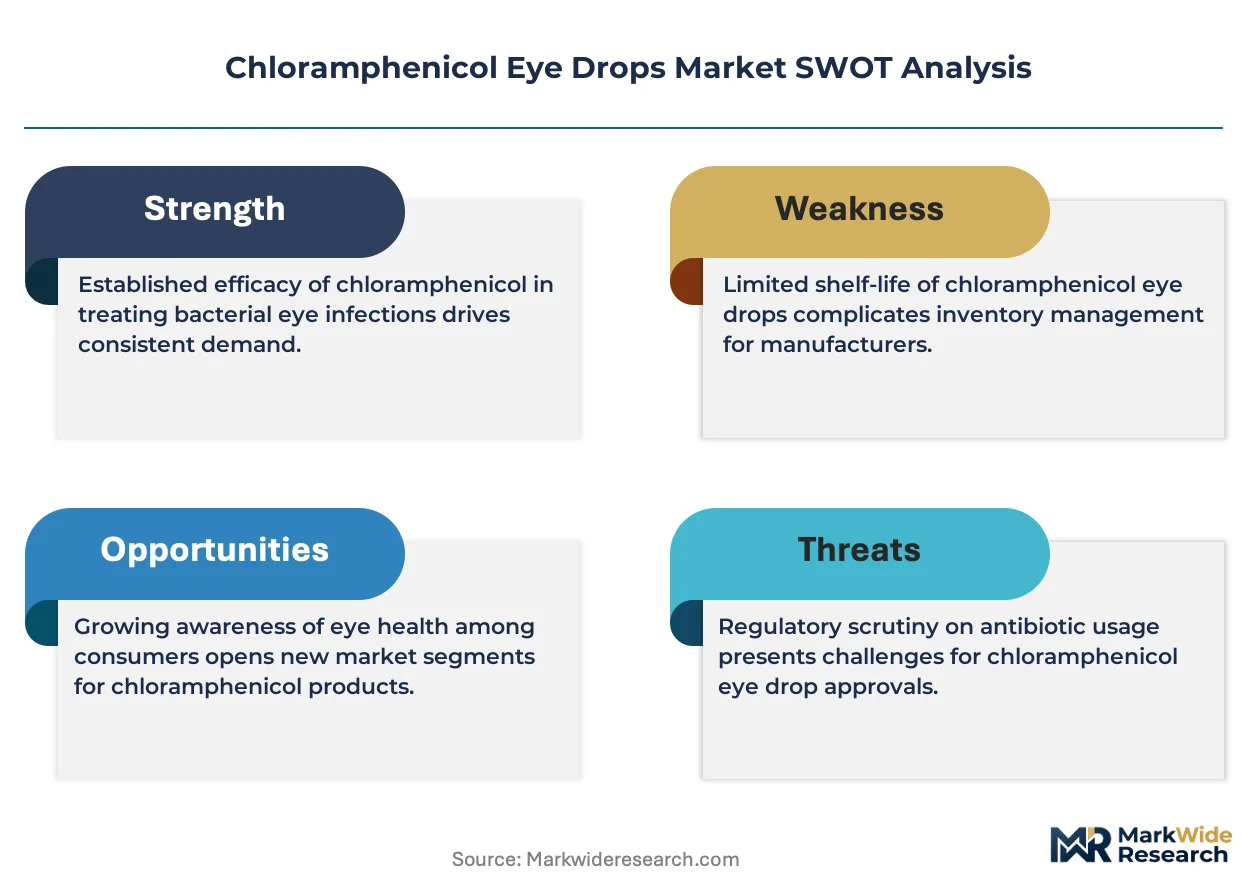
Chloramphenicol eye drops constitute a topical antibiotic ophthalmic solution containing chloramphenicol as the active pharmaceutical ingredient, typically formulated at 0.5% concentration in buffered aqueous vehicles with pH adjusted to 7.0-7.5 for ocular tolerability; the preparation functions primarily to treat bacterial conjunctivitis and superficial ocular infections by inhibiting bacterial protein synthesis. The therapy area dimension shows infections commanding the largest volume share, while post-surgical care applications generate premium pricing due to mandatory sterile protocols. Single-dose packaging formats are capturing share from multi-dose alternatives as regulatory agencies tighten preservative exposure guidelines for frequent-use patients.
The US FDA enforces Current Good Manufacturing Practice for sterile ophthalmic products under 21 CFR, while EMA's Guideline on Quality of Ophthalmic Products mandates container-closure integrity validation and particulate matter controls. India's CDSCO requires bioequivalence documentation for generic chloramphenicol formulations entering the market. Stakeholders must monitor evolving preservative-free mandates and sterile manufacturing capacity constraints as determinants of competitive viability.
Market Dynamics
Preservative-free formulation mandates from EMA and FDA are fragmenting manufacturing capacity, forcing capital reallocation toward sterile single-dose lines and compressing margins for multi-dose dependent producers.
Growth Catalysts
- CDSCO bioequivalence pathway:India's streamlined generic approval process accelerates market entry for WHO-prequalified manufacturers serving price-sensitive segments.
- Post-surgical infection protocols:Rising cataract and refractive surgery volumes in ophthalmology clinics drive mandatory prophylactic antibiotic use.
- Polymerase chain reaction (PCR) contamination testing:Advanced sterility verification methods reduce batch rejection rates and shorten release cycles.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in China create single-source vulnerability for chloramphenicol base material.
- 21 CFR sterility compliance costs:FDA-mandated environmental monitoring and personnel qualification requirements inflate fixed overhead for sterile suites.
- Fluoroquinolone substitution:Moxifloxacin and levofloxacin alternatives capture premium segments with broader spectrum coverage.
Strategic Opportunities
- Rural India clinic networks:Government-funded vision centers in tier-3 cities and district hospitals remain underserved by branded ophthalmic suppliers.
- WHO Essential Medicines List alignment:Prequalification status unlocks institutional procurement channels across Sub-Saharan Africa and Southeast Asia.
- Unit-dose blow-fill-seal technology:Aseptic forming and filling integration eliminates terminal sterilization bottlenecks.
Industry Challenges
- Aseptic processing workforce scarcity:Qualified cleanroom operators and sterility assurance specialists command premium wages amid limited training pipeline output.
- Container-closure integrity validation timelines:EMA-mandated dye ingress and microbial challenge studies extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloramphenicol Eye Drops Market |
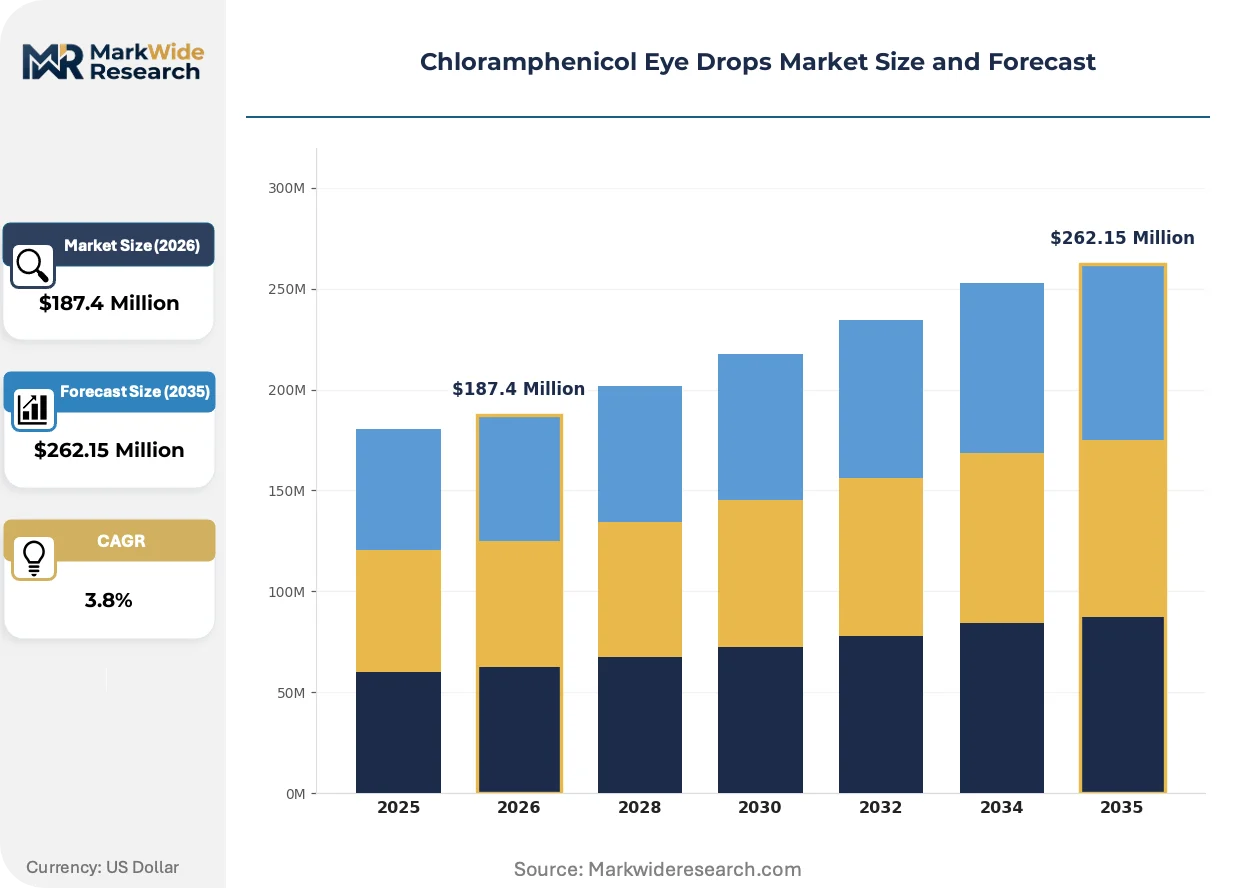
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservative-Free, Multi-Dose, Single-Dose, Combination Therapy Area: Infections, Inflammation, Allergies, Post-surgical Care Application: Ophthalmology Clinics, Home Care, Hospitals, Pharmacies Packaging Type: Dropper Bottles, Ampoules, Sachets, Vials |
| Companies Covered | Novartis AG, Pfizer Inc., Bausch & Lomb, Sun Pharmaceutical Industries Ltd., Cipla Limited, Ethypharm, Aurolab, Famar, Ciron Drugs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloramphenicol Eye Drops Market Emerging Trajectories
Formulation science and packaging engineering are converging to eliminate preservative systems entirely, while regulatory pressure on benzalkonium chloride exposure intensifies R&D resource allocation toward novel delivery mechanisms.
Blow-fill-seal (BFS) aseptic processing is decomposing traditional vial-filling workflows in ophthalmic manufacturing. Hospital pharmacy buyers and contract manufacturers in Germany and Japan are adopting BFS lines at accelerated capital deployment rates. This technology is decomposing the economics of multi-dose preserved products by enabling unit-cost parity at sterile assurance levels previously reserved for premium segments.
EMA's Guideline on Quality of Ophthalmic Products mandates particulate matter controls and extractables-leachables profiling for all new submissions. European manufacturers face reformulation costs for legacy products lacking modern container-closure data packages. Ophthalmic generics with pre-2018 approvals in France and Italy are most affected, with several MAH holders withdrawing rather than upgrading dossiers.
Hospital formulary consolidation is compressing supplier rosters to three or fewer approved chloramphenicol sources per institution. Procurement committees in NHS England trusts and Indian central government hospitals now require single-dose presentations for all high-frequency antibiotic indications. This pattern is most visible in tertiary eye care centers across Maharashtra and Tamil Nadu, where inventory rationalization programs favor sole-source contracts with integrated sterile manufacturers.
Chloramphenicol Eye Drops Market Segmentation
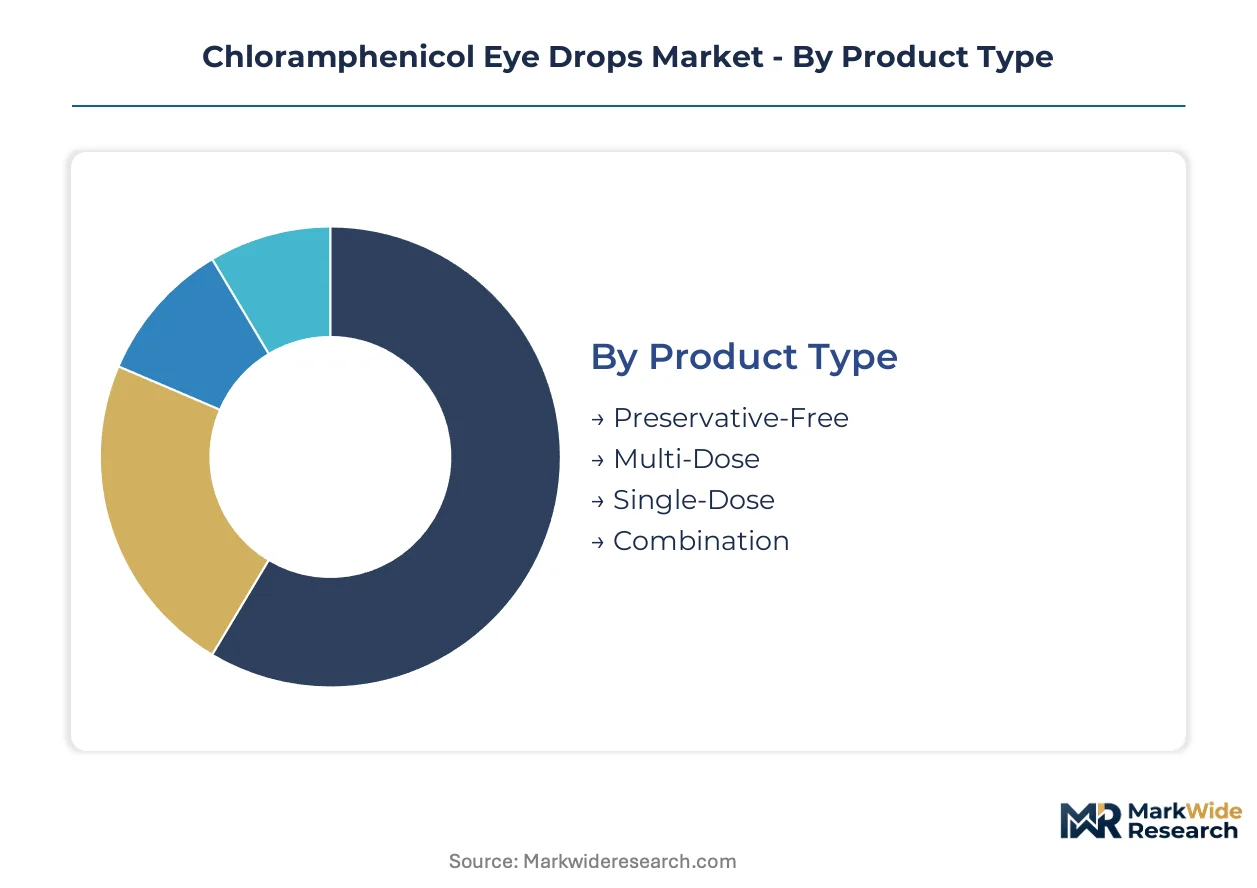
Segmentation in the chloramphenicol eye drops market reveals how regulatory pressure on preservatives and sterility protocols is fragmenting manufacturing economics across product formats. Each dimension exposes distinct vulnerability to fluoroquinolone substitution, cost-tier compression, or channel consolidation.
Product Type:
Multi-dose preserved formulations face the most acute substitution threat as EMA and FDA tighten benzalkonium chloride exposure guidelines for frequent-use patients.
- Preservative-Free:Buffered aqueous formulations eliminate benzalkonium chloride through terminal filtration and aseptic processing. Demand concentrates in NHS England trusts and German hospital pharmacies where formulary committees mandate single-dose presentations for high-frequency antibiotic indications.
- Multi-Dose:Traditional preserved formulations in 5ml and 10ml dropper bottles rely on benzalkonium chloride or phenylmercuric nitrate for antimicrobial protection. Cost-sensitive retail channels in India and over-the-counter pharmacy segments in Brazil retain volume despite regulatory headwinds.
- Single-Dose:Unit-dose polymer or blow-fill-seal ampoules deliver 0.5ml aliquots without preservative systems. Post-surgical protocols in tertiary eye care centers across Maharashtra and Tamil Nadu drive procurement.
- Combination:Fixed-dose combinations with steroids or NSAIDs require additional stability validation and extractables-leachables profiling. Limited to hospital formularies with specialized compounding oversight.
Multi-dose anchors the volume base in emerging retail channels while preservative-free gains share at the steepest rate through institutional procurement mandates.
Therapy Area:
Cost tier stratification separates commodity infection treatment from premium-priced prophylactic protocols in surgical settings.
- Infections:Bacterial conjunctivitis and superficial ocular infections constitute the foundational indication with standardized 0.5% chloramphenicol concentration. Volume concentrates in primary care and pharmacy-led diagnosis models across Sub-Saharan Africa.
- Post-surgical Care:Cataract and refractive surgery prophylaxis commands premium pricing through mandatory sterile single-dose requirements. Tertiary ophthalmology clinics in Seoul and Singapore drive specification.
- Inflammation:Adjunctive antibiotic coverage in inflammatory conditions competes with combination products. Limited formulary penetration outside WHO Essential Medicines List procurement channels.
- Allergies:Off-label or historical use in allergic conjunctivitis faces displacement by dedicated antihistamine drops. Minimal current clinical trial activity supports this segment.
Infections retain the broadest geographic footprint while post-surgical care delivers the highest per-unit economics through protocol-driven compliance.
Application:
Customer type fragmentation splits between institutional procurement committees and individual patient acquisition economics.
- Hospitals:Centralized pharmacy and therapeutics committees enforce sole-source contracts with integrated sterile manufacturers. NHS England trusts and Indian central government hospitals now require single-dose presentations exclusively.
- Ophthalmology Clinics:Specialized outpatient facilities balance formulary compliance with inventory efficiency. Chains in São Paulo and Mexico City consolidate supplier rosters to three approved sources per institution.
- Home Care:Patient-directed use following diagnosis or prescription refill. Price sensitivity dominates in uninsured populations across Southeast Asia.
- Pharmacies:Over-the-counter availability in regulated markets and pharmacist-led diagnosis in emerging economies. Regulatory divergence between scheduled and general sale categories affects shelf placement.
Hospitals anchor procurement volume through mandatory protocols while ophthalmology clinics expand most quickly through specialty network densification.
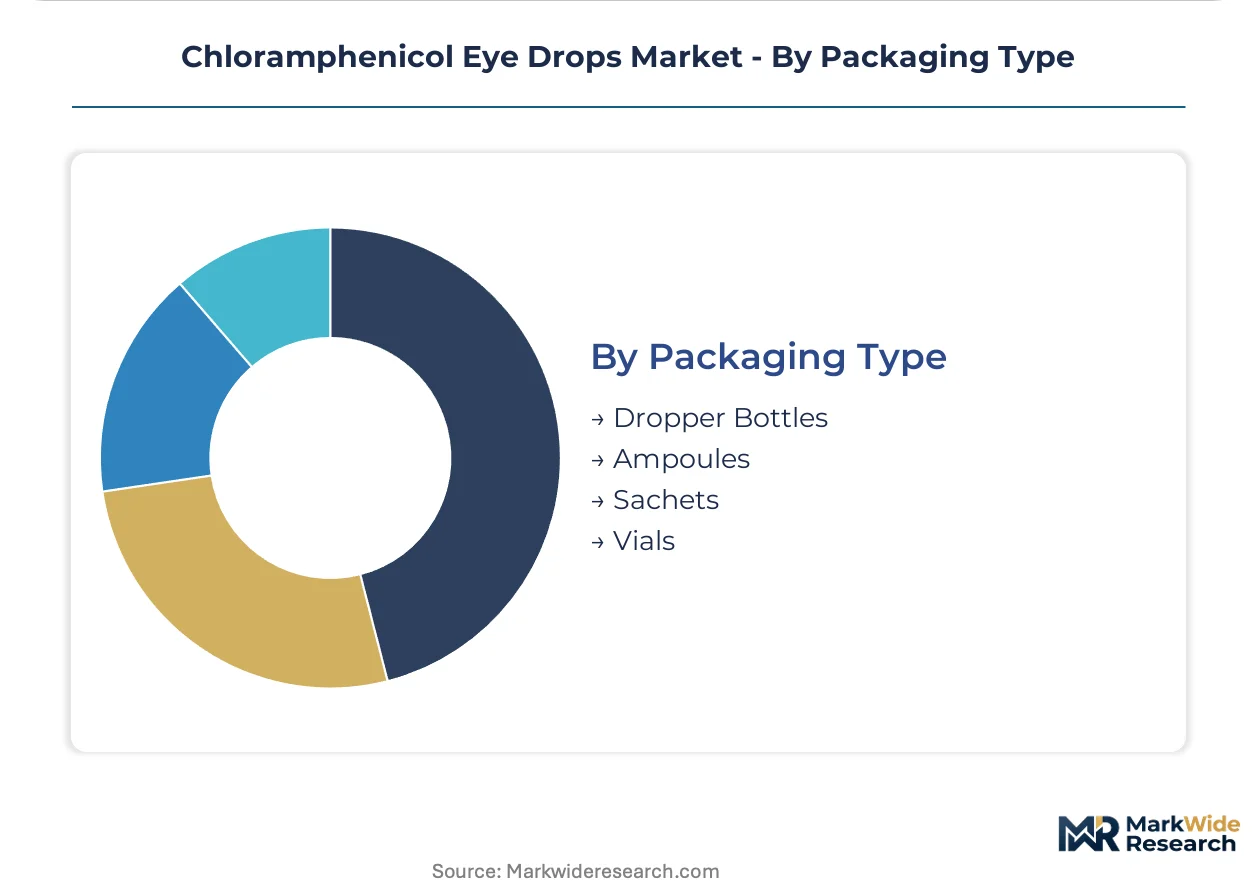
Packaging Type:
Supply concentration in blow-fill-seal technology is displacing traditional glass vial workflows for sterile assurance at unit-cost parity.
- Dropper Bottles:Multi-dose plastic or glass containers with integrated tip dispensers. Legacy manufacturing lines in Eastern European contract manufacturers serve preserved formulation demand.
- Ampoules:Glass or polymer single-unit containers for preservative-free delivery. Blow-fill-seal integration in German and Japanese manufacturing plants shortens release cycles.
- Sachets:Flexible film pouches for unit-dose distribution in tropical climates. WHO prequalification programs in Sub-Saharan Africa favor this format for cold-chain independence.
- Vials:Traditional glass containers requiring separate dropper assembly. Terminal sterilization bottlenecks constrain capacity expansion for new market entrants.
Dropper bottles maintain volume leadership in retail channels while ampoules climb the fastest through hospital formulary consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in chloramphenicol eye drops tilt toward API sourcing from China and finished formulation distribution to emerging markets. India's CDSCO bioequivalence pathway accelerates generic entry for domestic consumption and regional re-export. German and Japanese sterile manufacturing clusters supply premium preservative-free units to regulated markets.
United States
Cataract surgery volumes at tertiary centers in Florida and California drive institutional procurement of single-dose presentations. FDA enforcement of 21 CFR sterility standards elevates compliance costs for new market entrants. Boston-area hospital networks consolidate supplier rosters to three approved sources per formulary.
India
Government-funded vision centers in Maharashtra and Tamil Nadu expand access to ophthalmology clinics in tier-3 cities. CDSCO requires bioequivalence documentation for generic chloramphenicol formulations entering the domestic market. Mumbai and Hyderabad host contract manufacturing organizations serving WHO prequalification programs.
Germany
NHS England trusts and German hospital pharmacies mandate single-dose presentations for high-frequency antibiotic indications. EMA's Guideline on Quality of Ophthalmic Products mandates container-closure integrity validation for all new submissions. Bavarian blow-fill-seal manufacturing plants shorten sterile release cycles for European distribution.
China
Active pharmaceutical ingredient production clusters create single-source vulnerability for chloramphenicol base material. NMPA oversight of sterile ophthalmic manufacturing aligns with international GMP standards. Yangtze River Delta chemical parks supply raw material to formulation plants across Asia-Pacific.
Brazil
Over-the-counter pharmacy segments retain multi-dose volume despite regulatory headwinds on preservative exposure. ANVISA scheduling categories affect shelf placement in São Paulo retail chains. Ophthalmology clinic chains in São Paulo and Mexico City consolidate supplier rosters to three approved sources per institution.
Chloramphenicol Eye Drops Market Vendor Landscape
Concentration sits with integrated sterile manufacturers and cost-optimized generic specialists. The vendor base splits between premium-tier suppliers with hospital formulary contracts and emerging-market players competing on WHO prequalification status. Three archetypes dominate: multinational pharmaceutical conglomerates with aseptic processing networks, mid-cap Indian generics with backward integration into API sourcing, and European contract manufacturers with blow-fill-seal specialization. Competitive moves center on sterile capacity expansion and geographic licensing partnerships for preservative-free formulations.
Among Swiss and US-based pharmaceutical conglomerates, Novartis AG and Pfizer Inc. occupy positions anchored by integrated sterile manufacturing networks and hospital formulary contracts across North America and Europe. Sun Pharmaceutical Industries Ltd. exemplifies the cost-competitive archetype, maintaining WHO prequalification status while serving price-sensitive segments in emerging markets. These three entities represent the spectrum from premium regulated-market positioning to volume-driven generic supply.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Bausch & Lomb |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Limited |
| Ethypharm |
| Aurolab |
| Famar |
| Ciron Drugs |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR sterility certification gates both manufacturing qualification and price differentiation simultaneously, forcing capital-intensive cleanroom investments that stratify suppliers across premium institutional and economy retail tiers while compressing margins for non-compliant producers.
Pricing Analysis
Hospital formulary buyers anchor contract-based long-term procurement structures across the chloramphenicol eye drops market. Pricing stratifies across preservative-free premium, standard multi-dose, and economy generic tiers based on sterile certification grade and volume scale commitments. Cost compression in multi-dose segments is intensifying because fluoroquinolone alternatives capture protocol-driven prophylactic use cases. Uninsured retail patients in emerging markets exhibit highest price sensitivity, while NHS England trusts and German hospital pharmacies demonstrate lowest sensitivity due to mandated single-dose procurement protocols.
Supply Chain Analysis
API supply concentration in China's Yangtze River Delta chemical parks creates single-source vulnerability for chloramphenicol base material. Formulation manufacturing draws from Indian contract manufacturing clusters and German blow-fill-seal specialists, with sterile packaging components sourced from Japanese polymer suppliers. Regulatory restriction risk centers on EMA preservative-free mandates and FDA environmental monitoring requirements that disqualify legacy multi-dose lines. Distribution runs through hospital procurement committees in regulated markets and pharmacy wholesale networks in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with preservative-free formulation mandates that displace incumbent multi-dose capacity and create niche entry points for sterile specialists across hospital formulary channels.
For Market Incumbents: Consolidate sterile manufacturing capacity through backward integration into blow-fill-seal technology and exclusive hospital formulary contracts across NHS England trusts and Indian central government hospitals. Novartis AG and Pfizer Inc. anchor positions through integrated aseptic networks; smaller players face displacement from fluoroquinolone substitution and regulatory compliance cost inflation. Priority investment targets WHO prequalification status and EMA container-closure validation to defend institutional procurement access. For New Entrants and Emerging Players: Lead with unit-dose preservative-free presentations targeting rural India clinic networks in Maharashtra and Tamil Nadu tier-3 cities where branded ophthalmic suppliers remain absent. Government-funded vision centers offer penetrable demand concentration with protocol-driven compliance requirements. Go-to-market execution partners with Mumbai and Hyderabad contract manufacturing organizations already serving WHO prequalification programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterile single-dose manufacturing as EMA and FDA mandates force equipment replacement cycles. Long-term viability over the next decade favors integrated manufacturers with captive API sourcing and blow-fill-seal technology. Acquisition target archetype: mid-cap Indian generics with CDSCO bioequivalence documentation and backward integration into chloramphenicol base material. Signal to watch: hospital formulary consolidation to sole-source contracts in tertiary eye care centers.| Strategic Initiative | Industry Significance |
|---|---|
| Blow-Fill-Seal Capacity Expansion | Aseptic forming integration eliminates terminal sterilization bottlenecks for EMA-compliant preservative-free output. |
| WHO Prequalification Pathway | UNICEF and PAHO procurement channels unlock institutional demand across Sub-Saharan Africa and Southeast Asia. |
| Hospital Formulary Partnership | NHS England trusts and Indian central government hospitals mandate single-dose presentations exclusively. |
| API Backward Integration | Captive chloramphenicol base material supply insulates against Yangtze River Delta concentration risk. |
| Regulatory Dossier Upgrade | EMA container-closure integrity validation prevents withdrawal of legacy multi-dose products in France and Italy. |
Methodological Framework
Cross-validation between primary interviews with sterile manufacturing executives, hospital pharmacy procurement managers, regulatory affairs specialists, and ophthalmology clinic directors anchors the qualitative findings. Secondary validation draws from FDA 21 CFR guidance documents, EMA Guideline on Quality of Ophthalmic Products, CDSCO bioequivalence notifications, WHO prequalification assessment reports, and hospital formulary databases. Bottom-up demand modeling triangulates against top-down API production and finished formulation trade flow analysis.
Sensitivity analysis across product type, therapy area, application channel, packaging format, and regional regulatory cluster dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segmented volume and value build-ups incorporating cataract surgery volume trajectories, preservative-free mandate implementation timelines, and sterile manufacturing capacity expansion schedules. Industry-specific forecast inputs include blow-fill-seal technology adoption rates and hospital formulary consolidation patterns.
Underlying assumptions cover EMA and FDA regulatory stability, API supply continuity from Chinese chemical parks, and WHO prequalification program funding levels, with deviation risk concentrated in single-source API vulnerability and aseptic processing workforce scarcity. Practitioners should keep alternative scenarios live as sterile certification requirements and fluoroquinolone substitution patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Sitagliptin Market