
 Urinary Antibacterial and Antiseptic Pharmaceuticals Market | 2026-2036
Urinary Antibacterial and Antiseptic Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Antibacterial and Antiseptic Pharmaceuticals Market Analytics
Fluoroquinolone active pharmaceutical ingredients is shifting toward nitrofurantoin and fosfomycin bases as resistance profiles and safety warnings alter cost structures for manufacturers. Pfizer Inc leverages its broad antibiotic manufacturing infrastructure to sustain supply continuity across multiple therapeutic classes. Bayer AG anchors its position through specialized urology-focused development programs. Sun Pharmaceutical Industries Ltd competes on cost-engineered oral generics for high-volume hospital tenders.
Urinary antibacterial and antiseptic pharmaceuticals comprise systemic and topical agents formulated to eliminate or suppress uropathogenic bacteria in the renal system, bladder, and urethra, with nitrofurantoin requiring controlled crystal size below 10 microns to ensure dissolution and bioavailability. These products serve the primary commercial purpose of treating confirmed or suspected bacterial infections while reducing pyelonephritis progression and recurrent cystitis episodes. Oral formulations dominate volume consumption across pharmacy and homecare channels, while intravenous delivery commands premium positioning in hospital settings due to severe infection management requirements. Combination therapy represents the fastest-expanding structural segment as multidrug-resistant organism protocols drive sequential or concurrent agent deployment.
FDA antimicrobial stewardship mandates and EMA pharmacovigilance requirements for fluoroquinolone restrictions shape product labeling, prescribing limits, and market access pathways across the United States and European Union. India's CDSCO manufacturing standards and China's NMPA import registration protocols add compliance layers for generic suppliers seeking entry into regulated markets. Stakeholders must monitor resistance surveillance data and regulatory label revisions to align pipeline investments with shifting first-line therapy designations.
Market Dynamics
Antimicrobial stewardship programs across hospital systems are compressing fluoroquinolone utilization and redirecting procurement toward narrow-spectrum alternatives with cleaner resistance profiles.
Growth Catalysts
- FDA fluoroquinolone safety restrictions:The boxed warning expansion has triggered formulary exclusions across US hospital systems, accelerating uptake of nitrofurantoin and fosfomycin as first-line cystitis therapy.
- Multidrug-resistant organism surveillance:Carbapenem-resistant Enterobacteriaceae tracking in German and Japanese tertiary centers is mandating combination protocol adoption for complicated urinary tract infections.
- Intravenous-to-oral step-down protocols:Hospital antimicrobial stewardship teams are standardizing rapid de-escalation pathways that expand oral generic volume in post-acute care settings.
Market Restraints
- Active pharmaceutical ingredient concentration:Nitrofurantoin and fosfomycin raw material supply concentrates among Chinese and Indian manufacturers, exposing formulation continuity to single-source disruption.
- EMA pharmacovigilance label restrictions:European fluoroquinolone prescribing limitations have compressed branded revenue streams and forced portfolio restructuring toward lower-margin generics.
- Oral bioavailability thresholds:Crystal size engineering below 10 microns requires specialized micronization equipment that smaller generic manufacturers cannot access cost-effectively.
Strategic Opportunities
- Homecare infusion expansion:Outpatient parenteral antimicrobial therapy programs in the United States are creating demand for pre-mixed intravenous bags with extended stability profiles.
- CDSCO manufacturing standard harmonization:Indian bulk drug and formulation facilities upgrading to PIC/S compliance can access regulated European and North American tender markets previously blocked by technical barriers.
- Point-of-care resistance testing:Rapid phenotypic susceptibility platforms are converging with pharmacy dispensing workflows to enable same-day targeted therapy selection in urgent care settings.
Industry Challenges
- Antimicrobial stewardship specialist staffing:Hospital systems face persistent vacancies in infectious disease pharmacy and clinical microbiology functions needed to implement resistance-driven protocol changes.
- Multiparameter bioequivalence demonstration:Nitrofurantoin generic approvals require dissolution profile matching across multiple pH conditions, extending ANDA review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Antibacterial and Antiseptic Pharmaceuticals Market |
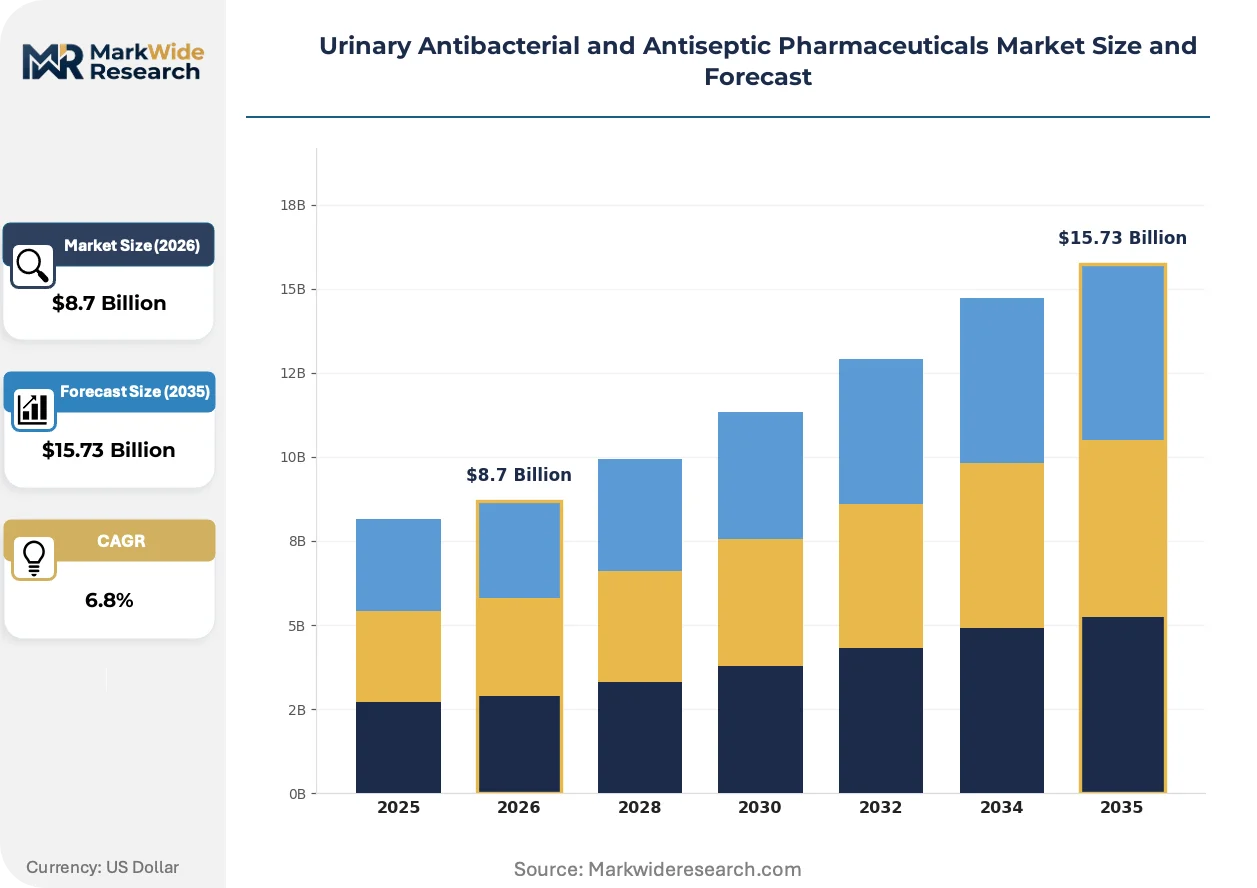
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ciprofloxacin, Nitrofurantoin, Fosfomycin, Trimethoprim Therapy Area: Urinary Tract Infections, Cystitis, Urethritis, Pyelonephritis Delivery Mode: Oral, Intravenous, Topical, Combination Therapy End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Pfizer Inc, Bayer AG, GlaxoSmithKline plc, Novartis AG, Cipla Ltd, Sanofi S.A., Merck & Co. Inc, AstraZeneca plc, Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Antibacterial and Antiseptic Pharmaceuticals Market Evolving Landscape
Formulation science and diagnostic integration are reshaping how urinary antibacterials move from laboratory bench to bedside, with particle engineering and rapid susceptibility testing compressing therapeutic decision cycles.
Controlled-release nitrofurantoin macrocrystal formulations are automating compliance optimization by extending dosing intervals to twice-daily regimens. Hospital outpatient departments and long-term care facilities are adopting these modified-release platforms to reduce nursing administration burden. The technology is automating adherence improvement while preserving efficacy against susceptible uropathogens.
EMA's tightened fluoroquinolone product information requirements have triggered label harmonization across EU member states, restricting systemic use to situations with no viable alternatives. Generic manufacturers have responded by accelerating nitrofurantoin and fosfomycin dossier submissions to capture displaced volume. The policy shift most severely impacts fluoroquinolone-dependent hospital formularies in France, Germany, and Italy.
Centralized hospital procurement consortia are consolidating antibiotic purchasing decisions across multi-hospital systems, displacing individual pharmacy-driven tendering. This concentration is compressing supplier margins while favoring manufacturers with vertically integrated active pharmaceutical ingredient production. The restructuring is most visible in United States integrated delivery networks and German hospital federations.
Urinary Antibacterial and Antiseptic Pharmaceuticals Market Segmentation
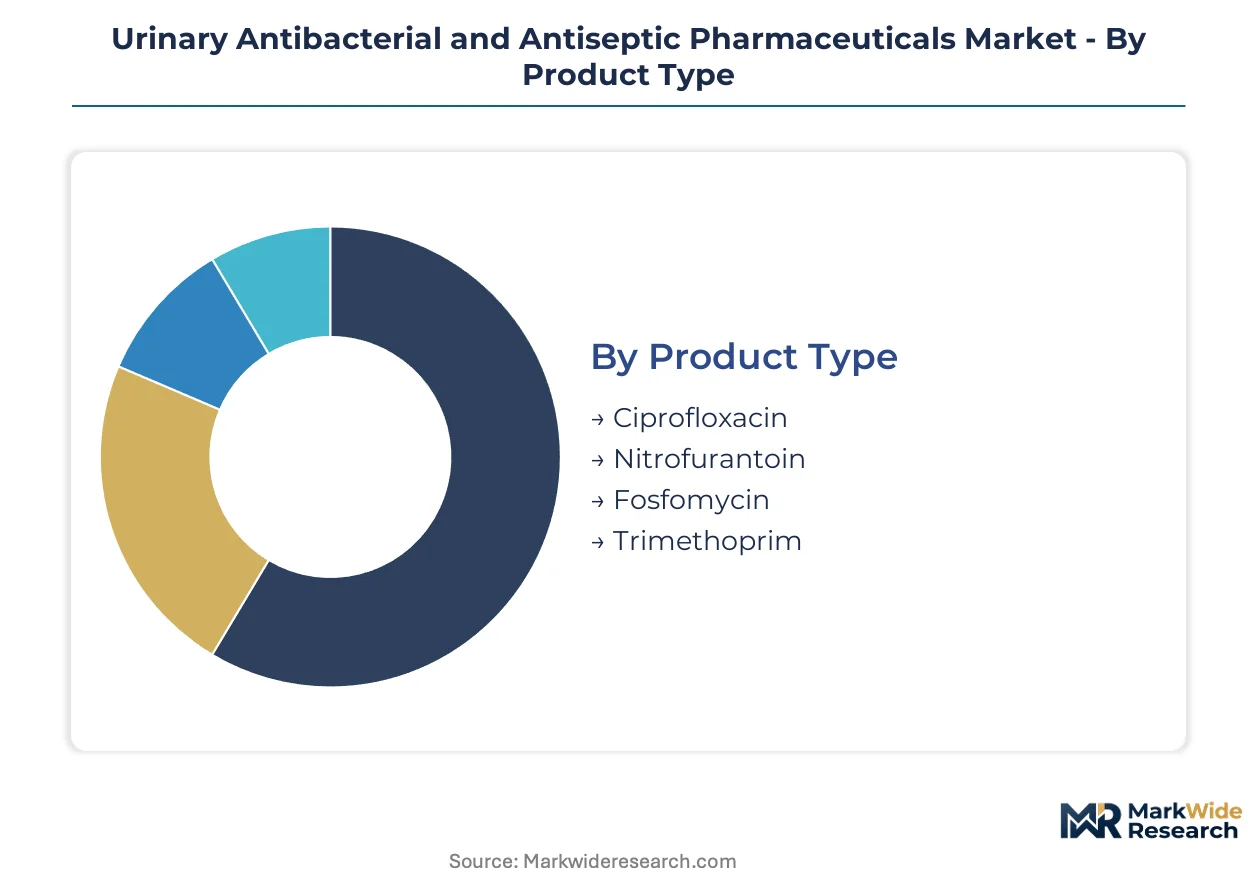
Segmentation in urinary antibacterials reveals how resistance patterns, administration settings, and reimbursement pathways fragment demand across molecular classes and delivery formats. Manufacturers align pipeline investments with the specific bioavailability requirements and stewardship protocols governing each segment.
Product Type:
Standardization dominates nitrofurantoin and fosfomycin production through pharmacopeial monographs, while ciprofloxacin formulations face escalating customization demands around particle engineering and extended-release matrices.
- Ciprofloxacin:Fluoroquinolone synthesis requires enantiomeric purity above 99.5% to meet FDA and EMA impurity thresholds. Hospital formularies in the United States and Germany are restricting procurement to reserve-only indications following boxed warning expansions.
- Nitrofurantoin:Macrocrystal engineering below 10 microns ensures dissolution compliance across gastric pH variation. German and Japanese tertiary centers are expanding nitrofurantoin protocols as first-line cystitis therapy displaces fluoroquinolone volume.
- Fosfomycin:Trometamol salt formulation dominates oral single-dose therapy for uncomplicated infections.
- Trimethoprim:Sulfonamide combination ratios require bioequivalence demonstration across multiple dissolution media.
Most installed capacity flows through nitrofurantoin. Expansion is steepest in fosfomycin.
Therapy Area:
Volume concentrates in high-frequency, low-acuity infections where oral generics dominate procurement, while margin accumulates in complicated cases requiring intravenous step-down protocols and resistance-driven combination regimens.
- Urinary Tract Infections:Uncomplicated cases drive 70% of prescription volume through pharmacy channels. US urgent care networks and Indian primary health centers are standardizing nitrofurantoin-first protocols to align with antimicrobial stewardship targets.
- Cystitis:Acute bacterial cystitis in premenopausal women represents the most protocolized indication with established susceptibility breakpoints. German outpatient clinics and Japanese community health centers are deploying point-of-care dipstick-to-prescription pathways.
- Urethritis:Sexually transmitted pathogen coverage requires dual-agent coverage beyond standard urinary antibacterials.
- Pyelonephritis:Parenteral initiation with oral step-down mandates intravenous-to-oral bioequivalence matching.
Prescription volume concentrates in urinary tract infections. Pyelonephritis commands the highest per-patient revenue.
Delivery Mode:
Hospital procurement prioritizes intravenous stability and extended shelf-life specifications, while retail pharmacy channels optimize for patient adherence through simplified dosing schedules and portable packaging formats.
- Oral:Immediate-release tablets and suspensions dominate outpatient dispensing with twice-daily or single-dose regimens improving completion rates. US pharmacy benefit managers and German statutory health insurers are tightening reimbursement to guideline-concordant oral selections.
- Intravenous:Pre-mixed bags with 24-hour stability reduce compounding burden in intensive care settings. Japanese tertiary centers and US integrated delivery networks are expanding outpatient parenteral antimicrobial therapy programs.
- Topical:Urethral instillations and periurethral applications serve specialized urology clinic workflows.
- Combination Therapy:Sequential or concurrent agent deployment addresses multidrug-resistant organism protocols in complicated infections.
Oral formulations carry the highest prescription count. Combination therapy is gaining share fastest among hospital formularies.
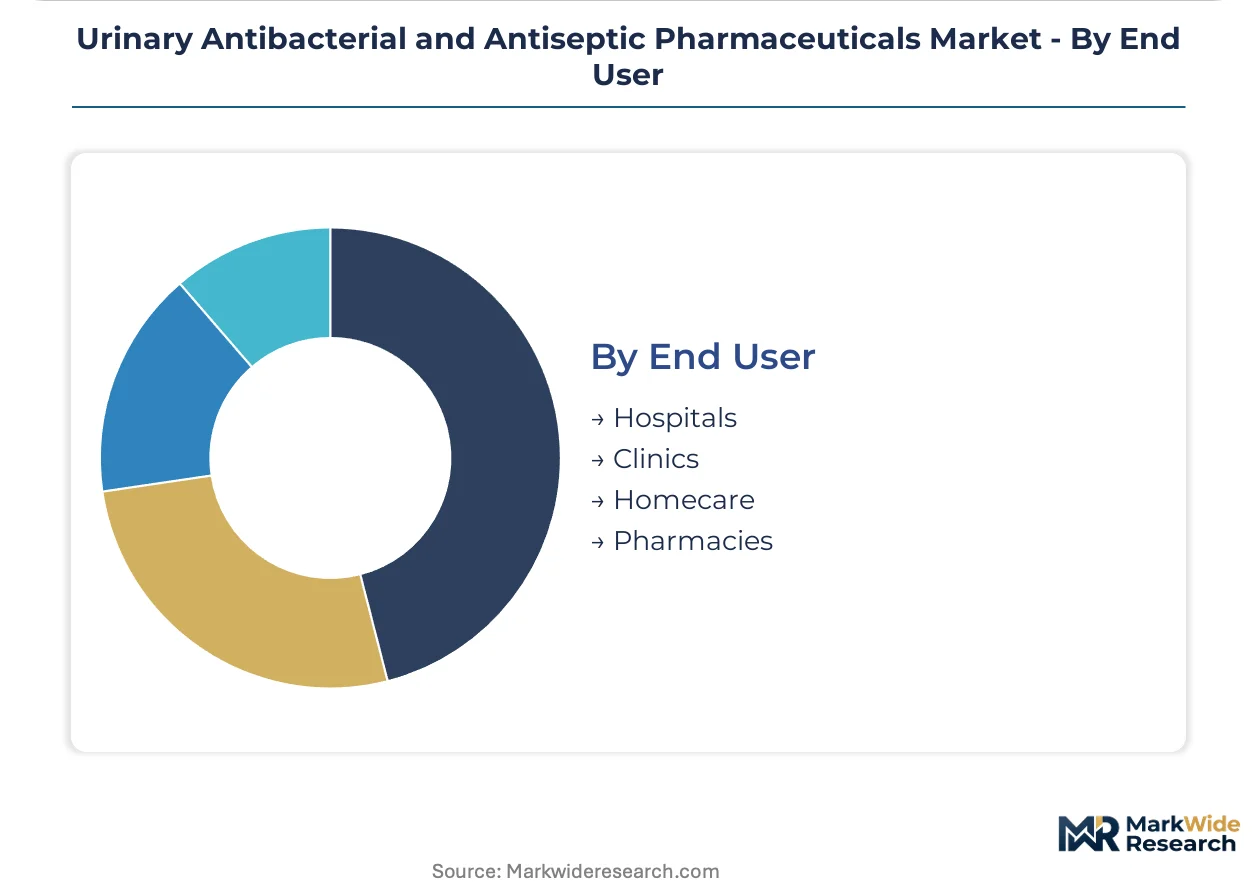
End User:
Purchasing authority fragments across centralized hospital consortia, individual clinic prescribers, and direct-to-patient pharmacy channels with divergent price sensitivity and protocol adherence requirements.
- Hospitals:Antimicrobial stewardship committees control formulary access through preauthorization requirements and automatic stop orders. US integrated delivery networks and German hospital federations are consolidating procurement across multi-facility systems.
- Clinics:Urology and infectious disease specialists drive off-label utilization and resistance testing integration.
- Homecare:Infusion nursing services enable outpatient parenteral therapy completion without hospital readmission.
- Pharmacies:Community dispensing faces generic substitution mandates and prior authorization friction.
Hospital procurement concentrates the highest-value intravenous volume. Homecare infusion is expanding most quickly as step-down protocols lengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad supply the majority of nitrofurantoin and fosfomycin active pharmaceutical ingredients, concentrating formulation feedstock in South Asian production corridors.
United States
FDA antimicrobial stewardship mandates drive hospital formulary exclusions of fluoroquinolones, redirecting procurement toward narrow-spectrum alternatives. The boxed warning expansion for ciprofloxacin compounds has accelerated nitrofurantoin-first protocols across integrated delivery networks. Boston and Philadelphia medical centers lead implementation of rapid intravenous-to-oral step-down pathways.
Germany
EMA pharmacovigilance restrictions on fluoroquinolone prescribing compress branded revenue streams and elevate generic substitution rates. German hospital federations consolidate antibiotic purchasing decisions across multi-facility systems, favoring suppliers with vertically integrated active pharmaceutical ingredient production. Berlin and Munich tertiary centers track carbapenem-resistant Enterobacteriaceae to mandate combination protocols.
Japan
PMDA regulatory alignment with EMA fluoroquinolone limitations redirects prescribing patterns toward fosfomycin trometamol for uncomplicated cystitis. Japanese community health centers deploy point-of-care susceptibility testing to enable same-day targeted therapy selection. Tokyo and Osaka outpatient parenteral antimicrobial therapy programs expand pre-mixed intravenous bag demand.
India
CDSCO manufacturing standards and PIC/S compliance upgrades unlock regulated European and North American tender markets for generic suppliers. Indian bulk drug facilities in Hyderabad and Vadodara engineer nitrofurantoin macrocrystals below 10 microns to meet dissolution bioequivalence requirements. Domestic primary health centers standardize cost-engineered oral generics for high-volume urinary tract infection treatment.
China
NMPA import registration protocols and dual carbon goals reshape active pharmaceutical ingredient export competitiveness for environmental compliance. Chinese manufacturers concentrate fosfomycin calcium and trometamol salt production in Zhejiang and Jiangsu chemical corridors. Shanghai and Beijing hospital procurement consortia tighten specifications around crystal size engineering and extended-release matrix technologies.
Urinary Antibacterial and Antiseptic Pharmaceuticals Market Competitive Landscape
Portfolio restructuring dominates the current landscape as fluoroquinolone-dependent manufacturers accelerate nitrofurantoin and fosfomycin dossier submissions. The vendor base separates into three tiers: multinational innovators with broad antibiotic manufacturing infrastructure, regional specialists in urology-focused development programs, and cost-engineered generic producers competing on high-volume hospital tenders. Strategic archetypes include stewardship-aligned portfolio diversifiers, micronization technology specialists, and vertically integrated active pharmaceutical ingredient suppliers. Competitive intensity concentrates around regulatory approval velocity and manufacturing standard harmonization.
Within the multinational tier, Pfizer Inc and Bayer AG occupy positions as anchors of supply continuity and specialized therapeutic development respectively. Sun Pharmaceutical Industries Ltd exemplifies the cost-engineered generic archetype, competing on oral formulation tenders for pharmacy and homecare channels. These three entities represent the dominant competitive vectors: manufacturing scale, therapeutic specialization, and price-access optimization.
| Leading Market Players |
|---|
| Pfizer Inc |
| Bayer AG |
| GlaxoSmithKline plc |
| Novartis AG |
| Cipla Ltd |
| Sanofi S.A. |
| Merck & Co. Inc |
| AstraZeneca plc |
| Sun Pharmaceutical Industries Ltd |
| Others |
Value Network & Pricing Analysis
Captive active pharmaceutical ingredient production in Hyderabad and Ahmedabad anchors both supply security and margin defense for nitrofurantoin and fosfomycin manufacturers serving regulated markets. This backward integration pattern insulates formulation specialists from raw material volatility while compressing procurement leverage for buyers dependent on spot API markets.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through from Chinese and Indian bulk manufacturers drives contract pricing volatility for European and North American formulators. Three-tier pricing structure across originator brands, PIC/S-certified generics, and non-certified economy suppliers reflects EMA and FDA compliance tier differentiation. Pricing pressure stems from centralized hospital procurement consortia consolidating tender volumes across multi-facility systems. Pharmacy benefit managers exhibit highest price sensitivity, while hospital antimicrobial stewardship committees prioritize resistance profile over unit cost.
Supply Chain Analysis
Specialized micronization workforce availability in Vadodara and Zhejiang chemical corridors constrains nitrofurantoin macrocrystal engineering capacity below 10 microns. API production concentrates in India, China, and selected European facilities, drawing from trometamol salt and calcium salt feedstocks. Single-source vulnerability pervades fosfomycin trometamol precursor supply. Distribution runs through hospital procurement consortia, integrated delivery networks, and pharmacy benefit manager formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA fluoroquinolone boxed warning expansion and EMA pharmacovigilance restrictions continuously redirect demand toward narrow-spectrum alternatives.
For Market Incumbents: Acquire micronization technology platforms and specialized particle engineering facilities to secure nitrofurantoin bioequivalence demonstration capabilities. Defend formulary position by accelerating PIC/S compliance upgrades in Indian bulk drug facilities before CDSCO manufacturing standard harmonization deadlines. Capacity addition in Hyderabad and Ahmedabad chemical corridors counters API supply disruption threats from single-source concentration. For New Entrants and Emerging Players: Homecare infusion nursing services represent an underserved buyer archetype with expanding outpatient parenteral antimicrobial therapy demand. Penetrate US integrated delivery network step-down protocols and Japanese community health center rapid susceptibility testing workflows. Deploy point-of-care diagnostic integration as the primary go-to-market angle for urgent care channel access. For Investors and Strategic Acquirers: Roll-up economics work for PIC/S-compliant Indian generic manufacturers because EMA and North American tender market technical barriers concentrate acquisition targets with scarce regulatory credentials. Five-to-ten year viability hinges on stewardship-aligned portfolio diversification away from fluoroquinolone dependence. Watch carbapenem-resistant Enterobacteriaceae surveillance data as the inflection indicator for combination therapy protocol expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Accelerated ANDA submissions for nitrofurantoin macrocrystal formulations capture fluoroquinolone-displaced volume. |
| Backward Integration | In-house API production of fosfomycin trometamol salts insulates margin from Chinese precursor supply volatility. |
| Manufacturing Scale-Up | PIC/S compliance upgrades in Hyderabad facilities unlock German hospital federation tender participation. |
| Pipeline Diversification | Controlled-release nitrofurantoin development aligns with US antimicrobial stewardship de-escalation protocols. |
| Hospital System Partnership | Pre-mixed intravenous bag supply agreements secure shelf space in Japanese outpatient parenteral therapy programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated across the analysis window.
Segment-weighting approaches distributed value and volume across product type, therapy area, delivery mode, and end user dimensions. CAGRs derived from regression analysis of historical prescription trends and antimicrobial stewardship policy implementation timelines. Resistance surveillance data and regulatory label revision schedules served as primary forecast inputs.
Underlying measurement precision varies by segment; oral generic prescription volume carries tighter precision than emerging combination therapy protocol adoption. Forecasts reflect documented assumptions around FDA and EMA regulatory trajectory, CDSCO manufacturing standard evolution, and carbapenem-resistant Enterobacteriaceae prevalence trends. Material deviation in fluoroquinolone restriction enforcement or API supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Laxatives Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Thin Film Drug Manufacturing Market