
 Conductive Plastic Compounds Market | 2026-2036
Conductive Plastic Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Plastic Compounds Market Analysis
Modular formulation kits are restructuring how tier-one automotive and electronics buyers procure conductive compounds, shifting from single-grade contracts to portfolio-based supply agreements. SABIC leverages its vertically integrated resin backbone to dominate high-volume carbon-filled grades for EMI shielding. RTP Company specializes in rapid-turn custom compounding, occupying a niche that rewards engineering responsiveness over commodity scale. LG Chem anchors its position through captive carbon nanotube supply, controlling input quality for thermal management applications.
Conductive plastic compounds are thermoplastic or thermoset matrices loaded with conductive fillers such as carbon black, carbon nanotubes, or metallic powders to achieve surface resistivity values typically ranging from 10^0 to 10^6 ohms per square, engineered primarily for electromagnetic interference mitigation and electrostatic discharge protection in sensitive electronic assemblies. Carbon-filled compounds lead volume due to cost-performance balance across automotive and consumer electronics grounding applications, while metal-filled variants command premium positioning in aerospace thermal management where outgassing specifications are stringent. Pellet form dominates commercial distribution because it integrates cleanly into standard injection molding and extrusion lines without secondary processing steps.
FDA and EPA frameworks in the United States govern healthcare and environmental compliance for conductive compounds entering medical device housings and electronics waste streams, while REACH and RoHS in Europe restrict hazardous substance migration across imported polymer formulations. China's GB standards and SAMR certification requirements create a parallel compliance track that shapes product development priorities for suppliers targeting domestic electronics assemblers. Stakeholders must monitor how diverging regional substance restrictions and carbon accounting rules will reshape formulation choices and sourcing geography.
Market Dynamics
Automotive electrification programs in Germany, China, and the United States are restructuring procurement patterns for EMI shielding grades, pulling volume away from traditional consumer electronics applications toward high-reliability automotive specifications.
Growth Catalysts
- China's dual carbon goals:Beijing's carbon neutrality mandates are accelerating substitution of metal housings with lightweight conductive plastics in EV battery enclosures, creating specification pull from domestic OEMs.
- EMI shielding for autonomous sensors:Radar and LiDAR module manufacturers in South Korea and Taiwan are specifying carbon nanotube-loaded compounds to manage electromagnetic interference in dense sensor arrays.
- REACH substance restrictions:ECHA's tightening controls on legacy flame retardants are forcing reformulation toward inherently conductive polymer systems that reduce additive burden.
Market Restraints
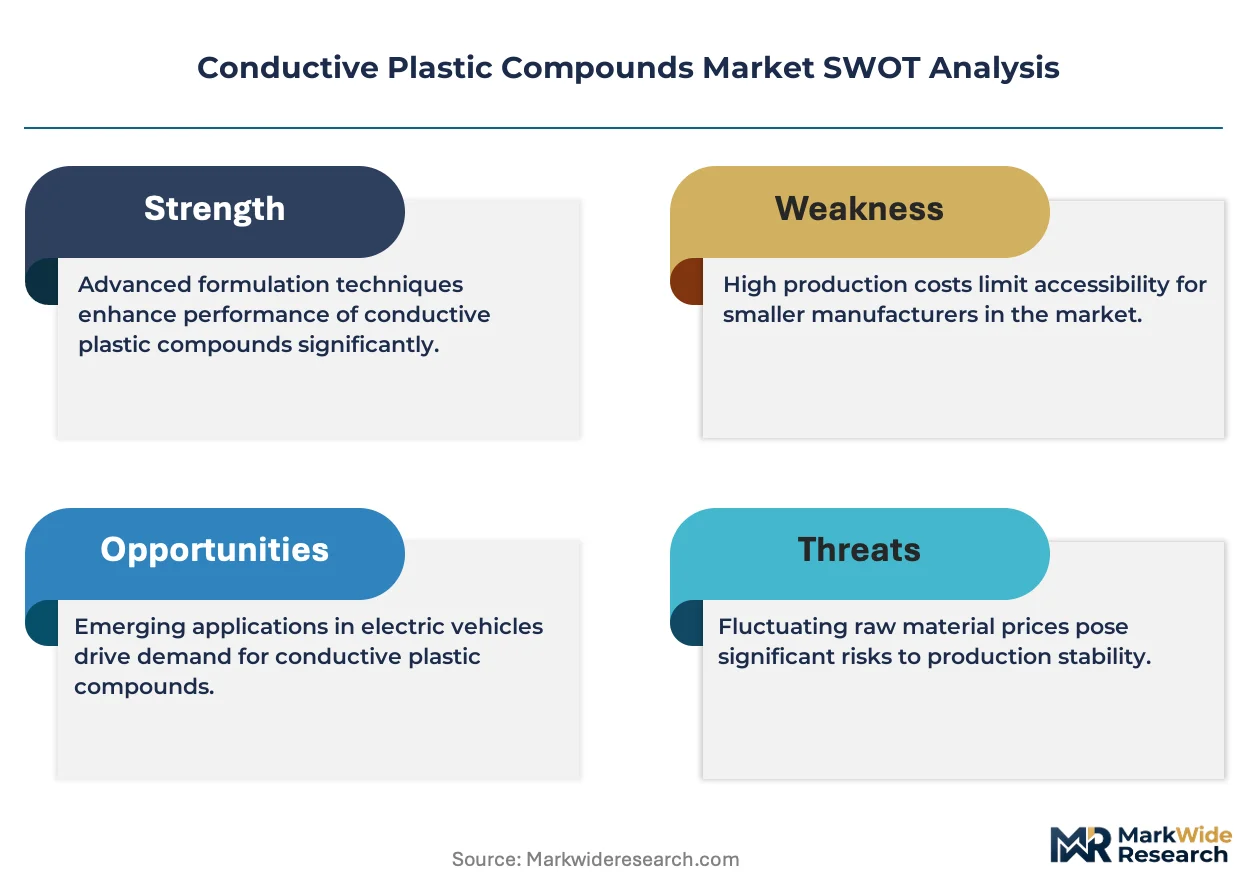
- Carbon black supply concentration:Feedstock volatility and geographic concentration of furnace black production in the United States and China create input cost instability for compounders.
- Metal-filled premium compression:Silver and copper powder loading above 40% by weight pushes aerospace-grade compounds into cost brackets that limit addressable market expansion.
- RoHS substance migration limits:European restrictions on heavy metal content in polymer waste streams complicate recycling pathways for legacy conductive formulations.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives for domestic mobile and component manufacturing are creating first-mover advantage for compounders establishing local compounding capacity.
- Thermal interface materials convergence:Integration of phase-change fillers with conductive polymer matrices opens battery pack thermal management applications beyond traditional EMI shielding.
- SAMR certification acceleration:China's streamlined medical device approval pathways are shortening qualification timelines for conductive housings in diagnostic equipment.
Industry Challenges
- Compounding technician scarcity:Specialized knowledge of percolation threshold control and filler dispersion optimization remains concentrated among aging workforces in Germany and Japan.
- Automotive PPAP timeline compression:Tier-one suppliers face 18-24 month production part approval process cycles that mismatch with EV platform development speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Plastic Compounds Market |
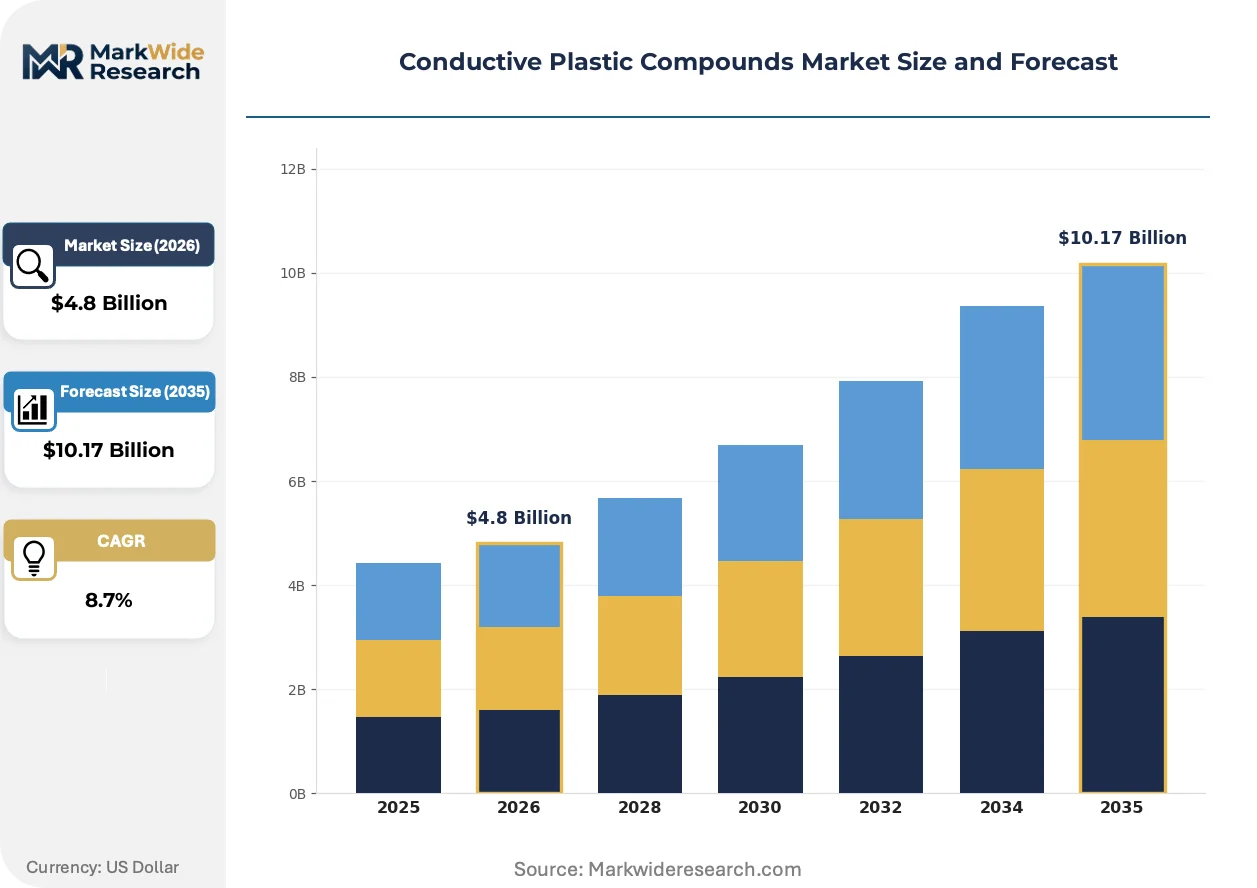
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Blends, Carbon-Filled Compounds, Metal-Filled Compounds, Conductive Coatings End User: Electronics, Automotive, Aerospace, Healthcare Application: EMI Shielding, Static Dissipation, Thermal Management, Antistatic Packaging Form: Granules, Pellets, Sheets, Films |
| Companies Covered | SABIC, LyondellBasell Industries, BASF SE, LG Chem, Covestro AG, Avient Corporation, Celanese Corporation, Mitsubishi Chemical Corporation, RTP Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Plastic Compounds Market Emerging Trajectories
Formulation science is migrating from fixed-grade catalogs toward adaptive compounding platforms that match electrical performance specifications to application-specific duty cycles rather than forcing standard grade selection.
Multi-walled carbon nanotube masterbatch technology is decentralizing compound production by enabling downstream processors to dial surface resistivity in-house rather than relying on centralized custom compounding. Tier-two automotive suppliers in Michigan and Bavaria are adopting on-site dilution systems to reduce inventory SKU counts. This capability diffusion is compressing lead times for prototype iterations while eroding the technical service premium historically commanded by specialized compounders.
EPA's emerging framework for per- and polyfluoroalkyl substances is forcing elimination of fluorinated processing aids from conductive compound manufacturing. Compounders serving medical device markets face reformulation costs exceeding standard automotive qualification expenses. FDA's heightened scrutiny of leachable substances from polymer housings is accelerating migration toward inherently processable conductive resins that require fewer external lubricants.
Specification consolidation among electronics contract manufacturers is displacing fragmented grade proliferation with platform-based procurement. Foxconn and Pegatron are reducing approved material lists from hundreds of conductive grades to fewer than twenty portfolio variants covering resistivity decades. Taiwan's ODM clusters are driving this rationalization fastest, pressuring compounders to demonstrate grade versatility across multiple customer programs rather than single-application optimization.
Conductive Plastic Compounds Market Segmentation
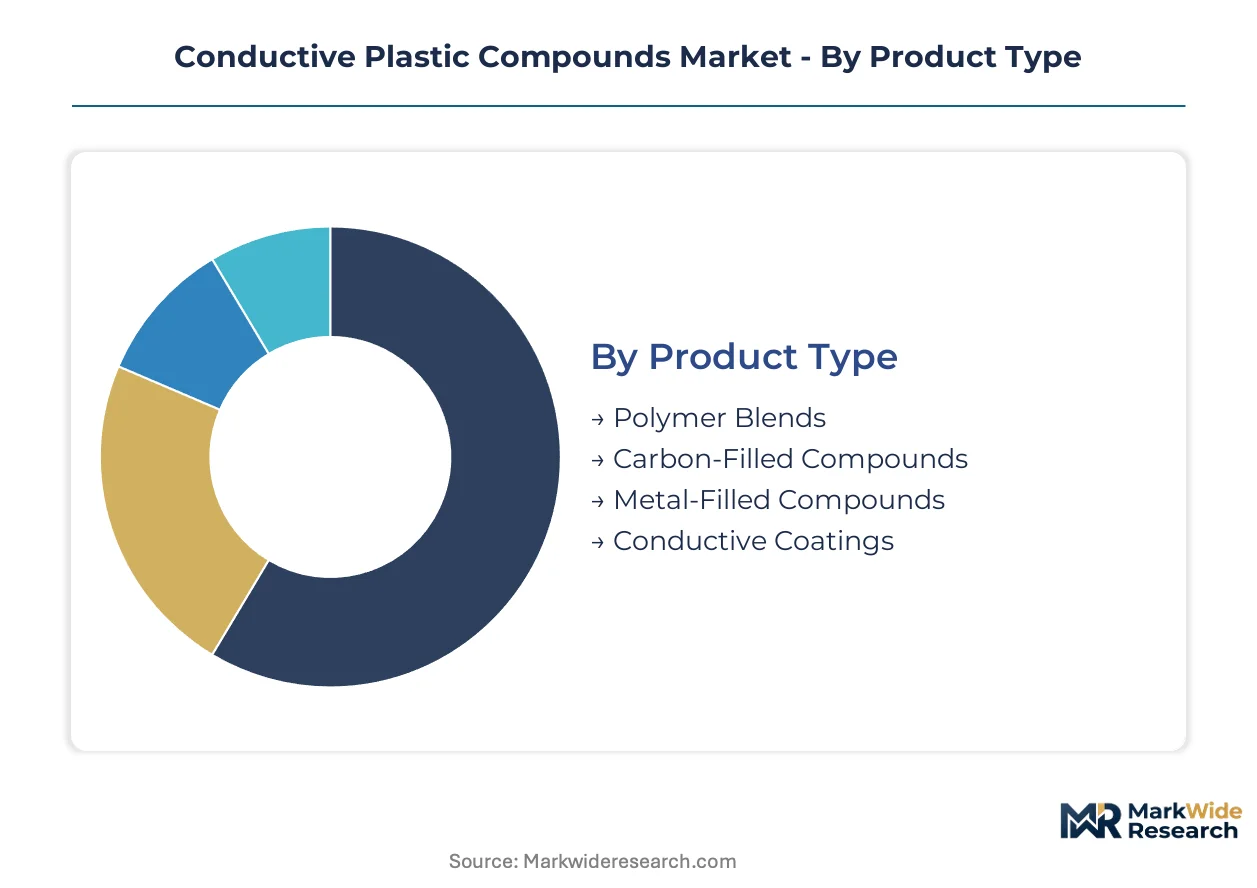
Conductive plastic compounds require precise specification alignment across electrical, thermal, and mechanical properties. Segmentation reveals how formulation choices map to distinct certification burdens and procurement economics in automotive, electronics, and regulated medical applications.
Product Type:
Carbon-filled compounds face REACH substance scrutiny in Europe and EPA reporting requirements in the United States, while metal-filled variants trigger additional RoHS heavy metal compliance protocols for aerospace and medical device markets.
- Carbon-Filled Compounds:Thermoplastic matrices loaded with carbon black or carbon nanotubes achieve surface resistivity from 10^1 to 10^6 ohms per square. Demand concentrates in German automotive EMI shielding for EV battery enclosures, driven by OEM lightweighting mandates under EU fleet emission rules.
- Metal-Filled Compounds:Silver, copper, or nickel powder loadings above 30% by weight deliver sub-10^0 ohm conductivity for thermal interface applications. Aerospace manufacturers in France and the United States specify these for satellite and avionics housings where outgassing limits under ESA and NASA standards apply.
- Polymer Blends:Inherently conductive polymers mixed with engineering resins reduce filler burden for medical device housings.
- Conductive Coatings:Surface-applied conductive layers offer retrofit EMI protection for legacy plastic enclosures.
Carbon-filled compounds sit at the top of the volume ranking, with polymer blends climbing the fastest as REACH restrictions intensify.
End User:
Customer procurement scale varies dramatically, with automotive tier-ones negotiating multi-year framework agreements while healthcare buyers operate on smaller lot sizes with stringent FDA and NMPA documentation requirements.
- Automotive:Battery pack manufacturers and sensor module suppliers specify conductive compounds for EMI containment in high-voltage architectures. China's NEV subsidy programs and Germany's ZEV mandates are pulling volume toward automotive-grade formulations with extended thermal cycling validation.
- Electronics:Contract manufacturers in Taiwan and South Korea consume compounds for smartphone, laptop, and server chassis grounding. Foxconn and Pegatron are consolidating approved material lists, pressuring compounders to demonstrate cross-platform versatility.
- Aerospace:Satellite and defense contractors demand metal-filled grades with traceable filler provenance and outgassing certification.
- Healthcare:Diagnostic equipment housings require FDA 510(k) or NMPA registration for conductive polymer enclosures.
Electronics maintains the largest installed base, though automotive applications are expanding most quickly as EV platform volumes scale.
Application:
Functional performance requirements dictate formulation complexity, with thermal management demanding the highest filler loadings and antistatic packaging accepting lower-cost carbon black solutions.
- EMI Shielding:Compounds attenuate electromagnetic interference across 30 MHz to 18 GHz for automotive radar and 5G infrastructure. South Korean LiDAR manufacturers specify carbon nanotube-loaded grades to manage interference in dense sensor arrays without metal housing weight penalties.
- Thermal Management:Phase-change conductive polymers dissipate heat from power electronics and battery modules. German and Chinese EV producers are qualifying these for pack-level thermal interface layers, replacing traditional gap pads.
- Static Dissipation:Controlled surface resistivity prevents electrostatic damage in semiconductor cleanrooms and explosive atmospheres.
- Antistatic Packaging:Lower-specification carbon-filled grades protect sensitive components during shipping and handling.
EMI shielding commands the highest formulation premium, while thermal management is gaining share fastest as battery energy densities rise.
Form:
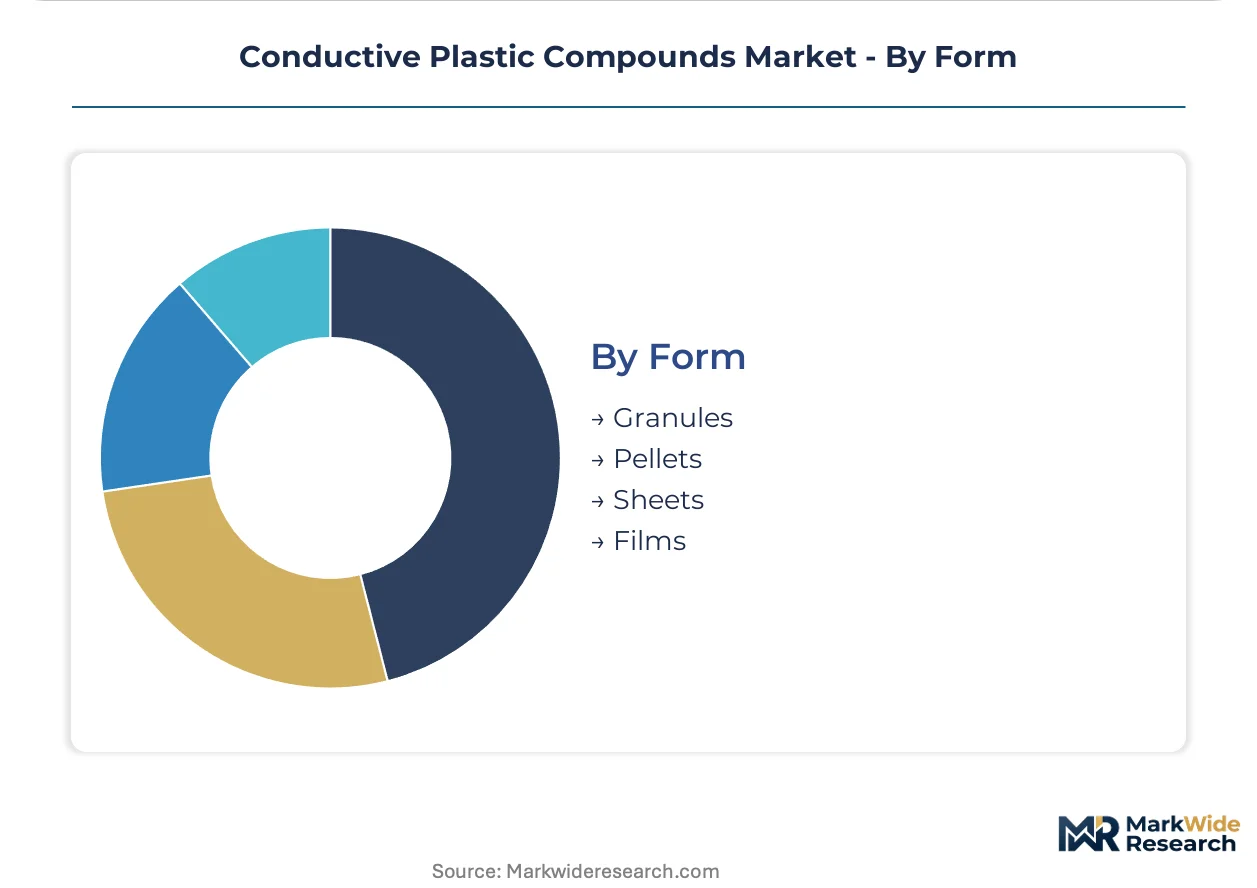
Processing method compatibility determines form selection, with injection molding favoring pellets and thermoforming applications requiring sheet or film formats.
- Pellets:Standardized cylindrical feedstock integrates directly into injection molding and extrusion lines without preprocessing. Tier-two automotive suppliers in Michigan and Bavaria are adopting on-site masterbatch dilution systems to reduce inventory complexity.
- Granules:Irregular particulate form suits compression molding and some extrusion applications where melt homogenization is less critical.
- Sheets:Pre-extruded flat stock enables thermoforming of complex EMI shielding enclosures for medical and aerospace applications.
- Films:Thin-gauge conductive layers serve flexible electronics and conformable thermal interface requirements.
Pellets dominate commercial volume, with sheets showing the steepest expansion trajectory as thermoformed medical and aerospace housings multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Conductive plastic compounds trace their industrial lineage to post-war German chemical engineering and Japanese electronics manufacturing, with commercial scale achieved through automotive supplier networks in the Rhine-Ruhr and Detroit corridors during the 1980s.
Germany
Automotive electrification programs at BMW, Mercedes-Benz, and Volkswagen pull volume toward EMI shielding grades for battery enclosures and sensor modules. The KBA enforces stringent material compliance for EV components under EU fleet emission regulations. Industrial concentration centers on Bavaria's automotive supplier belt around Munich and Ingolstadt, where compounders co-locate with tier-one injection molders.
China
NEV subsidy programs and dual carbon mandates accelerate substitution of metal housings with lightweight conductive plastics in EV battery packs. NMPA and SAMR certification requirements create parallel compliance tracks for medical device and electronics applications. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta host the densest concentration of compound blending capacity serving domestic ODMs.
United States
EPA reporting requirements for carbon black feedstocks and FDA scrutiny of leachable substances from polymer housings shape formulation priorities for medical and automotive markets. The Southeast automotive corridor spanning Tennessee, South Carolina, and Kentucky attracts compounder investment to supply EV platform launches. Michigan retains specialized compounding technician expertise concentrated around Detroit tooling networks.
South Korea
LiDAR and radar module manufacturers specify carbon nanotube-loaded compounds to manage electromagnetic interference in dense autonomous sensor arrays. MFDS regulates medical device polymer enclosures with streamlined pathways for diagnostic equipment. The Seoul Capital Area and Busan-Ulsan corridor concentrate electronics contract manufacturing demand from Samsung and Hyundai supplier ecosystems.
Japan
METI industrial policy supports domestic carbon nanotube masterbatch production to reduce import dependency for high-performance conductive fillers. JIS standards govern surface resistivity specifications for cleanroom and explosive atmosphere applications. The Chubu region around Nagoya maintains legacy compounding expertise serving Toyota's just-in-time supplier networks.
Conductive Plastic Compounds Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and qualification timeline dimensions, with aerospace and medical grades commanding three-to-four-fold pricing multiples over standard automotive EMI compounds. The vendor base organizes into three tiers: integrated resin producers with captive carbon supply, specialized custom compounders with rapid-turn engineering services, and regional blenders serving price-sensitive packaging applications. Dominant competitive moves include backward integration into carbon nanotube production and geographic expansion through joint ventures with Asian electronics contract manufacturers.
Within the integrated-resin-producer tier, SABIC and LG Chem exemplify divergent strategic positions. SABIC leverages its vertically integrated resin backbone to dominate high-volume carbon-filled grades. LG Chem anchors its position through captive carbon nanotube supply, controlling input quality for thermal management applications. RTP Company occupies the specialized custom compounding niche, rewarding engineering responsiveness over commodity scale.
| Leading Market Players |
|---|
| SABIC |
| LyondellBasell Industries |
| BASF SE |
| LG Chem |
| Covestro AG |
| Avient Corporation |
| Celanese Corporation |
| Mitsubishi Chemical Corporation |
| RTP Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders in Germany and Japan anchor premium-grade pricing discipline through multi-decade customer relationships and captive formulation expertise. Their ownership structure insulates pricing from quarterly earnings pressure, allowing sustained investment in automotive qualification timelines that financialized competitors cannot match.
Pricing Analysis
Three-tier pricing structure across aerospace-certified, automotive-qualified, and packaging-grade levels separates compounders by validation burden. Price differentiation hinges on PPAP completion status and carbon nanotube loading precision, with medical-grade variants commanding substantial premiums over standard EMI compounds. Cost compression in automotive carbon-filled grades is intensifying because Chinese NEV producers are consolidating supplier lists around volume commitments. Tier-two packaging buyers exhibit highest price sensitivity, while satellite contractors accept elevated pricing for traceable filler provenance.
Supply Chain Analysis
Single-source vulnerability sits with furnace carbon black production concentrated in the United States and China, where feedstock volatility transmits directly to compounder margins. Raw material dependencies encompass petroleum-derived carbon black, acetylene-processed nanotubes from South Korea, and silver flake for aerospace grades. Tariff exposure on carbon black imports into Europe is forcing German compounders to qualify alternative suppliers. Distribution runs through tier-one automotive supplier hubs in Bavaria, Michigan, and the Yangtze River Delta, with medical device channels requiring specialized cold-chain documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through carbon nanotube masterbatch adoption, which compresses inventory carrying costs and accelerates prototype turnaround for automotive customers.
For Market Incumbents: Hedge against formulation commoditization by securing captive carbon nanotube supply through joint ventures with South Korean or Japanese producers. Reinforce automotive positioning through co-location with tier-one injection molders in the Southeast United States automotive corridor, insulating against logistics disruption while shortening PPAP cycles. For New Entrants and Emerging Players: Digital direct-sales platforms targeting mid-volume electronics contract manufacturers in India bypass entrenched distributor relationships. India's PLI scheme for electronics manufacturing represents the most penetrable white-space, with domestic compounding capacity lagging behind assembly investments. Lead with rapid-turn custom formulation services rather than catalog grades. For Investors and Strategic Acquirers: Valuations sit cheapest among regional European compounders with automotive certification but limited carbon nanotube capabilities. Long-term viability over the next decade rests on successful migration from carbon black to nanotube formulations. Watch for NEV platform standardization announcements from Chinese OEMs as the inflection signal for qualification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Nanotube Production | Captive supply secures input quality for thermal management grades demanded by German EV producers. |
| Joint Venture with Asian Electronics Manufacturers | Local compounding capacity near Foxconn and Pegatron facilities reduces lead times for Taiwan ODM clusters. |
| Medical Device Certification Investment | FDA 510(k) and NMPA pathways open diagnostic equipment housing applications with extended contract durations. |
| On-Site Masterbatch Dilution Systems | Tier-two automotive suppliers in Michigan adopt decentralized processing to compress prototype iteration cycles. |
| Green Manufacturing Transition | Elimination of fluorinated processing aids aligns with EPA emerging substance frameworks for medical markets. |
Methodological Framework
Multiple input streams — technical director interviews at compounders, procurement lead discussions at tier-one automotive suppliers, and regulatory affairs consultations — were reconciled against secondary validation. Primary engagement encompassed plant managers at carbon black production facilities, R&D directors at resin producers, quality engineers at medical device OEMs, and distribution channel partners serving electronics contract manufacturers. Secondary sources included customs trade data for carbon black and carbon nanotube flows, SEC filings from integrated chemical producers, KBA and NMPA regulatory databases, and automotive production registration datasets. Bottom-up volume estimates from individual facility capacities were cross-checked against top-down demand calculations from end-use industry consumption patterns.
Historical shipment trajectories were cross-referenced against panel input from industry participants to establish baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type (carbon-filled, metal-filled, polymer blend), end-use industry (automotive, electronics, aerospace, healthcare), application function (EMI shielding, thermal management, static dissipation), and geographic production cluster. CAGRs were derived from fitted trend analysis adjusted for technology substitution effects and regulatory phase-in schedules. Industry-specific forecast inputs included NEV platform launch timelines, REACH substance restriction implementation calendars, and carbon nanotube capacity expansion announcements.
Feedstock price volatility, regulatory acceleration in China, and automotive platform consolidation are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding substitution rates and qualification timeline compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Saudi Arabia Collagen Market