
 Scratch-Resistant Compound Market | 2026-2036
Scratch-Resistant Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Scratch-Resistant Compound Market Analytics
China is rewriting capacity dynamics in scratch-resistant compounds as integrated petrochemical complexes along the Yangtze River Delta add compounding and surface-treatment lines. PPG Industries leverages its automotive coatings heritage to anchor premium-layering formulations for OEM glazing programs. BASF SE sustains R&D intensity in polyurethane-polymerization pathways, competing on hardness-to-flexibility ratios that differentiate interior from exterior applications. Mitsui Chemicals specializes in optical-grade polycarbonate derivatives, occupying a niche where clarity and mar resistance must coexist.
Scratch-resistant compounds are formulated thermoplastic or thermoset materials engineered to maintain surface integrity under abrasive contact, typically achieving pencil hardness ratings of 2H to 9H depending on crosslink density and ceramic filler loading; their primary purpose is to extend service life of exposed components in transportation, consumer electronics, and built environments. Acrylic compounds dominate furniture and display-covering applications where cost transparency and ease of thermoforming matter more than extreme durability. Polyurethane layering leads automotive interior segments because its elastomeric recovery absorbs micro-scratches from keys and fingernails without whitening. Glass-based surface treatment commands the steepest premium in electronics, where sapphire-like hardness justifies complex vapor-deposition or sol-gel processes.
EPA regulations on VOC emissions from coating operations constrain formulation choices for US-based automotive and industrial equipment applicators, while REACH restrictions on isocyanates and certain photoinitiators force European compounders to qualify alternative curing chemistries. China's MEE enforces GB standards on industrial coating volatile content that tighten progressively, compelling domestic manufacturers to adopt waterborne polymerization or electron-beam curing. Stakeholders must monitor how fragmented national chemical registries alter raw-material fungibility and whether coating-technology patents held by incumbent Japanese and German suppliers create licensing barriers for new capacity entrants.
Market Dynamics
Automotive OEMs in Germany and Japan are consolidating procurement of polycarbonate-based scratch-resistant glazing, compressing supplier qualification timelines and forcing compounders to co-locate technical service teams near assembly plants.
Growth Catalysts
- REACH Phase-In Restrictions:ECHA's tightening controls on isocyanates in polyurethane coatings push European formulators toward UV-curable acrylate alternatives that eliminate solvent-based curing.
- Center-Stack Display Integration:Tier-1 automotive electronics suppliers are specifying 9H pencil-hardness polycarbonate derivatives for curved instrument clusters that replace flat glass.
- Yangtze River Delta Concentration:Integrated petrochemical parks near Ningbo and Shanghai are capturing downstream compounding capacity, shortening raw-material transit for optical-grade surface treatments.
Market Restraints
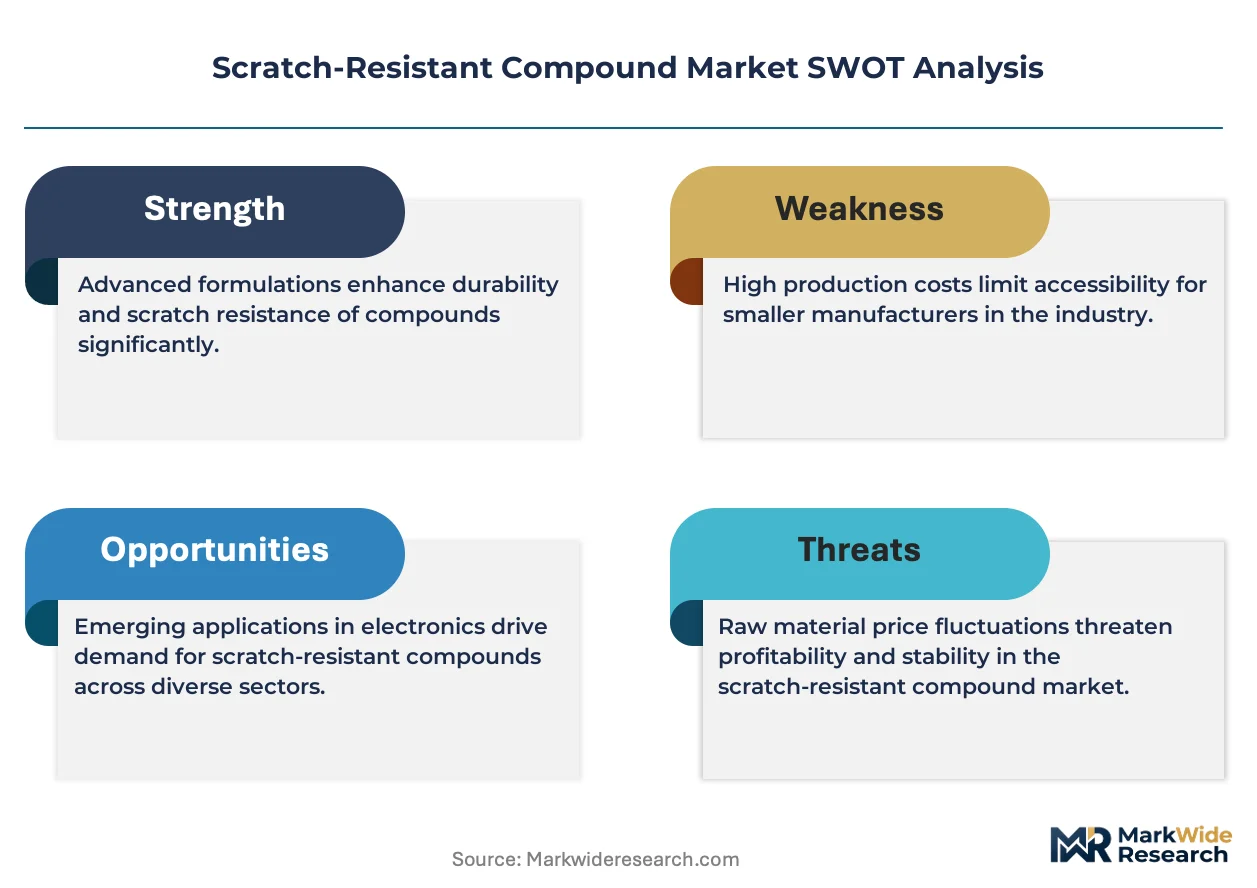
- Ceramic Nanoparticle Cost Volatility:Sol-gel silica precursors and aluminum oxide feedstocks face price swings tied to semiconductor-grade purity demand, squeezing margin on premium electronics coatings.
- Japanese Patent Thickets:Incumbent suppliers hold blocking positions on vapor-deposition chamber designs for sapphire-like hardness layers, creating licensing barriers for new capacity entrants.
- Technical Limitation on Flexibility:Ultra-hard 9H ceramic coatings suffer micro-crack propagation under thermoplastic substrate flexing, restricting their use in foldable device hinge mechanisms.
Strategic Opportunities
- India BIS Certification Pathway:Bureau of Indian Standards is drafting mandatory scratch-resistance grades for automotive glazing, creating first-mover advantage for compounders establishing local testing partnerships.
- Waterborne Polymerization Convergence:Electron-beam curing combined with waterborne polyurethane dispersion eliminates thermal drying ovens, opening retrofit opportunities at legacy automotive paint shops.
- Aftermarket Windshield Repair Channels:Mobile service networks for glass restoration are expanding SKU breadth to include DIY polycarbonate headlight restoration kits with UV-activated hardcoats.
Industry Challenges
- Cross-Functional Formulation Talent:Compounders struggle to hire chemists fluent in both photopolymerization kinetics and abrasion-testing metrology, slowing R&D cycle times.
- Dual Certification Timelines:Simultaneous EPA VOC method validation and REACH SVHC dossier preparation extend product launch windows by 18-24 months for North American-European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scratch-Resistant Compound Market |
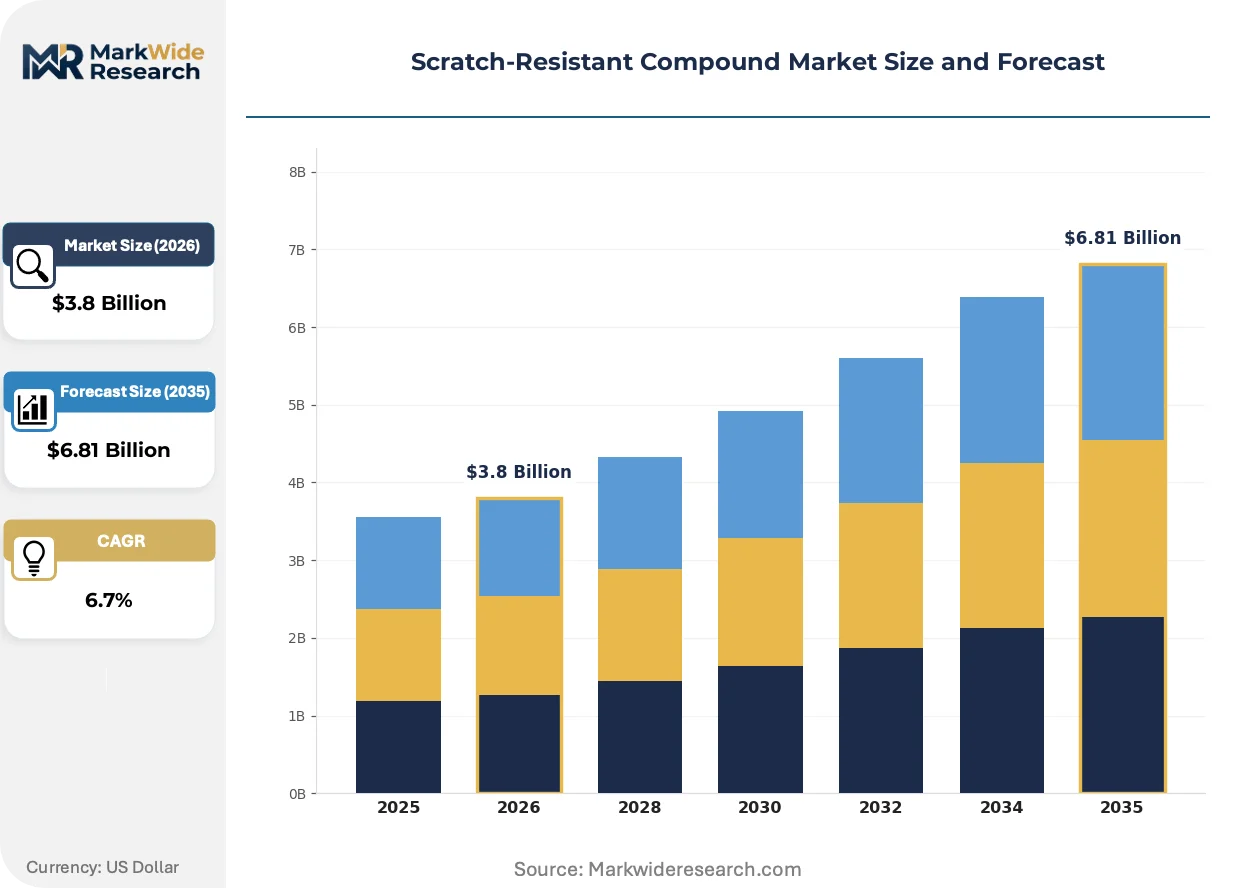
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polycarbonate, Glass, Polyurethane Application: Automotive, Electronics, Furniture, Industrial Equipment End User: Manufacturers, Distributors, Retailers, Contractors Technology: Coating, Layering, Polymerization, Surface Treatment |
| Companies Covered | PPG Industries, Inc., BASF SE, Akzo Nobel N.V., LyondellBasell Industries Holdings B.V., Borealis AG, SABIC, Mitsui Chemicals, Inc., Sherwin-Williams Company, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scratch-Resistant Compound Market Evolving Landscape
Digital twin simulation of coating cure kinetics is compressing pilot-line iteration cycles, while regulatory pressure on volatile content accelerates capital redeployment toward radiation-cured systems.
Self-healing polyurethane networks incorporating dynamic covalent bonds are virtualizing the traditional trade-off between hardness and mar recovery. Automotive interior suppliers in Stuttgart and Toyota City are piloting these materials for door-panel touch surfaces that erase micro-scratches within minutes at cabin temperatures. This capability is virtualizing the specification advantage previously held by thermoset acrylates in premium vehicle segments.
EPA's National Emission Standards for Hazardous Air Pollutants for coating operations are forcing automotive applicators to document mass-balance VOC destruction efficiency above 95 percent. This constraint is accelerating retirement of solvent-borne polyurethane lines at Midwest assembly plants and redirecting capital toward electron-beam curing infrastructure. Tier-2 compounders serving the aftermarket refinishing segment face the steepest compliance cost escalation.
Automotive OEMs are unbundling surface-treatment specifications from resin supply agreements, creating direct procurement relationships with hardcoat formulators previously captive to integrated polymer suppliers. This disintermediation is visible in Germany where BMW and Mercedes-Benz now separately source polycarbonate substrates from Mitsui Chemicals and UV-curable topcoats from PPG Industries, compressing the traditional value-chain margin stack.
Scratch-Resistant Compound Market Segmentation
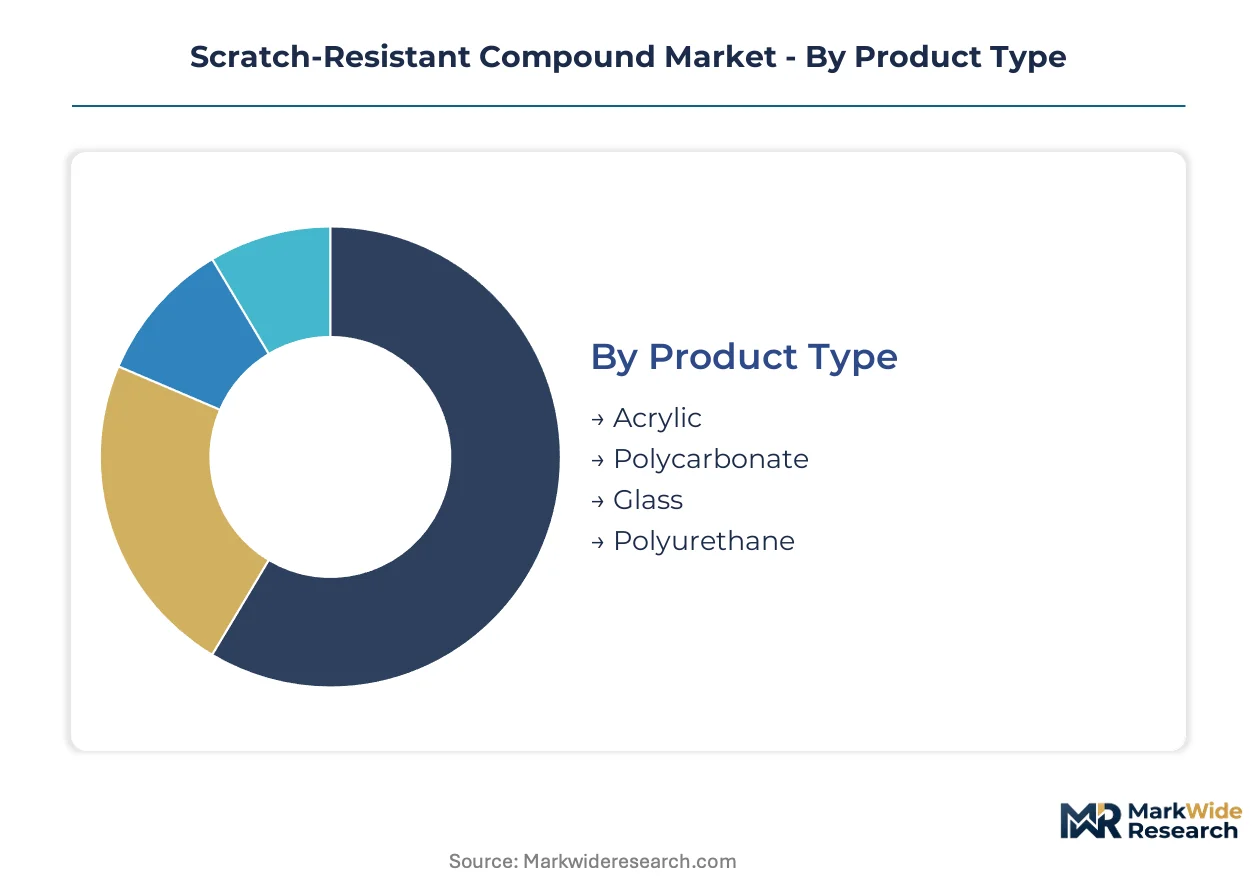
Scratch-resistant compounds fragment across material chemistries and application protocols that dictate performance thresholds, regulatory compliance pathways, and supply chain positioning. Understanding how product types, end-use verticals, and manufacturing technologies intersect reveals where margin concentrates and where capacity expansion faces technical barriers.
Product Type:
Cost tier differentiation separates commodity thermoplastics from precision-engineered ceramics, with hardness ratings and optical clarity driving specification premiums.
- Acrylic:Thermoplastic compounds valued for thermoforming ease and cost transparency in display coverings and furniture laminates. Furniture manufacturers in North America specify cast acrylic sheets for retail fixture applications where 2H-3H pencil hardness suffices and budget constraints dominate.
- Polycarbonate:High-impact thermoplastics achieving optical-grade clarity with 6H-9H surface hardness through UV-curable hardcoat layering. Automotive OEMs in Germany and Japan are consolidating procurement of polycarbonate glazing for curved instrument clusters that replace flat glass in premium vehicle segments.
- Glass:Sapphire-like hardness through vapor-deposition or sol-gel surface modification commands steepest premiums in consumer electronics. Complex fabrication limits deployment to high-value smartphone camera lenses and wearable device displays.
- Polyurethane:Elastomeric networks absorbing micro-scratches through elastic recovery without whitening. Automotive interior suppliers specify polyurethane layering for door panels and center-stack surrounds where fingernail contact is frequent.
Polycarbonate commands the established base. The steepest expansion runs through polyurethane self-healing formulations.
Application:
End-use verticals impose divergent performance specifications, with transportation and electronics demanding hardness-to-flexibility ratios that furniture and industrial equipment rarely require.
- Automotive:Exterior glazing and interior touch surfaces requiring 9H pencil hardness on polycarbonate substrates with elastomeric recovery for door panels. REACH restrictions on isocyanates are pushing European formulators toward UV-curable acrylate alternatives for interior applications.
- Electronics:Display covers, camera lenses, and foldable device hinges where optical clarity must coexist with abrasion resistance. Ceramic nanoparticle loading faces cost volatility from semiconductor-grade purity demand, squeezing margins on premium coatings.
- Furniture:Cost-driven specifications favoring cast acrylic and standard polycarbonate without hardcoat layering. Retail fixture manufacturers prioritize thermoforming speed over extreme durability.
- Industrial Equipment:Heavy-duty polyurethane and glass-ceramic composites for machinery guards and control panel covers. Harsh operating environments justify higher material costs through extended service intervals.
Automotive represents the deepest specification complexity. Electronics is gaining share fastest through foldable device hinge material innovation.
End User:
Customer type determines technical service intensity, with direct OEM relationships demanding co-located application engineering that distributor and retail channels rarely require.
- Manufacturers:Tier-1 automotive electronics suppliers and consumer electronics OEMs specifying 9H pencil-hardness polycarbonate derivatives with direct hardcoat procurement relationships. BMW and Mercedes-Benz separately source substrates and topcoats, compressing traditional value-chain margins.
- Distributors:Aftermarket refinishing segment serving collision repair and glass restoration networks. Mobile service networks expanding SKU breadth to include DIY polycarbonate headlight restoration kits with UV-activated hardcoats.
- Retailers:Consumer-facing channels for furniture and display accessory applications. Standard acrylic sheets move through mass-market home improvement chains with minimal technical support.
- Contractors:Specified procurement for architectural glazing and industrial equipment refurbishment. Project-based demand with irregular volume patterns and extended qualification timelines.
Manufacturers anchor volume concentration. Aftermarket distributors are climbing the fastest through mobile service network expansion.
Technology:
Manufacturing protocol selection locks in capital equipment requirements, regulatory compliance pathways, and raw-material fungibility across geographies.
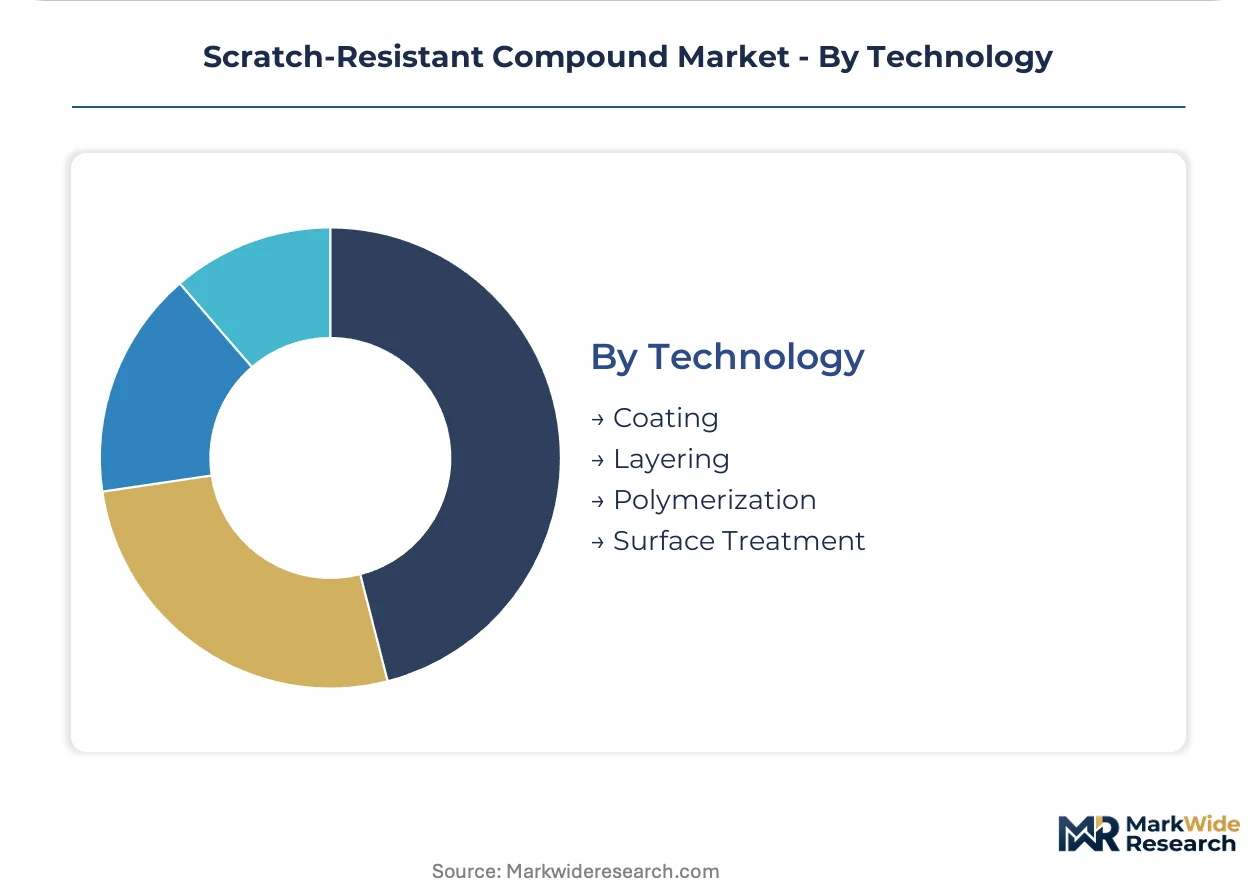
- Coating:Solvent-borne and waterborne polyurethane dispersions applied through spray or dip processes. EPA National Emission Standards forcing automotive applicators toward 95 percent VOC destruction efficiency, accelerating solvent-borne line retirement.
- Layering:Multi-lamination of hardcoat films onto thermoplastic substrates for optical-grade applications. Japanese patent thickets on vapor-deposition chamber designs create licensing barriers for new capacity entrants.
- Polymerization:In-situ formation of scratch-resistant networks through UV or electron-beam curing. Waterborne polymerization combined with electron-beam curing eliminates thermal drying ovens, opening retrofit opportunities at legacy automotive paint shops.
- Surface Treatment:Sol-gel silica and aluminum oxide deposition achieving sapphire-like hardness. Ceramic nanoparticle feedstocks face price swings tied to semiconductor-grade purity demand.
Coating retains the installed equipment base. Polymerization is expanding most quickly through radiation-cured system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes in East China are capturing downstream compounding capacity, while regulatory divergence across major economies fragments formulation standards and raw-material fungibility.
United States
Automotive OEMs in Michigan and Ohio are consolidating polycarbonate glazing procurement for electric vehicle instrument clusters. EPA National Emission Standards for Hazardous Air Pollutants mandate 95 percent VOC destruction efficiency at coating operations, forcing solvent-borne line retirements. Midwest assembly plants near Detroit are redirecting capital toward electron-beam curing infrastructure.
Germany
BMW and Mercedes-Benz separately source polycarbonate substrates and UV-curable topcoats, compressing traditional value-chain margins. REACH Phase-In restrictions on isocyanates push formulators toward UV-curable acrylate alternatives. Stuttgart suppliers pilot self-healing polyurethane networks for door-panel touch surfaces that erase micro-scratches at cabin temperatures.
China
Integrated petrochemical parks near Ningbo and Shanghai capture downstream compounding and surface-treatment capacity for optical-grade applications. MEE enforces GB standards on industrial coating volatile content that tighten progressively, compelling waterborne polymerization adoption. Yangtze River Delta concentration shortens raw-material transit for hardcoat formulators.
Japan
Automotive electronics suppliers in Toyota City specify 9H pencil-hardness polycarbonate derivatives for curved instrument clusters. METI oversees JIS standards alignment with international automotive glazing specifications. Incumbent suppliers hold blocking patent positions on vapor-deposition chamber designs for sapphire-like hardness layers.
India
Bureau of Indian Standards is drafting mandatory scratch-resistance grades for automotive glazing, creating first-mover pathways for compounders establishing local testing partnerships. Central government PLI scheme incentives attract hardcoat formulators to Gujarat and Maharashtra. Pune-based automotive clusters are expanding technical service teams to support OEM qualification timelines.
Scratch-Resistant Compound Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on formulation IP and raw-material positioning. The vendor base stratifies across integrated chemical conglomerates, coatings heritage players, and optical-grade polymer specialists. Three archetypes dominate: petrochemical-integrated compounders leveraging feedstock control, coatings-technology licensors monetizing application know-how, and niche material scientists occupying clarity-hardness intersections. Competitive intensity centers on co-location of technical service teams near automotive assembly plants and patent licensing for vapor-deposition chamber designs.
Among coatings-heritage specialists, PPG Industries and Sherwin-Williams occupy positions anchored in automotive OEM relationships. BASF SE exemplifies the petrochemical-integrated archetype through polyurethane-polymerization pathway control. Mitsui Chemicals represents the optical-grade niche where clarity and mar resistance specifications converge. These three anchors illustrate how competitive positioning fragments across upstream integration depth, application engineering intensity, and materials science specialization.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| BASF SE |
| Akzo Nobel N.V. |
| LyondellBasell Industries Holdings B.V. |
| Borealis AG |
| SABIC |
| Mitsui Chemicals, Inc. |
| Sherwin-Williams Company |
| Axalta Coating Systems |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta container freight corridors connecting Ningbo and Shanghai to European automotive hubs transmit raw-material cost volatility directly into downstream price differentiation. REACH compliance burdens and ceramic nanoparticle purity premiums stratify compound pricing across three performance tiers.
Pricing Analysis
REACH Phase-In restrictions dictate the pricing tier structure across the European scratch-resistant compound market. Three-tier pricing structure across premium optical-grade, standard automotive-grade, and economy furniture-grade levels separates formulations by pencil hardness certification and VOC compliance burden. Pricing pressure stems from semiconductor-grade silica precursor cost volatility squeezing margins on 9H electronics coatings. Aftermarket distributors exhibit highest price sensitivity due to commoditized acrylic sheet competition, while German automotive OEMs absorb premiums for co-located technical service.
Supply Chain Analysis
Extended payment terms from German and Japanese automotive OEMs compress working capital for hardcoat formulators serving tier-2 compounders. Supply concentrates in China, Germany, and Japan, with integrated petrochemical parks near Ningbo capturing downstream compounding capacity. Feedstock dependencies center on sol-gel silica precursors, aluminum oxide nanoparticles, and UV-curable acrylate monomers. Single-source vulnerability runs through Japanese patent holders controlling vapor-deposition chamber designs. Distribution runs through direct OEM procurement relationships that disintermediate traditional resin supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scratch-resistant compound market is recovering from a cyclical trough driven by automotive display integration cycles. OEM unbundling of substrate and hardcoat specifications creates temporary margin compression before consolidation rewards scale.
For Market Incumbents: Entrench position by securing backward integration into ceramic nanoparticle feedstocks and expanding electron-beam curing capacity at legacy Midwest automotive paint shops. Patent licensing revenue from vapor-deposition chamber designs must be defended against Chinese equipment makers developing alternative sol-gel protocols. Co-locating technical service teams near Stuttgart and Toyota City assembly plants preserves specification influence as procurement consolidates.
For New Entrants and Emerging Players: Waterborne polyurethane dispersion supply to Indian automotive clusters represents the most penetrable entry point as BIS certification pathways open. Aftermarket mobile service networks for polycarbonate headlight restoration offer low-capital SKU expansion with UV-activated hardcoat kits. Partner with Pune-based technical service teams to compress OEM qualification timelines.
For Investors and Strategic Acquirers: Optical-grade polycarbonate compounders with captive hardcoat formulation IP present the most defensible acquisition profile over a multi-year horizon. Self-healing polyurethane network patents signal technology inflection ahead of automotive interior specification shifts. Monitor EPA VOC enforcement intensity and MEE GB standard progression as regulatory arbitrage indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Nanoparticles | Captive supply of semiconductor-grade silica precursors insulates margin from purity-driven cost swings. |
| Electron-Beam Curing Infrastructure Deployment | Retrofit at solvent-borne automotive lines accelerates EPA National Emission Standards compliance. |
| India BIS Certification Partnership | First-mover testing relationships lock in automotive glazing specifications before mandatory grades take effect. |
| Self-Healing Polyurethane R&D Investment | Dynamic covalent bond networks virtualize hardness-flexibility trade-offs for interior touch surfaces. |
| Direct Hardcoat Procurement Relationships | Disintermediation from integrated resin suppliers captures value-chain margin compression at BMW and Mercedes-Benz. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive OEM procurement managers, Tier 1 electronics supplier technical directors, hardcoat formulator R&D leads, and petrochemical park operations heads. Secondary validation drew from EPA National Emission Standards filings, ECHA REACH SVHC dossiers, MEE GB standard progressions, customs trade data on ceramic nanoparticle flows, and SEC 10-K disclosures from coatings-heritage suppliers. Bottom-up volume builds across material chemistry grades were triangulated against top-down automotive production and electronics shipment aggregates.
Calibration against historical price realizations for optical-grade polycarbonate derivatives and ceramic nanoparticle feedstocks anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, application vertical, end-user procurement channel, and manufacturing technology protocol. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH restriction phase-in schedules and EPA enforcement intensity assumptions. Industry-specific forecast inputs captured automotive display integration rates and foldable device hinge material adoption curves.
Practitioners should monitor ceramic nanoparticle purity demand from semiconductor foundries and EPA VOC method validation timelines for early signals of cost or compliance inflection. Forecasts reflect documented assumptions on regulatory enforcement trajectories and raw-material fungibility across national chemical registries. Macroeconomic automotive production cycles, ECHA restriction expansion scope, or breakthrough self-healing formulation announcements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
China Collagen Market
Specialty Compounds
India Sealants Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Lithium Compound Market