
 Potassium Hydrogen Sulphite Market | 2026-2036
Potassium Hydrogen Sulphite Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Hydrogen Sulphite Market Analytics
Aftermarket technical service revenue is fragmenting across potassium hydrogen sulphite suppliers as buyers demand formulation support beyond commodity supply. BASF SE leverages its global technical service network to anchor premium relationships with multinational food processors. Chemtex Speciality Limited dominates India-centric water treatment procurement through direct mill relationships and localized blending capabilities.
Potassium hydrogen sulphite (KHSO3) is a white crystalline salt with sulfurous acid character, typically manufactured via absorption of sulfur dioxide in potassium carbonate solution and applied as an oxygen scavenger, reducing agent, and antimicrobial preservative across industrial and food systems. Food Grade material commands the widest volume base through beverage and processed fruit applications, while Pharmaceutical Grade concentrates margin pools due to stringent USP and EP certification requirements that limit qualified supply sources. Technical Grade supply competes aggressively in textile bleaching and leather processing where cost sensitivity favors standardized specifications over purity premiums.
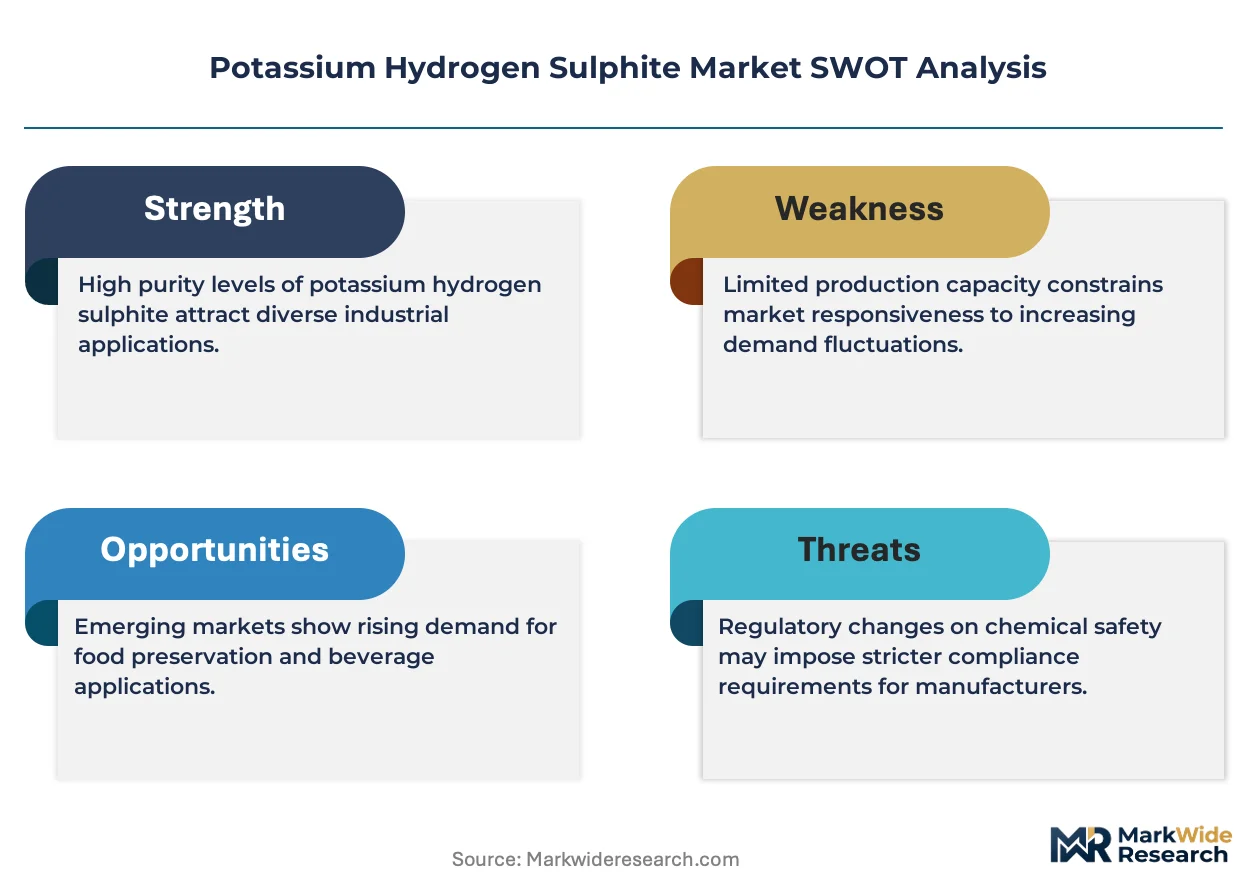
EPA drinking water standards and FDA food additive regulations in the United States, alongside REACH chemical registration and EFSA food contact material evaluations in Europe, collectively elevate analytical documentation burdens and restrict uncertified import channels. China's GB standards and NMPA pharmaceutical excipient rules impose parallel conformity demands that shape export qualification costs for non-domestic producers. Stakeholders must monitor evolving sulfite residue limits in codex-aligned markets and assess backward integration into sulfur dioxide capture infrastructure as a supply security determinant.
Market Dynamics
REACH registration deadlines and FDA food additive purity mandates are compressing qualified supplier pools while processed food processors scramble to secure certified KHSO3 volumes ahead of compliance windows.
Growth Catalysts
- Processed food sector expansion:Beverage and preserved fruit manufacturers in China and India are absorbing record KHSO3 volumes as sulfite-based antimicrobial preservation remains cost-competitive against alternative chemistries.
- REACH compliance deadlines:ECHA registration requirements for sulfur dioxide derivatives are redirecting European procurement toward pre-certified producers with complete toxicological dossiers.
- Textile dyeing capacity scaling:Indian and Bangladeshi fabric processors are expanding oxygen scavenger use in bleaching sequences to reduce water consumption and meet zero-discharge commitments.
Market Restraints
- Sulfur dioxide feedstock volatility:Smelter off-gas supply interruptions and petroleum refining rate fluctuations expose KHSO3 producers to input cost spikes without pass-through mechanisms.
- Substitution pressure from potassium metabisulfite:Winemakers and some food processors are reformulating toward the more stable pyrosulfite salt, eroding KHSO3 volume in traditional strongholds.
- Single-source supply concentration:A limited number of Chinese integrated sulfur chemical producers control merchant market availability, creating geographic vulnerability for non-Asian buyers.
Strategic Opportunities
- Pharmaceutical excipient certification:USP and EP compliance investments open margin-rich supply relationships with sterile formulation manufacturers seeking sulfite antioxidants for parenteral drugs.
- Water treatment application growth:Deoxygenation demand from boiler feed systems and oilfield injection water represents an underpenetrated industrial segment for technical grade material.
- Carbon capture integration:Sulfur dioxide recovery from flue gas treatment installations creates backward integration pathways for KHSO3 producers seeking supply security.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS and ion chromatography expertise required for sulfite speciation testing exceeds available qualified personnel in emerging production regions.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and NMPA food additive approvals demand 18-36 month documentation cycles that delay market entry for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Hydrogen Sulphite Market |
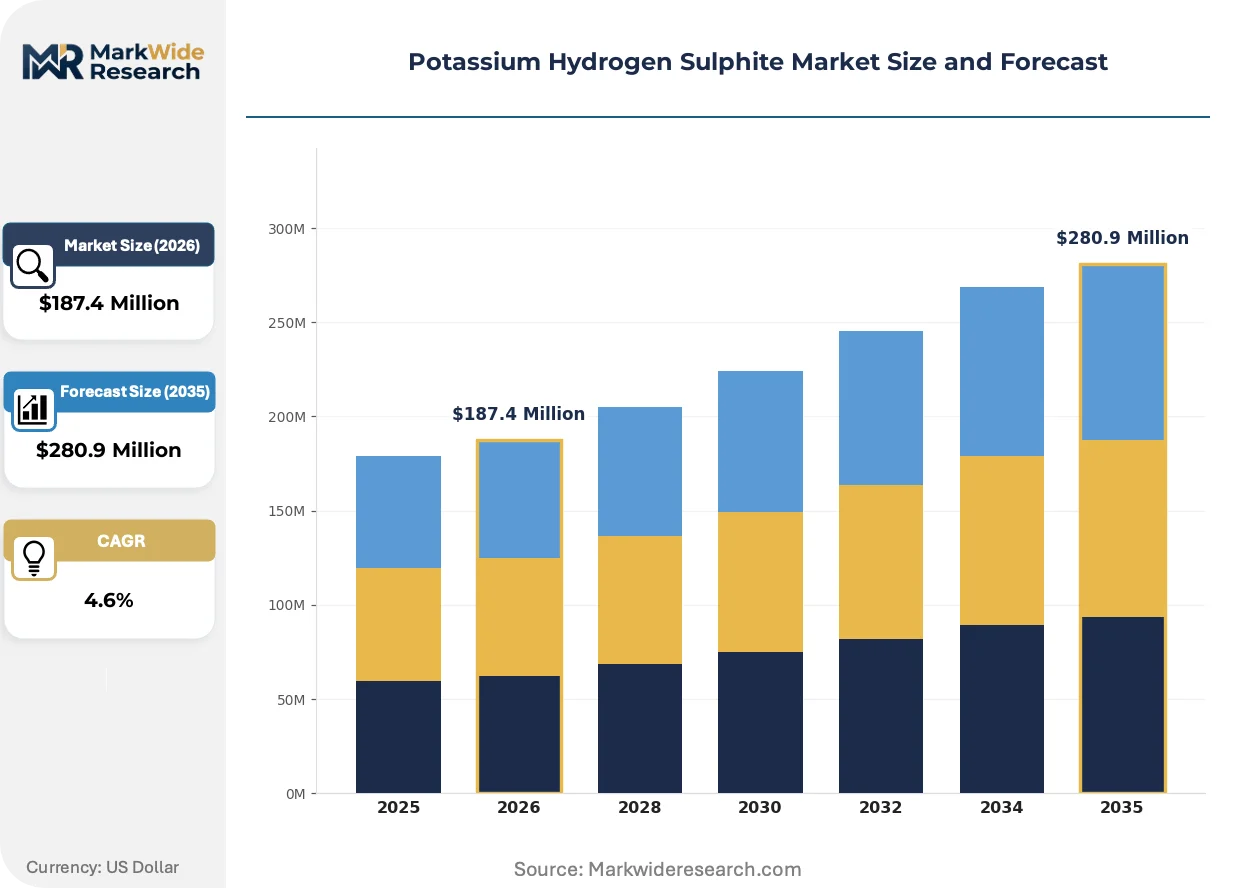
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Technical Grade, Industrial Grade, Pharmaceutical Grade Application: Food Preservation, Water Treatment, Textile Processing, Chemical Synthesis End User: Food Industry, Water Utilities, Textile Manufacturers, Pharmaceutical Companies Distribution Channel: Online Retail, Wholesalers, Direct Sales, Distributors |
| Companies Covered | Aditya Birla Chemicals Thailand, Sigma-Aldrich Co. LLC, Chemtex Speciality Limited, BASF SE, Akos Consulting & Solutions, Tractus, Wubei-Biochem, AkzoNobel, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Hydrogen Sulphite Market Evolving Landscape
Digital process control and automated sulfite monitoring systems are compressing quality variance and enabling real-time specification compliance across dispersed production networks.
Membrane electrolysis-based KHSO3 synthesis is virtualizing traditional absorption tower operations by enabling continuous production with tighter sulfur dioxide conversion efficiency. European and Japanese specialty chemical producers are piloting these modular units for pharmaceutical-grade output. The technology is virtualizing capital deployment patterns, allowing smaller-scale distributed production near end-use clusters rather than centralized mega-facilities.
EFSA's tightened sulfite residue limits in wine and dried fruits are forcing reformulation investments across European processors. The regulation mandates enhanced analytical documentation and traceability systems that favor vertically integrated suppliers with captive testing laboratories. French and Italian winemakers are responding by consolidating procurement relationships toward certified chemical producers with complete allergen labeling capabilities.
Buyers are unbundling technical service contracts from commodity supply agreements, demanding standalone formulation support and application engineering. Multinational food processors now source KHSO3 through separate commercial and technical contracts, fragmenting vendor relationships. This pattern is most pronounced in North American and Western European markets where procurement teams seek specialist service providers distinct from bulk chemical merchants.
Potassium Hydrogen Sulphite Market Segmentation
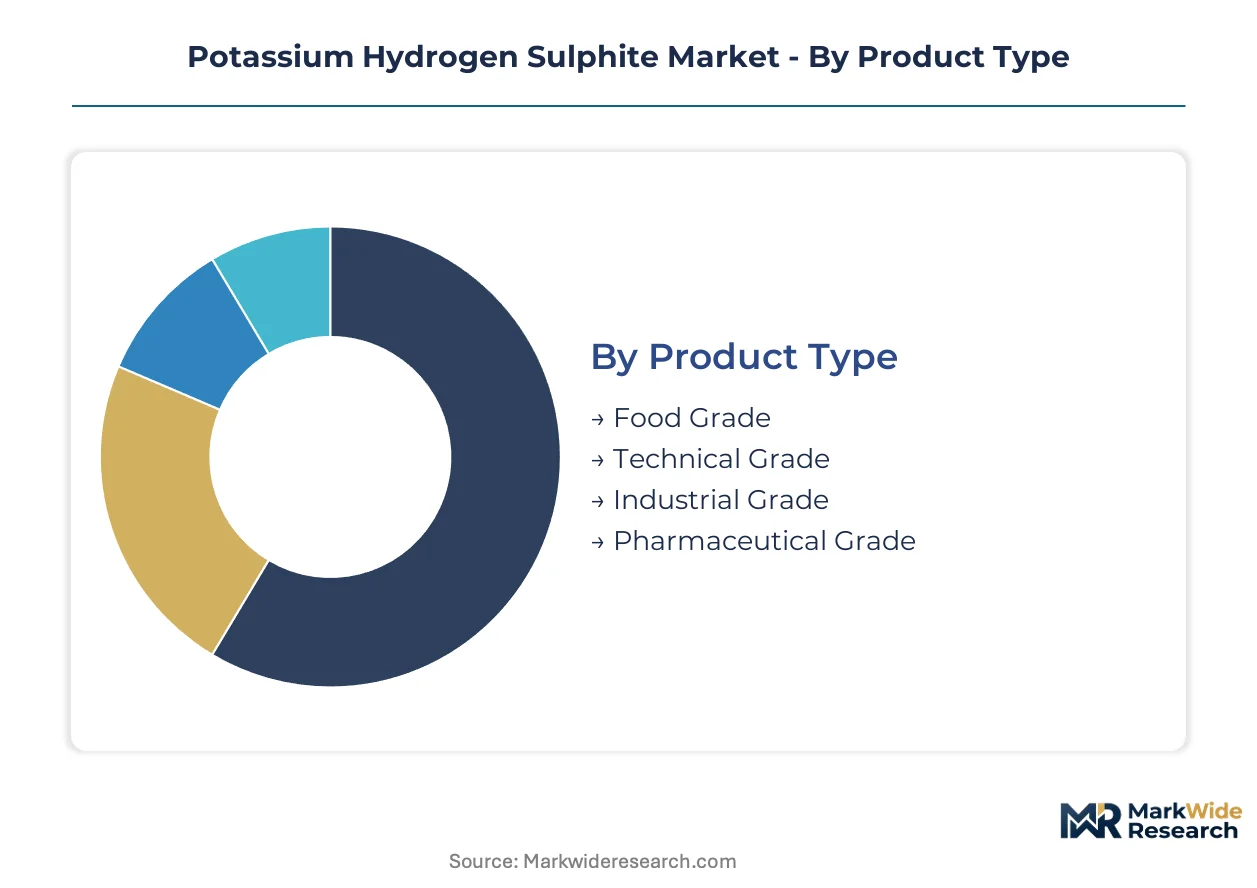
Potassium hydrogen sulphite procurement patterns diverge sharply across purity tiers and end-use requirements. Food and pharmaceutical buyers demand certified grades with complete toxicological documentation, while industrial consumers prioritize volume pricing and supply reliability over specification stringency.
Product Type:
Cost tier differentiation separates commodity chemical buyers from premium-grade seekers in KHSO3 procurement.
- Food Grade:This crystalline salt meets FDA and EFSA sulfite additive specifications for direct food contact. Beverage processors in China and India absorb the largest volumes as antimicrobial preservation in fruit juices and wine. Regulatory tightening on residue limits is compressing qualified supplier pools.
- Pharmaceutical Grade:USP and EP certification requirements limit production to specialized manufacturers with ion chromatography capabilities. Parenteral drug formulators pay substantial premiums for antioxidant-grade material with complete allergen documentation. Supply concentrates among European and Japanese specialty chemical producers.
- Technical Grade:Standardized specifications serve textile bleaching and leather tanning where cost sensitivity dominates procurement decisions.
- Industrial Grade:Bulk oxygen scavenger applications in boiler water treatment drive volume offtake with minimal purity requirements.
Food Grade holds installed capacity. Pharmaceutical Grade is rotating up the share rankings.
Application:
End-use function determines specification intensity and regulatory exposure across KHSO3 consumption.
- Food Preservation:Sulfurous acid character inhibits enzymatic browning and microbial spoilage in processed fruits, beverages, and wine. Chinese and Indian processors scale usage as alternative preservatives face cost or efficacy limitations. Substitution pressure from potassium metabisulfite is eroding volume in winemaking segments.
- Water Treatment:Oxygen scavenging properties protect boiler systems and oilfield injection infrastructure from corrosion. Deoxygenation demand from Indian textile mills and Bangladeshi fabric processors is climbing fastest as zero-discharge commitments tighten.
- Textile Processing:Bleaching sequence reduction and water consumption controls drive adoption among South Asian dye houses.
- Chemical Synthesis:Reducing agent applications in specialty chemical manufacturing require consistent sulfite content with minimal heavy metal contamination.
Food Preservation dominates current volume. Water Treatment is expanding most quickly.
End User:
Customer type shapes contract structures, with multinational food processors unbundling technical service from commodity supply.
- Food Industry:Processed fruit and beverage manufacturers require formulation support beyond bulk chemical delivery. BASF SE anchors premium relationships through global technical service networks. Procurement teams increasingly separate commercial and technical contracts.
- Water Utilities:Municipal and industrial water treatment operators prioritize supply security and logistics reliability over purity premiums. Chemtex Speciality Limited dominates India-centric procurement through direct mill relationships.
- Textile Manufacturers:Fabric processors in Bangladesh and Vietnam scale oxygen scavenger use to meet buyer sustainability requirements.
- Pharmaceutical Companies:Sterile formulation manufacturers seek sulfite antioxidants with complete USP and EP documentation packages.
Food Industry commands the widest contract base. Pharmaceutical Companies are gaining share fastest.
Distribution Channel:
Supply chain configuration reflects customer scale and geographic concentration patterns.
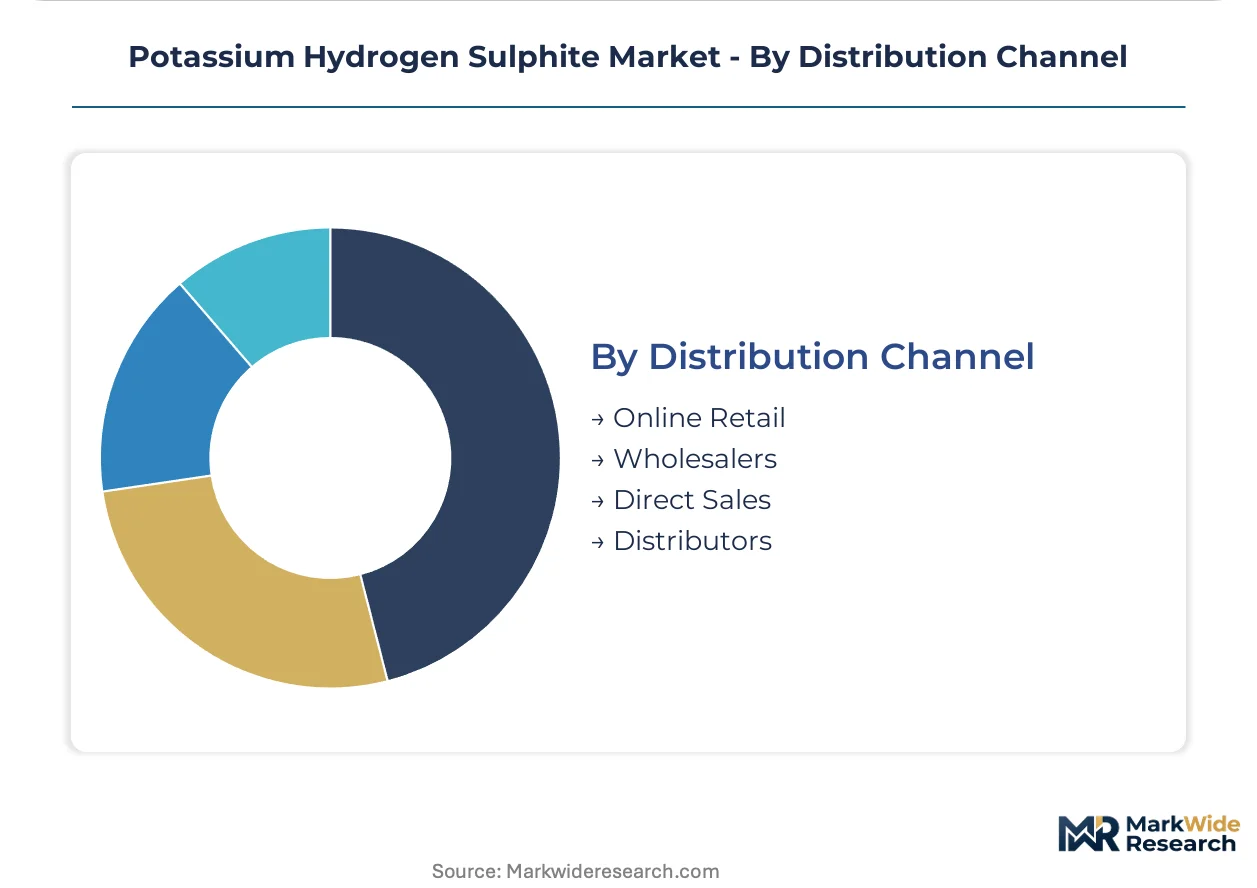
- Direct Sales:Large-volume food processors and pharmaceutical manufacturers negotiate long-term offtake agreements with certified producers. Contract structures increasingly specify analytical documentation and traceability systems.
- Distributors:Regional chemical distributors serve fragmented textile and water treatment demand with localized inventory and blending capabilities.
- Wholesalers:Bulk merchants handle standardized industrial grade material with minimal technical support requirements.
- Online Retail:E-commerce platforms capture small-laboratory and research-scale procurement with rapid fulfillment expectations.
Direct Sales holds the largest contract value. Distributors are climbing the fastest in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. China and India deploy potassium hydrogen sulphite primarily for food preservation and textile processing, while European and North American buyers concentrate procurement in pharmaceutical-grade material for sterile formulation applications.
China
Integrated sulfur chemical producers in Jiangsu and Shandong provinces supply domestic food processors and textile dye houses with technical and food-grade material. GB standards for food additives and NMPA pharmaceutical excipient rules shape export qualification requirements. The Yangtze River Delta cluster anchors production capacity expansion as sulfur dioxide recovery from flue gas treatment integrates into manufacturing operations.
India
Chemtex Speciality Limited dominates water treatment procurement through direct mill relationships in Gujarat and Maharashtra, while food preservation demand scales in Karnataka and Tamil Nadu processing hubs. FSSAI sulfite additive regulations and BIS purity specifications compress qualified supplier pools. Mumbai-Pune industrial corridor fabricators are expanding oxygen scavenger use to meet zero-discharge commitments in textile bleaching sequences.
Germany
REACH registration deadlines and ECHA toxicological dossier requirements redirect European procurement toward pre-certified producers with complete sulfur dioxide derivative documentation. BASF SE leverages its Ludwigshafen technical service network to anchor premium relationships with multinational food processors. Bavarian and North Rhine-Westphalian chemical clusters concentrate pharmaceutical-grade manufacturing for parenteral drug formulators seeking USP and EP compliance.
United States
FDA food additive purity mandates and EPA drinking water standards elevate analytical documentation burdens for sulfite antioxidant imports. Processed fruit and beverage manufacturers in California and Florida scramble to secure certified volumes ahead of compliance windows. Gulf Coast petrochemical infrastructure provides sulfur dioxide feedstock proximity for domestic KHSO3 synthesis, though merchant market availability remains constrained by single-source supply concentration risks.
Japan
METI industrial chemical regulations and PMDA pharmaceutical standards limit qualified production to specialized manufacturers with ion chromatography capabilities. Osaka-Kobe chemical corridor producers pilot membrane electrolysis-based synthesis for pharmaceutical-grade output. Japanese specialty chemical firms are virtualizing capital deployment patterns through modular distributed production units near end-use clusters rather than centralized mega-facilities.
Potassium Hydrogen Sulphite Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The supplier base stratifies between multinational chemical conglomerates with integrated technical service networks and regional specialists with localized blending and direct mill relationships. Three archetypes dominate: integrated sulfur chemical producers controlling feedstock-to-derivative value chains, specialty chemical firms with pharmaceutical certification capabilities, and water treatment-focused distributors with fragmented textile and utility relationships. Competitive moves center on backward integration into sulfur dioxide capture infrastructure and unbundling of technical service contracts from commodity supply agreements.
Among Germany-based chemical conglomerates, BASF SE exemplifies the premium-tier archetype through global technical service anchoring with multinational food processors. Chemtex Speciality Limited represents the India-centric specialist model with dominant water treatment procurement through direct mill relationships and localized blending capabilities. Sigma-Aldrich Co. LLC occupies the laboratory and research-scale distribution position within North American markets.
| Leading Market Players |
|---|
| Aditya Birla Chemicals Thailand |
| Sigma-Aldrich Co. LLC |
| Chemtex Speciality Limited |
| BASF SE |
| Akos Consulting & Solutions |
| Tractus |
| Wubei-Biochem |
| AkzoNobel |
| Solvay |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor anchors cost dynamics for potassium hydrogen sulphite, with container rates from Jiangsu ports to European pharmaceutical buyers amplifying price spreads between food-grade commodity volumes and certified excipient material. This logistics differential reinforces supply concentration effects, as integrated sulfur chemical producers in Shandong and Jiangsu capture margin premiums through captive sulfur dioxide recovery while distant buyers absorb landed cost penalties that widen tiered pricing separation.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade procurement, with parenteral drug formulators locking in eighteen-to-thirty-six month contracts for USP-certified material while food processors mix annual framework deals with spot purchases for technical grade volumes. Price differentiation rests on certification burden and analytical documentation depth, with ion chromatography-equipped producers commanding substantial premiums over standard-grade merchants. Cost compression in textile and leather processing tiers is intensifying because Indian and Bangladeshi dye houses prioritize volume scale over purity thresholds. Water treatment operators exhibit highest price sensitivity, accepting variable sulfite content in exchange for logistics reliability, whereas sterile formulation manufacturers show minimal elasticity due to regulatory compliance requirements.
Supply Chain Analysis
Extended payment terms from Indian textile mills and supply-chain finance facilities through Mumbai-based distributors are restructuring working capital requirements for regional potassium hydrogen sulphite merchants. Geographic supply concentration centers on China, India, and Germany, with Jiangsu and Shandong provinces hosting integrated sulfur dioxide recovery operations that feed captive derivative synthesis. Raw material dependencies draw from smelter off-gas sulfur dioxide, potassium carbonate feedstock, and petroleum refining byproduct streams. Single-source vulnerability pervades merchant market availability, as a limited cohort of Chinese integrated producers controls non-captive supply. Distribution runs through direct mill relationships for water treatment and textile segments, while pharmaceutical procurement channels through certified distributors with complete toxicological dossiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated multinational food processors, who are unbundling technical service contracts from commodity supply agreements and fragmenting vendor relationships across separate commercial and specialist service providers.
For Market Incumbents: Insulate pharmaceutical-grade margin pools through accelerated USP and EP certification investments, as potassium metabisulfite substitution threatens traditional winemaking volumes. BASF SE's technical service anchoring model offers a template for premium relationship defense. Backward integration into sulfur dioxide capture infrastructure provides supply security leverage against feedstock volatility from smelter and refinery rate fluctuations. For New Entrants and Emerging Players: Southeast Asian water treatment procurement represents the most penetrable white-space target, with Vietnamese and Indonesian boiler deoxygenation demand scaling faster than qualified local supply. Pharmaceutical excipient certification opens margin-rich relationships with sterile formulation manufacturers seeking sulfite antioxidants. A go-to-market angle emphasizing localized blending capabilities and direct utility relationships mirrors Chemtex Speciality Limited's India-centric dominance model. For Investors and Strategic Acquirers: Regional specialists with captive ion chromatography capabilities and established direct mill relationships in water treatment and textile processing offer the strongest acquisition target profile for medium-term value capture. Long-term viability hinges on regulatory compliance moats rather than commodity scale, with certification-limited supply pools sustaining premium pricing across pharmaceutical and food-grade tiers. The signal to watch is EFSA sulfite residue limit tightening, which would accelerate consolidation toward vertically integrated producers with captive testing laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Dioxide Recovery | Captive feedstock supply from flue gas treatment insulates producers against smelter off-gas volatility. |
| Pharmaceutical Excipient Certification Investment | USP and EP compliance opens sterile formulation relationships with complete allergen documentation. |
| Membrane Electrolysis Synthesis Deployment | Modular production units enable distributed manufacturing near end-use clusters in Japan and Europe. |
| Technical Service Unbundling | Separate formulation support contracts fragment vendor relationships and create specialist service opportunities. |
| Zero-Discharge Water Treatment Partnership | Indian and Bangladeshi textile mill commitments drive oxygen scavenger volume expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, chemical industry association reports, and regulatory filings from FDA, ECHA, and NMPA. Primary interviews engaged plant managers at sulfur derivative facilities, procurement leads at downstream food processors and pharmaceutical formulators, distribution channel partners in India and Southeast Asia, and technical R&D directors overseeing sulfite specification compliance. Bottom-up capacity and consumption estimates triangulated against top-down trade flow analysis and regional production cluster mapping.
Forecast inputs incorporate grade tier differentiation across food, pharmaceutical, technical, and industrial specifications; end-use industry segmentation spanning food preservation, water treatment, textile processing, and chemical synthesis; packaging format variations; and regional production hub concentration patterns. CAGRs were derived through regression analysis of historical consumption against projected downstream capacity expansion and regulatory compliance timeline impacts. Industry-specific inputs include sulfite residue limit evolution in codex-aligned markets and sulfur dioxide feedstock availability from flue gas recovery infrastructure deployment.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by specialty chemical producers or rapid membrane electrolysis scale-up would shift outcomes. Macroeconomic deviation in processed food export demand, regulatory acceleration of sulfite restrictions, or technological displacement by alternative antioxidant chemistries would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Tosyl Chloride Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Global Engineering Plastic Compounds Market