
 Hypalon Market | 2026-2036
Hypalon Market Size, Share, and Industry Trends Forecast 2026-2036
Hypalon Market Analytics
Specialty chemical distribution channels serving the Asia-Pacific rubber industry are rewriting procurement patterns for chlorosulfonated polyethylene intermediates. DuPont sustains technology leadership in high-performance elastomer formulations through its historical CSPE patent portfolio and application expertise. Tosoh Corporation dominates captive supply chains for specialty chlorination reagents essential to Hypalon synthesis. Weifang Polygrand Chemical leverages coastal logistics infrastructure to serve marine fabricators across Shandong Province and neighboring manufacturing zones.
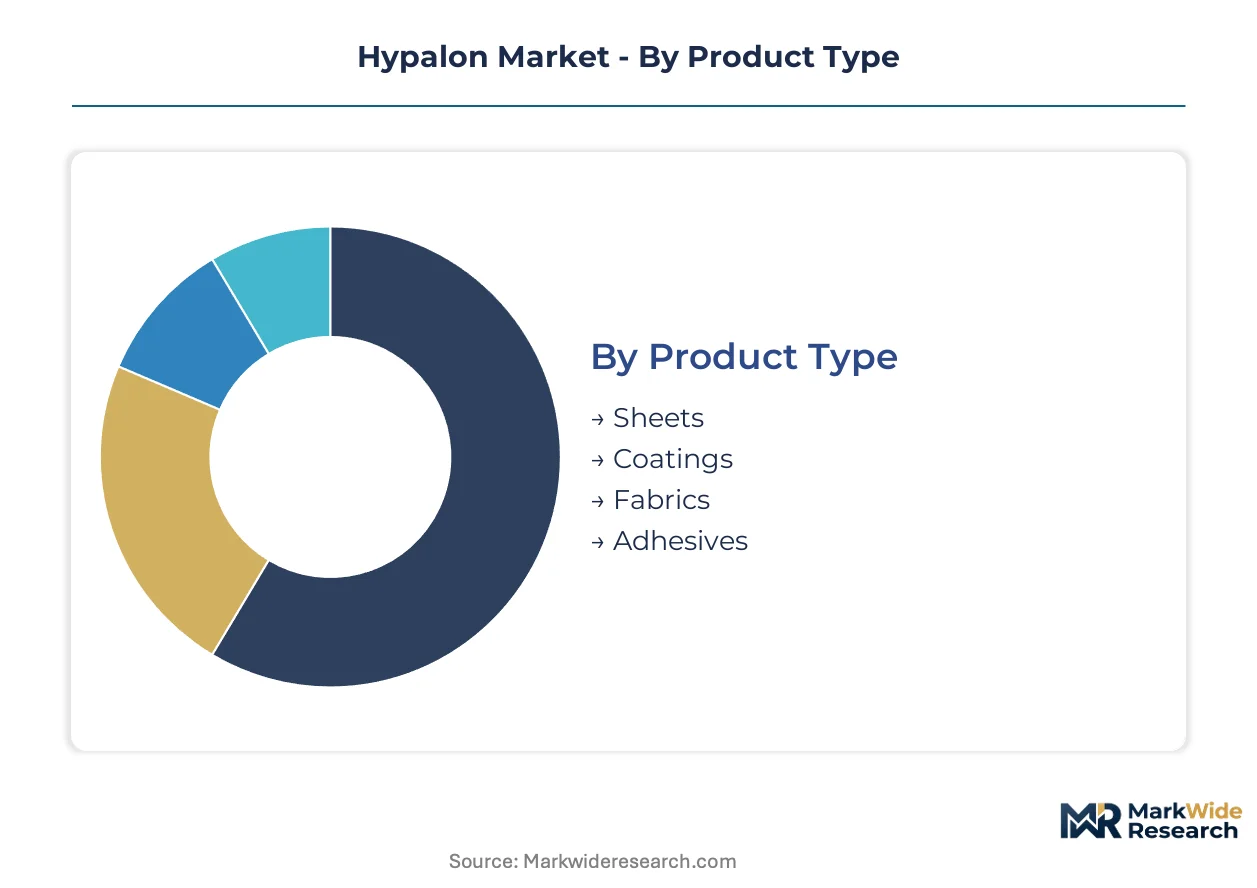
Hypalon denotes chlorosulfonated polyethylene, a synthetic rubber produced by treating polyethylene with chlorine and sulfur dioxide to yield a material with 25-43% chlorine content and 1.0-1.5% sulfur, imparting exceptional ozone resistance, chemical inertness, and thermal stability across -40°C to 150°C operating ranges. Industrial fabricators value this elastomer primarily for protective coatings, inflatable structures, and electrical insulation requiring prolonged exposure to weathering and corrosive media. Coatings command the dominant product type position due to their ubiquity in marine deck coverings and industrial tank linings, while sheets experience accelerated uptake in aerospace gasket applications where outgassing specifications are stringent. The fabrics segment anchors margin pools through customized textile-laminate combinations for military and commercial inflatable craft.
REACH restrictions on persistent organic pollutants and the EU F-Gas Regulation constrain formulation chemistries available to European Hypalon processors, compelling reformulation investments or supply chain relocation. China's MEE enforces emissions caps on chlor-alkali facilities that feed chlorosulfonated polyethylene production, tightening feedstock availability for domestic and export markets. The US EPA oversees chlorinated solvent handling under TSCA and Clean Air Act provisions affecting manufacturing site permitting. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where formulation registration costs and compliance timelines will reshape competitive manufacturing location decisions.
Market Dynamics
China's dual carbon goals and MEE emissions caps on chlor-alkali facilities are compressing feedstock availability for chlorosulfonated polyethylene, forcing manufacturers to relocate or reconfigure production assets.
Growth Catalysts
- Marine fabric standards:Tightening chemical exposure regulations for inflatable boat construction are elevating specification requirements that favor Hypalon-coated textiles over PVC alternatives in coastal manufacturing zones.
- REACH persistent organic pollutant restrictions:European reformulation mandates are creating premium market tiers for compliant chlorosulfonated polyethylene formulations with verified supply chain documentation.
- Chlorination reagent captive supply:Specialty chemical producers in East Asian manufacturing clusters are securing dedicated intermediate streams that stabilize output for marine coating applications.
Market Restraints
- Chlorine feedstock volatility:Chlor-alkali capacity constraints under China's MEE emissions caps are creating input cost instability for domestic and export-oriented Hypalon producers.
- Fluoropolymer substitution threat:Advanced FEP and ETFE materials are capturing aerospace gasket applications where outgassing specifications previously favored chlorosulfonated polyethylene sheets.
- EU F-Gas Regulation friction:Formulation chemistry restrictions are extending compliance timelines and registration costs for European processors seeking to maintain marine coating product lines.
Strategic Opportunities
- India's coastal manufacturing expansion:Gujarat and Tamil Nadu shipbuilding clusters present underpenetrated demand for inflatable craft fabrics as domestic naval procurement scales.
- Photovoltaic module sealing:Convergence of chlorosulfonated polyethylene with ethylene-vinyl acetate lamination technologies is opening solar panel edge-seal applications requiring 25-year weathering resistance.
- Japan METI green procurement incentives:Public tender preferences for low-emission rubber products are creating certified supplier channels for compliant Hypalon coating manufacturers.
Industry Challenges
- Chlorosulfonation process engineering expertise:The specialized skill set for controlled polyethylene chlorination and sulfur dioxide treatment is concentrated among retiring technical workforces in legacy production facilities.
- REACH registration timeline compression:Extended substance evaluation periods for chlorinated elastomers are delaying market access for reformulated products targeting European marine fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypalon Market |
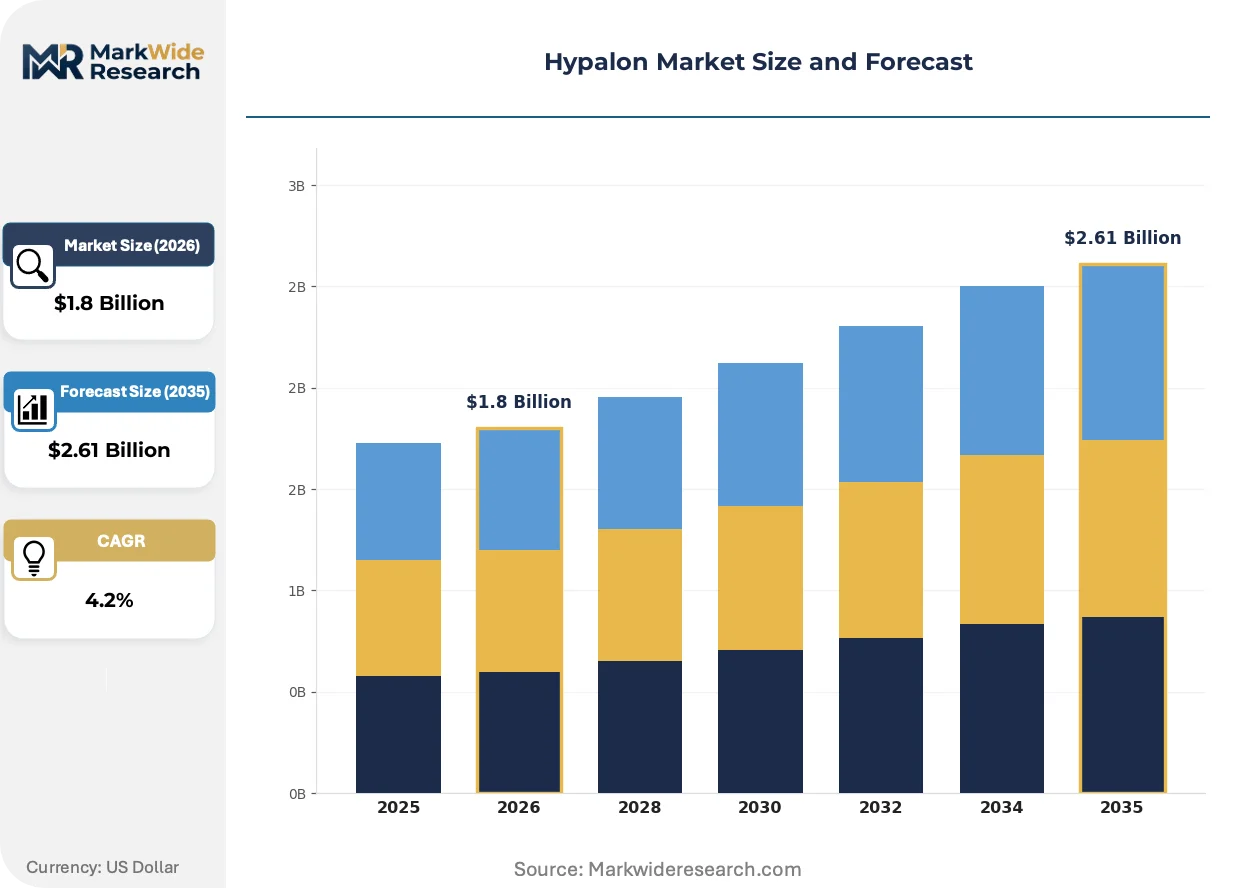
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Coatings, Fabrics, Adhesives End Use Industry: Automotive, Marine, Construction, Aerospace Application: Electrical Insulation, Protective Coverings, Industrial Linings, Consumer Goods Form: Rolls, Pre-cut Sheets, Custom Shapes, Liquid Formulations |
| Companies Covered | Weifang Polygrand Chemical, DuPont, Tosoh Corporation, Orion Engineered Carbons, Saint-Gobain Performance Plastics, Jiangxi Hongrun Chemical Industry, Shandong Shanxu New Material, Pennel & Flipo, Jilin Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypalon Market Evolving Landscape
Water-based dispersion coating technologies are disrupting solvent-dependent application methods across marine and industrial fabric segments, compressing environmental compliance costs while altering equipment investment requirements.
Advanced aqueous chlorosulfonated polyethylene dispersions are eliminating volatile organic compound emissions during inflatable boat fabric lamination. Marine fabricators in Shandong Province and Guangdong manufacturing clusters are retrofitting coating lines to accommodate these systems. Conventional solvent-based application equipment is rendering obsolete across new facility investments, forcing capital reallocation toward dispersion-compatible drying and curing infrastructure.
China's MEE enforcement of dual carbon goals is tightening emissions caps on chlor-alkali facilities that supply chlorine feedstock for Hypalon synthesis. Domestic chlorosulfonated polyethylene producers are relocating capacity to industrial parks with integrated waste gas treatment or importing chlorine derivatives from Southeast Asian suppliers. Coastal provinces with established rubber chemical supply chains are absorbing production gravity as inland facilities face compliance-driven curtailments.
Direct mill relationships are displacing traditional specialty chemical distribution channels for chlorosulfonated polyethylene intermediates. Marine fabricators and industrial coating applicators in East Asian manufacturing zones are consolidating procurement volumes to secure allocation priority from captive chlorination reagent producers. This concentration is most visible in Shandong Province, where Weifang-area fabricators are negotiating term supply agreements that bypass regional distributors entirely.
Hypalon Market Segmentation
Chlorosulfonated polyethylene applications diverge sharply across product configurations and industrial end-uses. Marine fabricators, automotive seal manufacturers, and construction membrane specialists each impose distinct specification requirements that reshape formulation priorities and margin structures across the value chain.
Product Type:
Cost tiers separate commodity elastomer grades from engineered formulations demanding captive chlorination infrastructure and technical service support.
- Coatings:Solvent-based and aqueous dispersion systems dominate marine deck coverings and industrial tank linings, with water-based technologies displacing conventional application methods under tightening VOC regulations. Demand concentrates in Shandong Province manufacturing clusters where fabricators retrofit coating lines to accommodate dispersion-compatible curing infrastructure.
- Fabrics:Textile-laminate combinations for inflatable craft anchor premium margin pools through customized adhesion engineering and military specification compliance. East Asian coastal provinces with established rubber chemical supply chains absorb production gravity as specifications tighten for chemical exposure resistance.
- Sheets:Calendered and molded stock serve gasket and membrane fabricators requiring defined thickness tolerances.
- Adhesives:Specialty bonding formulations link dissimilar substrates in industrial assembly operations.
Coatings command the established base. The steepest expansion runs through fabrics.
End Use Industry:
Application maturity varies dramatically across sectors, with aerospace outgassing specifications and marine fabric standards driving specification divergence.
- Marine:Inflatable boat construction and deck covering applications impose the most stringent chemical exposure and UV resistance requirements, elevating Hypalon-coated textiles over PVC alternatives in coastal manufacturing zones from Weifang to Guangdong.
- Aerospace:Gasket and seal applications demand low-outgassing sheet formulations meeting stringent thermal cycling specifications, though fluoropolymer substitution threatens share in next-generation aircraft programs.
- Automotive:Underhood seals and weatherstripping utilize chlorosulfonated polyethylene for ozone and fluid resistance in demanding thermal environments.
- Construction:Roofing membranes and waterproofing systems deploy sheet and coating forms for extended weathering performance.
Marine anchors the revenue base. Aerospace generates the steepest specification-driven premium expansion.
Application:
Functional requirements determine formulation complexity, with electrical and protective segments demanding certified supply chain documentation.
- Protective Coverings:Industrial tank linings, marine deck surfaces, and equipment enclosures require chemical inertness across pH extremes and solvent exposure, with REACH-compliant formulations commanding premium positioning in European procurement channels.
- Electrical Insulation:Wire jacketing and cable sheathing exploit thermal stability across -40°C to 150°C operating ranges, with Japan METI green procurement incentives creating certified supplier channels for compliant manufacturers.
- Industrial Linings:Corrosion-resistant barrier systems protect process equipment in chemical handling facilities.
- Consumer Goods:Recreational inflatable products and protective cases utilize lower-specification formulations.
Protective coverings dominate volume throughput. Electrical insulation captures the steepest margin expansion trajectory.
Form:
Supply chain configuration and customer scale determine format preference, with direct mill relationships displacing distribution channels for volume consumers.
- Rolls:Continuous sheet stock serves high-volume fabricators and coating applicators with standardized width and thickness requirements, with East Asian marine fabricators consolidating procurement volumes to secure allocation priority from captive chlorination reagent producers.
- Liquid Formulations:Dispersion and solution products enable spray, dip, and brush application methods, with aqueous systems eliminating volatile organic compound emissions during inflatable boat fabric lamination in Shandong and Guangdong manufacturing clusters.
- Pre-cut Sheets:Dimensioned stock reduces fabrication waste for gasket and membrane manufacturers.
- Custom Shapes:Molded and die-cut components serve specialized sealing and cushioning applications.
Rolls maintain the volume base. Liquid formulations climb the fastest on environmental compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites East Asia's dominance in chlorosulfonated polyethylene trade flows, connecting Shandong Province fabricators to marine coating applicators across the Pacific Rim.
China
Shandong Province manufacturing clusters absorb production gravity as inland chlor-alkali facilities face MEE emissions-driven curtailments. The country's dual carbon goals redirect chlorosulfonated polyethylene synthesis toward coastal industrial parks with integrated waste gas treatment. Weifang-area fabricators negotiate term supply agreements that bypass regional distributors entirely.
United States
Gulf Coast petrochemical corridors sustain chlorinated elastomer formulation capacity serving aerospace gasket manufacturers. EPA oversight under TSCA and Clean Air Act provisions shapes manufacturing site permitting timelines. Houston-area processors navigate chlorine feedstock logistics from integrated chlor-alkali complexes along the Texas-Louisiana border.
Germany
REACH persistent organic pollutant restrictions and EU F-Gas Regulation constrain formulation chemistries available to European Hypalon processors. The country's automotive seal manufacturers drive specification requirements for ozone-resistant elastomers. Industrial fabricators in the Rhine-Ruhr region invest in reformulation capabilities to maintain marine coating product lines.
Japan
METI green procurement incentives create certified supplier channels for compliant chlorosulfonated polyethylene coating manufacturers. Electrical insulation applications exploit thermal stability specifications for wire jacketing and cable sheathing. Chubu region chemical producers align output with public tender preferences for low-emission rubber products.
India
Gujarat and Tamil Nadu shipbuilding clusters present underpenetrated demand for inflatable craft fabrics as domestic naval procurement scales. The country's coastal manufacturing expansion attracts specialty chemical distributors rewriting procurement patterns for chlorosulfonated polyethylene intermediates. Mumbai-Pune industrial corridors develop formulation capabilities to serve emerging marine fabricator requirements.
Hypalon Market Competitive Landscape
On the supply side, the industry is tiered between captive chlorination reagent producers, legacy elastomer formulators, and regional coating specialists. Specialty chemical manufacturers with dedicated intermediate streams command allocation priority from volume fabricators. Three archetypes dominate: integrated petrochemical conglomerates, coastal logistics-anchored fabricators, and application-focused formulation houses. Competitive moves center on backward integration into chlorine feedstock security and water-based dispersion technology licensing.
Within the integrated petrochemical tier, DuPont and Tosoh Corporation exemplify formulation expertise and captive reagent supply respectively. Weifang Polygrand Chemical occupies a position among coastal logistics-anchored specialists leveraging Shandong Province infrastructure. These three represent distinct competitive vectors: technology leadership through historical patent portfolios, supply chain control via specialty chlorination reagents, and geographic proximity to marine fabricator demand clusters.
| Leading Market Players |
|---|
| Weifang Polygrand Chemical |
| DuPont |
| Tosoh Corporation |
| Orion Engineered Carbons |
| Saint-Gobain Performance Plastics |
| Jiangxi Hongrun Chemical Industry |
| Shandong Shanxu New Material |
| Pennel & Flipo |
| Jilin Petrochemical |
| Others |
Value Network & Pricing Analysis
Chlor-alkali concentration in China's Shandong and Jiangsu provinces funnels pricing power toward coastal chlorosulfonated polyethylene producers with captive chlorine access, while inland fabricators absorb feedstock cost volatility through compressed margins on standard-grade formulations.
Pricing Analysis
Volume-discount tiering separates marine fabricators negotiating term supply agreements from spot-market purchasers of commodity coating grades. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and captive chlorination reagent access. Pricing pressure stems from MEE emissions caps tightening chlorine feedstock availability for non-integrated processors. Small-scale coating applicators in Guangdong manufacturing clusters exhibit highest price sensitivity; aerospace gasket manufacturers with outgassing specifications demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Shandong Province chlorosulfonated polyethylene producers to marine fabricators are displacing traditional distributor financing arrangements. Supply concentrates in China, Japan, and Germany, with production gravity anchored in coastal Chinese industrial parks. The chain draws from chlorine, sulfur dioxide, and polyethylene resin inputs. Single-source vulnerability runs through Tosoh Corporation's specialty chlorination reagent captive supply. Distribution runs through direct mill relationships consolidating procurement volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chlorosulfonation process engineering expertise is retiring from legacy production facilities faster than knowledge transfer systems can replicate it, compressing the available talent pool for controlled polyethylene chlorination operations.
For Market Incumbents: Entrench position through backward integration into chlorine feedstock security and water-based dispersion technology licensing. Lock in term supply agreements with Shandong Province marine fabricators before captive reagent producers extend direct sales channels. Invest in chlor-alkali capacity within MEE-compliant coastal industrial parks to defend against feedstock volatility. For New Entrants and Emerging Players: Pursue photovoltaic module edge-seal applications as the most penetrable segment, where 25-year weathering resistance specifications intersect with limited incumbent formulation presence. Target Gujarat and Tamil Nadu shipbuilding clusters in India for inflatable craft fabric demand. Establish technical service partnerships with regional coating applicators lacking in-house dispersion expertise. For Investors and Strategic Acquirers: Capital is best deployed toward coastal logistics-anchored fabricators with established MEE-compliant production assets and direct mill relationships with marine OEMs. Long-term viability across the analysis window favors processors with integrated waste gas treatment and captive chlorination reagent streams. Watch for inflection in Japan METI green procurement certification timelines as signal of premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorine Feedstock | Secures supply stability under MEE emissions caps for Shandong producers. |
| Water-Based Dispersion Technology Licensing | Eliminates VOC compliance costs for marine fabricators facing REACH restrictions. |
| Long-term Supply Agreement with Marine OEMs | Locks in allocation priority from captive chlorination reagent producers. |
| Green Manufacturing Certification Program | Qualifies suppliers for Japan METI public tender preferences. |
| Joint Venture in India Coastal Manufacturing | Captures naval procurement scaling in Gujarat and Tamil Nadu clusters. |
Research Methodology
Desk research of customs trade data, chemical industry association reports, and SEC filings preceded structured interviews with plant managers at chlorosulfonated polyethylene facilities, procurement leads at marine fabricators, distribution channel partners, and technical R&D directors specializing in elastomer formulations. Primary intelligence combined with secondary validation through ACC and Cefic industry reports, permitting disclosures to China's MEE, and EPA TSCA filing records. Bottom-up capacity assessments and top-down demand modeling underwent triangulation.
Assumptions held fixed include MEE emissions cap enforcement intensity, REACH substance evaluation timelines, and marine fabric chemical exposure standard adoption rates across the projection horizon. The framework modeled segmentation by product type, end-use industry, application function, and geographic production hub. CAGRs derived from installed capacity expansion schedules cross-referenced against downstream demand elasticity estimates. Forecast inputs incorporated chlor-alkali utilization rates and photovoltaic module installation trajectories.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, shipping freight rates, or chlor-alkali capacity utilization would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Lentein Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Toner Resins Market