
 Conductive Polymers Market | 2026-2036
Conductive Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Polymers Market Intelligence
Organic semiconductor integration is tilting printed circuit manufacturing toward solution-processable conductors. DuPont de Nemours Inc. leverages its fluoropolymer backbone to anchor high-temperature electrode coatings for EV power modules. SABIC sustains petrochemical feedstock advantages that control raw material costs for polyaniline derivatives. Heraeus Holding GmbH dominates precious-metal-polymer hybrid formulations for medical sensor applications.
Conductive polymers are macromolecular materials with conjugated pi-electron backbones that achieve electrical conductivity through doping with oxidizing or reducing agents, typically reaching sheet resistances from 10 to 1000 ohm per square. They serve primarily as lightweight, corrosion-resistant alternatives to metals in electromagnetic shielding, antistatic packaging, and electrochemical energy storage. Polyaniline leads product type volumes due to its environmental stability and low synthesis cost, while polypyrrole captures premium margins in biomedical sensor electrodes where biocompatibility requirements are stringent. The batteries application segment is outpacing coatings growth, driven by solid-state electrolyte development programs across automotive end users.
The EPA regulates volatile organic compound emissions from polymer synthesis facilities, pushing manufacturers toward aqueous dispersion processes. RoHS and REACH restrict heavy-metal dopants in electronics-grade conductive polymers, redirecting R&D toward organic acid doping systems. China's MIIT enforces GB standards for conductive materials used in new energy vehicle components, creating compliance barriers for imported formulations. Stakeholders must monitor divergence between EU and Asian purity standards when configuring regional supply chains.
Market Dynamics
Automotive electrification is compressing development cycles for polyaniline-based battery electrodes, forcing polymer suppliers to align R&D roadmaps with OEM solid-state electrolyte timelines. This demand pull is restructuring supply relationships around captive synthesis capacity and regional purity certification.
Growth Catalysts
- EV Battery Scale-Up:Solid-state electrolyte programs across automotive OEMs are pulling polyaniline volumes for electrode coatings. China's MIIT enforces GB standards that favor domestic polymer sourcing.
- REACH and RoHS Alignment:European heavy-metal restrictions redirect R&D toward organic acid doping systems. Electronics-grade formulations gain qualification pathways.
- Printed Electronics Expansion:Solution-processable conductors enable roll-to-roll manufacturing of flexible circuits. Organic semiconductor integration accelerates.
Market Restraints
- Aniline Feedstock Volatility:Petrochemical price swings compress margins for polyaniline derivatives. SABIC's captive feedstock advantages create asymmetric cost structures.
- Precious-Metal Hybrid Concentration:Medical sensor applications depend on silver-polymer formulations dominated by German and Japanese suppliers. Single-source risk persists.
- Aqueous Process Transition Costs:EPA volatile organic compound rules force capital retooling for dispersion synthesis. Smaller producers face compliance exit pressure.
Strategic Opportunities
- Biomedical Sensor Premiumization:Polypyrrole captures margin in biocompatibility-critical electrodes. Heraeus formulations set purity benchmarks for implantable devices.
- India Electronics Manufacturing:PLI scheme incentives attract conductive polymer packaging for domestic PCB production. CDSCO medical device rules create certification demand.
- EMI Shielding Lightweighting:Aerospace and defense OEMs substitute metal enclosures with conductive polymer composites. FAA certification pathways are opening.
Industry Challenges
- Dopant Chemist Talent Scarcity:Organic acid doping expertise concentrates in academic and national lab pipelines. Industrial scale-up experience gaps slow formulation transfer.
- Regional Purity Standard Divergence:EU REACH, China GB, and US EPA thresholds create multi-certification burdens. Formulation reconfiguration costs fragment production economics.
- Legacy Coating Integration:Automotive paint lines require conductive polymer compatibility with existing spray equipment. Retrofit timelines extend qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Polymers Market |
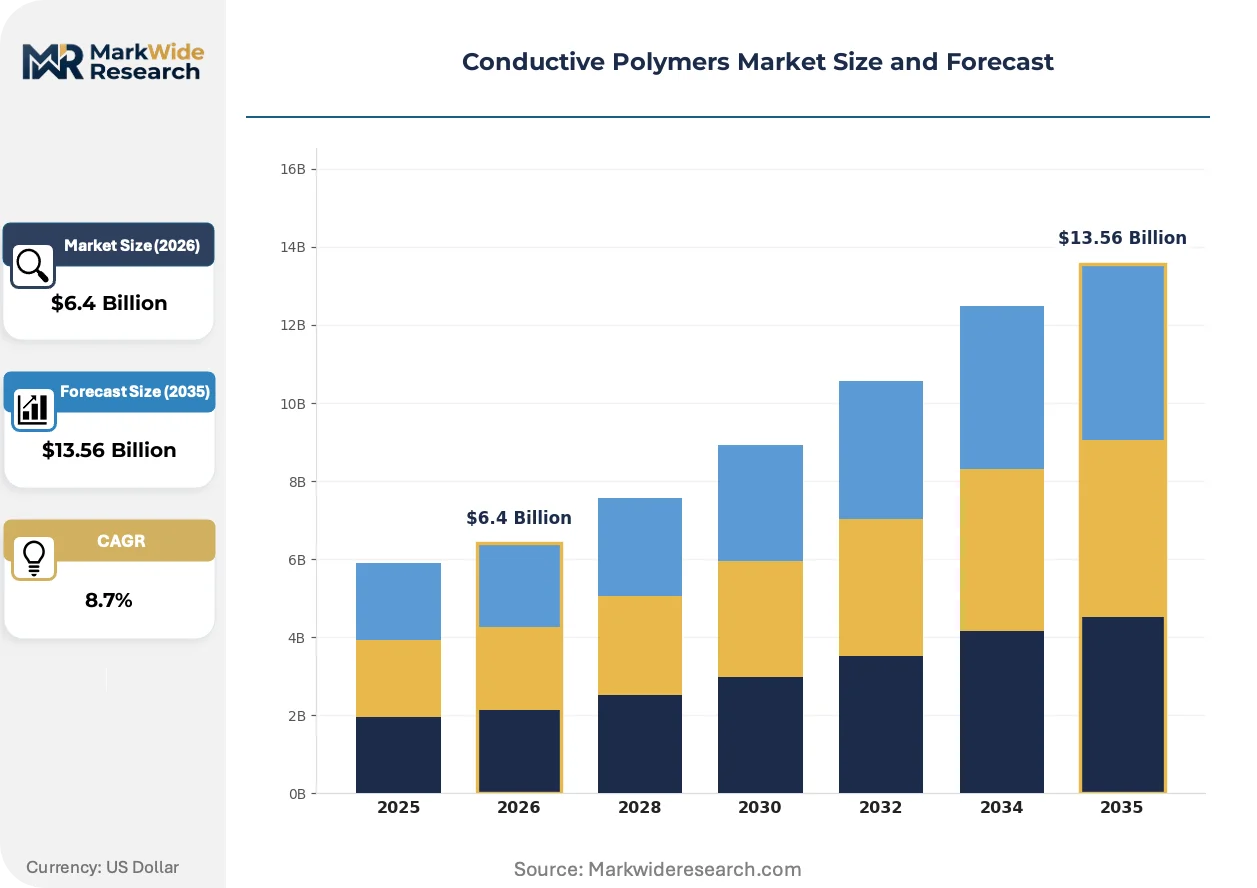
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyaniline, Polyacetylene, Polypyrrole, Conductive Carbon Black Application: Electronics, Sensors, Coatings, Batteries Grade: High Conductivity, Medium Conductivity, Low Conductivity, Specialty End User: Automotive, Aerospace, Healthcare, Consumer Electronics |
| Companies Covered | 3M Company, DuPont de Nemours Inc., SABIC, Covestro AG, Heraeus Holding GmbH, Agfa-Gevaert N.V., Celanese Corporation, Solvay S.A., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Polymers Market Strategic Shifts & Innovations
Organic semiconductor integration is redrawing competitive boundaries between traditional polymer suppliers and electronics materials specialists. Three convergent developments are compressing product lifecycles and rewiring procurement relationships.
Self-doped conductive polymers with covalently bound sulfonic acid groups eliminate external dopant leaching in humid environments. Medical device manufacturers in Germany and Switzerland are qualifying these materials for long-term implantable sensors. This stability breakthrough is rendering obsolete conventional externally-doped formulations in chronic monitoring applications.
China's MIIT has tightened GB/T standards for conductive materials in new energy vehicle battery modules, mandating traceability from monomer to finished electrode. Domestic EV manufacturers are accelerating in-house polymer synthesis to secure compliance certificates. Imported formulations face extended audit timelines, favoring local supply chain buildout.
Buyers are consolidating polymer procurement through direct long-term agreements with synthesis specialists, bypassing traditional chemical distributors. Automotive tier-1 suppliers in Japan and South Korea are locking five-year polyaniline supply contracts with volume guarantees. This channel compression is visible most acutely where battery cell production clusters in Gwangju and Nagoya.
Conductive Polymers Market Segmentation
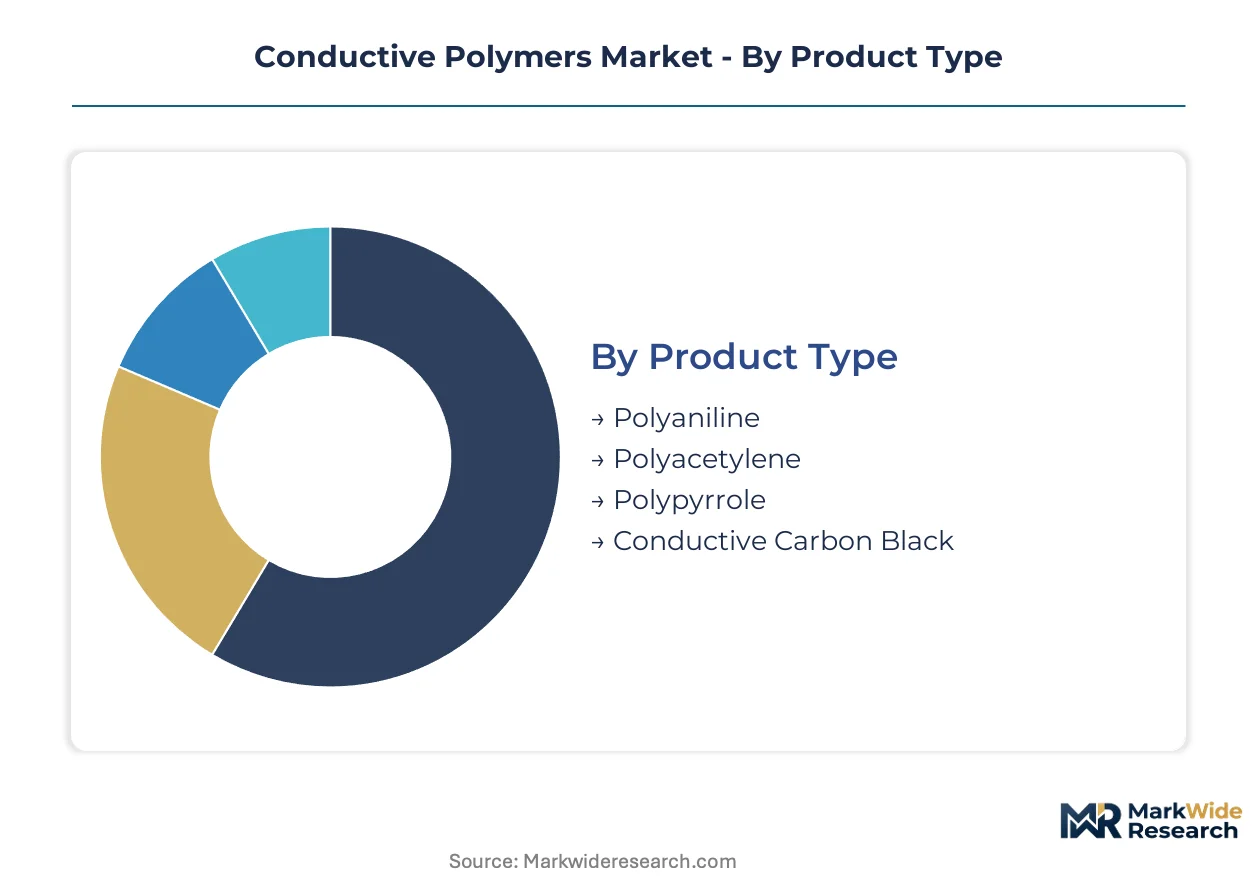
Segmentation in conductive polymers reveals how material properties, application requirements, and regulatory thresholds create distinct procurement patterns across the value chain. Product chemistry and conductivity grade determine qualification timelines, while end-user verticals impose divergent purity and certification burdens.
Product Type:
Polyaniline cycles through procurement fastest due to standardized synthesis routes, while polypyrrole and specialty grades face extended qualification periods for medical and aerospace applications.
- Polyaniline:Conjugated backbone polymer synthesized through oxidative polymerization of aniline, offering environmental stability and tunable conductivity via protonic acid doping. EV battery electrode coatings in China concentrate demand as MIIT GB standards tighten traceability requirements from monomer to finished component.
- Polypyrrole:Heterocyclic conducting polymer formed through electrochemical or chemical oxidation of pyrrole, distinguished by superior biocompatibility and aqueous processability. German and Swiss medical device manufacturers qualify this material for long-term implantable sensors where leaching resistance is paramount.
- Polyacetylene:Linear conjugated polymer with the simplest pi-electron backbone, historically significant but limited by oxidative degradation in ambient conditions.
- Conductive Carbon Black:Particulate carbon filler providing percolation-based conductivity in polymer composites, dominating antistatic packaging applications.
Polyaniline anchors the volume base while polypyrrole gains share at the steepest rate.
Application:
Cost tiers separate commodity coatings from premium sensor and battery formulations, with qualification expenses scaling nonlinearly across the four application clusters.
- Electronics:EMI shielding films, antistatic packaging, and printed circuit substrates requiring sheet resistances between 10 and 1000 ohm per square. RoHS and REACH heavy-metal restrictions redirect R&D toward organic acid doping systems for electronics-grade formulations.
- Batteries:Solid-state electrolyte development programs across automotive OEMs pull polyaniline volumes for electrode coatings and separator interfaces.
- Sensors:Biomedical and industrial transduction layers where polypyrrole captures premium margins in biocompatibility-critical electrodes.
- Coatings:Corrosion-resistant conductive layers for marine and infrastructure applications with established supply chains and compressed margins.
Batteries command the highest unit values while electronics delivers the largest absolute tonnage.
Grade:
Volume concentrates in medium-conductivity tiers where specification overlap allows supplier switching, while specialty grades lock in single-source relationships through proprietary doping chemistries.
- High Conductivity:Sheet resistance below 100 ohm per square achieved through heavy doping levels, essential for power distribution and high-frequency EMI applications. Automotive power module manufacturers in Japan and South Korea specify these grades for thermal management under elevated current densities.
- Medium Conductivity:Sheet resistance between 100 and 500 ohm per square balancing conductivity with mechanical flexibility, serving antistatic packaging and general electronics.
- Low Conductivity:Sheet resistance above 500 ohm per square for dissipation-grade applications where cost minimization dominates specification.
- Specialty:Custom-formulated grades with tailored dopants, molecular weights, or dispersion characteristics for medical device and aerospace certification pathways.
Medium conductivity anchors the volume base while specialty grades expand most quickly.
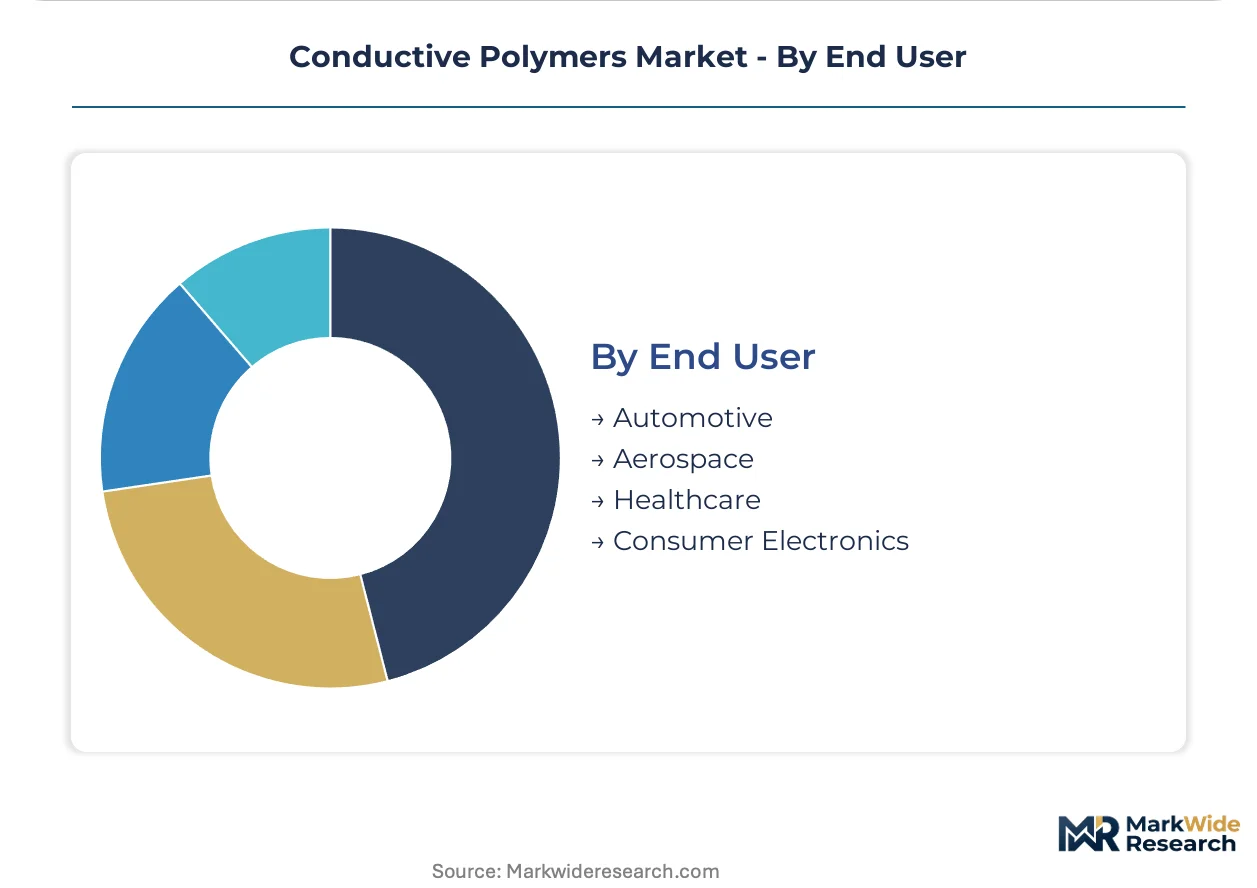
End User:
Customer type determines procurement structure, with automotive and aerospace imposing captive synthesis requirements while healthcare and consumer electronics tolerate distributor channels.
- Automotive:Battery cell and power electronics manufacturers driving polyaniline demand through direct long-term supply agreements with synthesis specialists. China's domestic EV manufacturers are scaling in-house polymer sourcing to secure MIIT compliance certificates.
- Aerospace:EMI shielding lightweighting initiatives substituting metal enclosures with conductive polymer composites, with FAA certification pathways opening for qualified formulations.
- Healthcare:Medical device OEMs requiring biocompatibility documentation and implantable-grade purity benchmarks, concentrating procurement with precious-metal-polymer hybrid specialists.
- Consumer Electronics:Flexible circuit and display manufacturers sourcing through consolidated procurement agreements with electronics materials distributors.
Automotive anchors the volume base while healthcare climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-purity conductive polymers is narrowing as battery cell manufacturers build captive synthesis capacity. Export flows of polyaniline derivatives from Germany and Japan are facing qualification delays in China due to traceability mandates. Regional supply chains are hardening around domestic certification pathways.
China
Domestic EV manufacturers are scaling in-house polyaniline production to satisfy MIIT GB standards for battery traceability. The ministry's tightened certification timelines favor local suppliers over imported formulations. Gwangju and Nagoya-based automotive tier-1s are locking five-year supply contracts with Chinese synthesis specialists to secure volume guarantees.
Germany
REACH compliance requirements are redirecting R&D budgets toward organic acid doping systems that eliminate heavy-metal additives. German medical device manufacturers in the Rhine-Ruhr region are qualifying self-doped conductive polymers for long-term implantable sensors. Heraeus formulations set purity benchmarks that Swiss and Austrian OEMs reference for cross-border procurement.
United States
EPA volatile organic compound rules are forcing aqueous dispersion process conversions at synthesis facilities in Texas and Louisiana. Aerospace OEMs in the Pacific Northwest are pursuing FAA certification for conductive polymer composites that replace metal EMI shielding. Defense procurement channels are opening qualification pathways for domestic specialty grade suppliers.
Japan
METI industrial policy is accelerating printed electronics programs that pull solution-processable conductors from Osaka and Nagoya manufacturing clusters. Automotive power module manufacturers specify high-conductivity grades for thermal management under elevated current densities. Japanese battery cell producers are backward integrating into polymer synthesis to reduce Korean and Chinese supply exposure.
South Korea
MFDS medical device regulations are creating certification demand for biocompatible polypyrrole formulations in the Seoul Capital Area. Electronics manufacturers in Busan-Ulsan are consolidating procurement through direct agreements with synthesis specialists, bypassing traditional chemical distributors. Domestic EV battery scale-up is compressing polyaniline qualification cycles to match OEM solid-state electrolyte timelines.
Conductive Polymers Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: diversified chemical conglomerates with captive feedstock advantages, specialty materials specialists with proprietary doping chemistries, and regional synthesis players serving MIIT-compliant domestic supply chains. Competitive moves center on backward integration into aniline production and five-year volume-lock contracts with automotive tier-1 suppliers.
Within the diversified chemical tier, BASF SE and SABIC exemplify feedstock-integrated positioning that controls raw material cost volatility for polyaniline derivatives. DuPont de Nemours Inc. occupies a position in high-temperature electrode coatings through fluoropolymer backbone expertise. Heraeus Holding GmbH anchors the precious-metal-polymer hybrid segment where medical sensor applications demand implantable-grade purity benchmarks.
| Leading Market Players |
|---|
| 3M Company |
| DuPont de Nemours Inc. |
| SABIC |
| Covestro AG |
| Heraeus Holding GmbH |
| Agfa-Gevaert N.V. |
| Celanese Corporation |
| Solvay S.A. |
| BASF SE |
| Others |
Cost & Logistics Intelligence
China's aniline monomer concentration anchors cost structures for polyaniline derivatives, concentrating margin pools with domestic EV manufacturers who have secured MIIT-compliant captive synthesis capacity. Imported formulations face extended audit timelines that compress their pricing power against local suppliers who control traceability documentation from monomer to finished electrode.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock volume guarantees across five-year horizons. Three-tier pricing structure across premium, standard, and economy levels separates implantable-grade polypyrrole with biocompatibility certification from general electronics grades. Cost compression in standard-grade polyaniline intensifies because petrochemical feedstock volatility transfers directly from SABIC's captive advantage to merchant market pricing. Consumer electronics manufacturers exhibit highest price sensitivity due to commoditized antistatic packaging specifications, while healthcare OEMs accept premium tiers for leaching-resistant self-doped formulations.
Supply Chain Analysis
Export-control restrictions on advanced doping chemistries limit technology flows from German and Japanese specialists to emerging synthesis players. Supply concentrates in China, Germany, and Japan, with raw material dependencies spanning aniline feedstocks from SABIC's petrochemical complexes, pyrrole monomers from BASF's Ludwigshafen operations, and precious-metal salts from Heraeus refining networks. Single-source vulnerability persists for medical-grade silver-polymer hybrids where Swiss and Austrian OEMs reference German purity benchmarks. Distribution runs through direct procurement agreements with automotive tier-1 suppliers, bypassing traditional chemical distributors in Gwangju and Nagoya clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as regional purity standard divergence between EU REACH, China GB, and US EPA thresholds forces formulation reconfiguration that rewards niche specialists over commodity suppliers.
For Market Incumbents: Insulate margin positions by deepening backward integration into aniline production and securing five-year volume-lock contracts with Japanese and South Korean automotive tier-1 suppliers. Invest in organic acid doping R&D to preempt REACH heavy-metal restrictions that threaten existing externally-doped product lines. Channel control through direct procurement agreements compresses distributor margins and locks out emerging competitors. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing presents underpenetrated demand for conductive polymer packaging in domestic PCB production, with CDSCO medical device rules creating parallel certification revenue streams. Target biomedical sensor applications where polypyrrole biocompatibility premiums offset scale disadvantages against polyaniline incumbents. Partner with Indian synthesis specialists to navigate BIS standards and establish local formulation credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional synthesis players in China who have secured MIIT compliance certificates but lack capital for aqueous process retooling mandated by EPA rules. Five-to-ten-year viability hinges on regulatory arbitrage between diverging purity standards rather than technology differentiation. Watch for consolidation signals when automotive OEMs accelerate solid-state electrolyte timelines and compress supplier qualification cycles beyond smaller players' capital capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Production | SABIC's captive feedstock model demonstrates margin control against petrochemical price volatility. |
| Aqueous Dispersion Process Conversion | EPA volatile organic compound rules force capital retooling that eliminates smaller synthesis competitors. |
| Long-term Supply Agreement with Automotive Tier-1s | Gwangju and Nagoya battery cell clusters lock volume guarantees through direct procurement channels. |
| Organic Acid Doping R&D Investment | REACH heavy-metal restrictions redirect qualification pathways toward leaching-resistant formulations. |
| Regional Certification Compliance Buildout | MIIT GB standards in China favor domestic traceability documentation over imported audit timelines. |
Research Approach
A spread of perspectives from polymer synthesis plant managers, automotive tier-1 procurement leads, medical device regulatory affairs directors, and electronics materials distribution channel partners converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MIIT certification databases. Bottom-up volume modeling across product chemistry, conductivity grade, and end-use vertical triangulated against top-down market sizing from regional production cluster analysis.
Demand-supply balance dynamics across the analysis window integrated capacity buildout timelines from Chinese domestic EV manufacturers, German medical device qualification cycles, and Japanese printed electronics program schedules. Segmentation dimensions modeled include product type chemistry, application cost tier, conductivity grade specification, and end-user procurement structure. CAGRs derived from annualized growth rate calculations applied to base-year volume estimates, with specific inputs from automotive solid-state electrolyte development roadmaps and biomedical sensor implantable-grade purity benchmarks.
Practitioners should monitor divergence between EU and Asian purity standards, EPA enforcement intensity on aqueous process conversions, and automotive OEM solid-state electrolyte timeline acceleration for early signals. Forecasts reflect assumptions on regulatory stability, feedstock cost transmission, and qualification cycle compression. Material shifts in REACH heavy-metal restriction scope or MIIT traceability mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Global UV Curable Resins Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
South America Polyamide Market