
 Thermoset Molding Compounds Market | 2026-2036
Thermoset Molding Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoset Molding Compounds Market Intelligence
The capital-intensity gap between integrated resin producers and compound specialists is collapsing as feedstock volatility compresses margin buffers for mid-scale operators. Toray Advanced Composites leverages captive carbon fiber supply chains to secure epoxy molding compound cost positions. BASF sustains global phenolic resin capacity through backward integration into formaldehyde and cresol feedstocks. Evonik Industries differentiates via high-performance polyimide-epoxy hybrids targeting aerospace thermal management applications.
Thermoset molding compounds are cross-linked polymer systems—epoxy, phenolic, polyester, and polyurethane-based—that irreversibly cure under heat and pressure, typically achieving glass transition temperatures exceeding 150°C and dielectric strengths above 15 kV/mm for electrical-grade formulations. These materials serve markets where dimensional stability under sustained thermal load, chemical resistance, and flame retardancy outweigh reprocessability requirements. Epoxy compounds dominate aerospace and electronics applications due to superior adhesion to fiber reinforcements and low moisture uptake, while phenolic formulations retain cost leadership in automotive under-hood components where short-term heat spikes exceed 200°C. Bulk molding compound formats are gaining share in high-volume automotive electrical connectors as manufacturers seek to reduce sheet scrap rates and accelerate cycle times.
REACH registration requirements in Europe, EPA TSCA Section 5 premanufacture notifications in the United States, and China's GB/T 2408 flame spread standards collectively shape formulation chemistry and market access timelines for new compound introductions. ECHA's restriction roadmap on formaldehyde emissions is forcing phenolic compound producers toward low-emitting resin architectures, while FAA fireworthiness standards for aircraft interiors sustain premium pricing for certified epoxy systems. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs for multi-market product lines escalate and regional formulation specialization becomes a structural requirement rather than a tactical option.
Market Dynamics
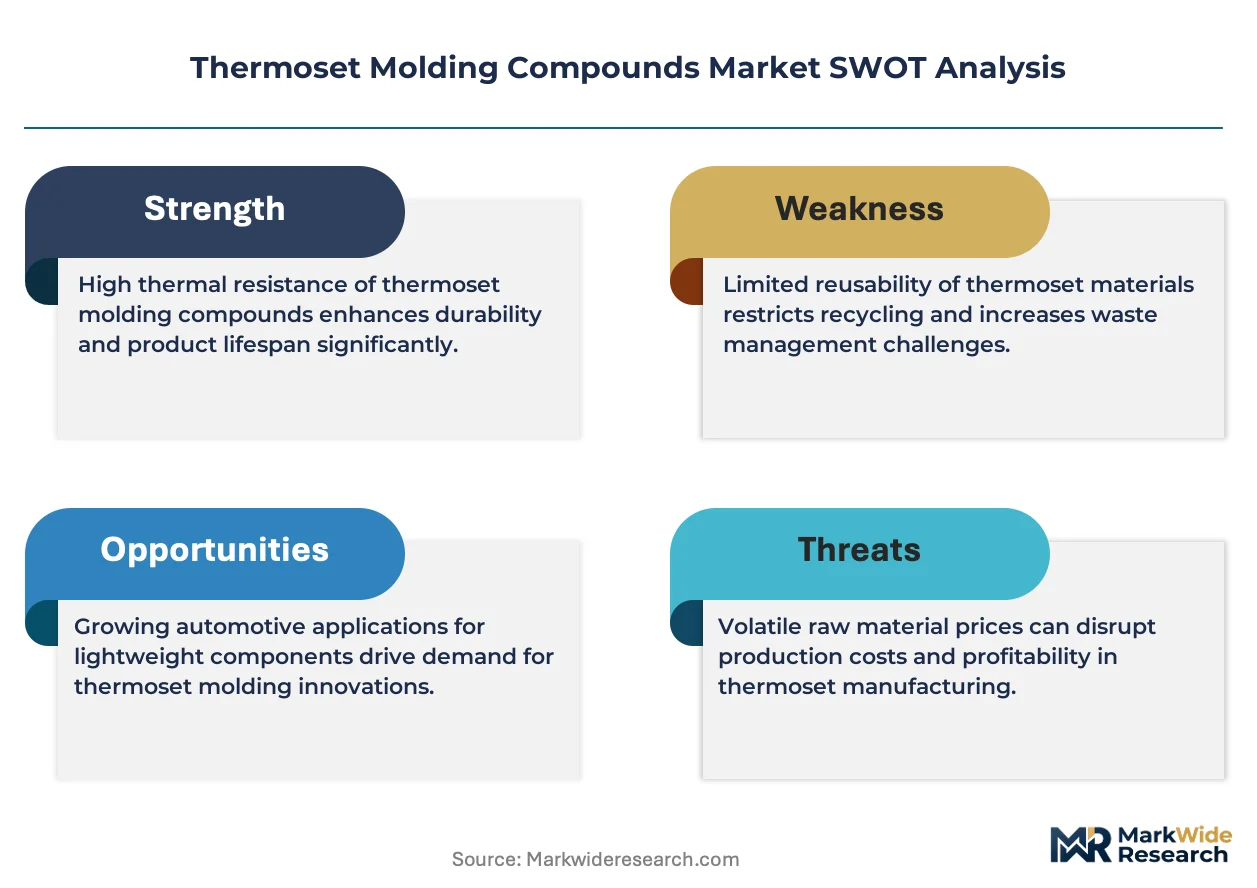
Feedstock volatility is compressing margin buffers for mid-scale compound operators, collapsing the capital-intensity gap between integrated resin producers and formulation specialists who must now secure captive supply chains or exit.
Growth Catalysts
- EV battery housing demand:China's eastern manufacturing corridor is absorbing bulk molding compound volumes for flame-retardant battery enclosures as domestic electric vehicle production scales.
- REACH formaldehyde restrictions:ECHA's emission roadmap is accelerating reformulation toward low-emitting phenolic architectures, creating first-mover advantage for compliant suppliers.
- Under-hood thermal specifications:Automotive OEMs in Germany and Japan are specifying thermoset grades that withstand sustained loads above 200°C where thermoplastics fail.
Market Restraints
- Formaldehyde feedstock volatility:Phenolic compound producers face margin erosion from methanol price swings that resist passing through to automotive contract customers.
- Carbon fiber supply concentration:Aerospace-grade epoxy molding compounds depend on Toray, Hexcel, and SGL Carbon fiber allocations concentrated in Japan, US, and Germany.
- Thermoplastic substitution in non-critical applications:High-heat polyphenylene sulfide and polyetherimide resins are capturing connector housings below 180°C operating thresholds.
Strategic Opportunities
- India electrical infrastructure buildout:Transmission grid expansion and railway electrification are creating import substitution opportunities for phenolic and epoxy insulator compounds.
- FAA fireworthiness certification premium:Aircraft interior epoxy systems command sustained pricing power as Boeing and Airbus OEMs consolidate qualified supplier bases.
- Polyimide-epoxy hybrid convergence:Aerospace thermal management applications are opening for formulations combining polyimide glass transition temperatures with epoxy processability.
Industry Challenges
- Formulation chemist scarcity:Expertise in reactive rheology control and cure kinetics optimization is concentrating at integrated producers, constraining specialist compounder R&D throughput.
- Multi-jurisdiction registration timelines:Simultaneous ECHA REACH dossier preparation, EPA TSCA Section 5 notifications, and China GB/T compliance extends new product introduction cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoset Molding Compounds Market |
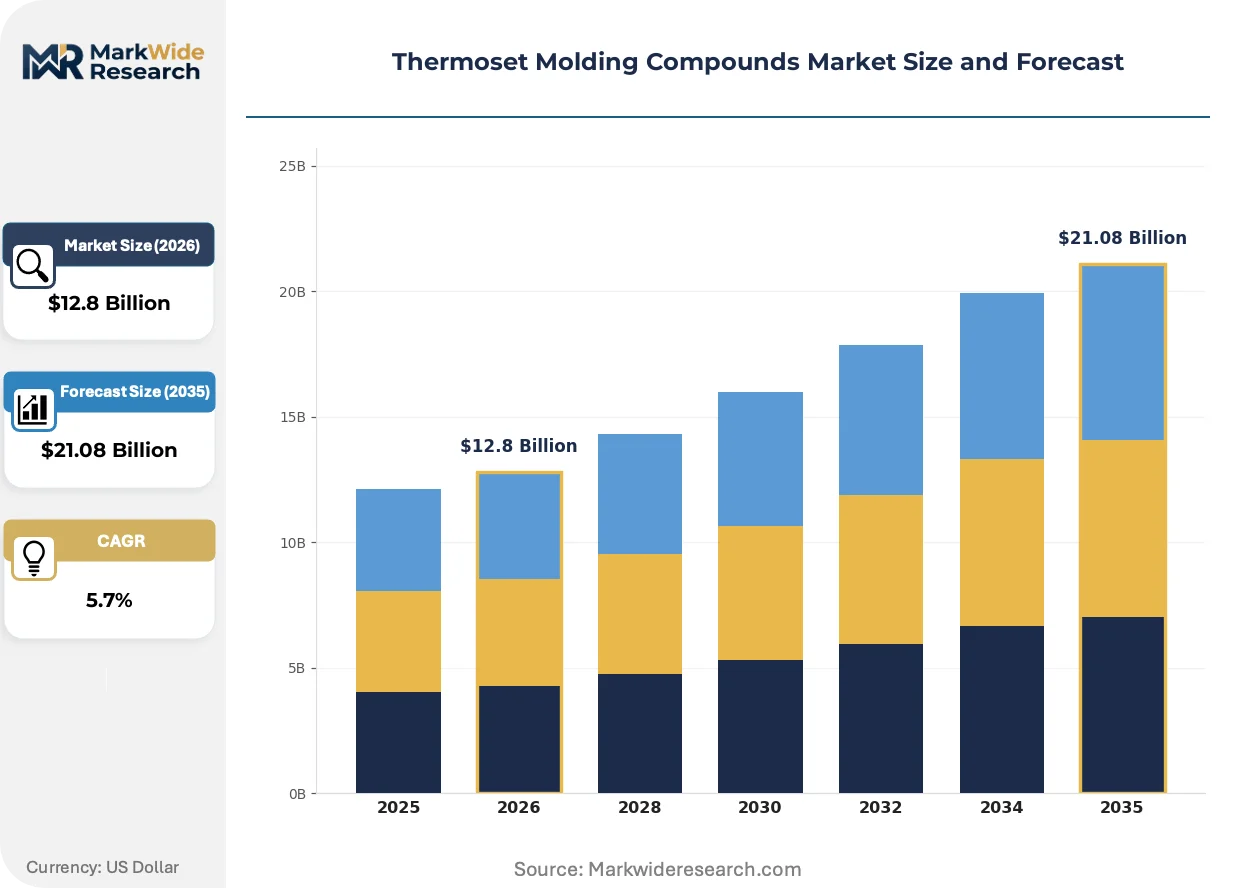
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Phenolic, Polyester, Polyurethane Application: Aerospace, Automotive Parts, Electrical Components, Consumer Goods End User: Manufacturers, OEMs, Aerospace Industry, Electronics Form: Sheet Molding Compound, Bulk Molding Compound, Liquid Molding Compound, Reinforced Molding Compound |
| Companies Covered | Toray Advanced Composites, Polynt, IDI Composites International, Evonik Industries, Eastman Chemical Company, BASF, Sumitomo Bakelite Co., Ltd., Huntsman Corporation, Hexion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoset Molding Compounds Market Strategic Shifts & Innovations
Reformulation cycles are accelerating as regulatory divergence between jurisdictions forces regional specialization, while material science convergence creates hybrid categories that resist traditional segmentation.
Bulk molding compound formats are fragmenting established sheet molding compound market positions in automotive electrical connectors. Tier-1 suppliers in Germany and Japan are converting press lines to BMC feeding systems that cut scrap rates from 35% to under 12% and compress cycle times by 40%. This transition is fragmenting historical supply relationships as compounders without BMC extrusion capability lose socketed connector programs.
EPA TSCA Section 5 premanufacture notification requirements are extending market access timelines for novel epoxy curing agents and flame-retardant synergists. The industrial consequence is a shift toward incremental modification of existing chemical substances rather than novel molecular architectures. Electronics-grade compound producers serving US aerospace and defense applications are responding by deepening inventories of pre-notified base chemistries to maintain formulation flexibility.
Automotive OEM technical buyers are consolidating qualified compound supplier lists from 8-12 vendors to 3-4 strategic partners per resin chemistry. Tier-2 molders in China's Yangtze River Delta are absorbing this consolidation pressure as SAIC, BYD, and NIO procurement teams centralize resin specification authority at headquarters level. This concentration is most visible in EV battery housing programs where single-source qualification timelines exceed 18 months.
Thermoset Molding Compounds Market Segmentation
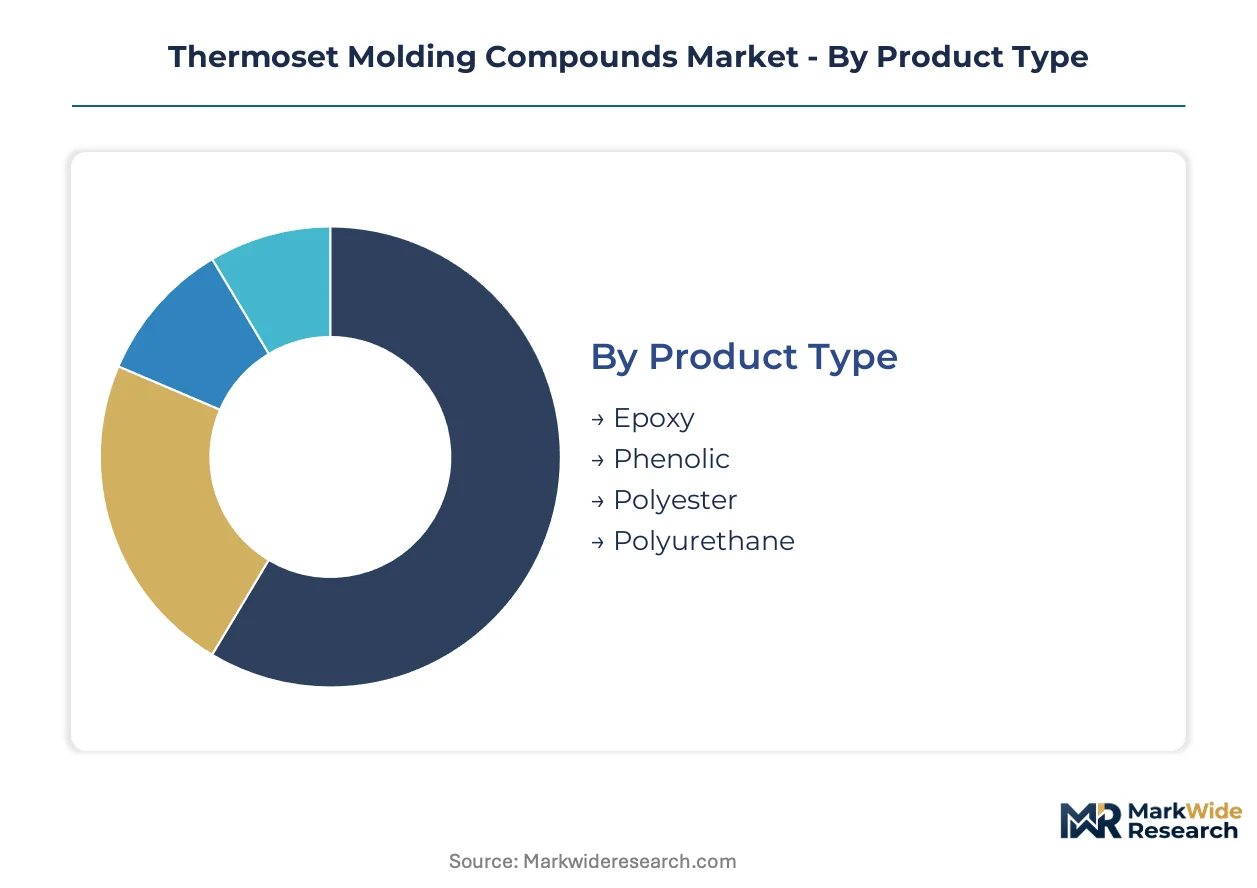
Thermoset molding compound procurement patterns diverge sharply across resin chemistries and form factors. Buyers in Germany and Japan source aerospace-grade epoxies through qualified supplier lists, while China's eastern corridor absorbs bulk phenolic volumes for domestic EV infrastructure.
Product Type:
Epoxy and phenolic formulations dominate export flows to regulated markets, while polyester and polyurethane serve cost-sensitive domestic applications.
- Epoxy:Superior adhesion to carbon fiber reinforcements and glass transition temperatures exceeding 180°C define aerospace and electronics-grade specifications. Demand concentrates in Japan's aircraft interior supply chain and Germany's automotive under-hood programs where FAA fireworthiness and OEM thermal specifications apply.
- Phenolic:Short-term heat resistance above 220°C and inherent flame retardancy position this chemistry for automotive engine bay components. China's SAIC, BYD, and NIO procurement teams specify phenolic bulk molding compounds for battery housings as domestic EV production scales.
- Polyester:Cost leadership in corrosion-resistant industrial applications serves construction and marine sectors with lower regulatory burdens.
- Polyurethane:Flexible formulations address consumer goods and insulation markets where reprocessability constraints are less critical.
Epoxy holds the largest share; momentum sits with phenolic as REACH formaldehyde restrictions accelerate reformulation toward low-emitting architectures.
Application:
Volume concentration follows regulatory intensity, with aerospace and automotive commanding premium pricing against electrical and consumer segments.
- Aerospace:FAA-certified epoxy systems for aircraft interiors sustain pricing power through consolidated qualified supplier bases at Boeing and Airbus. Toray Advanced Composites and Hexcel fiber allocations constrain compound availability for Tier-2 molders.
- Automotive Parts:Under-hood thermal specifications above 200°C displace thermoplastics in Germany and Japan OEM programs. Bulk molding compound adoption cuts scrap rates from 35% to under 12% in electrical connector production.
- Electrical Components:Transmission grid expansion in India and railway electrification create import substitution demand for phenolic and epoxy insulator compounds.
- Consumer Goods:Price-sensitive applications face thermoplastic substitution pressure where operating temperatures remain below 180°C.
Aerospace commands the highest margins; automotive parts are climbing the fastest as EV battery housing specifications proliferate.
End User:
Procurement authority centralization distinguishes OEM-direct relationships from distributor-served manufacturer networks.
- Manufacturers:Tier-2 molders in China's Yangtze River Delta absorb supplier consolidation pressure as resin specification authority migrates to headquarters procurement teams.
- OEMs:Automotive technical buyers in Germany and Japan have reduced qualified compound suppliers from 8-12 vendors to 3-4 strategic partners per resin chemistry.
- Aerospace Industry:Boeing and Airbus OEMs enforce 18-month single-source qualification timelines that protect incumbent compounders.
- Electronics:US defense applications require EPA TSCA Section 5 premanufacture notification compliance, extending market access timelines for novel curing agents.
OEMs control the largest procurement volumes; the aerospace industry maintains the steepest barriers to supplier entry.
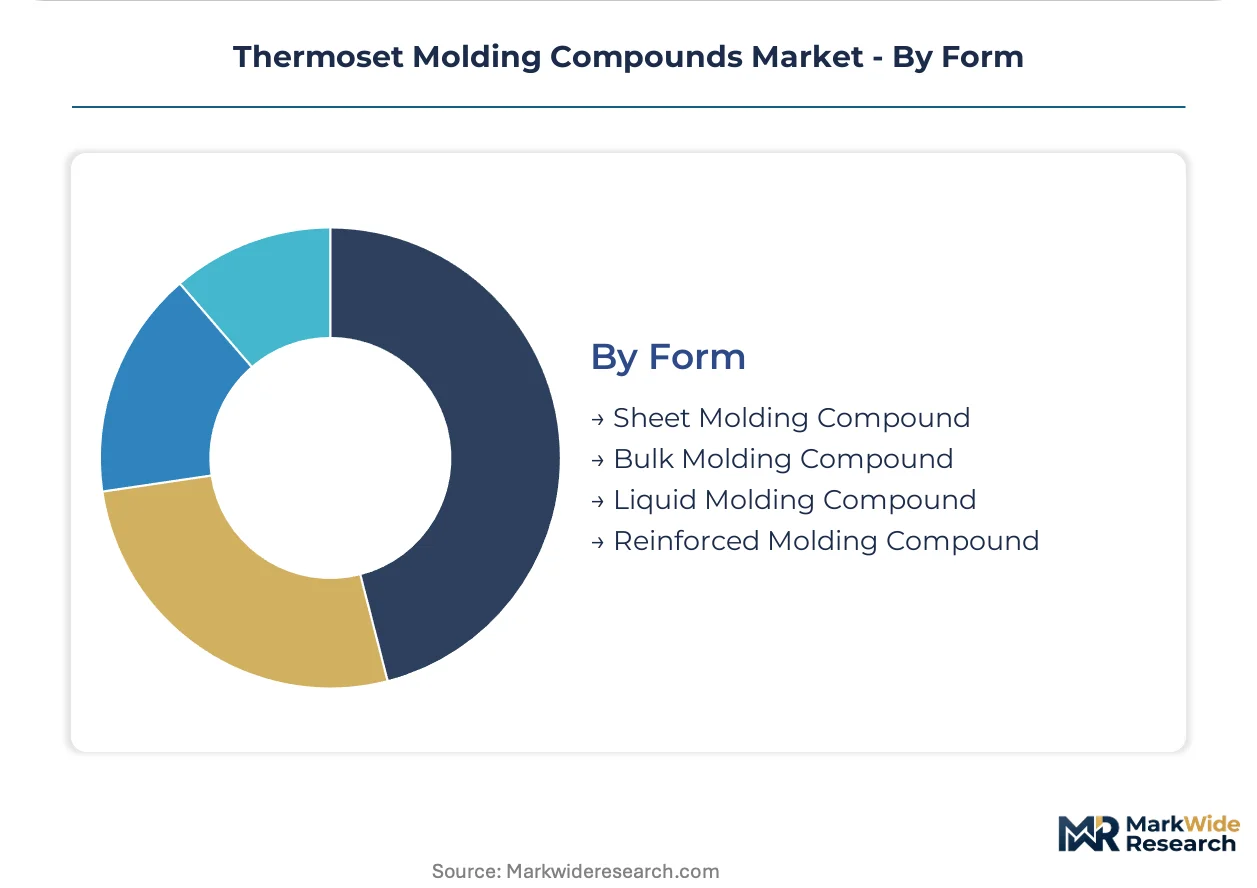
Form:
Processing economics and scrap reduction drive format migration across automotive electrical programs.
- Sheet Molding Compound:Historical standard for compression-molded automotive panels retains position in large-surface applications where fiber orientation control matters.
- Bulk Molding Compound:Extrusion-fed BMC systems compress cycle times by 40% and fragment established supply relationships as Tier-1 suppliers in Germany and Japan convert press lines.
- Liquid Molding Compound:Injection-compatible rheology serves complex geometries in electronics enclosures where thin-wall specifications apply.
- Reinforced Molding Compound:Continuous fiber formats address structural aerospace components requiring specific strength targets.
Sheet molding compound retains volume leadership; bulk molding compound is gaining share fastest through scrap reduction and cycle time compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers absorb bulk phenolic volumes with minimal price elasticity, while Japanese and German aerospace procurement teams pay substantial premiums for qualified epoxy systems. India's electrical infrastructure buildout sits at mid-elasticity, balancing cost sensitivity with specification compliance.
China
Domestic EV battery housing programs at SAIC, BYD, and NIO consume bulk molding compound volumes for flame-retardant enclosures. GB/T 2408 flame spread standards tighten material specifications and accelerate reformulation cycles. The Yangtze River Delta manufacturing corridor concentrates integrated molding facilities serving both automotive and electrical infrastructure demand.
Germany
Automotive OEM technical buyers specify thermoset grades for under-hood components requiring sustained thermal loads above 200°C. ECHA's REACH formaldehyde emission roadmap forces phenolic compound producers toward low-emitting resin architectures. Bavaria and Baden-Württemberg host Tier-1 suppliers converting press lines to BMC feeding systems.
Japan
Aerospace-grade epoxy systems for aircraft interiors command sustained pricing through consolidated qualified supplier bases at Boeing and Airbus Tier-1s. METI industrial standards shape domestic formulation chemistry. Toray Advanced Composites leverages captive carbon fiber supply chains from Nagoya and Tokyo production clusters.
United States
EPA TSCA Section 5 premanufacture notification requirements extend market access timelines for novel curing agents and flame-retardant synergists. FAA fireworthiness standards sustain premium pricing for certified epoxy systems serving defense and commercial aerospace. Electronics-grade compound producers deepen inventories of pre-notified base chemistries to maintain formulation flexibility.
India
Transmission grid expansion and railway electrification create import substitution opportunities for phenolic and epoxy insulator compounds. BIS standards and CEA technical specifications govern material qualification for electrical infrastructure. Maharashtra and Gujarat manufacturing clusters absorb compound volumes for domestic switchgear and transformer applications.
Thermoset Molding Compounds Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that faces margin compression from feedstock volatility. Integrated resin producers control formaldehyde, cresol, and epoxy feedstock supply chains, collapsing the capital-intensity advantage that mid-scale compounders once held. Three archetypes dominate: backward-integrated chemical conglomerates with captive raw material positions, carbon fiber-anchored composite specialists, and formulation-focused compounders serving qualified supplier lists. Competitive moves concentrate on securing captive supply chains and consolidating qualified supplier positions at automotive and aerospace OEMs.
Within the integrated chemical tier, BASF and Evonik Industries exemplify archetypes of backward-integrated resin producers sustaining global capacity through in-house production of formaldehyde and specialty monomer feedstocks. Toray Advanced Composites occupies a distinct position as a fiber-anchored specialist leveraging upstream control over carbon fiber supply chains to secure cost positions in aerospace-grade epoxy molding compounds. These three entities represent the structural divergence between feedstock-integrated conglomerates and reinforcement-captive composite specialists that defines competitive positioning in thermoset formulation supply.
| Leading Market Players |
|---|
| Toray Advanced Composites |
| Polynt |
| IDI Composites International |
| Evonik Industries |
| Eastman Chemical Company |
| BASF |
| Sumitomo Bakelite Co., Ltd. |
| Huntsman Corporation |
| Hexion Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between automotive OEMs and integrated resin producers lock in formaldehyde and epoxy feedstock allocations while anchoring price visibility across 18-month qualification windows. This contract structure insulates Tier-1 suppliers in Germany and Japan from methanol price volatility that erodes margins for spot-market compounders serving China's domestic EV programs.
Pricing Analysis
After-sales technical service contracts drive lifetime value for aerospace-grade epoxy systems, with FAA-certified formulations commanding sustained premiums through consolidated qualified supplier lists. Three-tier pricing structure across premium-certified, standard-industrial, and economy-domestic levels separates Boeing Tier-1 allocations from automotive under-hood specifications and China's battery housing commodity volumes. Cost compression in phenolic compounds is intensifying because methanol feedstock volatility resists pass-through to automotive contract customers. China's SAIC and BYD procurement teams exhibit highest price sensitivity, while Japan's aircraft interior supply chain maintains lowest elasticity due to single-source qualification barriers.
Supply Chain Analysis
China, Germany, and Japan anchor global thermoset molding compound production, with China's Yangtze River Delta hosting integrated molding facilities serving domestic EV infrastructure and Germany's Bavaria cluster supplying automotive under-hood specifications. Aerospace-grade epoxy formulations draw from Toray and Hexcel carbon fiber allocations concentrated in Japan and the US, while phenolic compounds rest on formaldehyde and cresol feedstocks controlled by backward-integrated chemical conglomerates. Single-source vulnerability runs through carbon fiber supply concentration for FAA-certified systems. Distribution feeds from integrated resin producers through qualified supplier lists to Tier-1 molders, bypassing traditional distributor networks in regulated end-uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where automotive OEM consolidation of qualified supplier lists from 8-12 vendors to 3-4 strategic partners per resin chemistry creates winner-take-most dynamics. Interoperability shifts in EV battery housing specifications are forcing compounders to integrate formulation, molding, and certification capabilities within single supply relationships.
For Market Incumbents: Shield qualified supplier positions at Boeing and Airbus Tier-1s by deepening inventories of pre-notified EPA TSCA base chemistries that accelerate formulation flexibility for defense electronics applications. Prioritize backward integration into formaldehyde and specialty monomer feedstocks to compress the capital-intensity gap that mid-scale compounders exploited. The threat of thermoplastic substitution in connector housings below 180°C demands certification investment in high-heat polyimide-epoxy hybrids that resist displacement. For New Entrants and Emerging Players: Lead with India's electrical infrastructure buildout as the most penetrable geography, where transmission grid expansion and railway electrification create import substitution demand for phenolic and epoxy insulator compounds absent entrenched qualified supplier lists. Target Maharashtra and Gujarat manufacturing clusters with BIS-compliant formulations that bypass 18-month automotive OEM qualification timelines. A technical service bundling go-to-market angle differentiates against commodity traders serving cost-sensitive switchgear applications. For Investors and Strategic Acquirers: Formulation-focused compounders with captive BMC extrusion capability and active ECHA REACH dossiers represent the most defensible acquisition archetype as automotive press line conversions fragment historical supply relationships. Long-term viability hinges on securing positions in consolidated OEM supplier lists before qualification windows close. Watch for FAA fireworthiness certification renewals at Boeing and Airbus as the inflection signal indicating which compounders will sustain premium pricing through the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Formaldehyde Feedstocks | BASF sustains global phenolic resin capacity through in-house production of cresol and formaldehyde monomers. |
| Carbon Fiber Supply Chain Anchoring | Toray Advanced Composites leverages Nagoya production clusters to secure aerospace-grade epoxy compound cost positions. |
| BMC Extrusion Capability Expansion | Tier-1 suppliers in Baden-Württemberg convert press lines to cut scrap rates from 35% to under 12%. |
| REACH Low-Emitting Phenolic Reformulation | ECHA's formaldehyde emission roadmap accelerates compliant architectures for European automotive programs. |
| India Electrical Infrastructure Localization | Maharashtra manufacturing clusters absorb compound volumes for domestic switchgear and transformer applications under CEA specifications. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with plant managers at integrated resin producers, procurement leads at German and Japanese automotive OEMs, distribution channel partners serving China's Yangtze River Delta, and technical R&D directors specializing in reactive rheology control; and secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and ECHA REACH registration databases. Bottom-up volume triangulation across resin chemistry, form factor, and end-use application intersected with top-down macroeconomic drivers to anchor forecast integrity.
Across the analysis window, the quantitative framework modeled thermoset molding compound demand through segmentation dimensions spanning resin chemistry tier, end-use industry intensity, processing form factor, and regional production hub concentration. CAGRs were derived from elasticity-adjusted volume projections that incorporated EV battery housing specification proliferation, REACH formaldehyde restriction compliance timelines, and aerospace qualified supplier list consolidation dynamics as core forecast inputs.
Forecasts assume regulatory continuity in ECHA REACH, EPA TSCA, and China GB/T regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Compounds Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Polyoxin Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Solketal Market