
 France Lubricants Market | 2026-2036
France Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
France Lubricants Market Foresight
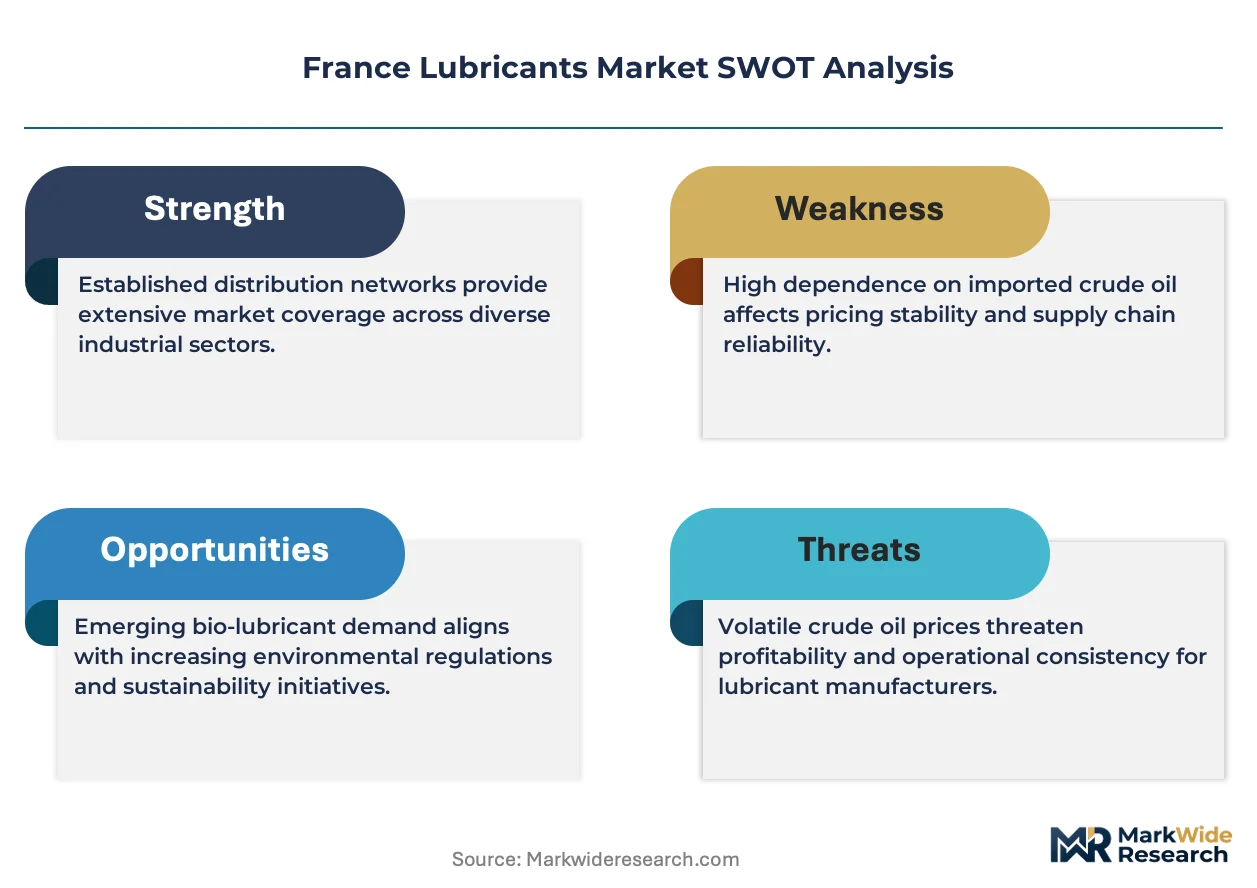
REACH compliance is recalibrating the cost-of-entry calculus for lubricant formulators serving the French market. TotalEnergies leverages its integrated refining and additive manufacturing footprint to absorb regulatory compliance costs more efficiently than importers. Shell anchors its position through sustained R&D spending on low-viscosity engine oils tailored to French OEM specifications. Motul specializes in high-performance synthetic formulations that command premium positioning among domestic automotive workshops.
Lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically ranging from ISO VG 32 to ISO VG 680 for industrial applications and SAE 0W-16 to 20W-50 for automotive engines. Their primary purpose is to extend equipment life and optimize energy efficiency across transportation and industrial systems. Engine Oil dominates product-level revenue due to the sheer installed base of passenger and commercial vehicles requiring periodic replacement. Industrial Machinery applications within the Application segment are drawing accelerated investment as French manufacturers automate production lines and extend maintenance intervals. The Distribution Channel dimension shows Wholesale Distributors controlling bulk volume flows to industrial plants, while Automotive Workshops capture higher per-unit margins through bundled service offerings.
France's national environmental regulator enforces REACH substance restrictions and biodegradability mandates that directly constrain formulation choices for metalworking fluids and marine lubricants. ECHA classification protocols for substance hazards shape labeling requirements and cross-border trade documentation for suppliers operating from German border zones into eastern France. ANSM oversight of workplace chemical exposure adds another compliance layer for industrial lubricant users in pharmaceutical manufacturing clusters near Strasbourg. Stakeholders must monitor how the EU Green Deal's evolving carbon border adjustments will restructure import economics for base oil feedstocks originating outside the European customs union.
Market Dynamics
REACH substance restrictions and biodegradability mandates are compressing formulation flexibility for metalworking fluids and marine lubricants across France's industrial corridor from Lyon to Grenoble. This regulatory pressure is forcing reformulation investments that favor integrated domestic producers over import-dependent competitors.
Growth Catalysts
- Automotive Engine Oil Demand:French OEMs are extending drain intervals while specifying lower viscosity grades, creating pull for advanced synthetic formulations that command premium positioning in authorized workshop networks.
- REACH Compliance:The ECHA classification protocol for substance hazards is accelerating consolidation among formulators capable of absorbing documentation and substitution costs.
- Industrial Automation:French manufacturers automating production lines near Strasbourg are demanding metalworking fluids with extended sump life and reduced microbial contamination risk.
Market Restraints
- Base Oil Feedstock Concentration:Import dependence on Group II/III base oils from non-EU sources exposes margins to carbon border adjustment mechanisms under the EU Green Deal.
- Biodegradability Technical Ceiling:Marine lubricants face performance trade-offs between rapid biodegradation and extreme-pressure protection in saltwater environments.
- ANSM Workplace Exposure:Pharmaceutical manufacturing clusters near Strasbourg face additional compliance layers that extend procurement cycles and limit supplier pools.
Strategic Opportunities
- Rhône-Alpes Industrial Corridor:Metalworking fluid demand concentrates around precision machining clusters where local blending capabilities reduce logistics costs and customs exposure.
- Re-refined Base Oils:Circular economy incentives under France's national waste reduction targets create feedstock cost advantages for domestic re-refiners with ECHA-approved recycling processes.
- Digital Fluid Monitoring:IoT-enabled condition monitoring is modularizing service contracts, allowing lubricant suppliers to capture recurring revenue through predictive maintenance integration.
Industry Challenges
- Formulation Chemist Scarcity:The specialized expertise required for REACH-compliant additive blending is concentrating among aging technical workforces in the Paris Basin and Lyon regions.
- Legacy Equipment Compatibility:Lower viscosity engine oils specified for new French vehicle platforms risk seal degradation in the national fleet's older passenger car installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Lubricants Market |
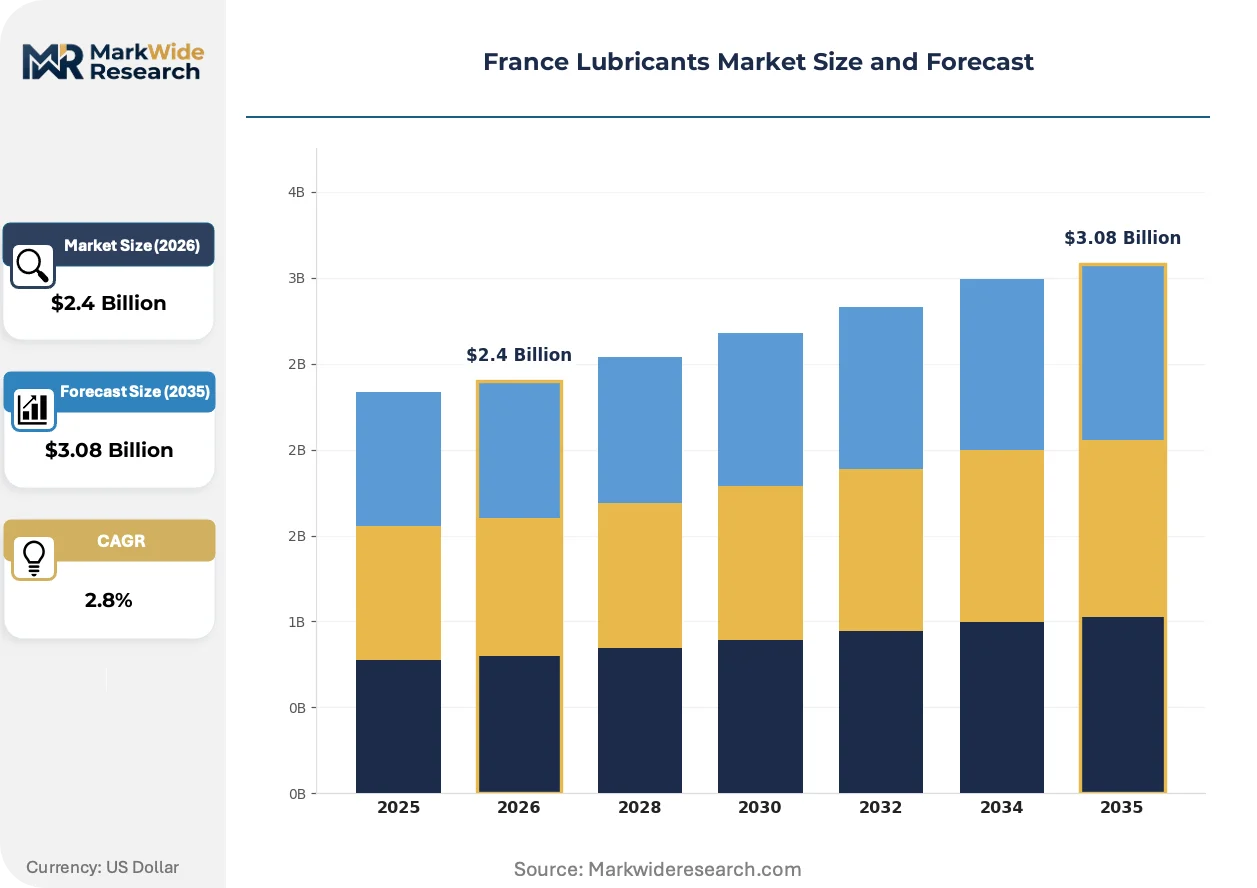
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.08 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluid, Metalworking Fluid, Grease, Compressor Oil Application: Automotive Engines, Industrial Machinery, Marine Equipment, Construction Equipment, Agricultural Machines, Power Generation End User: Vehicle Manufacturers, Industrial Plants, Shipping Companies, Construction Contractors, Farming Enterprises, Energy Producers Distribution Channel: Automotive Workshops, Retail Stores, Online Dealers, Wholesale Distributors, Industrial Suppliers, Specialty Shops |
| Companies Covered | TotalEnergies, Shell, BP, ExxonMobil, Motul, FUCHS, Chevron Corporation, Eni, LIQUI MOLY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Lubricants Market Shifts & Advancements
Synthetic lubricant architectures are displacing conventional mineral formulations across both automotive and industrial segments. Three interconnected developments are compressing traditional supply relationships while opening new service revenue streams.
Polyalkylene glycol synthetic base stocks are modularizing industrial lubricant system design. Food processing equipment manufacturers in Normandy are specifying these fluids for their thermal stability and clean-burn characteristics. This technology is modularizing the separation between lubrication and process fluid functions that previously required separate maintenance protocols.
France's national environmental regulator is tightening biodegradability mandates for metalworking fluids used in marine and freshwater applications. Metalworking shops in the Grenoble precision engineering cluster are reformulating emulsion systems to meet OECD 301B test protocols. The marine lubricant segment faces the steepest compliance gradient, with harbor authorities in Marseille and Le Havre already requiring documentation of aquatic toxicity profiles.
Fleet managers at French logistics operators are compressing procurement cycles through consolidated national agreements with direct manufacturer relationships. Automotive workshops in the Île-de-France region are bypassing traditional wholesale distributors for engine oil purchases, instead receiving scheduled deliveries from blender-operated logistics networks. This channel disintermediation is most visible in high-volume passenger vehicle service chains where inventory carrying costs outweigh price advantages from bulk distributor purchasing.
France Lubricants Market Segmentation
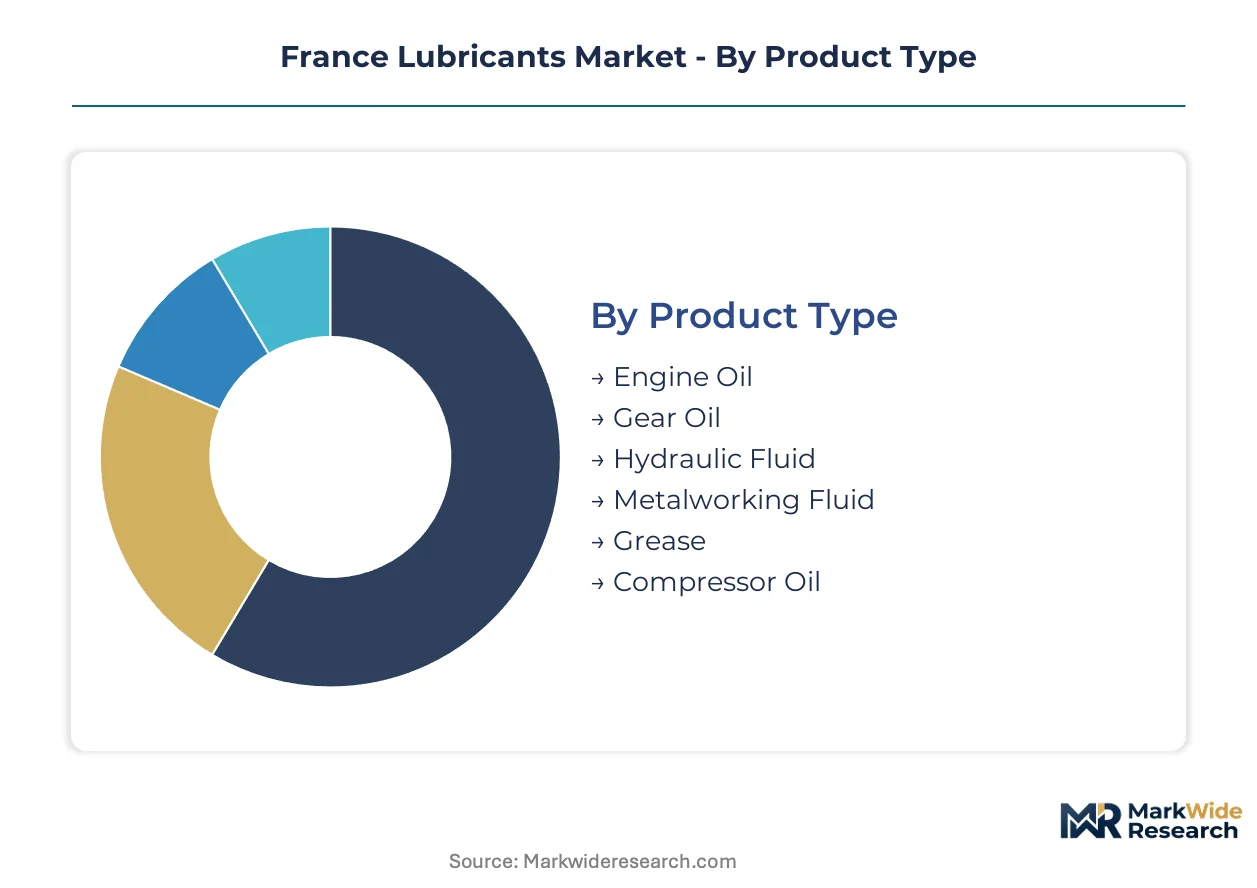
Segmentation in the France lubricants market reveals how regulatory pressure and supply chain geography reshape competitive positioning. Understanding these divides exposes where integrated domestic producers absorb compliance costs more efficiently than import-dependent rivals.
Product Type:
Supply concentration around synthetic formulations favors producers with captive additive manufacturing in the Lyon-Grenoble corridor.
- Engine Oil:Blends of Group III base stocks with friction-modifier packages dominate automotive service volumes. French OEM drain interval extensions pull demand toward low-viscosity synthetics in authorized workshop networks serving the Île-de-France vehicle cluster.
- Metalworking Fluid:Emulsifiable and neat oil formulations face the steepest REACH-driven reformulation costs. Precision machining clusters from Lyon to Grenoble specify extended-sump-life variants that reduce microbial contamination risk in automated production environments.
- Gear Oil:Extreme-pressure additive packages protect transmission systems in commercial vehicle fleets.
- Hydraulic Fluid:Anti-wear formulations serve construction and agricultural equipment across Normandy and Brittany.
- Grease:Thickener-based lubricants seal bearings in industrial machinery subject to ANSM workplace exposure protocols.
- Compressor Oil:Thermal stability requirements shape specification for food processing equipment manufacturers in Normandy.
Today's leader: Engine Oil. Tomorrow's challenger: Metalworking Fluid.
Application:
Application demand splits between mobility services with compressed procurement cycles and industrial users extending maintenance intervals through condition monitoring.
- Automotive Engines:Passenger and commercial vehicle powertrains require periodic replacement at volume scale. Fleet managers at French logistics operators consolidate national agreements that bypass traditional wholesale distributors for direct blender relationships.
- Industrial Machinery:Automated production lines near Strasbourg demand fluids with extended service life and reduced microbial degradation. Metalworking shops in this cluster absorb higher per-liter costs to minimize unplanned downtime in precision machining operations.
- Marine Equipment:Harbor authorities in Marseille and Le Havre mandate aquatic toxicity documentation for stern tube and deck machinery lubricants.
- Construction Equipment:Hydraulic systems in earthmoving fleets operate across variable temperature ranges in Auvergne-Rhône-Alpes infrastructure projects.
- Agricultural Machines:Seasonal demand peaks in cereal-producing regions of Grand Est and Hauts-de-France.
- Power Generation:Turbine and transformer oils serve nuclear and renewable asset operators in the Loire Valley.
Industrial Machinery is gaining share fastest as automation investments accelerate fluid specification upgrades.
End User:
End user procurement authority concentrates among national fleet operators and industrial plant engineering departments with direct manufacturer relationships.
- Vehicle Manufacturers:French OEM engineering teams specify factory-fill and service-fill grades that cascade through authorized dealer networks. Their viscosity grade requirements cascade down to captive workshop chains in the Paris Basin.
- Industrial Plants:Maintenance engineering departments in pharmaceutical manufacturing clusters near Strasbourg face ANSM compliance layers that extend procurement cycles. These buyers prioritize documented REACH compliance over unit cost minimization.
- Shipping Companies:Fleet technical managers in Marseille and Le Havre navigate harbor authority biodegradability mandates.
- Construction Contractors:Equipment rental fleets in Auvergne-Rhône-Alpes specify hydraulic fluids for mixed-use machinery.
- Farming Enterprises:Cooperative purchasing pools in Grand Est aggregate seasonal demand for tractor and combine lubricants.
- Energy Producers:Nuclear and hydroelectric operators in the Loire Valley require turbine oil monitoring protocols.
Vehicle Manufacturers currently anchor volume. Industrial Plants present the steepest margin expansion trajectory.
Distribution Channel:
Channel economics split between bulk volume flows to industrial plants and bundled service offerings capturing higher per-unit margins.
- Wholesale Distributors:Bulk storage and logistics infrastructure controls volume flows to industrial plants in the Lyon-Grenoble corridor. Their margin compression from channel disintermediation is partially offset by metalworking fluid blending services.
- Automotive Workshops:Authorized service chains in Île-de-France capture premium positioning through bundled oil change services. These outlets increasingly receive scheduled deliveries from blender-operated logistics networks rather than traditional distributor stocking.
- Retail Stores:DIY vehicle maintenance channels serve the aging national passenger car fleet in peripheral urban zones.
- Online Dealers:E-commerce platforms aggregate fragmented demand from independent repair shops.
- Industrial Suppliers:Technical distributors serve pharmaceutical and food processing clusters with compliance documentation.
- Specialty Shops:High-performance synthetic retailers target motorsport and classic vehicle collectors.
Wholesale Distributors dominate tonnage. Automotive Workshops command the margin expansion path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's lubricants industry traces its modern foundations to the post-war expansion of refining capacity along the Rhône corridor and the subsequent development of additive chemistry expertise in the Lyon basin during the 1960s.
Île-de-France
Automotive service chains and fleet management headquarters cluster around Paris, generating concentrated demand for low-viscosity engine oils. ANSM workplace exposure protocols extend procurement cycles for pharmaceutical manufacturing facilities in the outer suburbs. Workshop networks in this region increasingly receive direct deliveries from blender-operated logistics systems rather than traditional wholesale channels.
Auvergne-Rhône-Alpes
Precision machining and automotive component manufacturing anchor industrial lubricant consumption from Lyon through Grenoble. REACH substance restrictions force reformulation investments among metalworking fluid suppliers serving automated production lines. The corridor's captive additive blending capabilities reduce customs exposure for ECHA-compliant formulations.
Provence-Alpes-Côte d'Azur
Harbor authorities in Marseille mandate aquatic toxicity documentation for marine lubricants used in stern tube and deck machinery applications. Shipping companies navigating these biodegradability requirements face performance trade-offs between environmental compliance and extreme-pressure protection. Local blending operations supply port-adjacent fleet technical managers with documented OECD 301B test protocols.
Hauts-de-France
Agricultural machinery cooperative purchasing pools aggregate seasonal demand for tractor and combine lubricants across cereal-producing regions. The national waste reduction framework creates circular economy incentives for re-refined base oil feedstocks. Equipment rental fleets in this zone specify hydraulic fluids for mixed-use machinery subject to variable temperature ranges.
Grand Est
Pharmaceutical manufacturing clusters near Strasbourg absorb additional ANSM compliance layers that limit supplier pools and extend procurement cycles. Industrial buyers in this region prioritize documented REACH compliance over unit cost minimization. Food processing equipment manufacturers in adjacent zones specify polyalkylene glycol synthetic base stocks for thermal stability requirements.
France Lubricants Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with captive refining and additive manufacturing footprints. Domestic producers absorb REACH compliance costs more efficiently than import-dependent competitors through backward integration into base oil supply. Two strategic archetypes dominate: vertically integrated majors leveraging economies of scale across formulation and distribution, and specialized synthetic blenders commanding premium positioning through technical differentiation. Capacity consolidation and regulatory-driven portfolio restructuring represent the dominant competitive moves reshaping participant mix.
Within the integrated major tier, TotalEnergies anchors French market presence through its historical refining and additive manufacturing infrastructure. Shell and BP occupy positions alongside ExxonMobil as international energy companies with sustained R&D allocation toward low-viscosity engine oil specifications. Among specialized blenders, Motul exemplifies the premium synthetic formulator archetype serving high-performance automotive segments, while FUCHS represents the German-origin industrial lubricant specialist with metalworking fluid expertise. LIQUI MOLY sits within the additive-focused tier targeting workshop and retail channels with branded aftermarket positioning.
| Leading Market Players |
|---|
| TotalEnergies |
| Shell |
| BP |
| ExxonMobil |
| Motul |
| FUCHS |
| Chevron Corporation |
| Eni |
| LIQUI MOLY |
| Others |
Supply & Pricing Matrix
Group II/III base oil feedstock costs cascade through three distinct pricing tiers before reaching end-buyers in the Lyon-Grenoble industrial corridor. REACH compliance documentation expenses concentrate at the premium synthetic formulation level, while economy-grade mineral oils absorb margin compression from carbon border exposure on non-EU sourced feedstocks.
Pricing Analysis
Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels dominates the French market. Price differentiation rests on REACH certification grade and volume procurement scale, with pharmaceutical manufacturing clusters near Strasbourg absorbing premium positioning for documented compliance. Cost compression in the economy tier is intensifying because import-dependent blenders face EU Green Deal carbon border mechanisms on Group II/III base oils. Fleet operators consolidating national agreements demonstrate the least price sensitivity, while independent automotive workshops in peripheral urban zones exhibit the highest.
Supply Chain Analysis
Direct-to-OEM channels handle factory-fill specifications from French vehicle manufacturers, while blender-operated logistics networks increasingly bypass wholesale distributors for workshop deliveries. Geographic supply concentration centers on Belgium, Germany, and the Netherlands for Group III base oil refining, with additive packages sourced from German chemical clusters. Raw material dependencies include polyalphaolefin synthetic base stocks, friction-modifier additive packages, and re-refined base oil feedstocks. Single-source vulnerability persists for specialized REACH-compliant additive chemistries concentrated among aging technical workforces in the Paris Basin. Distribution runs through captive blending facilities in the Rhône-Alpes corridor to minimize customs exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France lubricants market represents a late-cycle quality story as automotive OEM drain interval extensions pull demand toward premium synthetic formulations commanding sustained margin premiums.
For Market Incumbents: Extend captive additive manufacturing capabilities in the Lyon-Grenoble corridor to absorb REACH reformulation costs that burden import-dependent competitors. Deepen backward integration into re-refined base oil feedstocks under France's national waste reduction framework, securing circular economy cost advantages against emerging entrants lacking ECHA-approved recycling processes. For New Entrants and Emerging Players: The price-point gap between Motul-premium synthetics and economy mineral formulations presents white-space opportunity for mid-tier semi-synthetic positioning. Target the Rhône-Alpes precision machining cluster with extended-sump-life metalworking fluids, leveraging local blending partnerships to reduce logistics costs and customs documentation burdens that constrain distant competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs exceed smaller formulators' capital absorption capacity, particularly among metalworking fluid specialists serving the Grenoble engineering cluster. Acquisition targets with captive ECHA-approved additive blending and documented OECD 301B biodegradability protocols offer the strongest long-term viability. The signal to watch is harbor authority mandate expansion from Marseille and Le Havre to additional French port complexes, accelerating marine lubricant specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-refined Base Oils | Captures circular economy incentives under France's national waste reduction targets while reducing feedstock cost volatility. |
| REACH-Compliant Additive Manufacturing Expansion | Absorbs regulatory documentation costs that compress margins for import-dependent competitors serving Lyon-Grenoble. |
| Digital Fluid Monitoring Platform Launch | Modularizes service contracts into recurring revenue streams through IoT-enabled predictive maintenance integration. |
| Direct Blender-to-Workshop Logistics Network | Bypasses wholesale distributor margin capture in Île-de-France automotive service chains. |
| OECD 301B Biodegradability Certification Investment | Secures harbor authority approval for marine lubricant sales in Marseille and Le Havre port complexes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant formulators, automotive workshop procurement managers, industrial plant maintenance directors, and ECHA regulatory affairs specialists with secondary validation from customs trade data, ACC/Cefic chemical industry reports, SEC filings of integrated energy majors, and French national environmental regulator enforcement disclosures. Bottom-up volume builds from end-use segment consumption patterns were triangulated against top-down macroeconomic indicators.
Comparable-period anchoring used historical demand patterns across automotive drain interval extensions, industrial automation adoption curves, and regulatory compliance phase-in timelines to structure projection assumptions. Segmentation dimensions modeled include product type, application sector, end-user procurement authority, and distribution channel structure, with additional granularity on REACH compliance tier and biodegradability certification status. CAGRs were derived from segment-level growth trajectory analysis incorporating OEM specification shifts and re-refined base oil feedstock availability projections.
The model assumes a particular technology adoption path for synthetic lubricant architectures; alternative pathways for polyalkylene glycol base stock penetration in food processing applications would alter the outlook for mineral oil displacement rates. Forecasts reflect documented assumptions on regulatory enforcement intensity and carbon border adjustment implementation scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Drilling Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Egypt Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Brazil Automotive Lubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Thailand Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
Global Grease Market