
 Putty Fillers Market | 2026-2036
Putty Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Putty Fillers Market Analysis
Automotive repair shops are redrawing demand patterns away from general contractors in the putty fillers space. Sherwin-Williams leverages its captive distribution network to dominate professional automotive channels. Sika AG anchors its position through deep specialization in high-performance industrial formulations. Henkel competes by sustaining R&D intensity in epoxy-based metal repair compounds.
Putty fillers are viscous, moldable compounds composed of resins, fillers, and solvents designed to fill surface imperfections before finishing; typical formulations cure through solvent evaporation or chemical cross-linking to achieve sandability and paint adhesion. Wood fillers command mature volume in residential renovation, while metal fillers capture expanding margin pools from automotive collision repair. Plastic fillers represent the fastest-growing application segment as polymer substrate repair gains traction in industrial maintenance and consumer goods restoration.
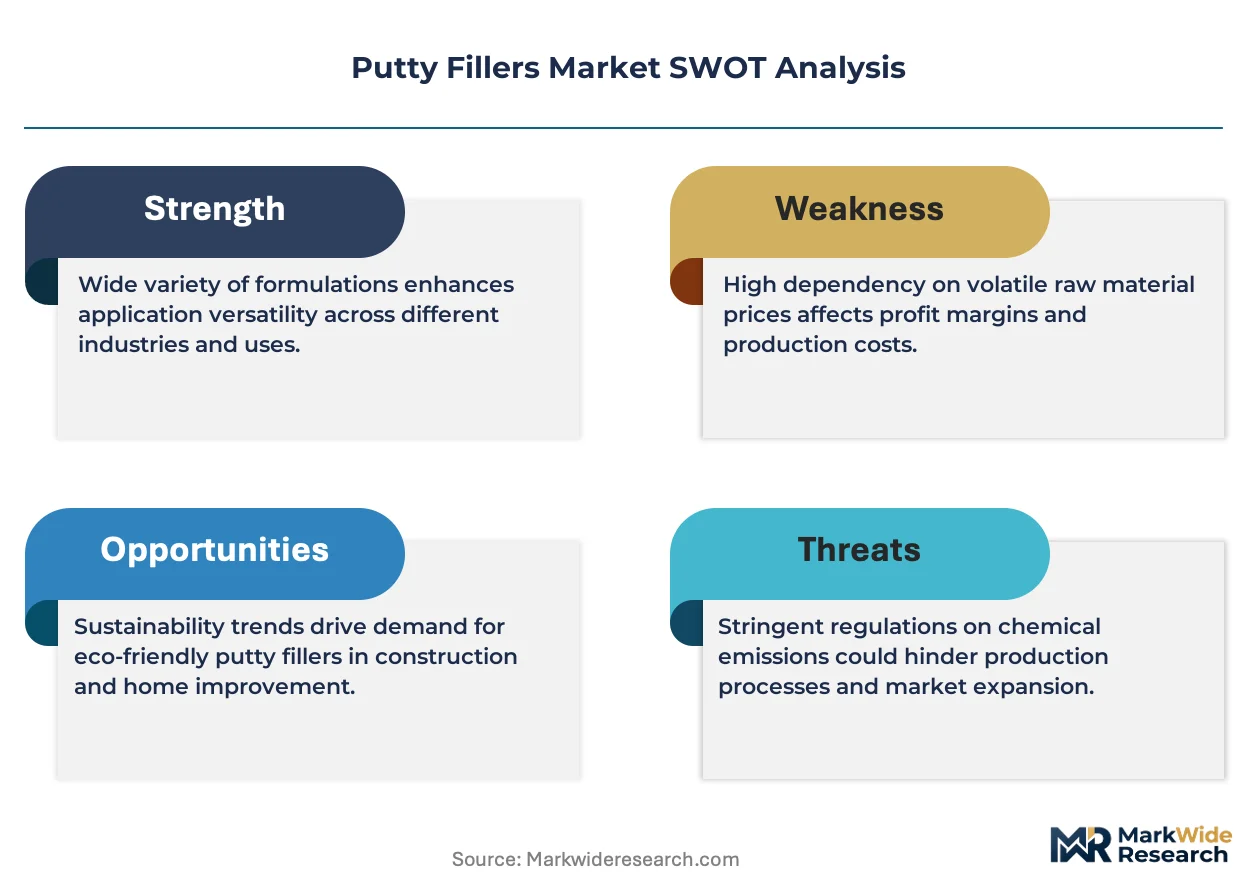
EPA VOC regulations in the United States restrict solvent content in architectural coatings, directly limiting conventional putty formulations and accelerating water-based product development. REACH and the EU Green Deal impose parallel constraints across European manufacturing, with ECHA classification rules affecting raw material sourcing for alkyd and polyester-based systems. Stakeholders must monitor evolving chemical hazard designations and decide whether to absorb reformulation costs or reposition toward exempt product categories.
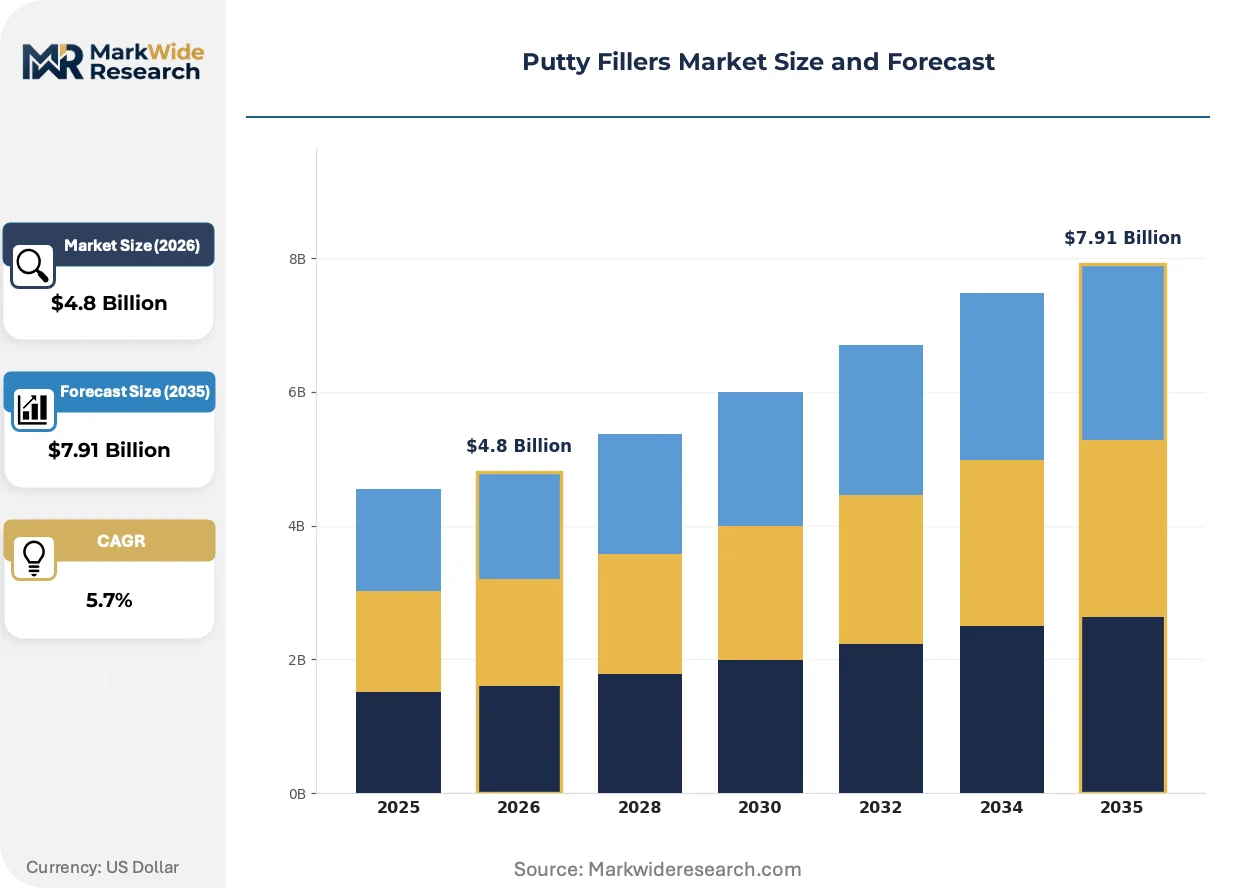
Market Dynamics
Automotive collision repair volumes are compressing cure-time tolerances and driving adoption of rapid-cure polyester formulations across professional refinishing channels. This demand compression is forcing raw material suppliers to prioritize low-temperature catalyst systems and specialized metal-grade fillers over commodity wood repair compounds.
Growth Catalysts
- REACH VOC thresholds:Tightening solvent limits across EU manufacturing are accelerating water-based alkyd reformulation and opening premium positioning for compliant system suppliers.
- Polymer substrate repair:Industrial maintenance teams are expanding plastic filler consumption for thermoplastic component restoration in consumer goods and equipment remanufacturing.
- Germany:Automotive refinishing clusters in Stuttgart and Wolfsburg are driving premium-grade metal filler volumes through specialized distributor networks serving OEM-certified repair facilities.
Market Restraints
- Titanium dioxide volatility:Pigment cost swings are compressing margin stability for white and light-tone filler formulations across architectural and automotive segments.
- Chinese resin concentration:Polyester and vinyl ester feedstock dependence on East Asian petrochemical complexes creates exposure to shipping bottlenecks and tariff friction.
- UV-cure substitution:Light-activated repair systems for clearcoat and gelcoat applications are capturing share in marine and recreational vehicle repair shops.
Strategic Opportunities
- India:BIS certification requirements for imported coatings are creating localized formulation partnerships for multinationals seeking access to infrastructure and automotive aftermarket expansion.
- Wind blade repair:Composite filler systems for turbine maintenance are emerging as a high-margin application as installed base ages and blade inspection cycles compress.
- EU Green Deal:Carbon border adjustments and embodied carbon tracking are rewarding bio-based resin development and solvent recovery system investments.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in hybrid epoxy-polyester systems for metal adhesion is concentrating at a handful of technical centers, constraining new product pipeline velocity.
- REACH pre-registration timelines:ECHA substance evaluation delays for novel cross-linking agents are extending go-to-market cycles by 18-24 months for innovative curing technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Putty Fillers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Fillers, Wall Fillers, Metal Fillers, Plastic Fillers Application: Interior Use, Exterior Use, Furniture Repair, Industrial Use End User: Contractors, DIY Homeowners, Furniture Manufacturers, Automotive Repair Shops Packaging Type: Tubes, Cans, Buckets, Pouches |
| Companies Covered | Sherwin-Williams, 3M Company, Akzo Nobel, Henkel, Evercoat, Sika AG, RPM International, Motip Dupli B.V., Heima Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Putty Fillers Market Emerging Trajectories
Waterborne chemistry is overtaking solvent-based systems as the default platform for professional-grade putty formulations. This transition is compressing the viable technology set and favoring suppliers with captive resin synthesis capabilities over compounders dependent on merchant feedstocks.
Hybrid waterborne-epoxy systems are displacing conventional nitrocellulose and alkyd solvent formulations in automotive refinishing applications. Tier-1 collision repair networks in Germany and the United States are specifying these systems for their flash-rust resistance and sandability profiles. The shift is compressing demand for traditional solvent-heavy metal fillers and forcing reformulation investments among mid-tier suppliers lacking waterborne expertise.
EPA VOC regulations for architectural coatings are tightening permissible solvent content in consumer-grade wood fillers and spackling compounds. Manufacturers serving the US home improvement channel are reducing toluene and xylene levels and accelerating water-based product registration. The compliance burden falls heaviest on small compounders without dedicated regulatory affairs functions, consolidating shelf access toward integrated coatings suppliers.
Certification-driven procurement is displacing price-based supplier selection in OEM-authorized automotive repair networks. I-CAR and manufacturer-specific certification requirements are narrowing approved product lists to formulations with documented cure performance and adhesion testing. This behavioral shift concentrates volume among technical service-intensive suppliers and reduces switching flexibility for independent repair shops seeking cost relief.
Putty Fillers Market Segmentation
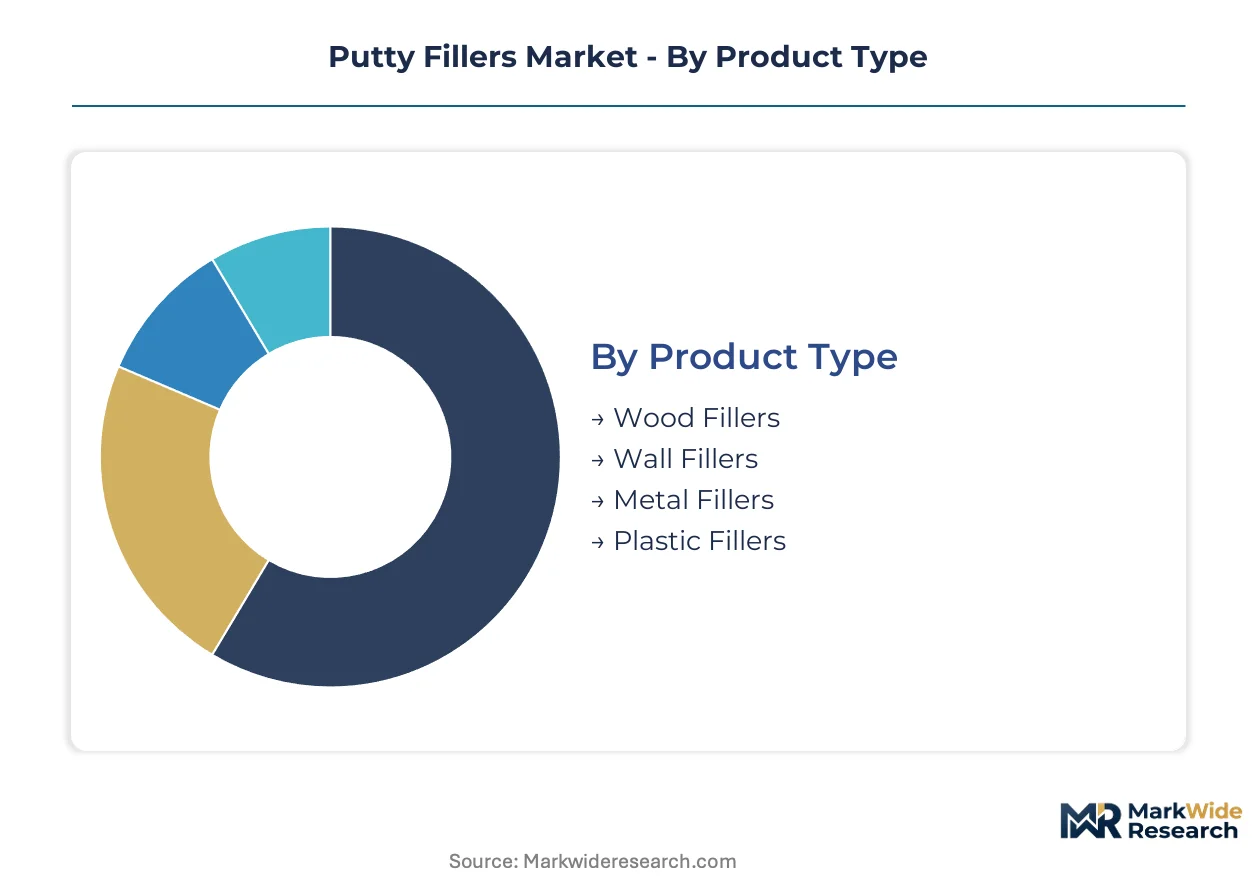
Putty fillers demand fragments across substrate-specific formulations, each carrying distinct technical specifications and margin profiles. Understanding where volume concentrates versus where value accumulates enables targeted portfolio positioning for suppliers navigating reformulation pressures.
Product Type:
Margin pools sit heaviest in metal-grade formulations serving collision repair networks, where certification barriers protect pricing power.
- Wood Fillers:Cellulose-reinforced alkyd or latex-based compounds formulated for grain-filling and nail-hole repair in softwood and hardwood substrates. DIY homeowners in North American home improvement channels drive baseline volumes, though EPA VOC limits are squeezing solvent-based variants and accelerating waterborne conversions among professional contractors.
- Metal Fillers:Polyester or epoxy-based systems with aluminum or fiberglass reinforcement, engineered for adhesion to steel, aluminum, and galvanized substrates. Automotive repair shops in Germany's Stuttgart refinishing cluster specify premium rapid-cure grades, compressing cure-time tolerances and favoring suppliers with low-temperature catalyst expertise.
- Wall Fillers:Gypsum or vinyl-modified spackling compounds for drywall seam finishing and surface leveling. Residential renovation contractors in mature markets sustain replacement demand.
- Plastic Fillers:Flexible urethane or epoxy formulations bonding to thermoplastic and thermoset polymers. Industrial maintenance teams expanding polymer substrate repair applications are climbing the fastest.
Metal fillers hold installed capacity. Plastic fillers are rotating up the share rankings.
Application:
Volume concentrates in interior architectural finishing, though exterior and industrial applications command formulation premiums for weathering resistance and chemical tolerance.
- Interior Use:Low-odor, quick-sand spackling and wood fillers for residential and commercial drywall finishing. Contractors in US metropolitan markets prioritize EPA-compliant low-VOC formulations to maintain jobsite access.
- Exterior Use:Elastomeric and epoxy-based fillers engineered for thermal cycling, moisture resistance, and UV stability. Siding repair and exterior trim restoration in climates with freeze-thaw exposure drive specification of flexible, paintable grades.
- Furniture Repair:Color-matched, stainable wood fillers for solid wood and veneer restoration. Furniture manufacturers in high-cost labor markets specify rapid-drying grades to compress finishing cycle times.
- Industrial Use:High-build, chemical-resistant fillers for equipment remanufacturing and facility maintenance. Expanding most quickly as asset life extension programs prioritize repair over replacement in capital-constrained environments.
Interior use anchors volume concentration. Industrial use is climbing the value chain fastest.
End User:
Procurement authority separates price-sensitive DIY purchasers from specification-locked professional channels where technical service determines supplier selection.
- Contractors:Professional finishers and renovators purchasing through distributor and direct sales channels. Volume scale and repeat purchase frequency support private-label and mid-tier brand positioning.
- DIY Homeowners:Retail-channel purchasers selecting pre-mixed, consumer-packaged wood and wall fillers. Home improvement retailers in the United States curate assortments around VOC compliance and ease-of-use claims.
- Furniture Manufacturers:Industrial buyers specifying fillers for production-line defect repair and finishing preparation. Quality consistency and batch-to-batch uniformity outweigh unit cost in supplier selection.
- Automotive Repair Shops:Collision repair facilities and refinishing networks with OEM certification requirements. I-CAR and manufacturer-specific approval lists narrow supplier pools to technically service-intensive providers.
Contractors hold volume concentration. Automotive repair shops are rotating up the margin rankings.
Packaging Type:
Packaging economics track application scale and jobsite logistics, with bulk formats serving high-volume contractors and unit-dose designs penetrating DIY and touch-up segments.
- Tubes:Squeeze-dispensed formats for small-quantity touch-up and consumer DIY applications. Retail shelf presence and controlled dispensing precision support premium positioning.
- Cans:Metal containers for solvent-based and waterborne putties requiring resealable storage. Standard format for professional wood and metal filler distribution.
- Buckets:Bulk packaging for high-volume contractors and industrial maintenance operations. Cost-per-unit advantages concentrate demand among professional finishers with established storage and handling systems.
- Pouches:Flexible, lightweight formats reducing shipping cost and shelf space requirements. Emerging in private-label and value-tier positioning for price-sensitive channels.
Cans hold installed format preference. Pouches are rotating up the innovation pipeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's role as a formulation hub for REACH-compliant waterborne systems. Rail corridors linking Stuttgart's automotive refinishing cluster to Antwerp's resin suppliers compress lead times for premium-grade metal fillers.
United States
EPA VOC regulations for architectural coatings are squeezing solvent-based wood filler formulations in the home improvement channel. The agency's 2024 emission standards are accelerating waterborne product registrations among professional contractors. Detroit's collision repair networks specify rapid-cure polyester systems for OEM-certified facilities serving the domestic automotive aftermarket.
Germany
REACH substance evaluation timelines are extending go-to-market cycles for novel cross-linking agents by 18-24 months. ECHA's 2023 updates to hazard classification rules are forcing reformulation of alkyd-based metal repair compounds. Stuttgart's refinishing cluster drives premium-grade consumption through specialized distributor networks serving Volkswagen and Porsche-certified repair facilities.
China
Dual carbon goals and MEE emission standards are tightening solvent content limits in industrial coatings manufacturing. GB standards for architectural coatings are accelerating water-based putty development among domestic compounders. Yangtze River Delta chemical parks near Shanghai concentrate polyester resin synthesis capacity serving regional automotive and furniture manufacturing.
India
BIS certification requirements for imported coatings are creating localized formulation partnerships for multinationals seeking aftermarket access. The PLI scheme for chemical manufacturing is incentivizing domestic resin production capacity. Maharashtra's automotive manufacturing belt around Pune and Nashik is driving collision repair network expansion and certified filler consumption.
Japan
METI's chemical management policies are aligning domestic formulation standards with REACH-equivalent hazard classifications. JIS standards for automotive refinishing materials are narrowing approved product lists for OEM-authorized repair networks. Kansai's industrial corridor around Osaka concentrates high-performance epoxy compound manufacturing for electronics and precision equipment restoration.
Putty Fillers Market Vendor Landscape
Concentration sits with integrated coatings suppliers controlling captive resin synthesis and distribution networks. The vendor base separates into three tiers: multinational chemical conglomerates with full formulation stacks, regional specialists in substrate-specific repair systems, and private-label compounders serving price-sensitive retail channels. Dominant competitive moves include backward integration into waterborne resin production and certification-driven partnerships with OEM-authorized repair networks.
Among integrated coatings suppliers, Sherwin-Williams and Akzo Nobel exemplify archetypes combining captive distribution with professional-channel certification depth. Sika AG occupies a position within the high-performance industrial formulation tier, anchoring expertise in hybrid epoxy-polyester systems for structural repair applications. These three represent contrasting pathways to margin protection: retail-scale private-label penetration, professional-service technical intensity, and industrial-specialization premium positioning.
| Leading Market Players |
|---|
| Sherwin-Williams |
| 3M Company |
| Akzo Nobel |
| Henkel |
| Evercoat |
| Sika AG |
| RPM International |
| Motip Dupli B.V. |
| Heima Chemicals |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles for polyester resin feedstocks concentrate pricing leverage among German and Chinese compounders with captive synthesis capacity, compressing margin capture for merchant-dependent formulators in North American automotive channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with I-CAR certification status and volume scale serving as the primary differentiation drivers. Price erosion runs through the economy tier as private-label compounders compete for shelf space at home improvement retailers. Automotive repair shops exhibit the lowest price sensitivity due to OEM-mandated product lists, while DIY homeowners drive aggressive cost competition.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for alkyd resin shipments originating from Yangtze River Delta chemical parks. Feedstock concentration in China, Germany, and Belgium draws from titanium dioxide, polyester resin, and low-temperature catalyst dependencies. Single-source vulnerability in Chinese petrochemical complexes creates tariff exposure. Distribution runs through specialized automotive refinishing distributors and home improvement retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as certification-driven procurement interoperability locks repair networks into approved product ecosystems, marginalizing standalone compounders lacking OEM authorization.
For Market Incumbents: Consolidate backward integration into waterborne resin synthesis to defend margin pools against REACH-driven reformulation costs. Deepen certification investment with Volkswagen and Porsche-certified repair networks in Stuttgart to anchor channel control. Acquire mid-tier compounders in India to preempt BIS-compliant localized production requirements. For New Entrants and Emerging Players: Anchor in wind blade repair applications as composite filler demand climbs with turbine aging. Target India's Maharashtra automotive belt through PLI-linked domestic formulation partnerships. Pursue private-label positioning with US home improvement retailers seeking EPA-compliant water-based wood filler alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across waterborne resin synthesis as REACH compliance mandates captive production infrastructure. Five-to-ten year viability favors integrated coatings suppliers with distributor network control over standalone compounders. Monitor ECHA substance evaluation timelines as inflection signals for novel curing technology acquisition windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waterborne Resin Synthesis | REACH VOC thresholds force captive production to protect margin stability. |
| OEM Certification Partnership Expansion | I-CAR and manufacturer-specific approvals narrow competitive supplier pools. |
| Localized Formulation Partnership in India | BIS certification requirements create barriers for unlocalized imports. |
| Wind Blade Repair Application Development | Composite filler systems address aging turbine maintenance demand. |
| Green Manufacturing Transition | EU Green Deal carbon border adjustments reward bio-based resin investments. |
Methodological Framework
Cross-validation between primary interviews with automotive refinishing technicians, collision repair shop owners, coatings procurement managers, and regulatory affairs directors anchors the qualitative findings. Secondary validation draws from ECHA substance registration databases, EPA VOC compliance filings, customs trade data for resin feedstocks, and automotive OEM technical service bulletins. Bottom-up volume estimates triangulate against top-down coatings market sizing.
Sensitivity analysis across substrate type, end-user procurement authority, and regional regulatory cluster informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product formulation chemistry, packaging format, certification tier, and regional production hub concentration. CAGRs derive from trend extrapolation of collision repair volumes, REACH implementation timelines, and waterborne conversion rates in professional channels.
Material uncertainties — ECHA hazard reclassification delays, titanium dioxide price volatility, and shipping route disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and OEM certification list stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Superacids Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Polyoxin Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Fluoropolymer Masterbatch Market