
 Organosulfur Compounds Market | 2026-2036
Organosulfur Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Organosulfur Compounds Market Analytics
ISO 22000 certification for food-grade organosulfur additives is bifurcating the supplier base into qualified and non-qualified tiers. AkzoNobel leverages its integrated alkyl sulfide chain to sustain European supply continuity for pharmaceutical-grade thiols. Chevron Philips anchors North American mercaptan production through its Gulf Coast petrochemical complex, while Gaylord Chemical specializes in dimethyl sulfide and dimethyl sulfoxide for specialty solvent applications.
Organosulfur compounds are carbon-sulfur bonded molecules typically synthesized via thiolation, sulfonation, or oxidation of hydrocarbon feedstocks, with purity grades ranging from technical (95%) to pharmaceutical (≥99.5%) specifications; they function primarily as chemical intermediates, vulcanization accelerators, and odorant additives across industrial processes. The thiol segment leads volume due to pervasive use in rubber curing and gas odorization, while sulfone derivatives are gaining fastest in pharmaceutical synthesis driven by bioactive molecule complexity. Liquid formulations dominate logistics efficiency for bulk chemical manufacturing, though powder forms command margin premiums in pharmaceutical and food processing end users where dosing precision matters.
EPA oversight of mercaptan emissions and REACH registration requirements for sulfur-containing substances are elevating compliance costs and favoring producers with established regulatory dossiers. FDA food additive regulations and F-Gas Regulation considerations in Europe further constrain formulation flexibility for cross-border suppliers. Stakeholders must monitor evolving BIS standards in India and anticipate harmonization pressures between EPA and ECHA hazard classifications that could reshape competitive access across major demand centers.
Market Dynamics
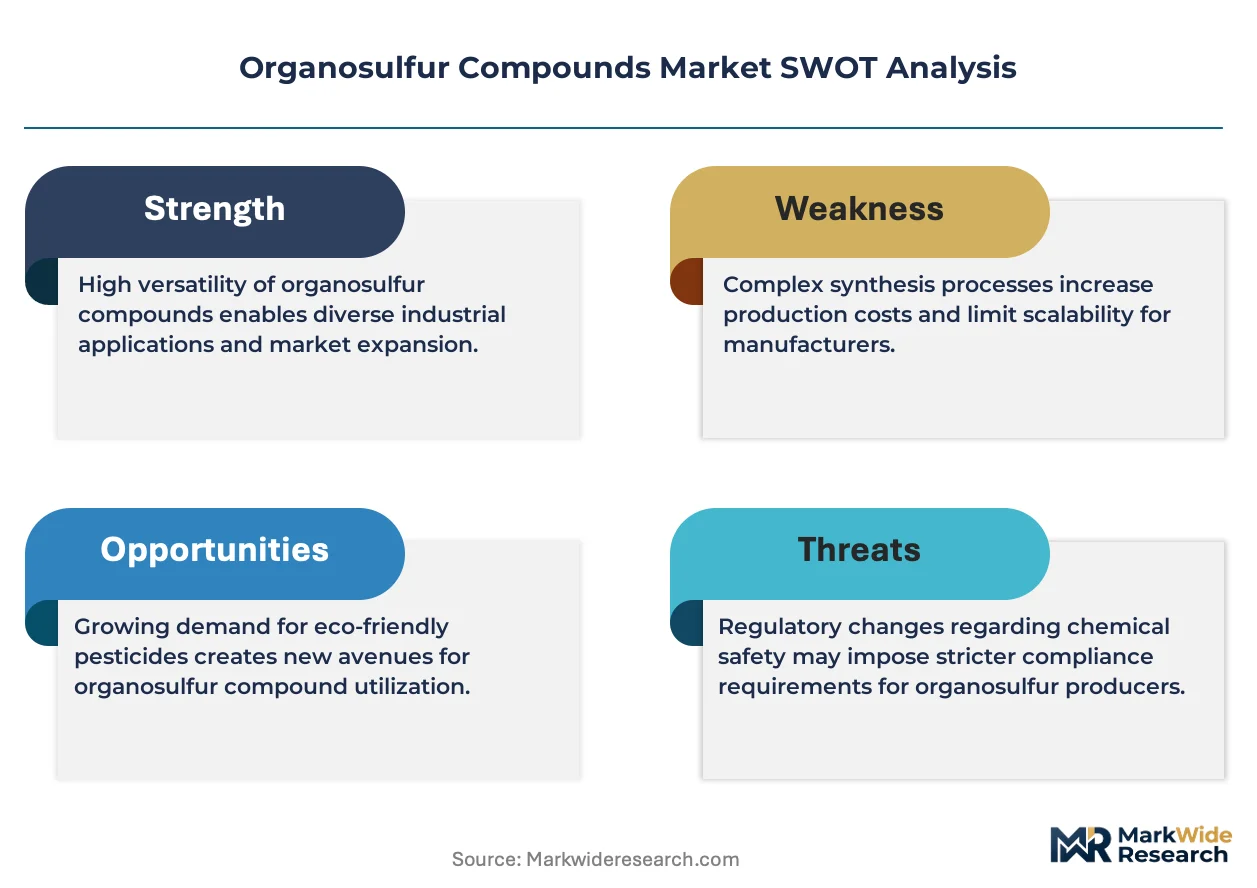
REACH registration dossiers for sulfur-containing substances are bifurcating the supplier base into compliant and non-compliant tiers, forcing capacity consolidation toward producers with established regulatory infrastructure and documented purity certifications.
Growth Catalysts
- Pharmaceutical thiol procurement:Active ingredient manufacturers are scaling purchases of thiol-based intermediates for complex bioactive molecule synthesis, particularly for antiviral and oncology therapeutic classes.
- India PLI scheme incentives:Production-linked incentive structures for specialty chemicals are attracting domestic and multinational capacity investments into organosulfur manufacturing clusters.
- Rubber vulcanization demand:Tire producers in Southeast Asia are expanding accelerator offtake as automotive OEMs restock inventory and electric vehicle production scales.
Market Restraints
- Feedstock sulfur volatility:Refinery sulfur output fluctuations and petroleum coke pricing swings compress margin predictability for mercaptan and sulfide producers.
- European supply concentration:REACH-compliant pharmaceutical-grade thiol capacity clusters disproportionately in Germany and the Netherlands, creating single-source vulnerability for qualified buyers.
- Substitution by nitrogen-based accelerators:Rubber compounders are piloting guanidine and thiourea alternatives in select curing applications to reduce odor and handling complexity.
Strategic Opportunities
- Brazil agrochemical formulation:ANVISA registration pathways for sulfur-based fungicides and nematicides remain underpenetrated relative to synthetic pyrethroid alternatives.
- Continuous flow thiolation:Microreactor technology convergence with photochemical activation is enabling on-demand pharmaceutical intermediate production with reduced solvent waste.
- FSSAI food additive expansion:India's food safety regulator is expanding approved uses for diallyl disulfide and related organosulfur flavor precursors in processed food categories.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA Drug Master File and EMA Active Substance Master File documentation for novel thiol intermediates extends 18-24 months, delaying commercialization.
- Specialized reaction engineering talent:Industrial-scale thiolation and controlled oxidation process expertise concentrates among retiring cohorts in European and Japanese chemical clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organosulfur Compounds Market |
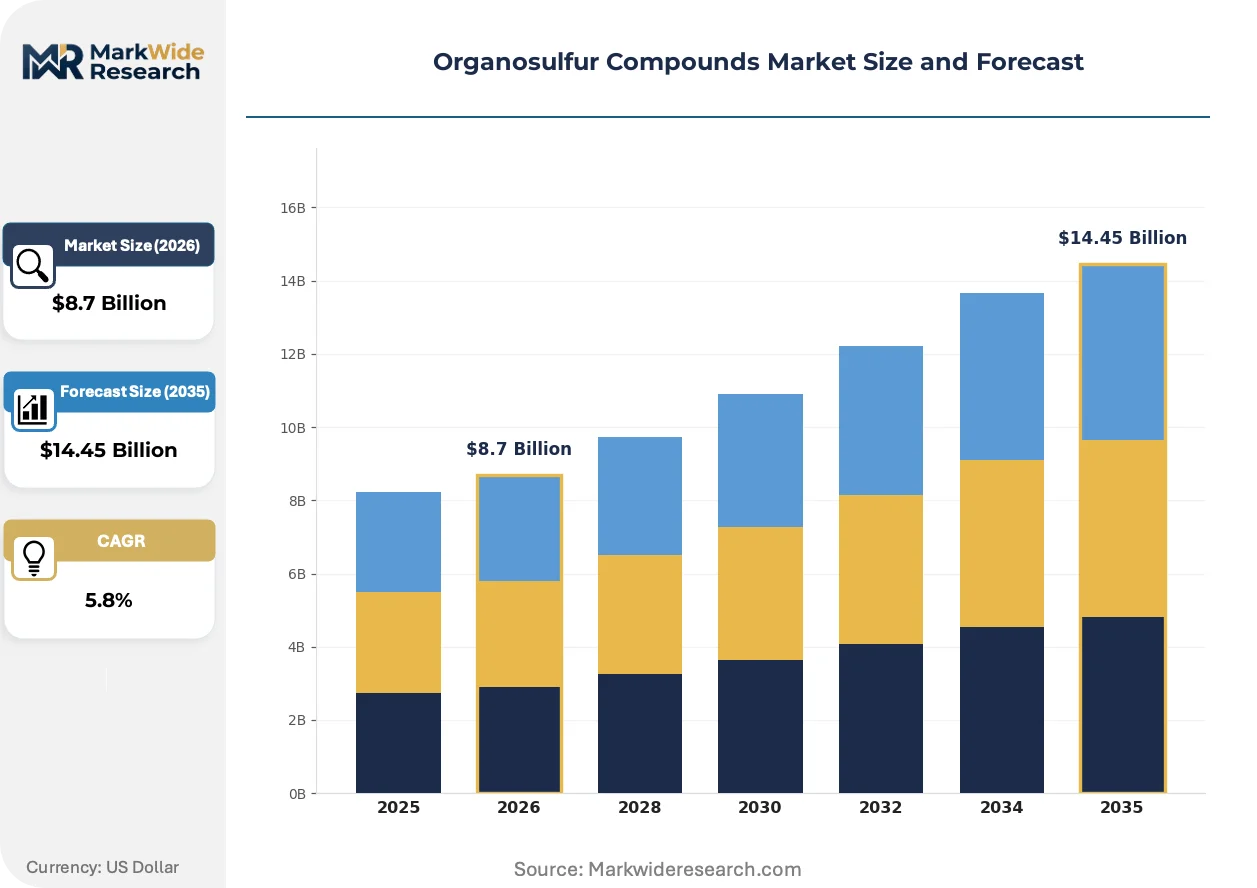
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thiol, Sulfoxide, Sulfone, Disulfide Application: Agriculture, Pharmaceuticals, Food Industry, Chemical Manufacturing End User: Research Institutions, Agrochemical Companies, Pharmaceutical Firms, Food Processors Form: Liquid, Powder, Granule, Paste |
| Companies Covered | New India Detergents, AkzoNobel, Chevron Philips, Tessenderlo Group, Nouryon Chemicals, Gaylord Chemical, Solvay, Sasol, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organosulfur Compounds Market Evolving Landscape
Process intensification and regulatory compliance automation are reshaping competitive advantage in organosulfur manufacturing, compressing the viable supplier set toward technology-integrated producers.
Continuous flow microreactor systems for thiolation and sulfonation reactions are miniaturizing batch-scale operations into modular, temperature-precise units. Pharmaceutical contract manufacturers in Switzerland and Singapore are adopting these systems for high-potency active ingredient precursors. The technology is miniaturizing capital requirements for entry into pharmaceutical-grade segments, enabling mid-scale producers to compete with integrated petrochemical majors on purity consistency.
REACH authorization requirements for substances of very high concern are tightening disclosure obligations for sulfur-containing process chemicals used in polymer manufacturing. ECHA's 2024-2025 substance evaluation work program prioritizes certain alkyl sulfides for hazard reassessment. German and Dutch chemical distributors are pre-positioning alternative sourcing arrangements ahead of potential restriction proposals, shifting procurement patterns toward pre-registered suppliers with complete toxicological dossiers.
Specification-driven procurement is consolidating buyer power among pharmaceutical and agrochemical formulators, compressing supplier margins while elevating technical service requirements. Tier-one compounders in India and South Korea are unbundling chemical supply from analytical validation support, awarding integrated service contracts to qualified producers. This pattern is most visible in the antibiotic intermediate segment, where CDMOs demand batch-specific impurity profiling and stability data packages as standard commercial terms.
Organosulfur Compounds Market Segmentation
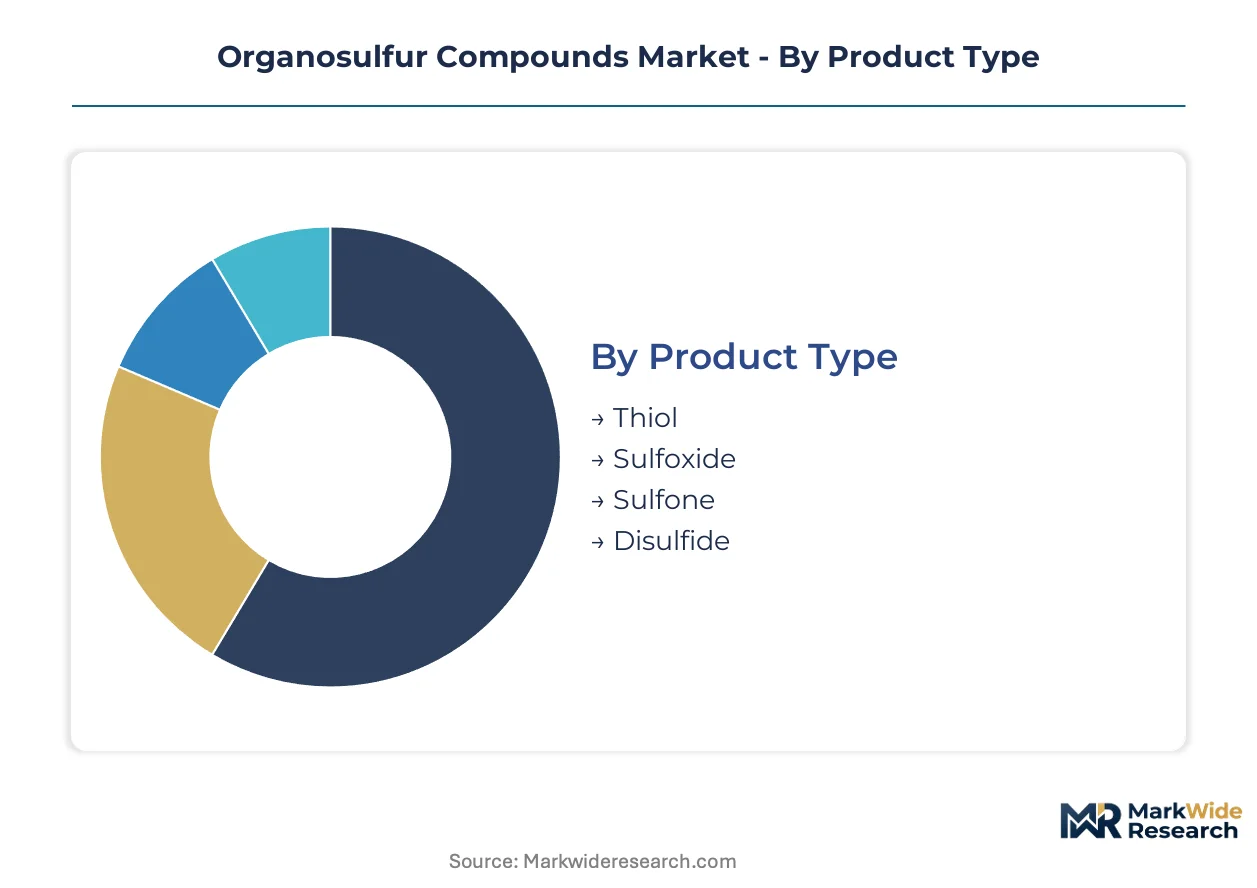
Margin concentration in organosulfur compounds varies sharply across molecular structures and purity grades. Pharmaceutical-grade specifications command substantial premiums over technical grades, while formulation flexibility determines access to high-value end-use contracts.
Product Type:
Margin pools concentrate in pharmaceutical-grade thiols and sulfones where regulatory dossiers create supply scarcity.
- Thiol:Carbon-sulfur bonded molecules with terminal -SH functional groups serve as vulcanization accelerators and gas odorants. Rubber manufacturers in India and Southeast Asia drive volume procurement for tire curing applications, though odor handling complexity elevates operational costs for compounders.
- Sulfone:Sulfur dioxide-embedded structures function as pharmaceutical intermediates for antiviral and oncology synthesis. CDMOs in Switzerland and Singapore are scaling sulfone procurement for high-potency active ingredient manufacturing, drawn by bioavailability enhancement properties.
- Sulfoxide:Polar aprotic solvents like dimethyl sulfoxide enable nucleophilic substitution reactions in specialty chemical synthesis.
- Disulfide:Sulfur-sulfur bonded compounds serve as rubber crosslinking agents and polymerization regulators.
The dominant share belongs to Thiol, while Sulfone is closing the gap fastest.
Application:
Cost tiers separate commodity chemical manufacturing from regulated pharmaceutical and food-grade applications requiring certification infrastructure.
- Pharmaceuticals:Active ingredient manufacturers procure thiol-based intermediates for complex bioactive molecule synthesis. FDA Drug Master File and EMA Active Substance Master File requirements extend certification timelines, concentrating procurement among qualified suppliers with established dossiers.
- Agriculture:Sulfur-based fungicides and nematicides face formulation constraints from EPA and REACH residue limits. Brazilian ANVISA registration pathways for organosulfur crop protection remain underpenetrated relative to synthetic pyrethroid alternatives.
- Food Industry:FSSAI in India is expanding approved uses for diallyl disulfide and related flavor precursors in processed food categories.
- Chemical Manufacturing:Technical-grade organosulfur compounds serve as process solvents and polymerization regulators.
Pharmaceuticals captures the highest margin tier, with Agriculture expanding most quickly on agrochemical formulation growth.
End User:
Customer type determines service intensity, with pharmaceutical firms demanding batch-specific analytical validation that commodity buyers forego.
- Pharmaceutical Firms:Active ingredient manufacturers require impurity profiling and stability data packages as standard commercial terms. Tier-one compounders in India and South Korea are unbundling chemical supply from analytical validation support, awarding integrated service contracts to qualified producers.
- Agrochemical Companies:Formulators prioritize cost efficiency and supply continuity for sulfur-based crop protection inputs.
- Food Processors:ISO 22000 certification requirements are bifurcating the supplier base into qualified and non-qualified tiers.
- Research Institutions:Academic and contract research organizations procure small-batch organosulfur compounds for method development.
Pharmaceutical Firms dominate procurement value, while Food Processors are gaining share fastest on FSSAI additive expansion.
Form:
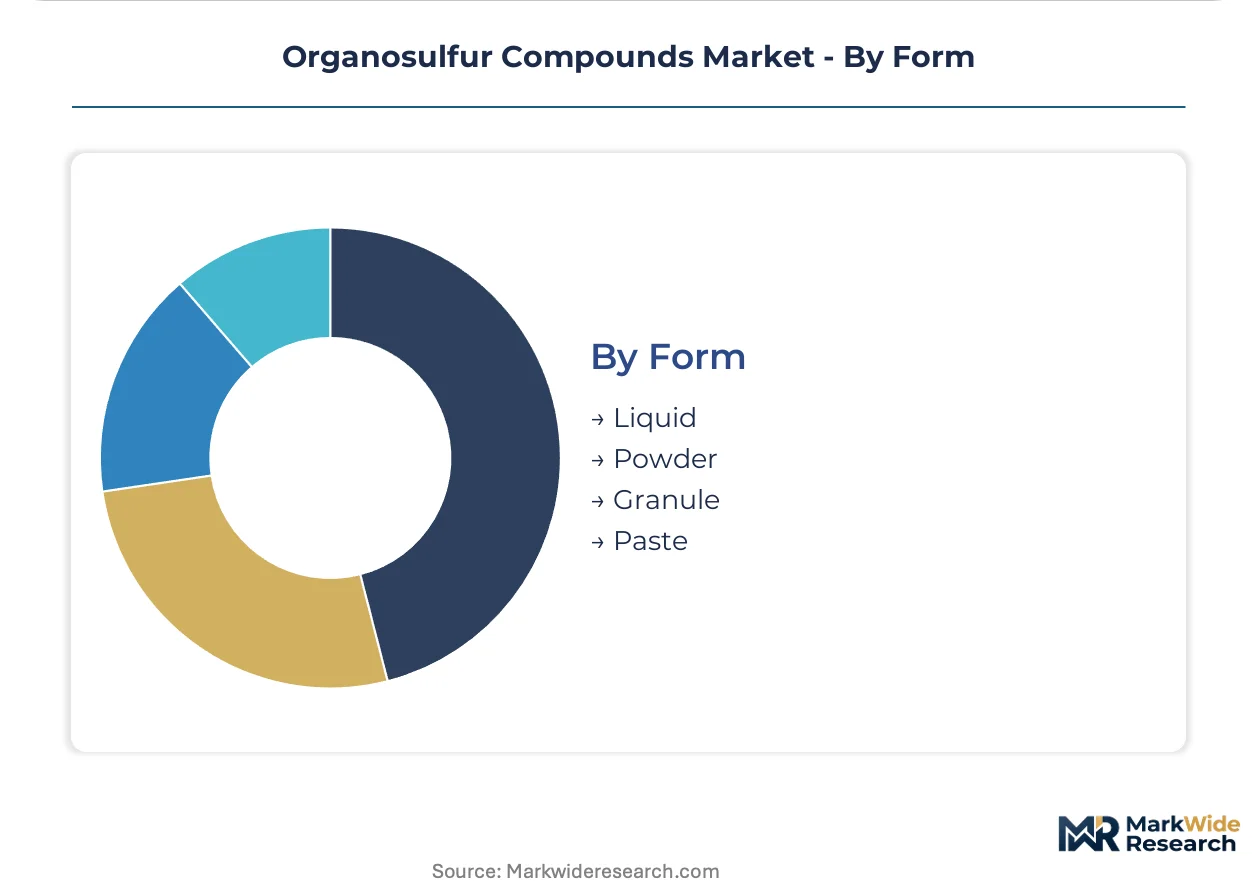
Physical state shapes logistics economics and dosing precision requirements across manufacturing contexts.
- Liquid:Bulk mercaptan and sulfide formulations dominate logistics efficiency for continuous chemical manufacturing. Chevron Philips anchors North American supply through Gulf Coast petrochemical complex infrastructure.
- Powder:Solid formulations command margin premiums in pharmaceutical and food processing where dosing precision matters. Powder handling complexity elevates capital requirements for producers.
- Granule:Controlled-release sulfur formulations serve agricultural nematicide applications.
- Paste:High-viscosity preparations enable localized application in rubber compounding.
Liquid holds the dominant share, while Powder is climbing the fastest on pharmaceutical precision dosing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel petrochemical corridor underwrites North American mercaptan supply continuity through integrated refinery-sulfur processing infrastructure.
United States
Gulf Coast petrochemical complexes process refinery sulfur streams into pharmaceutical-grade thiols and gas odorants. EPA emission standards for mercaptan handling tighten operational compliance thresholds. Houston and Baton Rouge concentration zones anchor Chevron Philips production capacity for North American tire and natural gas utility offtake.
Germany
Leverkusen and Ludwigshafen chemical clusters synthesize alkyl sulfide chains for European pharmaceutical intermediate demand. REACH registration dossiers for sulfur-containing substances bifurcate qualified from non-qualified supplier tiers. ECHA's substance evaluation work program prioritizes certain alkyl sulfides for hazard reassessment, pressuring distributors toward pre-registered sources.
India
Maharashtra and Gujarat specialty chemical parks scale thiol production under PLI scheme incentives for import substitution. BIS certification expansion for food-grade organosulfur additives concentrates qualified supply among certified producers. Ankleshwar and Dahej manufacturing corridors attract multinational capacity investments for agrochemical intermediate exports.
Switzerland
Basel-region contract manufacturers adopt continuous flow microreactor systems for high-potency pharmaceutical thiolation. Swissmedic oversight of active substance master files extends certification timelines for novel intermediates. The region's precision chemical engineering expertise supports on-demand production models for complex bioactive molecule synthesis.
China
Yangtze River Delta petrochemical hubs integrate sulfur recovery from coal processing into dimethyl sulfide and sulfoxide production. NMPA registration requirements for pharmaceutical-grade imports create documentation barriers for foreign suppliers. Zhejiang and Jiangsu provinces concentrate technical-grade capacity for rubber accelerator and solvent export markets.
Organosulfur Compounds Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier depth and purity certification infrastructure. The supplier base consolidates toward producers with established REACH registrations and FDA Drug Master File documentation, compressing viable participants in pharmaceutical-grade segments. Three archetypes dominate: integrated petrochemical majors with captive sulfur feedstock, European specialty chemical houses with regulatory dossier libraries, and Asian contract manufacturers scaling under production-linked incentive schemes. Competitive dynamics center on backward integration into refinery sulfur streams and technology licensing for continuous flow thiolation processes.
Within the integrated petrochemical tier, Chevron Philips and Sasol occupy positions anchored to Gulf Coast and South African refinery-sulfur infrastructure respectively. AkzoNobel exemplifies the European specialty chemical archetype with documented alkyl sulfide chain integration. Gaylord Chemical sits within the North American specialist segment focused on dimethyl sulfide and dimethyl sulfoxide solvent applications. These three represent divergent strategic postures on vertical scope and geographic market access.
| Leading Market Players |
|---|
| New India Detergents |
| AkzoNobel |
| Chevron Philips |
| Tessenderlo Group |
| Nouryon Chemicals |
| Gaylord Chemical |
| Solvay |
| Sasol |
| Arkema |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day pharmaceutical-grade thiol lead times concentrate pricing power among REACH-registered producers in Germany and the Netherlands, while technical-grade mercaptan buyers in Southeast Asia leverage spot-market liquidity to compress contract premiums. This inventory-band divergence rewards dossier-complete suppliers with margin capture in regulated segments and exposes commodity producers to sulfur feedstock volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels stratifies margin pools by certification burden. Price differentiation centers on REACH dossier completeness and FDA Drug Master File status, with pharmaceutical buyers absorbing premiums for qualified supply while tire compounders negotiate volume rebates. Pricing pressure stems from refinery sulfur output fluctuations that compress mercaptan producer margins. Agrochemical formulators exhibit highest price sensitivity due to pyrethroid substitution alternatives, whereas CDMOs prioritize supply security over unit cost.
Supply Chain Analysis
Forty-five-day average inventory cover for Gulf Coast mercaptan producers masks single-source vulnerability in pharmaceutical-grade thiol supply. Production concentrates in the United States, Germany, and India, with each hub anchored to distinct feedstock regimes—refinery sulfur streams, coal-chemical integration, and PLI-subsidized specialty chemical parks respectively. Raw material dependencies span petroleum coke, refinery off-gas sulfur, and methanol for dimethyl sulfide synthesis. Tariff exposure on Chinese technical-grade imports threatens downstream rubber accelerator supply. Distribution runs through integrated petrochemical complexes and specialty chemical distributors with regional regulatory expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical thiol procurement acceleration represents an early-cycle expansion tailwind, with CDMOs scaling sulfone intermediate offtake for antiviral and oncology synthesis pipelines. This adoption inflection creates asymmetric returns for qualified suppliers with established regulatory dossiers.
For Market Incumbents: Shield pharmaceutical-grade margin pools by accelerating ECHA pre-registration for alkyl sulfides under substance evaluation review. Prioritize backward integration into Gulf Coast refinery sulfur streams to insulate against petroleum coke price volatility. Consolidate analytical validation capabilities to capture integrated service contracts from tier-one compounders in India and South Korea. For New Entrants and Emerging Players: Differentiate on continuous flow microreactor technology to bypass capital-intensive batch-scale infrastructure. Target Brazil's underpenetrated ANVISA registration pathways for sulfur-based fungicides and nematicides. Pursue FSSAI-certified food additive segments in India where BIS expansion concentrates qualified supply scarcity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pharmaceutical-grade thiolation as modular microreactor systems miniaturize entry requirements. Five-to-ten-year viability favors producers with documented REACH registrations and established FDA Master File libraries. Watch ECHA restriction proposal timelines as inflection signals for alternative sourcing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Sulfur | Captive feedstock supply from Gulf Coast petrochemical complexes insulates margin volatility from petroleum coke price swings. |
| Continuous Flow Microreactor Deployment | Modular thiolation systems enable pharmaceutical-grade purity consistency with reduced solvent waste and capital footprint. |
| REACH Dossier Pre-Registration | Complete toxicological documentation ahead of ECHA substance evaluation protects market access for alkyl sulfide producers. |
| FSSAI Food Additive Certification | BIS-approved diallyl disulfide production unlocks processed food formulation contracts in India's expanding flavor precursor market. |
| Integrated Analytical Service Contracts | Batch-specific impurity profiling and stability data packages capture CDMO procurement from tier-one compounders in South Korea. |
Research Methodology
A standing panel of pharmaceutical procurement directors, rubber compounder plant managers, agrochemical formulation leads, and specialty chemical distribution heads provided ongoing calibration against customs trade data, SEC chemical company filings, ECHA registration databases, and Cefic sector reports. Primary interviews with REACH compliance officers and FDA regulatory consultants cross-validated purity certification timelines and documentation requirements. Bottom-up volume modeling across thiol, sulfone, sulfoxide, and disulfide product categories triangulated with top-down macro chemical demand indicators.
Consistency checks against European petrochemical production statistics and Indian specialty chemical export data validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by molecular structure, purity grade tier, end-use industry, physical formulation, and regional production hub. CAGRs were derived from regression analysis of historical procurement patterns and forward capacity investment announcements, with pharmaceutical intermediate demand and tire industry restocking cycles as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical thiol procurement growth or accelerated ECHA restriction timelines would require recalibration. Forecasts reflect documented assumptions on feedstock sulfur availability and PLI scheme continuity. Regulatory harmonization pressures between EPA and ECHA hazard classifications represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Triallyl Isocyanurate Market