
 Conductive Plastics Market | 2026-2036
Conductive Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Plastics Market Analysis
UL-94 V-0 and aerospace-grade EMI shielding specifications is collapsing the gap between commodity thermoplastics and engineered conductive compounds. Covestro AG leverages its polycarbonate resin backbone to dominate automotive battery module housings. RTP Company anchors North American custom compounding with rapid-turn formulation services for electronics OEMs. SABIC competes through high-heat sulfone polymers targeting 5G infrastructure applications.
Conductive plastics are polymer matrices loaded with carbon black, carbon nanotubes, metal fibers, or inherently conductive polymers to achieve surface resistivity below 10^6 ohm/sq, primarily serving electromagnetic interference shielding, static dissipation, and current-carrying functions. Polymer composites lead volume consumption due to their tunable conductivity thresholds and compatibility with injection molding. Electronics applications generate the fastest expansion as device miniaturization intensifies shielding requirements. Healthcare represents a concentrated margin pool where biocompatible conductive formulations command premium positioning.
FDA biocompatibility standards and EPA reporting requirements for carbon nanotube handling shape product development pathways in the United States. REACH authorization processes in Europe restrict legacy metal-based additives, redirecting formulation investment toward carbonaceous alternatives. Stakeholders must monitor evolving semiconductor packaging standards and battery safety certifications as these specifications increasingly dictate material selection criteria for next-generation conductive compounds.
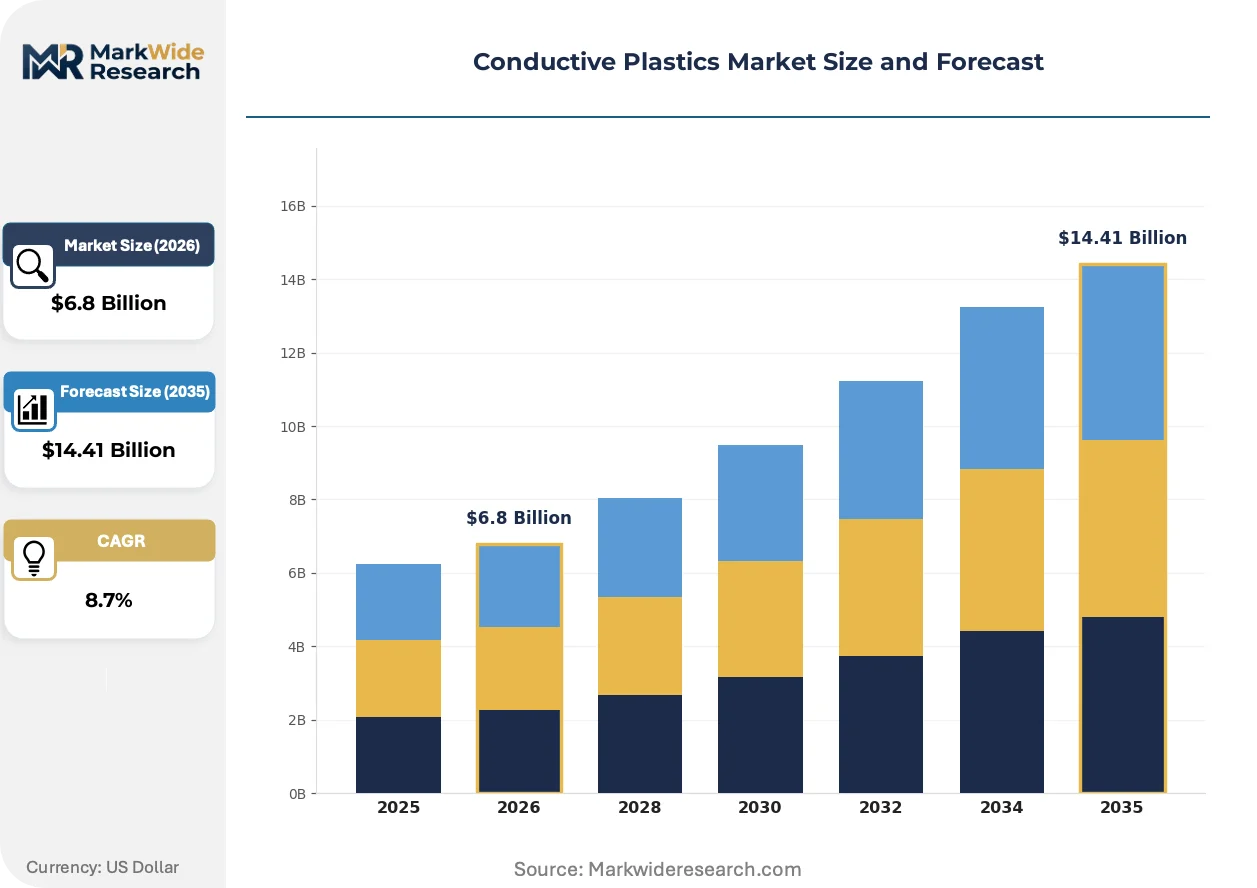
Market Dynamics
REACH authorization timelines for legacy metal-based additives are forcing compounders to rebuild formulation portfolios around carbonaceous filler systems, compressing development cycles and redrawing competitive boundaries across automotive and electronics supply chains.
Growth Catalysts
- Automotive electrification mandates:Battery housing specifications from NHTSA and China's MIIT require flame-retardant conductive compounds, pulling volume into polycarbonate and polyamide formulations.
- 5G infrastructure buildouts:FCC emission limits for base station equipment intensify demand for high-frequency EMI shielding grades in sulfone and LCP polymer families.
- Carbon nanotube cost curves:Purification yield improvements at Korean and Japanese suppliers are expanding addressable markets beyond aerospace into consumer electronics.
Market Restraints
- Silver flake price volatility:Precious metal loading in medical-grade compounds exposes compounders to London Bullion Market Association pricing swings that resist hedging.
- Single-source carbon black:Furnace-grade conductive fillers from specific Appalachian suppliers create geographic concentration risk for North American compounders.
- Permeability-performance tradeoffs:High-load carbon systems degrade impact resistance in thin-wall battery housings, limiting design freedom for EV OEMs.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor packaging and mobile assembly create first-mover positioning for EMI compounders establishing local compounding.
- Wearable medical devices:Biocompatible TPU formulations with tuned surface resistivity address unmet demand in continuous glucose monitoring patches.
- Recycled content mandates:EU Green Deal packaging regulations are opening specification windows for post-industrial conductive regrind in non-critical shielding applications.
Industry Challenges
- Compounding technician scarcity:Specialized knowledge of twin-screw extrusion for shear-sensitive nanotube dispersion commands wage premiums that mid-tier compounders struggle to match.
- Multi-certification stacking:UL-94 V-0, IEC 62368-1, and OEM-specific battery safety approvals create 18-24 month qualification timelines that freeze formulation iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Plastics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Composites, Conductive Films, Coatings, Additives Application: Electronics, Automotive, Healthcare, Aerospace End User: Manufacturers, OEMs, Research Institutions, Consumer Electronics Form: Powders, Sheets, Films, Granules |
| Companies Covered | Covestro AG, Agfa-Gevaert NV, DuPont de Nemours, Inc., RTP Company, Heraeus Materials Technology GmbH, BASF SE, SABIC, Celanese Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Plastics Market Emerging Trajectories
Formulation science is pivoting from incremental conductivity tuning toward multifunctional performance bundles that simultaneously address thermal management, mechanical integrity, and regulatory compliance in single material platforms.
Graphene nanoplatelet masterbatches are displacing conventional carbon black in automotive battery module housings where through-plane thermal conductivity above 5 W/mK is becoming baseline specification. Tier-1 suppliers in Germany and South Korea have qualified these systems for 800V architectures. The shift is compressing incumbent conductive filler suppliers into commodity pricing tiers while rewarding integrated graphene producers with specification lock-in.
ECHA's 2023 restriction proposal on nickel release in prolonged skin contact applications is redirecting wearable electronics compounders toward carbon nanotube and PEDOT:PSS alternatives. Medical device OEMs face reformulation costs exceeding two development cycles for legacy metal-filled TPU grades. The regulatory friction falls heaviest on diabetes monitoring and neurostimulation device categories where signal fidelity requirements previously favored metal loading.
Consolidated procurement desks at major EV battery manufacturers are unbundling material specification from molding service contracts, forcing compounders to prove standalone value in conductivity consistency and lot-to-lot variance control. This purchasing rationalization is most visible in China's Yangtze River Delta cluster where CATL and BYD procurement teams have reduced qualified supplier pools by half since 2022. Surviving compounders now compete on statistical process control documentation rather than historical relationship depth.
Conductive Plastics Market Segmentation
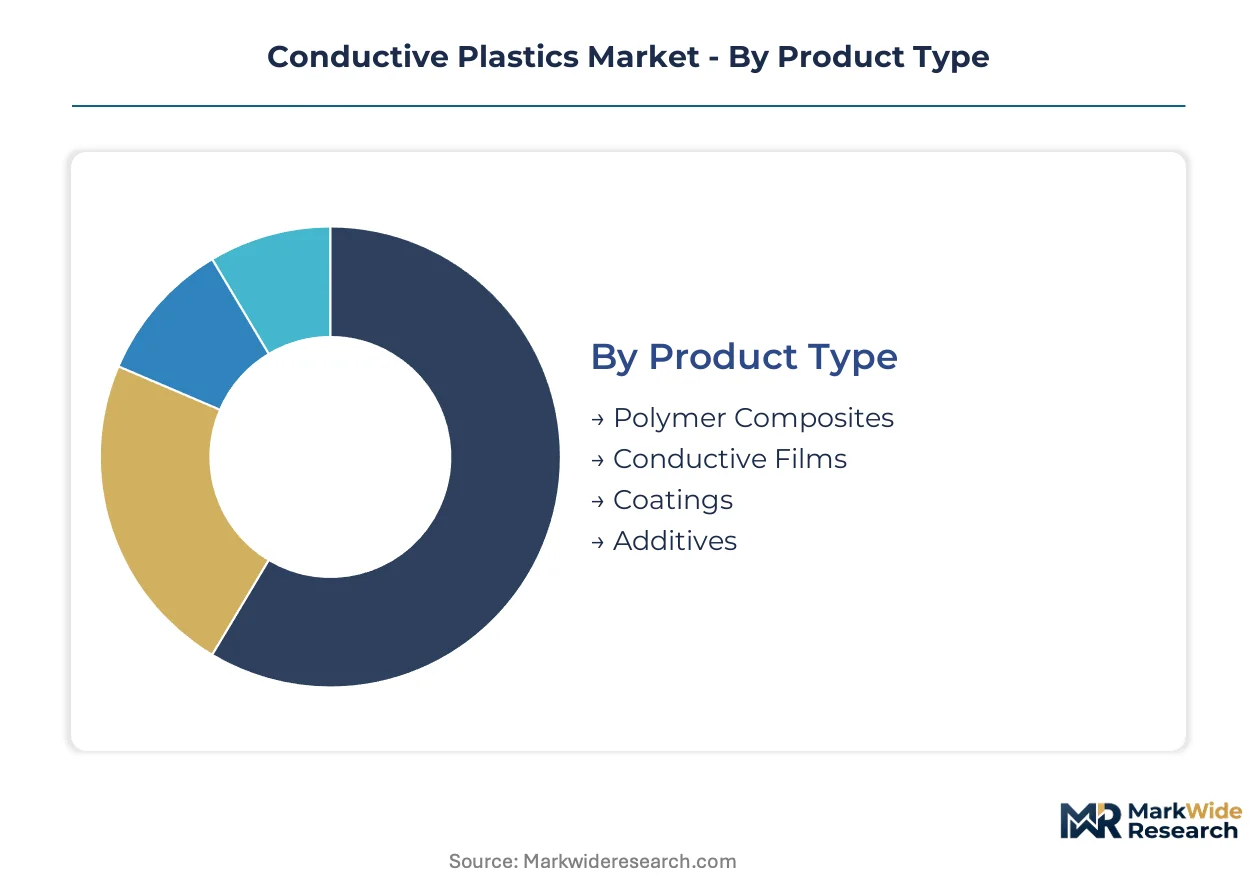
Segmentation in conductive plastics reveals where formulation investments concentrate and which material platforms face displacement from emerging filler technologies. Understanding these divides exposes where compounders can defend specification lock-in versus where margin compression threatens established positions.
Product Type:
Polymer composites face the most acute substitution pressure as graphene nanoplatelet systems displace carbon black in premium automotive and 5G applications, forcing legacy compounders to rebuild masterbatch portfolios or retreat to commodity tiers.
- Polymer Composites:Carbon black, carbon nanotube, or metal fiber loaded thermoplastics achieving surface resistivity below 10^6 ohm/sq through twin-screw compounding. Demand concentrates in China's Yangtze River Delta battery housing cluster where CATL and BYD procurement teams enforce tight lot-to-lot variance specifications.
- Conductive Films:Thin-gauge extruded or cast films with vapor-deposited or intrinsically conductive polymer layers for flexible circuit substrates and EMI gaskets. Japanese and Korean electronics OEMs drive consumption for foldable display shielding where mechanical cycling durability determines qualification.
- Coatings:Sprayable or dip-coated conductive layers applied to non-conductive substrates for localized shielding or static dissipation. Aerospace wire harness applications in Germany and France specify these for weight reduction versus solid metal braid.
- Additives:Masterbatch concentrates and dispersed filler systems sold to downstream compounders for let-down into final formulations. Korean carbon nanotube purification yield improvements are expanding this segment's addressable market beyond aerospace into consumer electronics.
Polymer composites retain volume leadership; conductive films hold the steepest expansion curve.
Application:
Cost tier stratification separates specification-intensive automotive and aerospace grades from price-sensitive consumer electronics volumes, with healthcare occupying a concentrated premium position where biocompatibility certifications justify substantial formulation premiums.
- Electronics:EMI shielding enclosures, static-dissipative packaging, and antenna substrates for smartphones, laptops, and base station equipment. FCC emission limits for 5G infrastructure intensify demand for high-frequency shielding grades in sulfone and LCP polymer families.
- Automotive:Battery module housings, charging connector shells, and sensor shields requiring combined flame retardancy and conductivity. NHTSA and China's MIIT specifications pull volume into polycarbonate and polyamide formulations for 800V architectures.
- Healthcare:Biocompatible electrodes, neurostimulation housings, and continuous glucose monitoring patches where FDA and EMA device regulations govern material selection. ECHA's nickel release restrictions are redirecting wearable compounders toward carbon nanotube and PEDOT:PSS alternatives.
- Aerospace:Lightweight EMI shielding for avionics, satellite components, and wire harnesses where FAA certification requirements and specific gravity targets dominate material selection. German and South Korean tier-1 suppliers have qualified graphene systems for satellite applications.
Electronics generates the highest absolute demand; healthcare commands the most favorable margin structure.
End User:
Procurement consolidation among large OEMs is unbundling material specification from molding services, forcing compounders to compete on statistical process control documentation rather than historical relationship depth.
- Manufacturers:Tier-1 and tier-2 parts producers purchasing conductive compounds for injection molding and extrusion of finished components. Consolidated procurement desks at major EV battery manufacturers have reduced qualified supplier pools by half since 2022.
- OEMs:Original equipment manufacturers specifying conductive plastics directly for captive production or vendor-managed inventory arrangements. Apple's supplier responsibility requirements and Samsung's Eco-Partner certification create qualification barriers for compounders seeking smartphone shielding business.
- Research Institutions:Universities and national laboratories sourcing small-lot experimental grades for next-generation filler and polymer matrix development. MIT, Fraunhofer, and Tsinghua University programs drive early-stage graphene and carbon nanotube formulation innovation.
- Consumer Electronics:Brands and contract assemblers specifying shielding materials for finished devices. India's PLI scheme incentives for semiconductor packaging and mobile assembly create first-mover positioning for EMI compounders establishing local compounding.
Manufacturers absorb the greatest compound volume; OEMs exert the strongest pricing leverage through consolidated procurement.
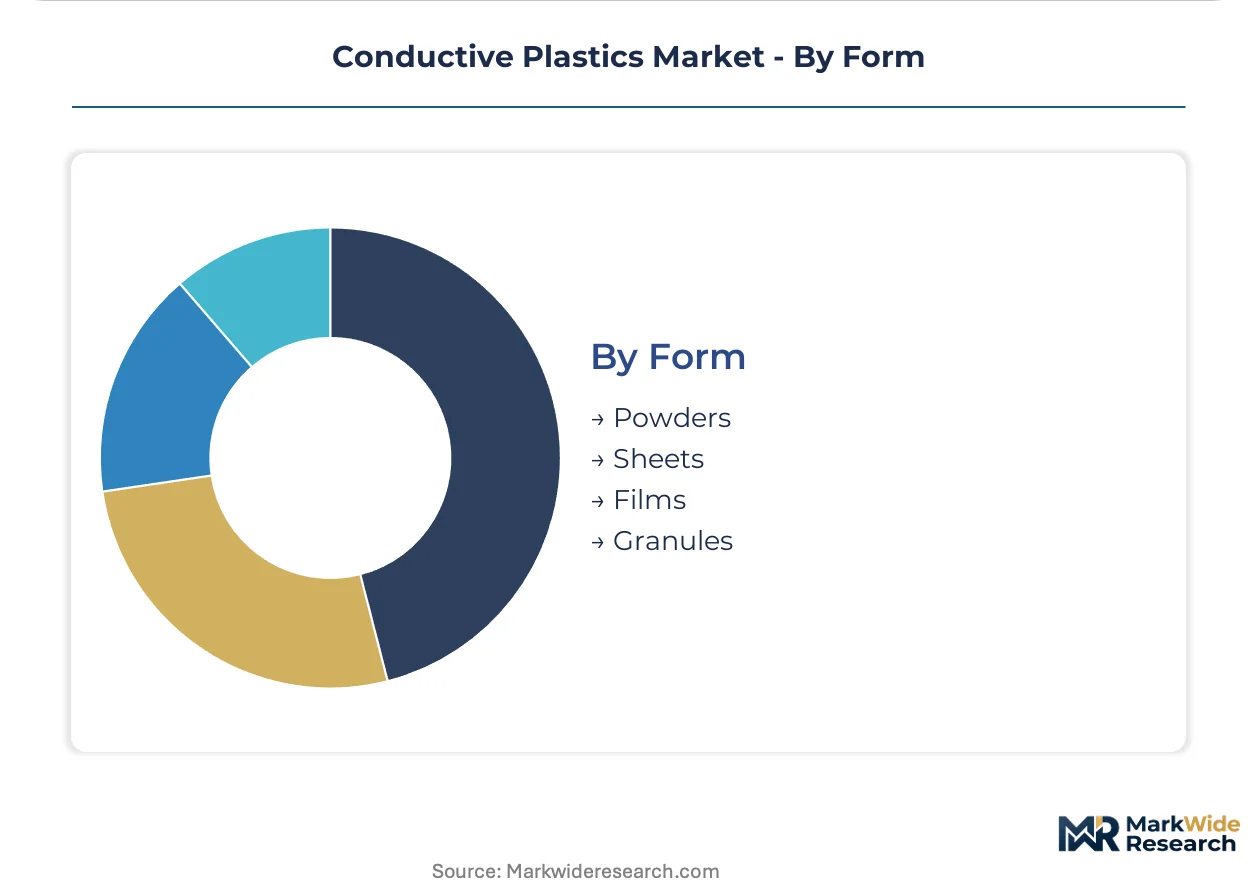
Form:
Supply concentration in Appalachian furnace-grade carbon black creates geographic risk for North American compounders, while Asian granule and film production scales to serve electronics manufacturing clusters.
- Powders:Fine-particulate conductive fillers and compounded resins for dry blending, compression molding, and coating applications. Powder handling EPA reporting requirements for carbon nanotubes shape product development pathways in the United States.
- Sheets:Extruded flat stock for thermoformed shielding enclosures, static-dissipative workstation surfaces, and battery housing structural layers. German automotive suppliers specify these for EV battery module separators requiring combined electrical isolation and thermal management.
- Films:Thin-gauge rolled goods for flexible circuits, adhesive-backed EMI gaskets, and display shielding laminates. South Korean and Japanese electronics supply chains dominate consumption for foldable device applications.
- Granules:Pelletized compounds for injection molding and extrusion, the dominant delivery format for high-volume automotive and electronics production. Chinese domestic compounding capacity expansion is reducing import dependence for standard polycarbonate and polyamide conductive grades.
Granules dominate shipment volumes; films capture the most rapid demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese battery manufacturers enforce the tightest lot-to-lot variance specifications, compressing margins for compounders serving Yangtze River Delta clusters. German automotive suppliers absorb premium pricing for graphene-enabled thermal management grades. North American electronics OEMs prioritize rapid-turn formulation services over unit cost minimization.
China
CATL and BYD procurement teams have halved qualified supplier pools since 2022, forcing compounders to compete on statistical process control documentation. MIIT battery safety specifications for 800V architectures pull volume into flame-retardant polycarbonate and polyamide formulations. Domestic compounding capacity expansion around Suzhou and Ningbo is reducing import dependence for standard conductive grades.
Germany
Automotive tier-1 suppliers specify graphene nanoplatelet masterbatches for EV battery module housings requiring through-plane thermal conductivity above 5 W/mK. ECHA's 2023 nickel release restrictions redirect wearable electronics compounders toward carbon nanotube alternatives. The Stuttgart-Munich corridor hosts qualification programs for sulfone polymer families targeting 5G infrastructure shielding.
United States
FCC emission limits for 5G base station equipment intensify demand for high-frequency EMI shielding grades. FDA biocompatibility standards and EPA carbon nanotube handling requirements shape product development pathways for medical-grade formulations. RTP Company anchors North American custom compounding with rapid-turn services for electronics OEMs concentrated in Minnesota and California.
South Korea
Purification yield improvements at domestic carbon nanotube suppliers are expanding addressable markets beyond aerospace into consumer electronics. Samsung's Eco-Partner certification creates qualification barriers for compounders seeking smartphone shielding business. Busan-Ulsan industrial complexes concentrate film production for foldable display applications where mechanical cycling durability determines specification.
India
PLI scheme incentives for semiconductor packaging and mobile assembly create first-mover positioning for EMI compounders establishing local compounding. BIS standards for electronics manufacturing are converging with IEC frameworks, accelerating qualification timelines for imported masterbatches. Tamil Nadu and Karnataka clusters are emerging as preferred locations for contract manufacturers serving Apple and Samsung supply chains.
Conductive Plastics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers dominating high-performance automotive grades while independent compounders capture electronics customization volumes. The market structure concentrates around three strategic tiers: integrated chemical conglomerates with captive polymer backbones, specialized independent compounders with rapid-turn formulation capabilities, and regional masterbatch producers serving price-sensitive packaging applications. Dominant competitive moves include backward integration into carbon nanotube purification and geographic expansion into India and Southeast Asia to capture electronics manufacturing migration.
Among integrated chemical conglomerates, Covestro AG and SABIC occupy positions defined by resin backbone control and high-heat polymer families respectively. RTP Company exemplifies the independent compounder archetype with rapid-turn formulation services. These three anchors illustrate how competitive positioning splits between specification-intensive automotive qualification and speed-to-market electronics customization.
| Leading Market Players |
|---|
| Covestro AG |
| Agfa-Gevaert NV |
| DuPont de Nemours, Inc. |
| RTP Company |
| Heraeus Materials Technology GmbH |
| BASF SE |
| SABIC |
| Celanese Corporation |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Graphene nanoplatelet displacement of carbon black in automotive battery housings simultaneously redraws supply geography toward Korean and German tier-1 suppliers while compressing legacy filler producers into commodity pricing tiers. This substitution dynamic concentrates pricing power with integrated graphene producers who capture specification lock-in, while compounders dependent on Appalachian furnace-grade carbon black face margin compression from buyer consolidation.
Pricing Analysis
After-sales technical service and reformulation support drive lifetime value in conductive plastics, with compounders bundling rapid-turn customization into long-term offtake contracts. Pricing stratifies across automotive qualification-grade, electronics rapid-turn, and packaging economy tiers, with differentiation resting on UL-94 certification level and lot-to-lot variance documentation. Cost compression in standard polycarbonate and polyamide grades is intensifying because Chinese domestic compounding capacity expansion has reduced import dependence. Electronics OEMs concentrated in Minnesota and California exhibit the lowest price sensitivity, prioritizing speed-to-market over unit cost minimization.
Supply Chain Analysis
Inventory buffers for carbon nanotube masterbatches have tightened as Korean purification yield improvements expand demand beyond aerospace into consumer electronics. Raw material sourcing draws from Appalachian carbon black suppliers, Korean carbon nanotube purifiers, and German graphene nanoplatelet producers. Single-source vulnerability concentrates in furnace-grade conductive fillers from specific Appalachian suppliers, creating geographic concentration risk for North American compounders. Distribution runs through qualified supplier programs at CATL, BYD, and Apple procurement desks that enforce statistical process control documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated procurement desks at major EV battery manufacturers, with CATL and BYD having halved qualified supplier pools since 2022. This concentration forces compounders to compete on documentation rather than relationship depth.
For Market Incumbents: Consolidate formulation expertise around carbon nanotube dispersion and graphene masterbatch production to defend against Korean and Japanese supplier expansion. Backward integration into carbon nanotube purification or captive graphene sourcing secures margin position as REACH restrictions on metal-based additives accelerate. Priority certification investment in MIIT battery safety and UL-94 V-0 specifications locks out mid-tier compounders lacking 18-24 month qualification timelines.
For New Entrants and Emerging Players: Rapid-turn formulation services for wearable medical devices represent a service-layer gap where incumbents under-serve, with ECHA nickel release restrictions forcing reformulation cycles that legacy metal-filled TPU suppliers struggle to meet. India's PLI scheme for semiconductor packaging offers the most penetrable geography, with Tamil Nadu and Karnataka clusters emerging as contract manufacturing hubs. Go-to-market through BIS-converged IEC qualification accelerates timeline versus import-dependent masterbatch routes.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed independent compounders possessing rapid-turn capabilities but lacking resin backbone control. Long-term viability hinges on 5-10 year positioning toward multifunctional thermal-conductive-mechanical platforms rather than single-attribute fillers. Watch carbon nanotube cost curves as the inflection signal—purification yield improvements that expand addressable markets beyond aerospace indicate consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Nanotube Purification | Korean yield improvements are expanding addressable markets beyond aerospace into consumer electronics. |
| MIIT Battery Safety Certification Investment | China's 800V architecture specifications pull volume into flame-retardant polycarbonate formulations. |
| India PLI Scheme Local Compounding | Tamil Nadu and Karnataka clusters create first-mover positioning for semiconductor packaging supply. |
| Graphene Nanoplatelet Masterbatch Scale-Up | German tier-1 suppliers have qualified these systems for EV battery module thermal management. |
| Wearable Medical Device Formulation Services | ECHA nickel release restrictions redirect compounders toward carbon nanotube and PEDOT:PSS alternatives. |
Methodological Framework
Initial hypotheses were tested against primary input from compounder technical directors, OEM procurement managers at CATL and BYD, automotive tier-1 supplier engineers, and carbon nanotube purification specialists, then refined against secondary validation. Primary fieldwork combined structured interviews with downstream electronics and automotive manufacturers, distribution channel partners in China and Germany, and regulatory affairs leads navigating REACH and FDA pathways. Secondary sources drew from SEC filings of integrated chemical conglomerates, MIIT battery safety documentation, ECHA restriction proposals, and customs data tracking carbon black and graphene trade flows. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Variance decomposition separated volume growth from price-mix effects across product type, application, and regional production hub dimensions. The analytical framework modeled polymer composites, conductive films, coatings, and additives as distinct segments with divergent substitution dynamics. CAGRs derived from regression against automotive electrification buildout rates, 5G infrastructure deployment schedules, and carbon nanotube cost curve trajectories. Industry-specific forecast inputs included NHTSA and MIIT battery housing specifications, FCC emission limits for base station equipment, and EMA biocompatibility certification timelines.
Underlying assumptions cover sustained automotive electrification mandates, REACH authorization timelines for metal-based additives, and carbon nanotube purification yield improvements, with deviation risk concentrated in silver flake price volatility and single-source carbon black supply disruption. Forecasts reflect these assumptions without contingency for abrupt regulatory reversal or raw material sourcing shocks. Revision becomes warranted when Chinese domestic compounding capacity expansion crosses thresholds that eliminate import dependence for standard grades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Talc Alternatives Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Elastic Films Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Absorbent Booms and Socks Market