
 Saudi Arabia Collagen Market | 2026-2036
Saudi Arabia Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Collagen Market Analytics
Precision extraction technology is fragmenting collagen manufacturing into species-specific and application-dedicated production lines across Saudi Arabia. Darling Ingredients Inc. anchors its position through backward integration into halal-certified raw material sourcing. Gelita AG competes on pharmaceutical-grade gelatin purity for medical device applications. Rousselot specializes in hydrolyzed collagen peptides tailored to nutraceutical formulations.
Collagen comprises triple-helix protein structures extracted from bovine hide, porcine skin, or marine organisms through acid or alkaline hydrolysis, yielding molecular weights from 50 to 300 kDa depending on processing intensity. Its primary commercial purpose spans gelling, emulsifying, and film-forming functions in food matrices, plus tissue scaffolding in biomedical applications. Gelatin occupies the mature volume base in Saudi food manufacturing, while collagen peptides capture expanding margin pools in dietary supplements. Native collagen retains niche positioning within medical devices due to higher biocompatibility thresholds.
SFDA halal certification requirements and Saudi Food and Drug Authority good manufacturing practice standards govern import准入 and domestic production compliance, elevating barriers for uncertified suppliers. The Saudi Standards, Metrology and Quality Organization (SASO) technical regulations on food additives further constrain formulation flexibility. Stakeholders must monitor evolving halal traceability mandates and decide between captive slaughterhouse partnerships versus third-party certified imports.
Market Dynamics
SFDA halal certification mandates are restructuring Saudi Arabia's collagen supply chains, forcing manufacturers to abandon porcine sources and rebuild procurement networks around bovine and marine alternatives. This regulatory pivot concentrates competitive advantage among suppliers with captive halal-certified slaughterhouse partnerships.
Growth Catalysts
- Food fortification mandates:SASO technical regulations on functional food additives are accelerating collagen peptide incorporation into dairy and beverage formulations across Riyadh and Jeddah manufacturing clusters.
- Nutraceuticals demand:Health-conscious consumers in urban centers are prioritizing dietary supplements containing hydrolyzed collagen for joint and skin health applications.
- Precision extraction technology:Species-specific production lines are enabling pharmaceutical-grade purity thresholds that unlock medical device contract manufacturing opportunities.
Market Restraints
- Halal certification costs:SFDA compliance expenses and third-party audit requirements impose disproportionate burdens on small-scale importers lacking backward integration into certified raw material sourcing.
- Marine supply concentration:Red Sea fishing quotas and seasonal variability constrain consistent marine collagen availability, creating input volatility for peptide manufacturers.
- Substitution by plant proteins:Pea and rice protein isolates are capturing share in food fortification applications where gelling functionality is secondary to nutritional labeling claims.
Strategic Opportunities
- Eastern Province manufacturing:Underdeveloped industrial zones near Dammam offer land and utility cost advantages for greenfield collagen extraction facilities serving Gulf Cooperation Council export markets.
- Biomedical scaffolding:Native collagen's superior biocompatibility positions Saudi manufacturers to capture medical device outsourcing contracts from European orthopedic implant producers.
- Direct-to-consumer channels:E-commerce platforms and pharmacy chains are collapsing traditional distributor margins, enabling branded peptide producers to capture value previously lost to intermediaries.
Industry Challenges
- Halal traceability expertise:Shortage of supply chain auditors qualified in Islamic slaughter certification and blockchain documentation systems delays SFDA approval timelines.
- Pharmaceutical-grade capex:Cleanroom infrastructure and GMP-compliant hydrolysis equipment require capital commitments that strain mid-tier domestic processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Collagen Market |
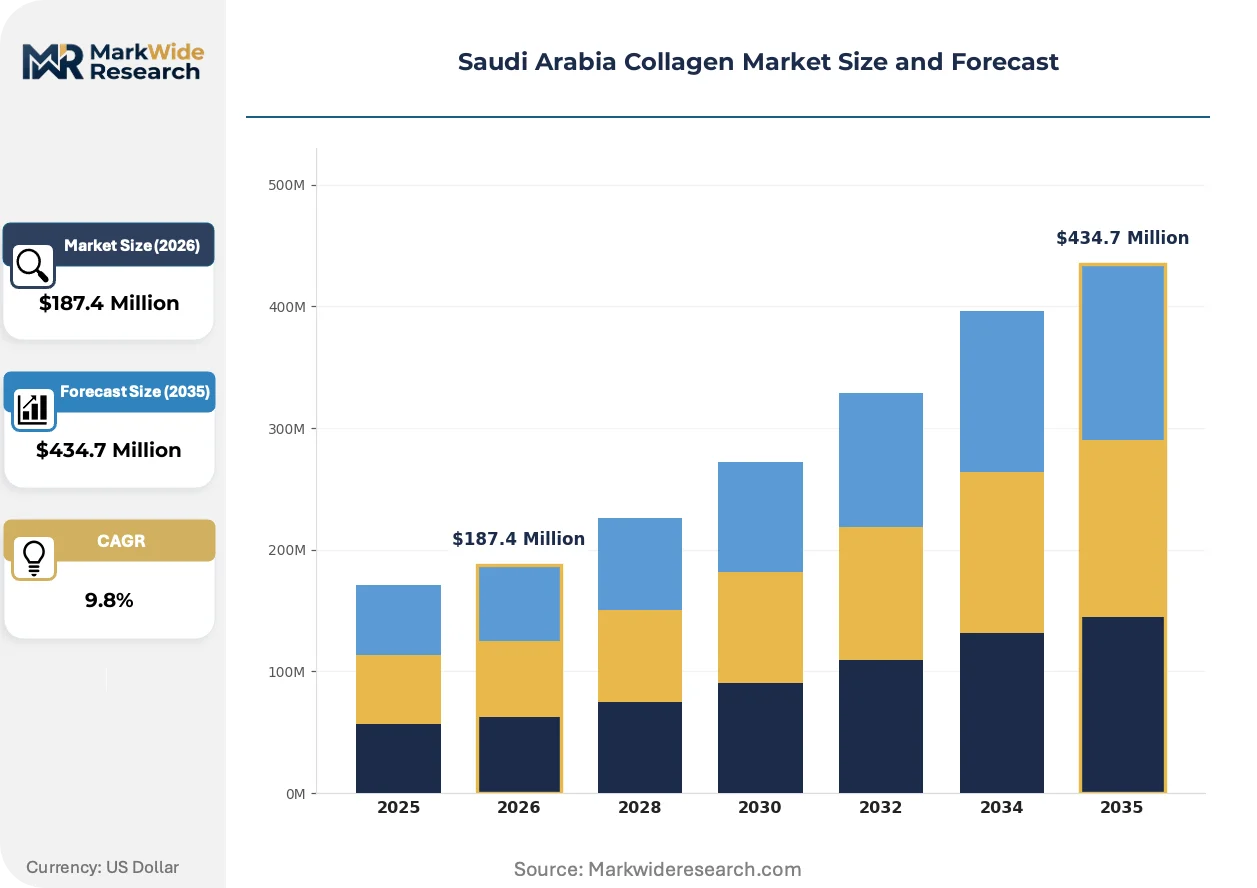
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Hydrolyzed Collagen, Collagen Peptides, Native Collagen End User: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Application: Skin Care, Dietary Supplements, Medical Devices, Food Fortification Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | PB Gelatins, Darling Ingredients Inc., Rousselot, Italgelatine S.p.A, Ewald-Gelatine GmbH, Gelita AG, Weishardt Group, GELNEX, Nitta Gelatin Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Collagen Market Evolving Landscape
Enzymatic hydrolysis protocols and species-specific extraction systems are fragmenting production into dedicated lines for food, nutraceutical, and biomedical grades. This technological specialization is compressing batch cycle times and enabling purity premiums.
Membrane filtration technology is rendering obsolete traditional acid-alkali hydrolysis methods for high-molecular-weight collagen extraction. Pharmaceutical contract manufacturers in Jeddah's industrial corridor are adopting ceramic membrane systems at accelerating rates. The shift is compressing capital recovery periods from five-year to three-year horizons for premium-grade producers.
SFDA tightening of halal traceability requirements is mandating blockchain-verified slaughterhouse documentation for all imported bovine raw materials. The regulation is disqualifying uncertified European and South American suppliers from Saudi import eligibility. Domestic manufacturers with captive halal-certified sourcing are consolidating market position as gatekeepers for compliant supply.
Consumer preference for clean-label supplements is rotating demand toward single-ingredient collagen peptides and away from multi-component formulations. Pharmacy chains in Riyadh are expanding dedicated collagen shelving and reducing blended supplement facings. The behavioral shift favors transparent sourcing narratives and compresses margins for complex formulation marketers.
Saudi Arabia Collagen Market Segmentation
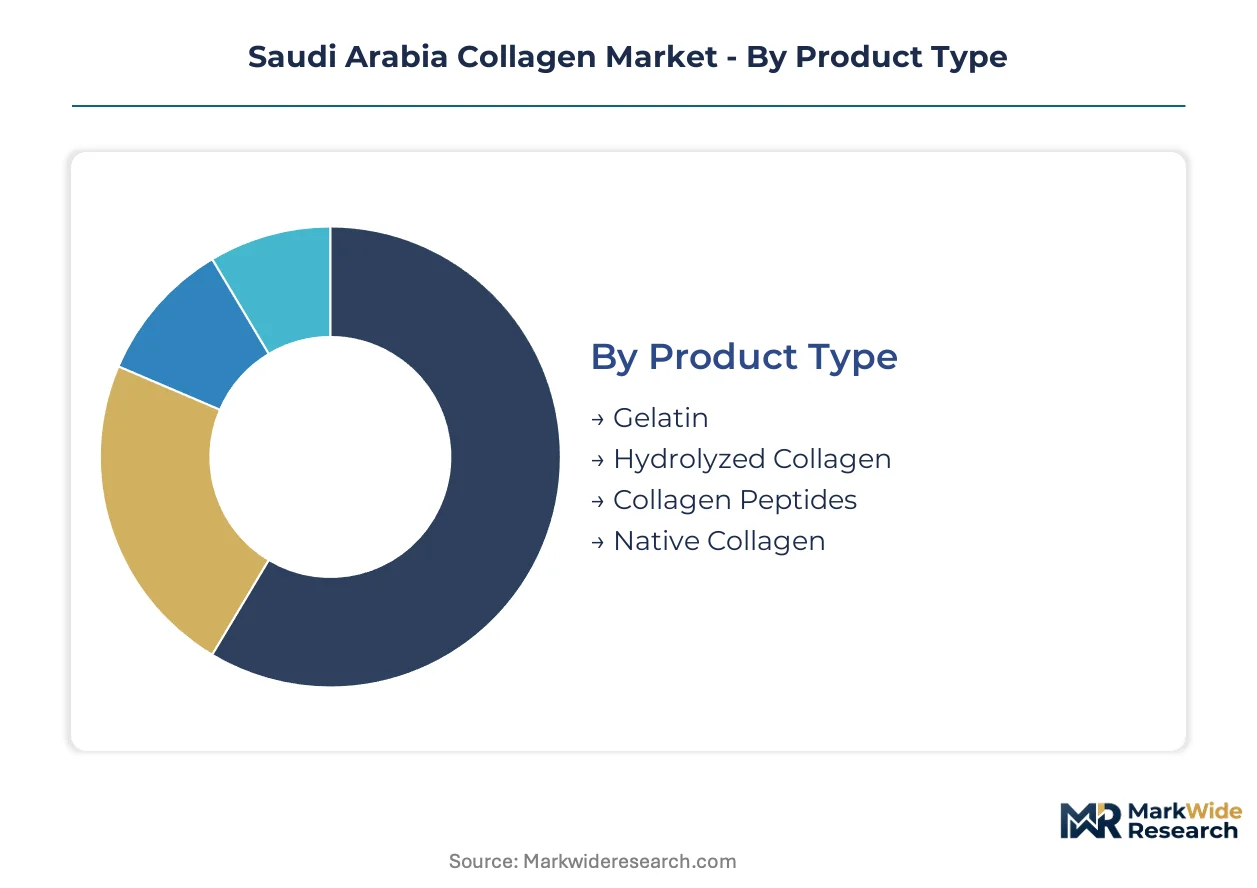
Segmentation in Saudi Arabia's collagen market reveals divergent procurement cycles and margin structures across product grades and end-use applications. Understanding these velocity differentials enables suppliers to align inventory positioning with demand rhythms across Riyadh and Jeddah consumption clusters.
Product Type:
Gelatin turns inventory fastest through industrial food manufacturing contracts, while native collagen sits longest in biomedical validation pipelines.
- Hydrolyzed Collagen:Low-molecular-weight peptides processed through enzymatic hydrolysis achieve rapid dissolution in beverage matrices. Health-conscious consumers in Riyadh's pharmacy chains are driving repeat purchase velocity for joint health formulations, though SFDA halal certification documentation adds 30-45 days to procurement lead times.
- Gelatin:Denatured collagen with gelling properties from 50-300 kDa molecular weight ranges dominates dairy and confectionery manufacturing. Jeddah's food processing corridors consume bulk volumes for dessert and yogurt applications, constrained by seasonal slaughterhouse availability for halal-certified bovine hides.
- Collagen Peptides:Bioactive fractions optimized for nutraceutical bioavailability command formulation premiums in dietary supplement SKUs.
- Native Collagen:Triple-helix structures preserved through non-denaturing extraction serve orthopedic scaffold manufacturing with extended qualification cycles.
Gelatin dominates installed base. Hydrolyzed collagen is where expansion concentrates.
End User:
Cost tier stratification separates commodity food manufacturers from premium pharmaceutical contract developers.
- Food & Beverage:Industrial buyers in Riyadh and Jeddah manufacturing zones procure gelatin in metric-ton volumes for dairy fortification and confectionery applications. SASO technical regulations on functional food additives mandate collagen peptide labeling standards that elevate formulation compliance costs for mid-tier processors.
- Nutraceuticals:Direct-to-consumer brands and pharmacy chains across the Kingdom's urban centers stock hydrolyzed collagen powders and capsules targeting skin elasticity and joint mobility claims. Clean-label preferences are compressing multi-ingredient formulations in favor of single-source peptide positioning.
- Cosmetics:Topical collagen formulations in premium skincare lines utilize marine-sourced peptides for anti-aging positioning.
- Pharmaceuticals:Medical device manufacturers and drug formulators require pharmaceutical-grade gelatin for capsule shells and wound dressing substrates.
Food & Beverage anchors volume throughput. Nutraceuticals is climbing the fastest in margin contribution.
Application:
Volume concentration in food fortification contrasts with value concentration in biomedical scaffolding.
- Food Fortification:Collagen peptide incorporation into dairy beverages and baked goods accelerates across Saudi manufacturing facilities responding to SASO functional additive regulations. Urban retail channels in Riyadh display fortified yogurt and protein-enriched bread categories with prominent collagen callouts.
- Dietary Supplements:Pharmacy chains and e-commerce platforms stock hydrolyzed collagen powders, capsules, and ready-to-drink formats targeting consumers prioritizing joint health and dermal elasticity. The segment benefits from direct-to-consumer margin capture bypassing traditional distributor networks.
- Skin Care:Cosmetic formulations leverage marine collagen peptides for topical anti-aging claims in premium retail positioning.
- Medical Devices:Native collagen scaffolds for orthopedic and wound healing applications require pharmaceutical-grade purity thresholds and extended regulatory validation.
Food Fortification represents the dominant installed application base. Dietary Supplements is where expansion concentrates.
Distribution Channel:
Customer type fragmentation separates institutional procurement from individual purchase behavior.
- Online Retail:E-commerce platforms collapse traditional distributor margins and enable branded peptide producers to capture direct consumer relationships. Riyadh and Jeddah digital commerce penetration supports subscription-based collagen replenishment models with recurring revenue structures.
- Supermarkets:Mass-market gelatin and basic collagen supplements occupy shelf space in hypermarket chains across the Kingdom's retail corridors.
- Specialty Stores:Premium nutraceutical retailers and pharmacy chains curate pharmaceutical-grade peptide assortments with transparent sourcing narratives.
- Direct Sales:Industrial food manufacturers and pharmaceutical contract developers procure bulk gelatin and native collagen through negotiated supply agreements with certified slaughterhouse partners.
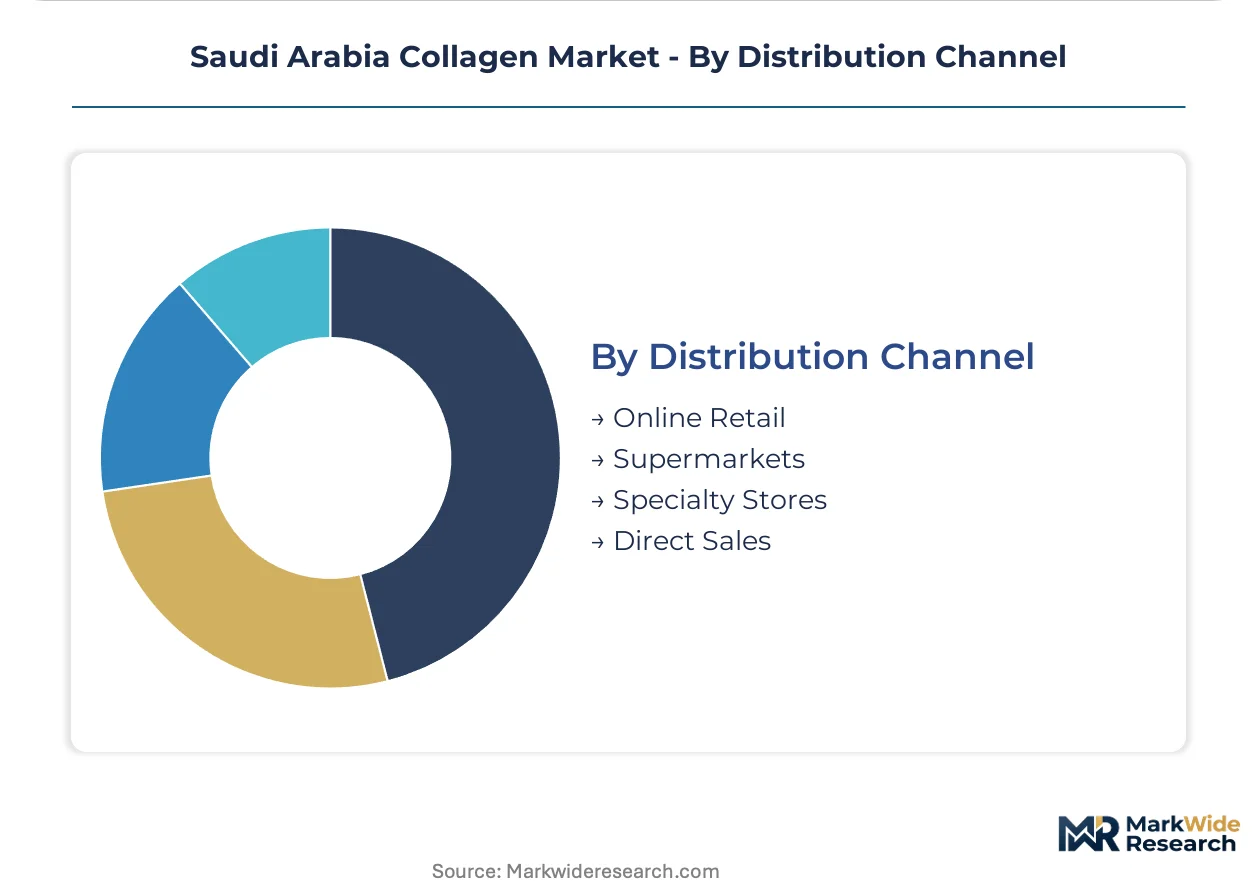
Supermarkets dominate installed base. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian bovine hide exporters supply halal-certified raw materials to Saudi processors under SFDA-mandated blockchain traceability protocols. Marine collagen flows from Southeast Asian fishing cooperatives through Jeddah's port infrastructure.
Riyadh
Pharmacy chains and nutraceutical distributors in Riyadh drive hydrolyzed collagen peptide demand for joint health formulations. SFDA halal certification requirements redirect procurement toward bovine and marine sources with verified slaughterhouse documentation. The King Salman Park development zone attracts greenfield extraction facilities serving domestic and GCC export markets.
Eastern Province
Petrochemical infrastructure in Dammam and Jubail supports industrial-scale gelatin production for food manufacturing contracts. SASO technical regulations on functional food additives mandate collagen peptide labeling standards that elevate compliance costs for mid-tier processors. The King Fahd Industrial City hosts expanding dairy fortification facilities incorporating collagen into yogurt and beverage formulations.
Western Region
Jeddah's Red Sea port handles marine collagen imports from Indonesian and Malaysian suppliers facing seasonal fishing quota constraints. The city's food processing corridor consumes bulk gelatin volumes for confectionery and dessert applications. King Abdullah Economic City attracts pharmaceutical-grade collagen investments targeting medical device scaffolding contracts.
NEOM Northwest
The NEOM development zone prioritizes biotech manufacturing clusters with pharmaceutical-grade purity infrastructure. SFDA good manufacturing practice standards govern planned collagen extraction facilities targeting European orthopedic implant outsourcing. The linear city's renewable energy profile supports enzymatic hydrolysis operations with lower carbon intensity benchmarks.
Saudi Arabia Collagen Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Backward-integrated suppliers with captive halal-certified slaughterhouse partnerships command premium positioning in bovine-sourced segments. Marine collagen specialists compete on traceability narratives and Red Sea proximity. Pharmaceutical-grade purity thresholds separate medical device suppliers from commodity food gelatin producers. Dominant competitive moves include strategic partnerships with certified raw material sources and capacity expansion in Eastern Province industrial zones.
Among European gelatin specialists, PB Gelatins, Italgelatine S.p.A, and Ewald-Gelatine GmbH exemplify the heritage-tier archetype with long-established halal certification protocols. These entities occupy positions anchored in multi-generational processing expertise and regulatory compliance depth. Their geographic concentration in traditional manufacturing regions contrasts with the supply-chain control orientation of North American and Asian competitors.
| Leading Market Players |
|---|
| PB Gelatins |
| Darling Ingredients Inc. |
| Rousselot |
| Italgelatine S.p.A |
| Ewald-Gelatine GmbH |
| Gelita AG |
| Weishardt Group |
| GELNEX |
| Nitta Gelatin Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Saudi Arabia's pharmaceutical-grade collagen segment is compressing batch premiums and forcing buyers into longer contract commitments. Eastern Province manufacturers exploit this tightness to extend payment terms and secure captive slaughterhouse partnerships before competitors can qualify alternative sources.
Pricing Analysis
Membrane filtration technology commands a 40-60% premium over acid-alkali hydrolysis systems due to shorter capital recovery cycles and higher purity yields. Pharmaceutical-grade gelatin draws from ISO-certified cleanroom infrastructure and SFDA halal documentation depth, while food-grade gelatin competes on volume scale and seasonal bovine hide availability. Cost compression in commodity gelatin runs through Jeddah's food processing corridor as Brazilian hide exporters consolidate shipping contracts. Industrial dairy manufacturers exhibit highest price sensitivity, whereas orthopedic scaffold developers accept premium positioning for native collagen biocompatibility.
Supply Chain Analysis
Extended payment terms from Saudi processors are restructuring supplier relationships with Brazilian hide exporters and Indonesian fishing cooperatives. Raw material flows draw from halal-certified Brazilian slaughterhouses, Red Sea marine cooperatives, and captive Eastern Province bovine operations. Dependency on seasonal fishing quotas and blockchain-verified slaughterhouse documentation creates input volatility for peptide manufacturers. Distribution runs through Jeddah's port infrastructure for marine imports and Dammam's industrial corridor for domestic food manufacturing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea and rice protein isolates threaten collagen's position in food fortification applications where gelling functionality is secondary to nutritional labeling claims. Incumbents must defend against this substitution through certification depth and application-specific purity positioning.
For Market Incumbents: Harden halal traceability infrastructure through captive slaughterhouse partnerships in the Eastern Province before SFDA mandates tighten further. Deepen enzymatic hydrolysis capabilities to compress batch cycle times and defend margin pools against commodity gelatin price erosion from Brazilian import competition.
For New Entrants and Emerging Players: Build out pharmaceutical-grade extraction capacity in NEOM's biotech manufacturing clusters to capture European orthopedic implant outsourcing contracts. Target the native collagen scaffold segment where qualification cycles and purity thresholds create defensive moats against established food-grade processors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because SFDA halal certification requirements are consolidating supply chain gatekeeper positions among backward-integrated domestic manufacturers. Watch for blockchain traceability mandate acceleration as the signal that certification compliance costs will disqualify uncertified importers.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Investment | SFDA compliance depth anchors competitive positioning against uncertified Brazilian and European suppliers. |
| Membrane Filtration Adoption | Ceramic systems in Jeddah's pharmaceutical corridor compress capital recovery from five-year to three-year horizons. |
| Captive Slaughterhouse Partnership | Eastern Province backward integration secures bovine hide supply ahead of seasonal availability constraints. |
| Direct-to-Consumer Channel Buildout | E-commerce platforms in Riyadh collapse distributor margins and enable subscription-based peptide replenishment models. |
| Pharmaceutical-Grade Capacity Expansion | NEOM biotech clusters target European medical device outsourcing with GMP-compliant hydrolysis infrastructure. |
Research Methodology
A spread of perspectives from SFDA regulatory affairs officers, halal certification auditors, pharmaceutical contract manufacturers, and Jeddah food processing procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with supply chain stakeholders and secondary validation through SASO technical regulation filings, SFDA import documentation databases, and Saudi customs trade records. Bottom-up segment sizing across hydrolyzed collagen, gelatin, and native collagen grades triangulated against top-down GDP elasticity models for nutraceutical consumption.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by product type, end-use application, and distribution channel. CAGRs derived from elasticity-adjusted consumption curves incorporated pharmaceutical-grade purity premiums, halal certification compliance costs, and enzymatic hydrolysis technology adoption rates as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Brazilian hide exporters or accelerated blockchain traceability mandates by SFDA would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Compounds Market
Specialty Compounds
Hypalon Market