
 Global Antifreeze Proteins Market | 2026-2036
Global Antifreeze Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antifreeze Proteins Market Analysis
Marine biotechnology extraction capacity in North Atlantic fisheries is decoupling from traditional seasonal harvesting constraints. Sirona Biochem leverages synthetic biology platforms to sustain non-seasonal glycoprotein output. Kaneka Corporation anchors Japanese supply through precision fermentation infrastructure. Unilever competes via captive demand from its own ice-cream and frozen-food portfolios.
Antifreeze proteins comprise a class of ice-binding polypeptides, typically 2.5-14 kDa in molecular weight, that depress the freezing point of bodily fluids without significantly altering osmotic pressure. These biomolecules function by adsorbing to ice crystal surfaces and inhibiting recrystallization during thermal cycling, a mechanism critical for cryopreservation of living tissues and extension of frozen-food shelf stability. Fish-sourced antifreeze glycoproteins dominate current commercial supply due to established extraction protocols from cold-water species, while plant-derived variants represent the fastest-expanding category as agricultural biotechnology firms engineer transgenic expression systems. Biotechnology applications command the deepest margin pools because pharmaceutical-grade purity requirements create certification barriers that synthetic-source competitors struggle to clear.
FDA biologics guidance, EMA's Good Manufacturing Practice standards for active pharmaceutical ingredients, and Japan's PMDA quality benchmarks collectively shape product specifications and market access conditions for antifreeze protein suppliers. REACH registration obligations in Europe further constrain which source organisms and extraction chemistries qualify for commercial scale. Stakeholders must monitor regulatory divergence between jurisdictions on genetically modified organism classification, as this classification determines whether synthetic-biology production routes face accelerated approval or extended safety-review timelines.
Market Dynamics
Precision fermentation infrastructure is displacing marine extraction as the dominant supply architecture for pharmaceutical-grade antifreeze proteins, compressing batch-to-batch variability and decoupling output from North Atlantic fishing seasons.
Growth Catalysts
- EU Green Deal purity mandates:REACH-registered biologically sourced inputs now command preferential access to European cryopreservation supply chains, filtering out non-compliant extraction chemistries.
- Cell therapy manufacturing:Commercial-scale expansion of CAR-T and stem-cell production lines in Germany, Japan, and the United States is institutionalizing cold-chain biotechnology demand.
- Synthetic biology platforms:Engineered microbial expression systems enable year-round glycoprotein output without seasonal harvesting constraints.
Market Restraints
- Input cost volatility:Cold-water fish biomass prices fluctuate with North Atlantic quota allocations, squeezing margin predictability for extraction-dependent suppliers.
- Regulatory friction:Divergent GMO classification protocols between FDA, EMA, and PMDA create extended safety-review timelines for synthetic-biology production routes.
- Substitution threat:Synthetic polymer cryoprotectants compete on cost for non-pharmaceutical frozen-food applications where purity certification is not mandated.
Strategic Opportunities
- Underpenetrated geography:South Korea's MFDS biologics approval pathway offers accelerated market entry for fermentation-derived proteins meeting GMP standards.
- Regulatory tailwind:Japan's PMDA quality benchmarks for active pharmaceutical ingredients create certification premiums that synthetic-source competitors struggle to capture.
- Technology convergence:Integration of continuous bioprocessing with real-time analytics is compressing production cycles for clinical-grade material.
Industry Challenges
- Specialized talent scarcity:Protein purification chemists with marine biotechnology experience command premium compensation in Germany and Japan.
- Capex intensity:GMP-compliant fermentation suites require eight-figure infrastructure investments before regulatory qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antifreeze Proteins Market |
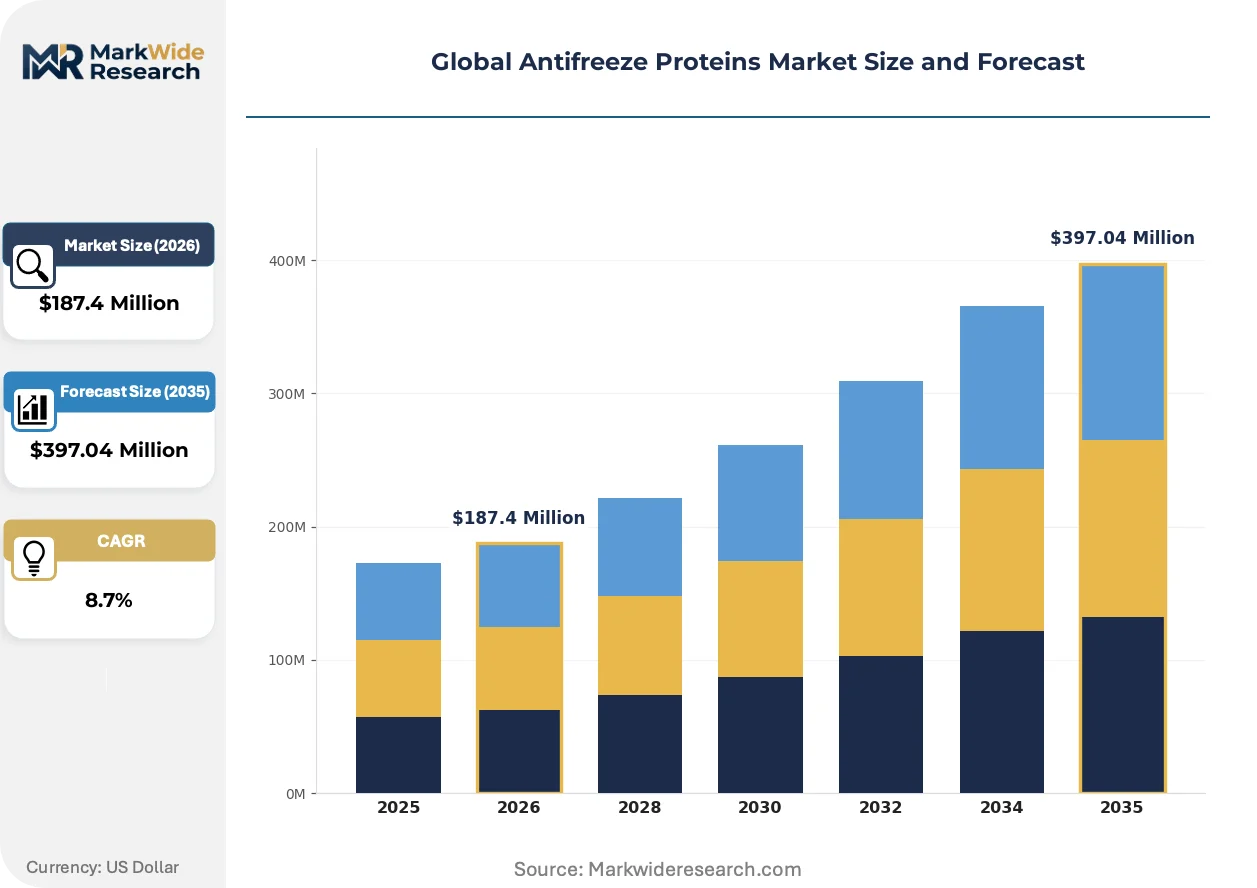
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Food Preservation, Biotechnology, Aquaculture Type: Antifreeze glycoproteins, Antifreeze peptides, Antifreeze proteins, Cryoprotectants Source: Fish, Insects, Plants, Microorganisms End User: Pharmaceuticals, Food Industry, Research Institutions, Cosmetics |
| Companies Covered | A/F Protein Inc., Sirona Biochem, ProtoKinetix, Inc., Kaneka Corporation, Unilever, BASF SE, Cargill, Incorporated, Nichirei Corporation, Shanghai Yu Tao Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antifreeze Proteins Market Emerging Trajectories
Production architecture is fragmenting across three distinct technical pathways, each optimizing for different purity-certification tiers and end-use specifications.
Continuous bioprocessing is modularizing antifreeze protein manufacturing by replacing batch fermentation with perfusion-based microbial culture. Pharmaceutical contract manufacturers in Germany and Japan are adopting these systems to serve cell therapy clients requiring lot-to-lot consistency. The technology is compressing facility footprints while expanding output variability for different molecular weight fractions.
REACH registration obligations are tightening extraction chemistry qualifications across European supply chains. ECHA substance evaluation protocols now require full toxicological dossiers for fish-sourced glycoprotein isolates. Biotech suppliers are responding by shifting documentation burden toward synthetic-biology alternatives with cleaner regulatory pedigrees.
Certificate-of-analysis requirements are reshaping procurement patterns for cryopreservation-grade material. Large pharmaceutical manufacturers in the United States now mandate third-party analytical validation for every production lot, displacing spot-market purchasing. This behavioral shift concentrates contract volumes with suppliers maintaining captive QC laboratories in Massachusetts and North Carolina.
Global Antifreeze Proteins Market Segmentation
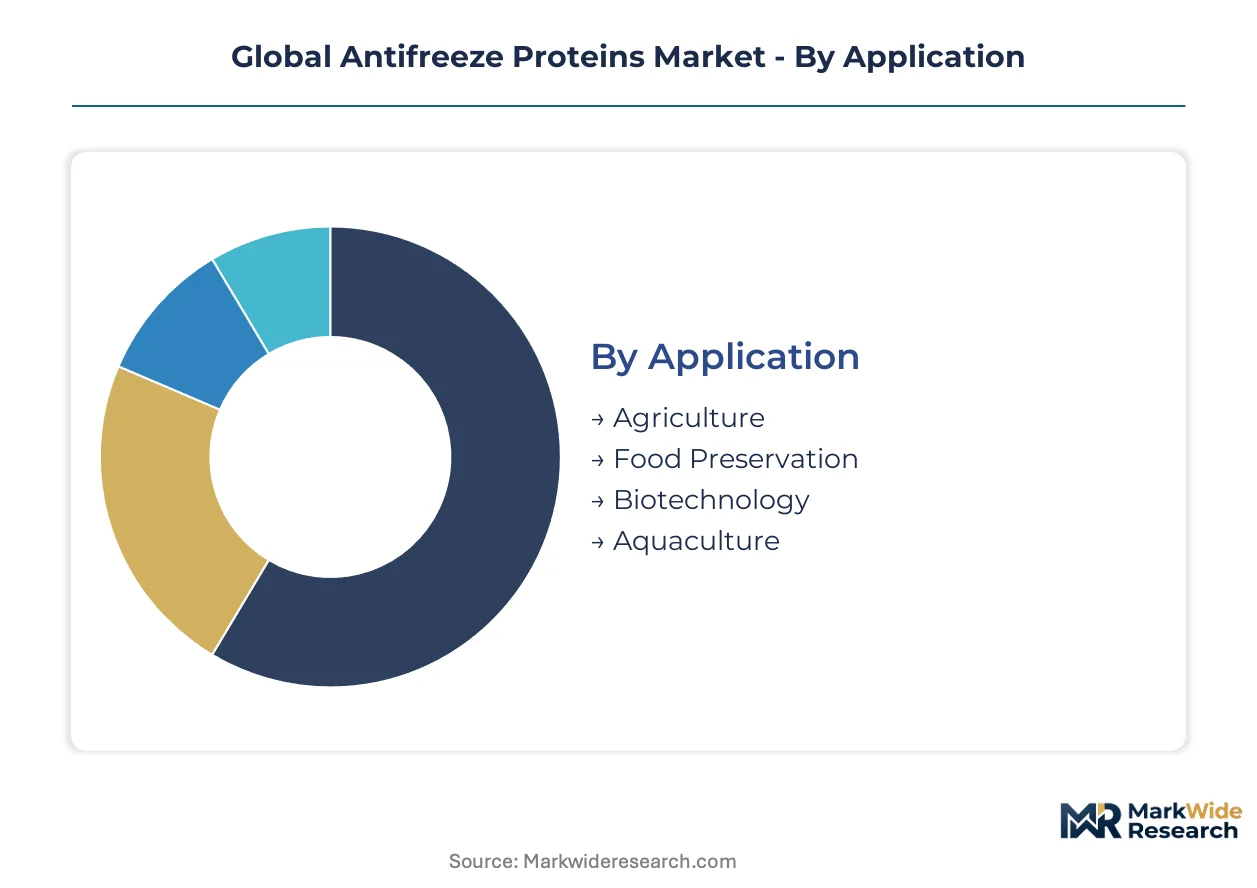
Antifreeze proteins exhibit divergent purity requirements and certification burdens across end-use applications. Segmentation reveals which production architectures command margin premiums versus which compete on unit economics.
Application:
Biotechnology buyers prioritize lot-to-lot consistency and regulatory documentation over per-gram cost.
- Biotechnology:Cryopreservation of CAR-T therapies and stem-cell lines demands pharmaceutical-grade purity with third-party analytical validation. German and Japanese cell therapy manufacturers institutionalize cold-chain demand here. Volume sits with Biotechnology; growth tilts toward Food Preservation.
- Food Preservation:Ice-crystal inhibition extends frozen dessert shelf stability without osmotic damage. Unilever and Nestlé deploy captive demand through in-house frozen-food portfolios. This segment climbs fastest as clean-label formulations displace synthetic cryoprotectants.
- Agriculture:Transgenic expression in frost-resistant crops targets yield protection in temperate zones. Regulatory divergence on GMO classification constrains commercial rollout speed.
- Aquaculture:Cold-water species husbandry uses AFPs to reduce winter mortality in salmon and trout farming. Norwegian and Chilean operations drive procurement volume.
Biotechnology commands the steepest price premiums; Food Preservation offers the broadest volume pathway.
Type:
Structural classification determines extraction complexity and regulatory qualification burden.
- Antifreeze glycoproteins:These 2.5-14 kDa molecules dominate fish-sourced commercial supply due to established North Atlantic extraction protocols. ECHA substance evaluation now demands full toxicological dossiers, pushing suppliers toward synthetic alternatives.
- Antifreeze peptides:Shorter sequences enable microbial expression with cleaner regulatory pedigrees. Sirona Biochem and Kaneka Corporation scale precision fermentation for year-round output decoupled from fishing seasons.
- Antifreeze proteins:Non-glycosylated variants from insect sources offer thermal hysteresis activity without carbohydrate moieties. Purification complexity limits pharmaceutical adoption.
- Cryoprotectants:Synthetic polymer alternatives compete on cost for non-pharmaceutical applications where purity certification is not mandated. Dimethyl sulfoxide and glycerol remain entrenched in research settings.
Glycoproteins retain incumbent position; peptides gain share through synthetic biology scale-up.
Source:
Organism origin shapes seasonal availability, GMO classification risk, and REACH registration obligations.
- Microorganisms:Engineered yeast and bacterial platforms enable continuous bioprocessing with compressed batch-to-batch variability. FDA, EMA, and PMDA divergence on GMO safety-review timelines creates regulatory friction for market entrants.
- Fish:Cold-water species from North Atlantic fisheries provide the dominant commercial supply. Quota allocation volatility squeezes margin predictability for extraction-dependent suppliers.
- Plants:Transgenic expression in crops represents the fastest-expanding category as agricultural biotechnology firms engineer frost-resistant varieties. EU Green Deal purity mandates filter out non-compliant chemistries.
- Insects:Overwintering beetles and moths produce thermal hysteresis proteins with distinct ice-binding mechanisms. Limited extraction infrastructure constrains commercial scale.
Fish sources anchor current volume; microorganisms attract capital for pharmaceutical-grade expansion.
End User:
Procurement sophistication varies from certificate-of-analysis mandates to spot-market purchasing.
- Pharmaceuticals:Large manufacturers in Massachusetts and North Carolina now require third-party analytical validation for every production lot. This behavioral shift concentrates contract volumes with suppliers maintaining captive QC laboratories.
- Food Industry:Frozen-food manufacturers prioritize cost position over purity certification. Synthetic polymer substitutes compete aggressively here.
- Research Institutions:Academic laboratories purchase lower-grade material for mechanistic studies. Spot-market purchasing persists despite consolidation trends elsewhere.
- Cosmetics:Skin-care formulations exploit ice-binding properties for texture stabilization. Regulatory pathways remain underdeveloped relative to pharmaceutical benchmarks.
Pharmaceuticals drive margin expansion; Food Industry absorbs volume at compressed pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Atlantic cold-water fisheries supply the dominant feedstock for commercial extraction, while precision fermentation infrastructure concentrates in pharmaceutical manufacturing clusters across three continents.
United States
Cell therapy manufacturers in Massachusetts and North Carolina drive pharmaceutical-grade demand with mandatory third-party analytical validation for every production lot. FDA biologics guidance shapes purity specifications for cryopreservation applications. The Greater Boston corridor anchors contract manufacturing concentration for clinical-grade material.
Germany
CAR-T and stem-cell production lines in Baden-Württemberg and Bavaria institutionalize cold-chain biotechnology procurement. EMA Good Manufacturing Practice standards for active pharmaceutical ingredients filter market access. The Rhine-Main biotechnology cluster integrates continuous bioprocessing with real-time analytics for lot-to-lot consistency.
Japan
PMDA quality benchmarks for active pharmaceutical ingredients create certification premiums that concentrate contract volumes with qualified suppliers. METI industrial biotechnology programs support precision fermentation scale-up. The Kansai region hosts Kaneka Corporation's year-round glycoprotein output infrastructure.
United Kingdom
Research institutions in the Cambridge-Oxford-London triangle purchase lower-grade material for mechanistic studies while pharmaceutical manufacturers upgrade to certificate-of-analysis mandates. REACH registration obligations constrain which source organisms qualify for commercial scale. Scottish marine biotechnology operations face ECHA substance evaluation protocols for extraction chemistries.
South Korea
MFDS biologics approval pathways offer accelerated market entry for fermentation-derived proteins meeting GMP standards. Domestic cell therapy developers expand manufacturing capacity in the Seoul Capital Area. Busan-Ulsan chemical processing infrastructure supports downstream purification operations for export-oriented suppliers.
Global Antifreeze Proteins Market Vendor Landscape
Global majors compete with regional champions across certification tiers and production architectures. The vendor base stratifies between marine-extraction incumbents with seasonal output constraints and synthetic-biology entrants scaling precision fermentation year-round. Three archetypes dominate: pharmaceutical-grade specialists with captive QC laboratories, diversified food-industry conglomerates with captive demand, and synthetic-biology platforms decoupled from fishing seasons. Competitive moves concentrate on regulatory qualification speed and backward integration into fermentation infrastructure.
Within the synthetic-biology tier, Sirona Biochem and Kaneka Corporation exemplify platform-based production architectures. Sirona Biochem occupies a position among North American biotechnology specialists leveraging engineered microbial expression. Kaneka Corporation anchors Japanese supply through precision fermentation infrastructure. Unilever represents the diversified conglomerate archetype with captive demand absorption from frozen-food portfolios. A/F Protein Inc. and ProtoKinetix, Inc. sit within the marine-extraction segment with established North Atlantic sourcing relationships.
| Leading Market Players |
|---|
| A/F Protein Inc. |
| Sirona Biochem |
| ProtoKinetix, Inc. |
| Kaneka Corporation |
| Unilever |
| BASF SE |
| Cargill, Incorporated |
| Nichirei Corporation |
| Shanghai Yu Tao Industrial Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Cold-water fish biomass indices cascade through three distinct pricing tiers, with North Atlantic quota volatility compressing margins for extraction-dependent suppliers while pharmaceutical-grade fermentation output commands certification premiums. REACH-registered synthetic alternatives decouple from seasonal harvesting constraints, creating a bifurcated cost structure that rewards backward integration into precision fermentation infrastructure.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade suppliers from spot-market vendors, with third-party analytical validation now mandatory for cell therapy manufacturers in Massachusetts and North Carolina. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, volume scale, and regulatory pedigree differentiation. Cost compression in food-preservation tiers intensifies as synthetic polymer cryoprotectants compete aggressively for frozen-food applications where purity certification remains unmandated. Research institutions exhibit highest price sensitivity, while biotechnology buyers prioritize lot-to-lot consistency over per-gram cost.
Supply Chain Analysis
EMA Good Manufacturing Practice standards and PMDA quality benchmarks gate supply chain access, concentrating qualified production in Germany, Japan, and the United States. Raw material flows draw from engineered yeast platforms, North Atlantic cold-water fisheries, and transgenic crop systems. Single-source vulnerability runs through marine extraction routes tethered to seasonal quota allocations. Distribution runs through pharmaceutical contract manufacturers with captive QC laboratories and diversified food-industry conglomerates with captive demand absorption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation capital requirements are forcing consolidation among marine-extraction incumbents unable to fund GMP-compliant infrastructure upgrades. Eight-figure facility investments before regulatory qualification filter out sub-scale competitors.
For Market Incumbents: Cement market position by accelerating backward integration into continuous bioprocessing infrastructure in the Rhine-Main biotechnology cluster and Kansai region. Synthetic-biology entrants threaten seasonal-dependent suppliers with year-round output consistency; counter by acquiring precision fermentation platforms or forming exclusive toll-manufacturing arrangements with qualified contract manufacturers. For New Entrants and Emerging Players: Pharmaceutical contract manufacturers in South Korea's Seoul Capital Area offer the most penetrable entry channel, with MFDS biologics approval pathways providing accelerated market access for fermentation-derived proteins meeting GMP standards. Target food-preservation applications with clean-label formulations displacing synthetic cryoprotectants, leveraging regulatory tailwinds from EU Green Deal purity mandates. Partner with frozen-food manufacturers seeking captive supply security. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap synthetic-biology platforms with qualified fermentation infrastructure in Germany and Japan. Long-term viability hinges on regulatory qualification speed across FDA, EMA, and PMDA jurisdictions. Watch for inflection signals in cell therapy manufacturing capacity announcements from CAR-T and stem-cell producers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Kaneka Corporation's year-round glycoprotein output decouples supply from North Atlantic fishing seasons. |
| Regulatory Qualification Investment | EMA GMP standards and PMDA benchmarks create certification barriers that synthetic-source competitors struggle to clear. |
| Continuous Bioprocessing Adoption | German pharmaceutical contract manufacturers integrate perfusion-based microbial culture for lot-to-lot consistency. |
| Certificate-of-Analysis Mandates | Third-party analytical validation requirements concentrate contract volumes with suppliers maintaining captive QC laboratories. |
| Clean-Label Formulation Partnerships | Unilever deploys captive demand from frozen-food portfolios to displace synthetic cryoprotectants. |
Methodological Framework
Independent corroboration across primary interviews with protein purification chemists, cell therapy manufacturing executives, and regulatory affairs specialists, combined with secondary validation through EMA submissions, FDA biologics guidance documents, and REACH registration databases, underwrites the qualitative findings. Bottom-up triangulation across application segments and top-down cross-checks against precision fermentation capacity announcements ensure analytical consistency.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects, with segmentation modeling across biotechnology, food preservation, agriculture, and aquaculture applications. Source-origin differentiation by fish, microorganism, plant, and insect categories, combined with end-user procurement sophistication tiers, anchors the forecast framework. CAGRs derive from installed cell therapy manufacturing capacity trajectories and clean-label formulation adoption curves in frozen-food portfolios.
Caveats apply where divergent GMO classification protocols between FDA, EMA, and PMDA could materially shift synthetic-biology approval timelines, or where North Atlantic quota allocations compress marine-extraction viability. Forecasts reflect assumptions about regulatory harmonization progress and fermentation yield improvements. A model refresh is warranted upon material change in cell therapy commercial manufacturing capacity announcements or REACH substance evaluation protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Sheet Moulding Compound (SMC) Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Compounds Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Metasulphite Market