
 Gulf Collagen Market | 2026-2036
Gulf Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf Collagen Market Foresight
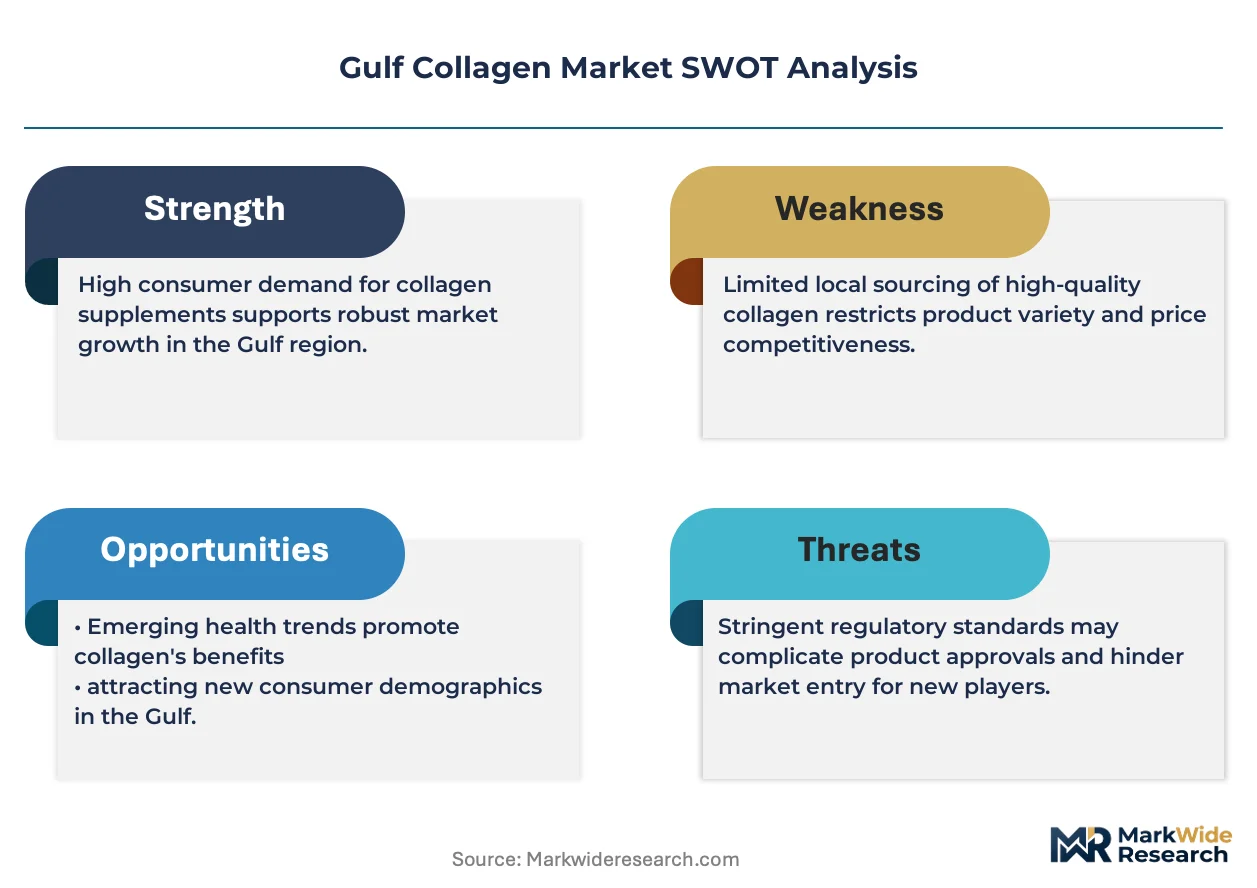
A capital-intensity divergence between integrated collagen processors and regional distributors is reorganizing competitive dynamics across the Gulf. Gelita AG leverages backward integration into bovine hide sourcing to sustain margin control against price volatility. Rousselot anchors its position through pharmaceutical-grade gelatin certification, while PB Leiner competes via specialized marine collagen extraction capabilities tailored to halal-sensitive markets.
Collagen encompasses extracellular matrix proteins—primarily type I, II, and III—extracted through acid or enzymatic hydrolysis of bovine, porcine, or marine tissues, yielding peptides with molecular weights typically below 10 kDa for optimal bioavailability. Its primary commercial purpose spans wound-healing matrices, joint-health nutraceuticals, and anti-aging dermal formulations. Collagen peptides dominate value capture due to superior solubility and absorption profiles, while gelatin retains volume leadership in food stabilization applications across the Gulf's confectionery sector. The nutraceuticals end-user segment represents the fastest-expanding margin pool, driven by powder and liquid form factors preferred in sports nutrition and clinical dietary protocols.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce halal certification and import quality benchmarks that shape product eligibility across Gulf Cooperation Council borders. Gulf Standardization Organization alignment with CODEX Alimentarius and ISO 17025 testing protocols determines laboratory accreditation requirements for collagen ingredient verification. Stakeholders must monitor evolving halal traceability mandates and local production incentive structures to secure long-term supply positioning.
Market Dynamics
Halal traceability mandates from Gulf Standardization Organization are restructuring supplier qualification protocols, forcing ingredient vendors to demonstrate full chain-of-custody documentation from slaughterhouse to finished peptide.
Growth Catalysts
- CODEX Alimentarius alignment:Gulf Standardization Organization harmonization with international food standards is eliminating redundant testing requirements for hydrolyzed collagen imports, accelerating customs clearance timelines.
- Preventive wellness pivot:Saudi consumers are prioritizing joint-health and skin-aging interventions ahead of clinical treatment, expanding powder and liquid nutraceutical consumption in Riyadh and Jeddah retail channels.
- Local manufacturing partnerships:Joint ventures between European collagen processors and Saudi food conglomerates are transferring enzymatic hydrolysis technology to domestic production facilities.
Market Restraints
- Bovine hide cost volatility:Feed price fluctuations and livestock cycle variations in South American sourcing regions are compressing margins for gelatin-dependent confectionery applications.
- Marine collagen supply concentration:Wild-caught fish skin and scale processing capacity clusters in Southeast Asian coastal facilities, exposing Gulf importers to shipping lane disruptions and seasonal catch variability.
- Porcine-derived substitution barriers:Islamic dietary prohibitions block approximately one-third of global collagen supply sources from entering Saudi Arabia, UAE, and Kuwait markets entirely.
Strategic Opportunities
- Kuwait underpenetration:Functional beverage and clinical nutrition applications remain nascent in Kuwaiti retail and hospital channels, presenting first-mover positioning for halal-certified peptide suppliers.
- Emirates Authority for Standardization and Metrology streamlining:Proposed mutual recognition agreements with European notified bodies would reduce duplicate laboratory testing costs for UAE-destined collagen ingredients.
- Precision fermentation convergence:Microbial collagen expression technologies are approaching commercial viability, potentially decoupling Gulf supply from animal-derived raw material constraints.
Industry Challenges
- Halal auditor scarcity:Qualified certification bodies capable of verifying collagen slaughter compliance across multi-country supply chains are insufficient relative to application volumes from Saudi Food and Drug Authority registrants.
- ISO 17025 laboratory accreditation timelines:Gulf-based testing facilities face eighteen-to-twenty-four-month queues for international accreditation, delaying product launch schedules for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf Collagen Market |
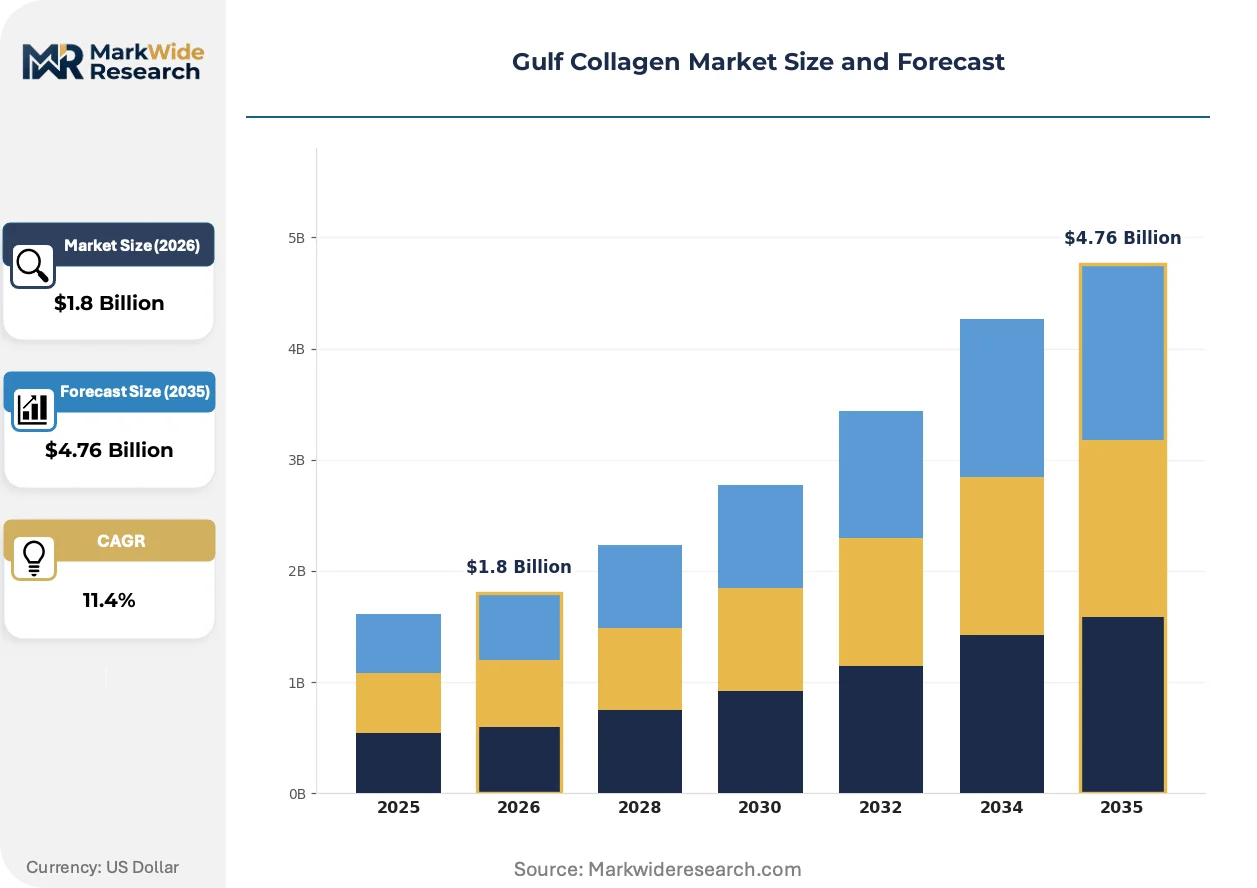
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen Peptides, Gelatin, Hydrolyzed Collagen, Collagen Supplements Form: Liquid, Powder, Capsule, Gummy End User: Healthcare, Cosmetics, Food & Beverage, Nutraceuticals Application: Wound Healing, Joint Health, Skin Care, Bone Health |
| Companies Covered | Gelita AG, Rousselot, PB Leiner, ConnOils LLC, Weishardt Group, Collagen Solutions Plc, Holista Colltech, Advanced BioMatrix, Inc., Vital Proteins LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf Collagen Market Shifts & Advancements
Enzymatic hydrolysis protocols and molecular weight fractionation are displacing traditional acid-extraction methods across Gulf manufacturing partnerships, tightening peptide uniformity specifications for nutraceutical applications.
Marine collagen extraction from tilapia and pangasius aquaculture byproducts is supplanting bovine-derived alternatives in premium cosmetic formulations. Dubai-based dermal care manufacturers are accelerating adoption to meet halal-sensitive export requirements for Southeast Asian markets. This shift is compressing reliance on South American hide supply chains while elevating aquaculture waste valorization economics.
Saudi Food and Drug Authority implementation of electronic halal traceability platforms is mandating blockchain-verified documentation for all collagen ingredient imports. Industrial consequence includes forced ERP system upgrades among regional distributors and manufacturers. Smallest Gulf-based trading houses without integrated supply chain software face disqualification from approved vendor lists.
Sports nutrition procurement in UAE fitness channels is pivoting from bulk powder sacks toward single-serve sachet and ready-to-drink formats. E-commerce platforms and gym-affiliated retail are displacing traditional pharmacy distribution for collagen peptide sales. This behavioral shift concentrates most visibly in Abu Dhabi and Dubai metropolitan zones where subscription-model supplement delivery is penetrating corporate wellness programs.
Gulf Collagen Market Segmentation
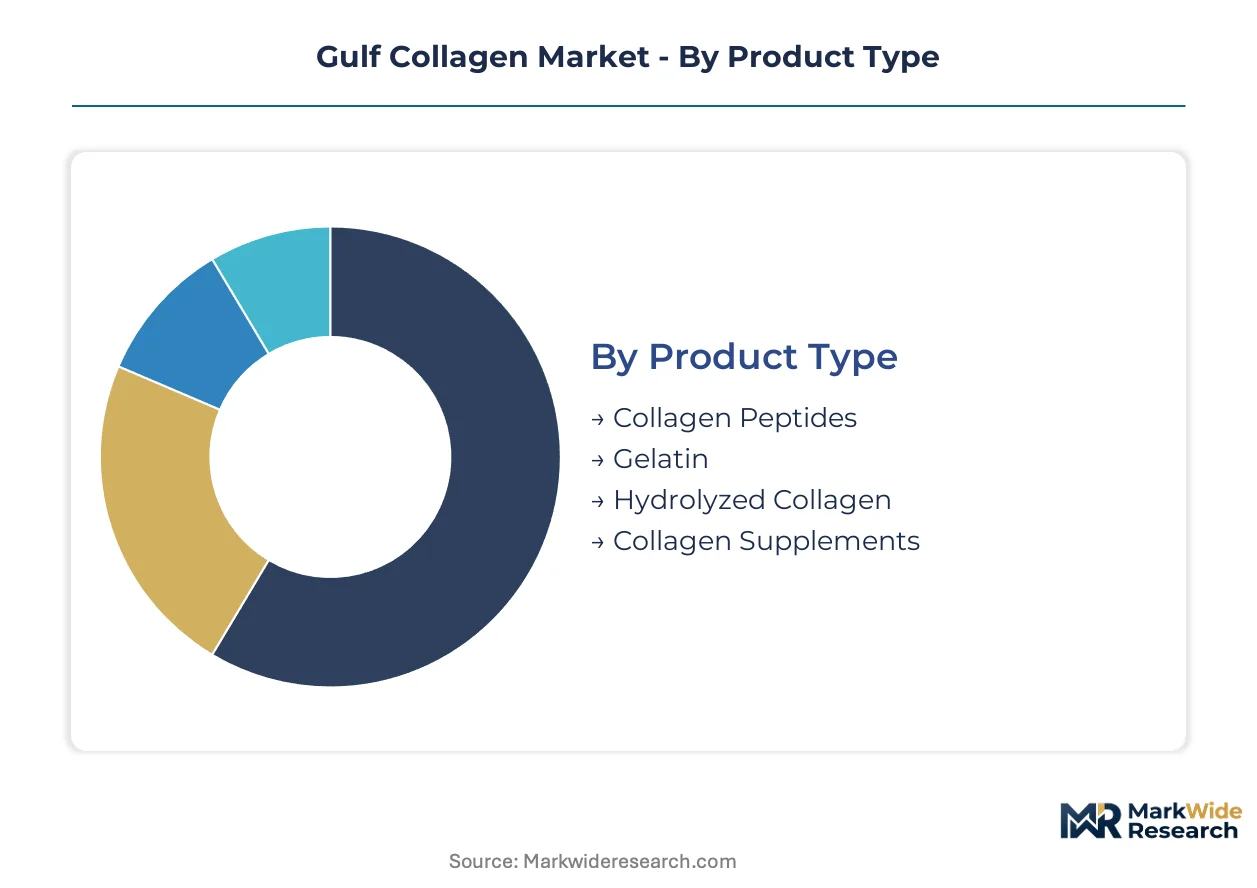
Segmentation across the Gulf collagen market reveals divergent supply chain configurations and regulatory pathways. Product type and form factor choices determine halal certification complexity, while end-user concentration in Saudi Arabia and the UAE shapes regional manufacturing priorities.
Product Type:
Domestic production partnerships concentrate on bovine-derived categories, while marine-sourced segments remain import-dependent through Southeast Asian supply chains.
- Collagen Peptides:Enzymatically hydrolyzed proteins with molecular weights below 10 kDa deliver superior bioavailability for nutraceutical absorption. Demand clusters in Riyadh sports nutrition channels and Dubai clinical dietary protocols, driven by Saudi Food and Drug Authority preference for documented enzymatic processing over acid extraction.
- Gelatin:Partially hydrolyzed collagen retains gelling functionality for confectionery and pharmaceutical encapsulation. Kuwaiti and Bahraini food manufacturers anchor regional volume, though bovine hide cost volatility from South American sourcing regions compresses margin stability.
- Hydrolyzed Collagen:Intermediate molecular weight fractions serve functional beverage and powder applications across Gulf retail.
- Collagen Supplements:Finished dosage forms combine peptides with vitamins and minerals for direct consumer distribution.
Collagen peptides holds the largest share; momentum sits with hydrolyzed collagen as local manufacturing partnerships transfer enzymatic technology to Saudi facilities.
Form:
Cost tier differentiation separates premium convenience formats from economy bulk positioning, with packaging technology determining shelf-life extension in Gulf climate conditions.
- Liquid:Ready-to-drink formulations with stabilized peptide suspensions target UAE fitness channel subscription models. Abu Dhabi and Dubai metropolitan zones show fastest adoption through gym-affiliated retail and corporate wellness programs.
- Powder:Bulk and single-serve sachet configurations dominate Saudi preventive wellness consumption. Riyadh and Jeddah retail channels favor powder for joint-health and skin-aging interventions ahead of clinical treatment.
- Capsule:Hard-shell and soft-gel encapsulation serves pharmaceutical-grade applications requiring precise dosing.
- Gummy:Confectionery-format delivery appeals to younger demographics and compliance-sensitive therapeutic segments.
Powder commands volume leadership; liquid is climbing the fastest as e-commerce platforms displace traditional pharmacy distribution.
End User:
Application maturity varies sharply, with established food stabilization contrasting against emerging clinical nutrition protocols.
- Nutraceuticals:Dietary supplements spanning joint health, skin aging, and sports recovery represent the steepest expansion trajectory. Preventive wellness prioritization among Saudi consumers drives powder and liquid consumption through specialized retail channels.
- Food & Beverage:Gelatin-dependent confectionery and functional beverage applications retain volume leadership across Kuwaiti and Bahraini manufacturing.
- Cosmetics:Marine collagen extraction from tilapia and pangasius aquaculture byproducts supplants bovine alternatives in premium dermal formulations for Dubai-based manufacturers.
- Healthcare:Wound-healing matrices and clinical dietary protocols require pharmaceutical-grade certification and halal traceability documentation.
Food & beverage holds the largest share; nutraceuticals gains share fastest as consumer behavior shifts toward preventive intervention.
Application:
Supply concentration in peptide extraction technology favors certain therapeutic categories over others.
- Skin Care:Anti-aging dermal formulations leverage type I and III collagen peptides for topical and ingestible delivery. Dubai manufacturers accelerate marine collagen adoption to meet halal-sensitive export requirements for Southeast Asian markets.
- Joint Health:Type II collagen and undenatured formulations target osteoarthritis prevention and athletic recovery. Saudi consumer prioritization of joint-health interventions ahead of clinical treatment expands retail penetration.
- Wound Healing:Collagen matrices and dressings require pharmaceutical-grade certification and sterile manufacturing protocols.
- Bone Health:Calcium-collagen combination products address osteoporosis prevention in aging demographics.
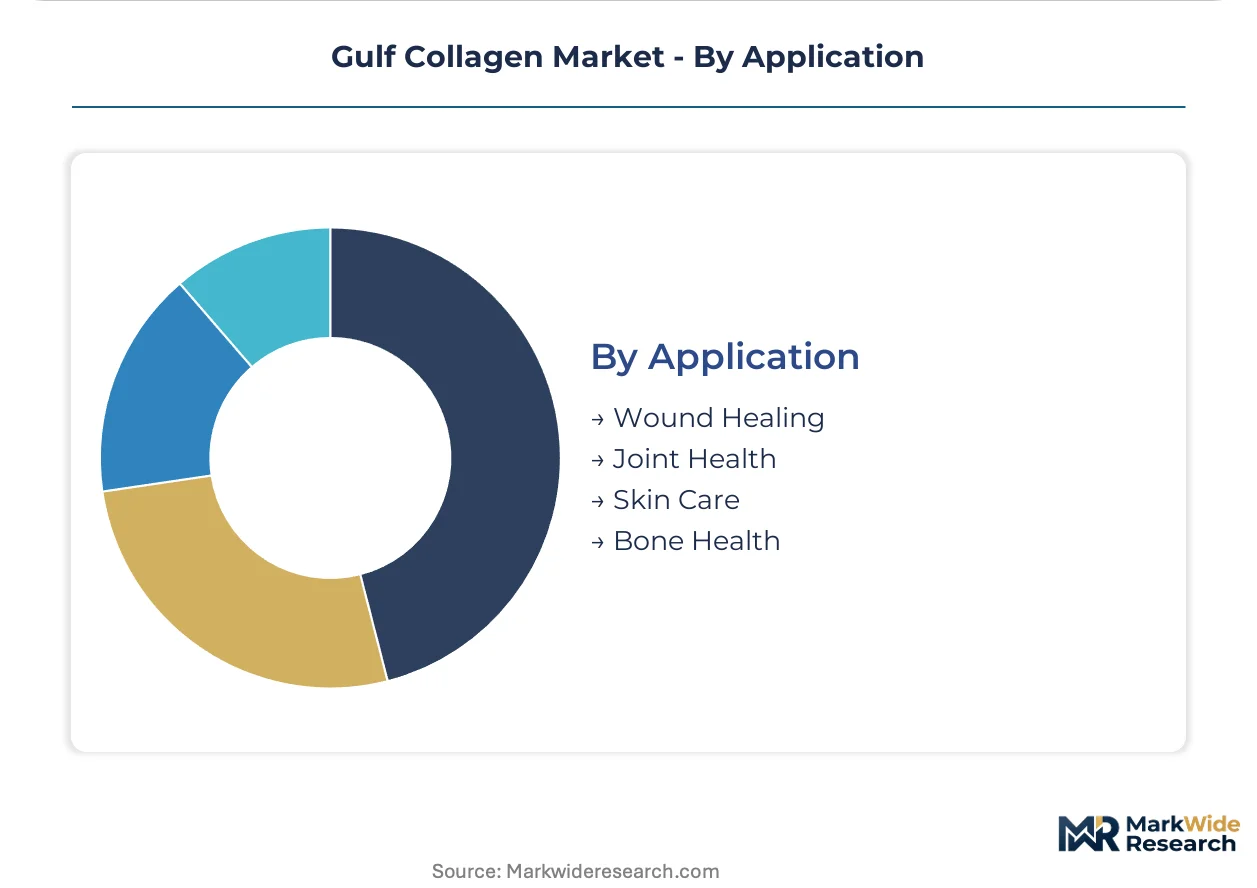
Joint health holds the largest share; skin care shows the steepest expansion trajectory as marine sourcing decouples from bovine supply volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes collagen peptides predominantly in preventive wellness formats, while the UAE channels demand through fitness-affiliated subscription models and Kuwait retains gelatin-centric food stabilization traditions.
Saudi Arabia
Riyadh and Jeddah retail channels prioritize powder-form joint-health and skin-aging interventions ahead of clinical treatment. Saudi Food and Drug Authority mandates blockchain-verified halal traceability documentation for all collagen ingredient imports. Domestic manufacturing partnerships in Riyadh industrial zones are transferring enzymatic hydrolysis technology from European processors to local facilities.
United Arab Emirates
Abu Dhabi and Dubai metropolitan zones show fastest adoption of ready-to-drink collagen formats through gym-affiliated retail and corporate wellness programs. Emirates Authority for Standardization and Metrology is advancing mutual recognition agreements with European notified bodies to reduce duplicate laboratory testing costs. Dubai-based dermal care manufacturers are accelerating marine collagen adoption to meet halal-sensitive export requirements for Southeast Asian markets.
Kuwait
Functional beverage and clinical nutrition applications remain nascent in Kuwaiti retail and hospital channels, presenting positioning opportunities for halal-certified peptide suppliers. The country's national food regulator enforces Gulf Standardization Organization alignment with CODEX Alimentarius for import quality benchmarks. Kuwaiti and Bahraini food manufacturers anchor regional gelatin volume for confectionery stabilization applications.
Qatar
Sports nutrition procurement through premium fitness channels is expanding as Doha's wellness infrastructure matures. The national standardization body implements Gulf Standardization Organization harmonization protocols for hydrolyzed collagen customs clearance. Industrial concentration clusters around Doha metropolitan pharmaceutical and nutraceutical distribution hubs serving domestic and re-export demand.
Gulf Collagen Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into raw material sourcing separating margin-sustainable processors from price-exposed distributors. The competitive terrain organizes around three archetypes: hide-sourced bovine integrators, marine extraction specialists, and pharmaceutical-grade gelatin certifiers. Dominant competitive moves include technology-transfer joint ventures with Saudi manufacturing partners and enzymatic hydrolysis capability acquisitions.
Within the integrated processor tier, Gelita AG and Rousselot occupy positions exemplifying backward integration and pharmaceutical certification strategies respectively, while PB Leiner represents marine collagen extraction specialization for halal-sensitive markets. These entities anchor the competitive structure through distinct sourcing and certification vectors that regional distributors must navigate.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| PB Leiner |
| ConnOils LLC |
| Weishardt Group |
| Collagen Solutions Plc |
| Holista Colltech |
| Advanced BioMatrix, Inc. |
| Vital Proteins LLC |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month ISO 17025 accreditation queues for Gulf-based testing facilities concentrate pricing power among European-notified-body-certified suppliers, while compressing margin buffers for regional distributors lacking captive laboratory infrastructure.
Pricing Analysis
Long-term offtake agreements between Saudi food conglomerates and European collagen processors dominate contract structures, locking in enzymatic hydrolysis technology transfer pricing against South American bovine hide volatility. Price differentiation rests on halal certification grade and pharmaceutical-grade gelatin tier, with blockchain-verified traceability commanding premium positioning. Pricing pressure intensifies in gelatin-dependent confectionery tiers as feed price fluctuations transmit through South American livestock cycles. Regional distributors exhibit highest price sensitivity due to ERP upgrade burdens from Saudi Food and Drug Authority electronic traceability mandates, while integrated processors with backward integration into hide sourcing maintain margin insulation.
Supply Chain Analysis
Strategic stockpile preferences among Gulf importers are displacing just-in-time inventory strategies as marine collagen supply concentration in Southeast Asian coastal facilities exposes procurement to shipping lane disruptions. Raw material sourcing draws from South American bovine hide operations, Southeast Asian wild-caught fish processing, and emerging Middle Eastern aquaculture byproduct streams. Single-source vulnerability clusters around enzymatic hydrolysis equipment suppliers and qualified halal auditor capacity. Distribution runs through Riyadh industrial zone manufacturing partnerships, Dubai metropolitan fitness channel subscription platforms, and Kuwaiti food stabilization wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-verified halal traceability platforms are restructuring the Gulf collagen market into a platform-economics inflection, where ERP-integrated supply chain software becomes the interoperability layer determining vendor list eligibility.
For Market Incumbents: Compound backward integration into bovine hide sourcing to sustain margin control against price volatility from South American feed fluctuations. Accelerate pharmaceutical-grade gelatin certification investments to defend positioning against marine collagen substitution threats from Dubai-based dermal manufacturers. Prioritize technology-transfer joint ventures in Riyadh industrial zones to anchor enzymatic hydrolysis capability within Saudi manufacturing partnerships. For New Entrants and Emerging Players: Anchor in Kuwait's underpenetrated functional beverage and clinical nutrition channels, where halal-certified peptide suppliers face minimal established competition. Target single-serve sachet and ready-to-drink format white space in hospital procurement and corporate wellness programs. Pursue gym-affiliated retail partnerships in Abu Dhabi and Dubai metropolitan zones as the primary go-to-market angle, leveraging subscription-model supplement delivery penetration. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because halal auditor scarcity and ISO 17025 accreditation bottlenecks create durable moats for integrated processors with existing regulatory infrastructure. Acquisition focus should center on marine collagen extraction specialists with tilapia and pangasius aquaculture byproduct capabilities. The signal to watch is precision fermentation technology commercialization timelines, which could decouple supply from animal-derived raw material constraints entirely.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Traceability Platform Integration | Blockchain-verified documentation from Saudi Food and Drug Authority mandates ERP upgrades across regional distributor networks. |
| Enzymatic Hydrolysis Technology Transfer | European processor joint ventures with Saudi food conglomerates localize peptide production in Riyadh industrial zones. |
| Marine Collagen Sourcing Diversification | Tilapia and pangasius aquaculture byproduct extraction reduces dependence on South American bovine hide supply chains. |
| Pharmaceutical-Grade Certification Investment | Rousselot's gelatin certification strategy anchors positioning in wound-healing matrices and clinical dietary protocols. |
| Subscription-Model Format Innovation | Single-serve sachet and ready-to-drink configurations penetrate UAE fitness channels and corporate wellness programs. |
Research Methodology
Desk research of customs and trade data, Gulf Standardization Organization regulatory filings, and CODEX Alimentarius alignment documentation preceded structured interviews with Saudi Food and Drug Authority registrants, Emirates Authority for Standardization and Metrology officials, enzymatic hydrolysis technology providers, and Riyadh industrial zone manufacturing partners. Secondary validation drew from SEC filings of integrated collagen processors, hospital procurement databases, and fitness channel retail audit data. Bottom-up demand modeling across nutraceutical, food and beverage, and cosmetics applications was cross-checked against top-down supply capacity assessments from Southeast Asian marine processing facilities and South American hide sourcing regions.
Variance decomposition across product type, form factor, end-user segment, and halal certification tier shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level demand elasticity modeling and supply capacity expansion timelines. Industry-specific forecast inputs included enzymatic hydrolysis technology transfer rates from European-Saudi joint ventures and blockchain traceability platform adoption curves mandated by Saudi Food and Drug Authority implementation schedules.
Material uncertainties — precision fermentation technology commercialization, halal auditor capacity expansion, and South American livestock cycle disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding Gulf Standardization Organization harmonization maintenance and CODEX Alimentarius alignment continuity. Revision becomes warranted when marine collagen shipping lane disruption frequency or bovine hide price volatility crosses historical threshold bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Solketal Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Sheet Moulding Compound (SMC) Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Carbon Black for Packaging Market